
 Global Smart Appliances Market | 2026-2036
Global Smart Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Appliances Market Outlook
Korean component manufacturing is hardening as a supply bottleneck for sensor modules and display panels used in connected appliances. Samsung Electronics leverages vertical integration across semiconductor and appliance divisions to secure captive chip supply. LG Electronics anchors its position through OLED display technology leadership in smart refrigerator interfaces. Haier Smart Home dominates connected kitchen ecosystems in Asia through its open-source U+ platform architecture.
Smart appliances denote household and commercial equipment embedded with network connectivity, sensors, and microprocessors enabling remote operation, automated diagnostics, and energy optimization through data exchange with centralized platforms. Wi-Fi and IoT Integration technologies constitute the dominant connectivity stack, with voice control emerging as the fastest-growing interface layer due to natural language processing advances in residential settings. Smart refrigerators capture the largest margin pool among product types, while smart ovens represent the fastest-expanding category as precision cooking algorithms attract commercial hospitality buyers.
The EU Ecodesign framework and REACH chemical compliance standards shape material selection and interoperability mandates for appliances sold across Europe. The US FCC regulates wireless transmission protocols while the EPA ENERGY STAR program certifies connected devices for utility rebate eligibility. Stakeholders must monitor evolving cybersecurity certification requirements as national regulators begin mandating baseline encryption standards for IoT-enabled household equipment.
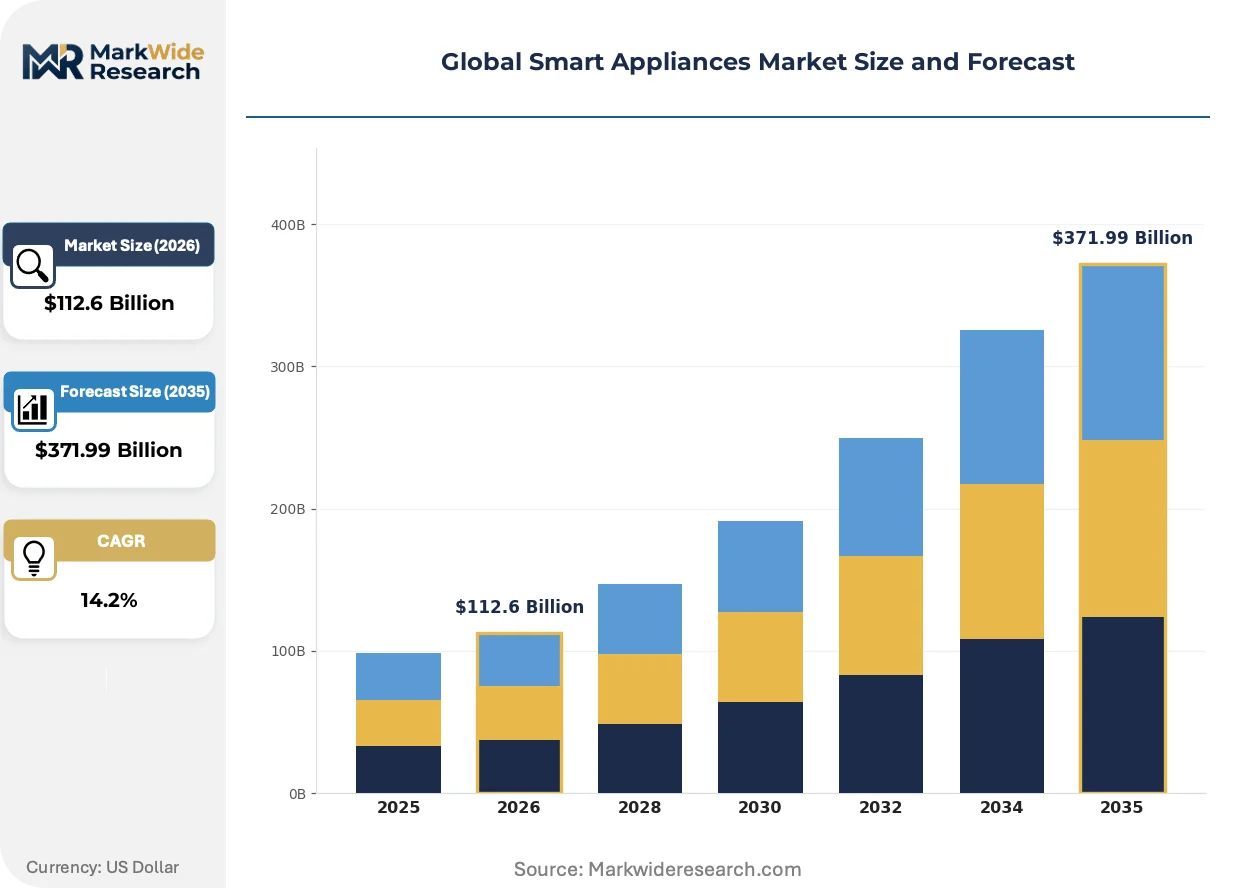
Market Dynamics
Component supply concentration in Korean semiconductor and display manufacturing is creating asymmetric power distribution across the smart appliance value chain, forcing appliance OEMs to secure long-term offtake agreements or develop captive production capabilities.
Growth Catalysts
- EU Ecodesign Efficiency Mandates:The EU Green Deal's escalating minimum efficiency thresholds for connected home devices are accelerating replacement cycles across European residential markets.
- Voice Interface Proliferation:Natural language processing advances are embedding voice control as the dominant human-machine interface layer in residential smart kitchens.
- China IoT Platform Scale:Domestic ecosystem integration through open-source platform architectures is concentrating connected appliance deployment in Chinese metropolitan housing developments.
Market Restraints
- OLED Display Supply Concentration:Korean manufacturers control critical output capacity for premium smart refrigerator interface panels, creating input cost volatility for competing OEMs.
- Cybersecurity Certification Friction:Emerging national encryption standards for IoT-enabled household equipment are extending product launch timelines and compliance expenditure.
- Sensor Module Bottleneck:Hardening availability constraints for MEMS-based environmental sensors are limiting production scaling for mid-tier connected appliance lines.
Strategic Opportunities
- India Smart Home Underpenetration:Low connected appliance penetration in Indian urban residential markets offers first-mover positioning for localized platform partnerships.
- Precision Cooking Algorithm Licensing:Commercial hospitality buyers are purchasing subscription-based culinary optimization software for smart oven fleets.
- US ENERGY STAR Rebate Alignment:Utility rebate eligibility for EPA-certified connected devices is opening channel partnerships with regional electricity distributors.
Industry Challenges
- Embedded Systems Talent Scarcity:Shortage of firmware engineers with IoT security specialization is delaying product development cycles across appliance engineering teams.
- Multi-Protocol Integration Complexity:Fragmentation across Wi-Fi, Zigbee, Matter, and proprietary connectivity stacks is forcing redundant hardware design and certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Appliances Market |
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $371.99 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Refrigerators, Smart Ovens, Smart Washers, Smart Dishwashers Technology: Wi-Fi, Bluetooth, Voice Control, IoT Integration End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics Inc., Whirlpool Corporation, BSH Hausgeräte GmbH, Panasonic Holdings Corporation, AB Electrolux, Haier Smart Home Co., Ltd., GE Appliances, Midea Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Appliances Market Strategic Shifts
Edge computing migration and predictive maintenance algorithm deployment are compressing the latency between appliance sensor data and automated response, reshaping how manufacturers monetize hardware through software-enabled service layers.
Sensor fusion architectures combining temperature, humidity, occupancy, and energy consumption data streams are enabling context-aware automation in residential environments. High-end property developers in Germany and the Netherlands are specifying these capabilities as standard in new construction. The technology is integrating appliance operation with building management systems, collapsing the distinction between standalone devices and integrated home infrastructure.
REACH chemical compliance standards and the EU AI Act's risk classification framework are tightening material selection and algorithmic transparency requirements for appliances sold across Europe. Manufacturers must now document training data provenance for cooking recommendation engines. Smart oven products with autonomous decision-making capabilities face the most intensive conformity assessment timelines.
Commercial hospitality buyers are consolidating procurement through equipment-as-a-service contracts that unbundle hardware ownership from maintenance and software update obligations. Full-service restaurant chains in France and Japan are piloting these arrangements for connected kitchen fleets. This model shifts capital expenditure to operating budgets while locking suppliers into decade-long performance commitments.
Global Smart Appliances Market Segmentation
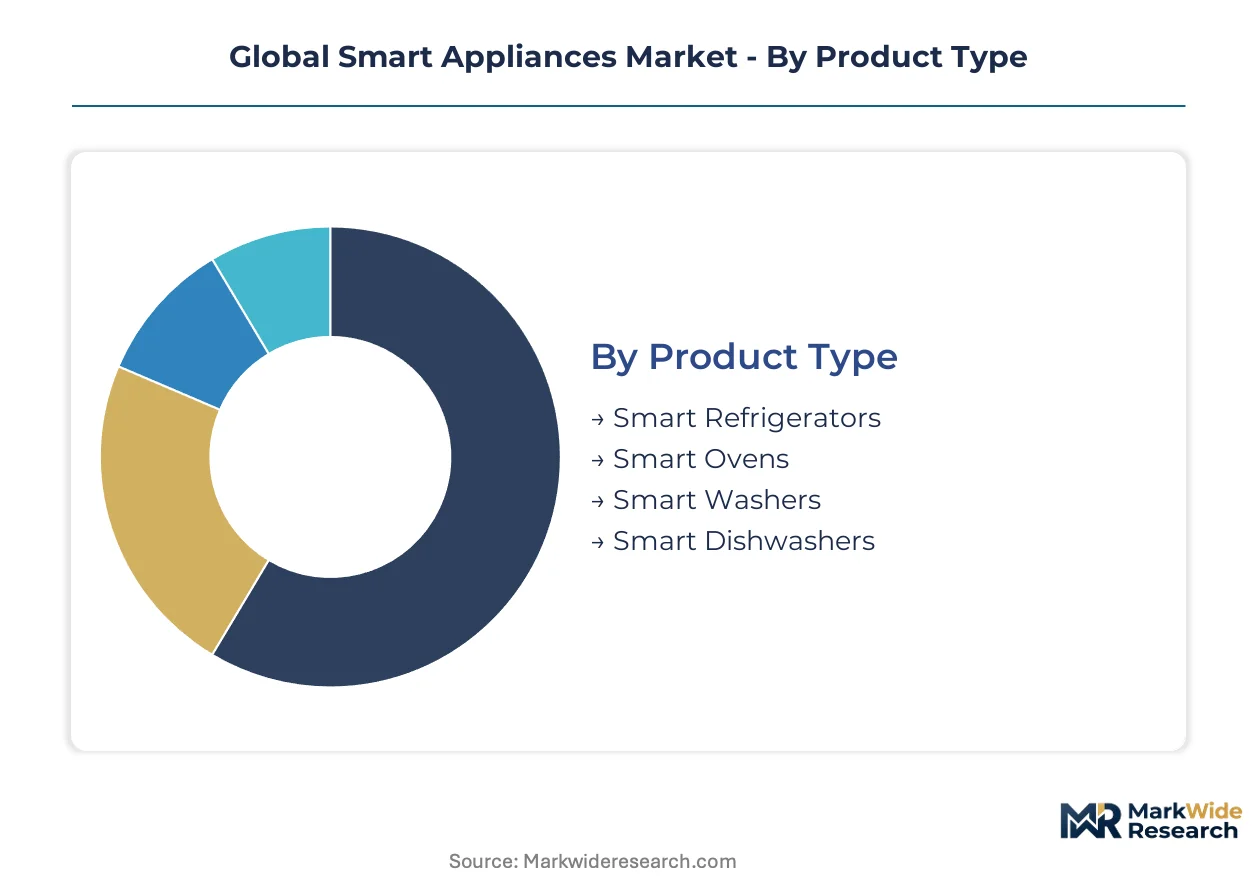
Smart appliance segmentation reveals divergent certification pathways and margin architectures across product categories. Regulatory frameworks from the EPA, EU Ecodesign, and China's GB standards impose distinct testing burdens on each segment, reshaping how manufacturers allocate R&D and compliance resources.
Product Type:
Smart refrigerators carry the heaviest certification load, requiring EPA ENERGY STAR validation, EU Ecodesign efficiency thresholds, and FCC electromagnetic compliance for embedded connectivity modules. Smart ovens face additional scrutiny under the EU AI Act for autonomous cooking algorithms.
- Smart Refrigerators:These units integrate multi-zone climate control, camera-based inventory systems, and OLED interface panels. Demand concentrates in Chinese metropolitan housing developments where Haier and Midea bundle connected kitchen ecosystems through open-source platform architectures. EU Ecodesign mandates on minimum efficiency thresholds accelerate replacement cycles across German and Dutch residential markets.
- Smart Ovens:Precision cooking algorithms enable automated temperature curves and ingredient recognition. Commercial hospitality buyers in France and Japan are consolidating procurement through equipment-as-a-service contracts that unbundle hardware from software update obligations. The EU AI Act's risk classification framework imposes intensive conformity assessment timelines on autonomous decision-making capabilities.
- Smart Washers:Sensor-driven load optimization and remote cycle management dominate residential specifications. Water efficiency certifications from EPA WaterSense and EU Ecolabel shape regional product variants.
- Smart Dishwashers:Connected diagnostics and energy consumption tracking appeal to utility rebate programs. REACH chemical compliance standards restrict detergent dispensing system materials in European markets.
Leading the category by volume: smart refrigerators. Growing fastest: smart ovens.
Technology:
Technology segmentation maps directly to hardware cost structures and interoperability complexity. Multi-protocol integration forces redundant certification across FCC, CE marking, and China's SRRC radio transmission standards.
- Wi-Fi:Dominant connectivity stack enabling cloud-based remote operation and over-the-air firmware updates. Residential installations in US suburban markets prioritize mesh network compatibility for whole-home coverage.
- Bluetooth:Lower-power protocol for proximity-based pairing and localized control. Smart refrigerator water filter replacement alerts and smart oven preheat notifications leverage this stack for reduced latency.
- Voice Control:Natural language processing advances embed this interface as the dominant human-machine layer in residential smart kitchens. Amazon Alexa and Google Assistant certification programs add 4-6 weeks to product launch timelines.
- IoT Integration:Comprehensive platform architecture enabling sensor fusion and predictive maintenance. Building management system integration in German and Dutch new construction specifications drives commercial demand.
Wi-Fi dominates installed base. Voice control climbs the fastest.
End User:
End user segmentation determines service model architecture and pricing elasticity. Residential buyers prioritize upfront cost containment while commercial and hospitality segments accept subscription-based software layers.
- Residential:Individual households purchasing through retail channels. Energy management and remote monitoring capabilities drive replacement decisions in EU markets facing escalating electricity tariffs.
- Commercial:Corporate cafeterias and institutional food service operations. Equipment-as-a-service contracts shift capital expenditure to operating budgets while locking suppliers into performance commitments.
- Hospitality:Full-service restaurant chains and hotel kitchen operations. Precision cooking algorithm licensing generates recurring revenue streams from smart oven fleet deployments.
- Retail:Appliance showroom and electronics retail environments requiring demonstration connectivity and inventory management integration.
Residential claims the largest absolute volume. Hospitality expands most quickly.
Distribution Channel:
Channel segmentation reflects divergent margin extraction and customer acquisition cost profiles. Direct sales and distributor networks carry heavier technical support burdens than self-service online retail.
- Online Retail:E-commerce platforms and manufacturer direct-to-consumer storefronts. US utility rebate eligibility for EPA-certified devices opens channel partnerships with regional electricity distributors through this route.
- Offline Retail:Big-box appliance stores and specialty electronics retailers. In-person demonstration requirements for voice control interfaces sustain this channel's relevance.
- Direct Sales:Manufacturer-owned sales forces targeting commercial hospitality and new construction property developers. Full-service contracts with decade-long performance commitments require consultative selling.
- Distributors:Third-party logistics and value-added resellers covering fragmented regional markets. Inventory carrying costs and technical training obligations concentrate this channel in high-volume metropolitan corridors.
Online retail leads transaction volume. Direct sales delivers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Korean semiconductor foundries and display fabs anchor component supply for smart appliance manufacturing worldwide. This feedstock geography shapes where assembly clusters concentrate and which OEMs secure captive component access.
United States
Residential demand concentrates in suburban markets prioritizing mesh Wi-Fi compatibility and voice control integration. The EPA ENERGY STAR program certifies connected devices for utility rebate eligibility across regional electricity distributors. Appliance assembly clusters in the Southeast and Midwest source display panels and sensor modules through long-term offtake agreements with Korean suppliers.
China
Metropolitan housing developments in Shanghai, Beijing, and Shenzhen drive volume through bundled smart home ecosystem deployments. The MIIT governs radio transmission standards under GB certification frameworks for domestic IoT platforms. Haier and Midea leverage open-source U+ platform architectures to integrate appliances with local cloud infrastructure at scale.
Germany
New construction specifications in Berlin, Munich, and Hamburg mandate sensor fusion capabilities integrating appliances with building management systems. The EU Ecodesign framework and REACH chemical compliance standards impose material selection and interoperability mandates. Premium property developers specify context-aware automation as standard infrastructure.
South Korea
Domestic demand for OLED refrigerator interfaces and MEMS-based environmental sensors concentrates in Seoul and Busan metropolitan corridors. The MFDS oversees device safety while MIIT-aligned standards govern cross-border platform compatibility. Samsung Electronics and LG Electronics leverage vertical integration across semiconductor and appliance divisions to secure captive chip supply.
India
Urban residential markets in Mumbai, Bangalore, and Delhi-NCR present first-mover positioning for localized platform partnerships amid low connected appliance penetration. The BIS mandates safety certifications for imported electronic components under the Compulsory Registration Order. Regional distributors carry inventory concentrated in high-volume metropolitan corridors facing technical training obligations.
Global Smart Appliances Market Competitive Environment
Global majors compete with regional champions across platform ecosystem control and component supply security. The vendor base stratifies between vertically integrated conglomerates with captive semiconductor supply, platform-agnostic appliance specialists, and emerging IoT-native entrants. Three archetypes dominate: ecosystem orchestrators bundling hardware with proprietary cloud infrastructure, component-integrated manufacturers securing display and sensor supply, and software-layer specialists licensing precision algorithms to commercial buyers. Competitive moves center on strategic partnerships with utility distributors for rebate channel access and backward integration into sensor module production.
Within the ecosystem orchestrator tier, Samsung Electronics Co., Ltd. and LG Electronics Inc. exemplify vertically integrated structures spanning semiconductor fabrication through finished appliance assembly. Haier Smart Home Co., Ltd. occupies a distinct position anchoring open-source platform architectures in Asian metropolitan markets. These three entities represent divergent strategic postures: Korean conglomerates leveraging captive component supply, Chinese firms prioritizing domestic cloud integration scale.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Whirlpool Corporation |
| BSH Hausgeräte GmbH |
| Panasonic Holdings Corporation |
| AB Electrolux |
| Haier Smart Home Co., Ltd. |
| GE Appliances |
| Midea Group Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU Ecodesign efficiency mandates and emerging cybersecurity certification requirements are forcing appliance OEMs to absorb compliance costs into hardware pricing while restructuring supplier relationships around certified component sources. This demand-side specification tightening compresses margins for non-integrated manufacturers while rewarding vertically integrated players with captive semiconductor and display supply.
Pricing Analysis
Warranty and predictive maintenance service bundling now separates premium smart refrigerator tiers from standard economy offerings, with commercial hospitality buyers accepting subscription-based algorithm licensing for precision cooking capabilities. Price differentiation hinges on ENERGY STAR certification tier and OLED interface panel quality grade. Cost compression in mid-tier connected washer lines is intensifying due to MEMS sensor module scarcity. Residential retail channels exhibit highest price sensitivity, while hospitality equipment-as-a-service contracts show lowest elasticity.
Supply Chain Analysis
Container freight rate volatility and semiconductor fab capacity constraints are reshaping procurement timelines for appliance OEMs sourcing from South Korea, Taiwan, and China. Korean foundries supply critical MEMS environmental sensors and OLED display panels. The supply chain rests on single-source vulnerability for premium refrigerator interface components. Distribution runs through manufacturer-direct sales forces for commercial hospitality contracts and e-commerce platforms for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework for autonomous cooking algorithms creates a compliance moat that favors incumbents with established conformity assessment infrastructure and documented training data provenance.
For Market Incumbents: Acquire captive sensor module production capacity to insulate against Korean semiconductor supply bottlenecks. Samsung Electronics and LG Electronics already leverage in-house chip fabrication to secure display panel supply. Invest in firmware engineering talent pools with IoT security specialization to accelerate product development cycles threatened by embedded systems scarcity. For New Entrants and Emerging Players: Launch via direct-to-consumer online retail channels targeting Indian metropolitan markets with localized platform partnerships. White-space exists in mid-tier smart washer segments facing sensor availability constraints that exclude established OEMs from volume scaling. Precision cooking algorithm licensing for commercial hospitality fleets offers recurring revenue without hardware manufacturing capital intensity. For Investors and Strategic Acquirers: The window for entry favors component-integrated manufacturers with backward integration into MEMS sensor or OLED display production. Long-term viability across the projection horizon hinges on supply security rather than brand equity alone. Watch for Korean foundry capacity expansion announcements as the inflection signal for input cost relief.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Module Backward Integration | Captive MEMS production insulates OEMs from Korean supply bottlenecks and stabilizes input costs. |
| EU Cybersecurity Certification Investment | Early compliance with emerging encryption mandates accelerates product launch timelines versus lagging competitors. |
| Precision Algorithm Licensing Launch | Software-as-a-service models generate recurring revenue from French and Japanese hospitality fleet deployments. |
| Indian Platform Partnership Formation | Localized cloud integration with domestic IoT providers captures first-mover positioning in underpenetrated urban markets. |
| Utility Rebate Channel Alignment | EPA ENERGY STAR certification unlocks regional electricity distributor partnerships for residential replacement demand. |
Study Parameters
Independent corroboration across appliance engineering executives, smart home platform architects, and commercial hospitality procurement directors underwrites the qualitative findings in this study. Primary interviews with semiconductor supply planners and regulatory affairs specialists at Korean and Chinese OEMs were cross-referenced against secondary validation from MIIT GB standard filings, EPA ENERGY STAR certification databases, and EU Ecodesign implementing measure texts. Bottom-up unit shipment estimates by product category were reconciled with top-down value projections across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across Wi-Fi connectivity, voice control interface, and full IoT integration technology tiers. Segmentation modeling incorporates product type, connectivity protocol, end-user archetype, and distribution channel dimensions. CAGRs were derived from fitted trend extrapolation adjusted for regulatory mandate implementation schedules and sensor module supply elasticity. Forecast inputs include Korean foundry capacity utilization rates and EU AI Act conformity assessment timeline assumptions.
Semiconductor supply disruption, cybersecurity certification deadline acceleration, and REACH chemical compliance scope expansion are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Global Baby Car Seats Market
Consumer Goods
Sports Socks for Children Market
Consumer Goods
Australia Denim Jeans Market
Consumer Goods
UK Camping Equipment Market
Consumer Goods
APAC Smart Watch Market
Consumer Goods
Underwear Disinfection Dryers Market
Consumer Goods
Intelligent Electric Rice Cooker Market
Consumer Goods
Global Beard Balm Market
Consumer Goods
Germany Hair Care Market
Consumer Goods
Australia Vegan Cosmetics Market
Consumer Goods
Handmade False Eyelash Market
Consumer Goods
Floor Displays Market
Consumer Goods
Europe Soundbar Market
Consumer Goods
Brush Cover Market
Consumer Goods
New Zealand Camping Equipment Market
Consumer Goods
Hair Accessories Market