
 Commercial Countertop Ranges Market | 2026-2036
Commercial Countertop Ranges Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Countertop Ranges Market Outlook
Cloud kitchen operators are redrawing procurement priorities for commercial countertop ranges, favoring induction and high-capacity gas configurations over traditional electric models. Vulcan leverages its foundry-to-finished-product pipeline to control lead times on heavy-duty gas lines. Garland anchors its position through deep specialization in modular configurations for high-volume restaurants. Southbend differentiates via NSF-certified ranges engineered for food safety compliance in institutional settings.
Commercial countertop ranges are self-contained cooking appliances designed for installation on work surfaces, typically featuring open burners with outputs from 25,000 to 150,000 BTU per burner and constructed from stainless steel frames with cast iron grates for thermal retention and durability. Their primary purpose is to deliver high-intensity, controllable heat in space-constrained professional kitchens where floor-standing equipment is impractical. Gas configurations still occupy the largest installed base due to chef preference for instantaneous temperature modulation, though induction segments are recording the fastest growth as operators confront rising utility costs and ventilation constraints. Multi-burner and high-capacity variants capture disproportionate margin pools because they command premium pricing in steakhouse and hotel banquet applications where throughput determines revenue per square foot.
NSF International standards govern food equipment sanitation and materials safety across the US market, while the DOE's energy conservation standards for commercial cooking equipment mandate minimum efficiency thresholds that reshape product development roadmaps. The EPA's ENERGY STAR certification program creates market access differentiation for manufacturers whose induction and electric ranges meet strict performance criteria. Stakeholders must monitor how municipal electrification mandates in cities like New York and Seattle constrain gas hookup availability and redirect capital toward induction infrastructure.
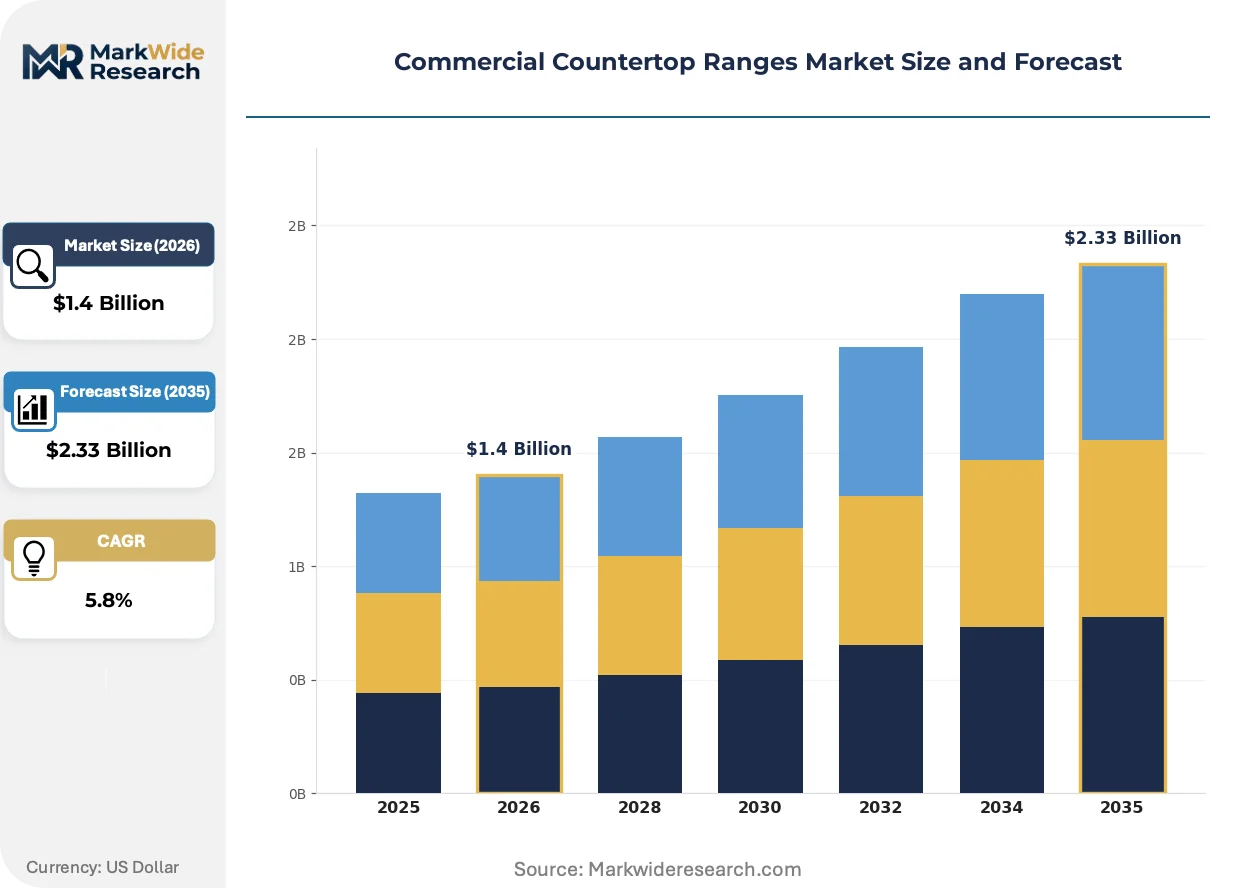
Market Dynamics
The US Department of Energy's efficiency standards for commercial cooking equipment are forcing a technology migration from open-flame gas configurations to induction systems, compressing the installed base of legacy equipment while opening premium replacement cycles.
Growth Catalysts
- Food truck permitting expansion:Mobile kitchen operators in Texas, Florida, and California are driving compact high-output equipment procurement as municipal licensing accelerates.
- Cloud kitchen density:Ghost kitchen operators favor modular countertop configurations that maximize throughput per square foot in delivery-only facilities.
- ENERGY STAR certification:The EPA's efficiency program creates procurement preference for induction ranges in institutional foodservice contracts.
Market Restraints
- Copper and cast iron input volatility:Foundry-grade metal price swings compress margin stability for heavy-duty gas range manufacturers.
- Ventilation infrastructure lock-in:Existing hood systems in older commercial kitchens create technical friction for induction retrofits requiring different exhaust profiles.
- Municipal gas hookup moratoria:Electrification mandates in New York and Seattle constrain new gas range installations regardless of chef preference.
Strategic Opportunities
- Institutional NSF-certified segments:Healthcare and correctional foodservice facilities represent underpenetrated demand for safety-compliant ranges.
- Induction-gas hybrid configurations:Dual-fuel countertop systems address chef preference while satisfying emerging efficiency codes.
- Direct-to-operator digital channels:Equipment rental platforms and B2B marketplaces bypass traditional foodservice distribution for independent restaurants.
Industry Challenges
- Certification timeline compression:NSF and DOE compliance testing creates product launch delays as standards tighten simultaneously.
- Legacy electrical infrastructure:Older buildings require costly panel upgrades to support high-amperage induction installations, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Countertop Ranges Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas, Electric, Induction, Combination End User: Restaurants, Cafes, Catering Services, Food Trucks Capacity: Single, Double, Multi-Burner, High Capacity Installation Type: Counter-Mounted, Stand-Alone, Built-In, Portable |
| Companies Covered | Cooking Performance Group, Vulcan, Garland, American Range Corporation, Imperial, Southbend, Waring, Nemco, Alto-Shaam Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Countertop Ranges Market Strategic Shifts
Induction technology is compressing the competitive landscape by rewarding manufacturers with captive power electronics capabilities while penalizing pure-play gas specialists. Three developments are restructuring product roadmaps and procurement patterns.
Precision induction coil arrays with embedded temperature feedback loops are displacing traditional thermostatic gas controls in high-throughput applications. Steakhouse chains and hotel banquet operations are adopting these systems to reduce ventilation loads and utility exposure. The technology is displacing conventional gas ranges in new construction projects where total cost of ownership calculations dominate capital allocation.
The EPA's ENERGY STAR Version 3.0 commercial cooking equipment specification tightens idle energy limits and introduces cooking energy efficiency metrics. Manufacturers must redesign control logic and insulation packages to maintain certification access. Induction and electric range categories face the steepest compliance thresholds, accelerating R&D concentration among mid-cap specialists with captive electronics engineering.
Cloud kitchen operators are consolidating procurement through equipment-as-a-service arrangements that bundle installation, maintenance, and upgrade rights. Traditional dealer networks lose volume to direct manufacturer relationships and third-party rental platforms. This behavior shift concentrates most visibly in California and Texas metropolitan markets where ghost kitchen facility construction outpaces conventional restaurant openings.
Commercial Countertop Ranges Market Segmentation
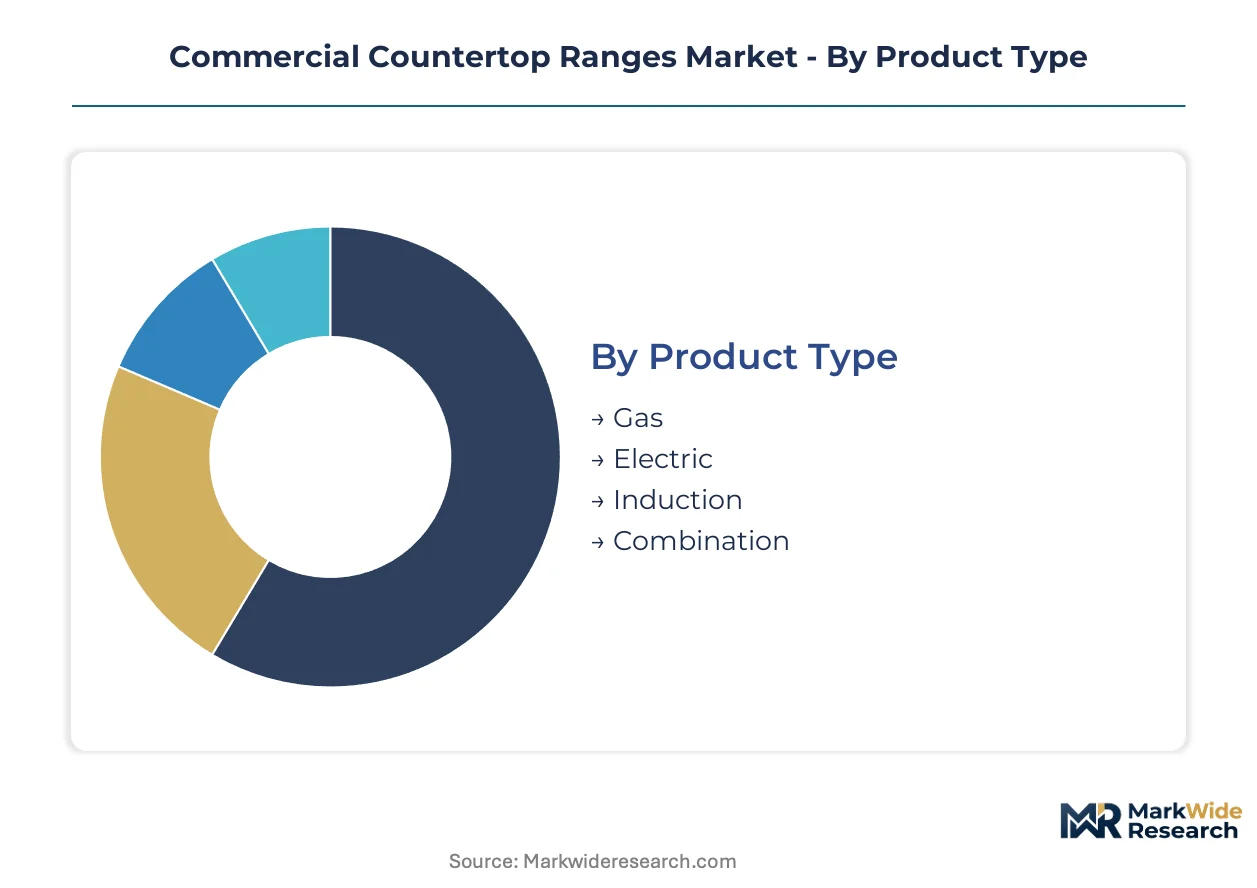
Commercial countertop ranges segment across four critical dimensions that determine procurement patterns, regulatory exposure, and margin architecture. Product type and capacity classifications carry the heaviest weight in capital allocation decisions, while end-user and installation categories dictate distribution channel selection and service requirements.
Product Type:
DOE efficiency standards and ENERGY STAR certification thresholds create divergent compliance burdens across fuel technologies, reshaping manufacturer R&D priorities and operator replacement cycles.
- Gas:Open-flame configurations with instantaneous temperature modulation dominate chef preference in high-throughput steakhouse and hotel banquet settings. Legacy installed base concentration in Texas, Florida, and California sustains replacement demand despite electrification mandates in coastal municipalities.
- Induction:Precision coil arrays with embedded temperature feedback loops reduce ventilation loads and utility exposure in cloud kitchen facilities. The EPA's ENERGY STAR Version 3.0 specification tightens idle energy limits, accelerating R&D concentration among manufacturers with captive power electronics capabilities.
- Electric:Resistance-element systems occupy mid-market positioning with lower capital cost but higher operating expense profiles.
- Combination:Dual-fuel hybrid configurations address chef preference while satisfying emerging efficiency codes in jurisdictions with partial electrification mandates.
Established volume favors gas configurations; emerging adoption favors induction systems.
End User:
Procurement authority and specification complexity vary sharply across operator scale, with institutional contracts demanding NSF certification and independent restaurants prioritizing flexibility.
- Restaurants:Full-service and quick-service operators drive multi-burner and high-capacity variant demand where throughput determines revenue per square foot. Chef preference for flame visibility sustains gas specification in premium dining segments despite utility cost pressure.
- Food Trucks:Mobile kitchen operators in Texas, Florida, and California seek compact, high-output cooking surfaces with portable installation profiles. Municipal permitting acceleration in these states concentrates procurement volume for space-optimized configurations.
- Catering Services:Event-based operators require rapid deployment capabilities and modular burner arrangements for variable menu execution.
- Cafes:Limited-menu operators favor single and double burner electric configurations with minimal ventilation infrastructure requirements.
Contract volume concentrates in restaurants; steepest expansion trajectory appears in food trucks.
Capacity:
Throughput economics and kitchen footprint constraints determine burner count selection, with premium pricing attaching to configurations that maximize output density.
- Multi-Burner:Four to six burner arrays capture disproportionate margin pools in high-volume applications where simultaneous cooking operations justify capital intensity. Hotel banquet and institutional foodservice facilities specify these configurations for peak-period throughput.
- High Capacity:Specialized units exceeding standard burner output ratings serve steakhouse chains and production kitchens with intensive protein cooking requirements. Foundry-grade cast iron grate construction and enhanced gas manifold pressure distinguish this tier.
- Double:Two-burner configurations balance space efficiency with operational flexibility for mid-scale independent restaurants.
- Single:Compact units address supplemental cooking needs and severe space constraints in food trucks and small cafes.
Revenue concentration sits with multi-burner specifications; fastest share gains occur in high-capacity variants.
Installation Type:
Physical integration requirements determine electrical and ventilation infrastructure needs, with portable configurations commanding rental market participation.
- Counter-Mounted:Standard work-surface installation dominates new construction and renovation projects where permanent kitchen layouts are established. NSF sanitation certification and stainless steel frame construction are baseline requirements.
- Portable:Self-contained units with integrated power connections and caster mobility serve food trucks and temporary catering operations. Equipment-as-a-service rental platforms concentrate procurement volume in California and Texas metropolitan markets.
- Stand-Alone:Freestanding configurations with integrated base storage address kitchens lacking built-in counter infrastructure.
- Built-In:Flush integration with custom millwork specifies premium dining and display kitchen applications.
Permanent installation favors counter-mounted units; flexibility demand favors portable configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based manufacturers export commercial countertop ranges to foodservice operators across Canada and Mexico under USMCA trade provisions, with cross-border volumes concentrated in high-efficiency induction configurations.
United States
Food truck permitting expansion in Texas, Florida, and California drives compact high-output equipment procurement. The Department of Energy's commercial cooking equipment efficiency standards mandate minimum thresholds that reshape product development roadmaps. Cloud kitchen density in Los Angeles, Dallas, and Miami concentrates demand for modular countertop configurations.
Canada
Institutional foodservice contracts in healthcare and correctional facilities prioritize ENERGY STAR-certified induction ranges. Health Canada's food equipment safety guidelines align with NSF sanitation standards for cross-border equipment acceptance. Toronto and Vancouver metropolitan markets lead ghost kitchen facility construction.
Mexico
Quick-service restaurant chains expanding into northern border states specify multi-burner gas configurations for high-throughput protein cooking. The country's national energy efficiency regulator implements commercial appliance standards that gradually tighten efficiency requirements. Monterrey and Mexico City anchor procurement volume for heavy-duty countertop equipment.
Germany
Precision engineering demands from hotel banquet and premium dining segments favor induction systems with embedded temperature feedback controls. The EU Ecodesign Directive and F-Gas Regulation constrain gas infrastructure expansion in new commercial construction. Frankfurt and Munich clusters concentrate cloud kitchen operator procurement.
China
Domestic foodservice modernization programs accelerate replacement of legacy gas ranges with induction alternatives in tier-one cities. The Ministry of Industry and Information Technology's dual carbon goals pressure commercial kitchen electrification timelines. Shanghai and Shenzhen manufacturing bases supply cost-optimized induction coil arrays for export markets.
Commercial Countertop Ranges Market Competitive Environment
Listed leaders compete with private specialists across certification depth and foundry integration. The vendor base stratifies between consolidated heavy-duty gas fabricators and emerging induction technology specialists. Three archetypes dominate: foundry-integrated manufacturers controlling cast iron supply chains, power electronics specialists with captive coil engineering, and modular configuration providers serving cloud kitchen operators. Competitive moves concentrate on vertical integration into foundry operations and strategic partnerships with equipment-as-a-service rental platforms.
Specialists in heavy-duty gas configurations include Vulcan, Garland, and Southbend. Vulcan exemplifies the foundry-integrated archetype with upstream control over cast iron grate production. Garland occupies a position within modular configuration providers serving high-volume restaurant segments. Southbend anchors the NSF-certified institutional tier, representing compliance-focused positioning for healthcare and correctional foodservice contracts.
| Leading Market Players |
|---|
| Cooking Performance Group |
| Vulcan |
| Garland |
| American Range Corporation |
| Imperial |
| Southbend |
| Waring |
| Nemco |
| Alto-Shaam Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day foundry lead times for cast iron grates compress margin buffers for gas range specialists while amplifying pricing power for induction manufacturers with captive coil production. This inventory-to-pricing dynamic concentrates procurement leverage among operators in Texas, Florida, and California who face municipal electrification mandates.
Pricing Analysis
The technology-generation pricing gap between legacy open-flame gas systems, current induction coil arrays, and next-generation precision feedback controls structures procurement decisions across operator tiers. Three-tier pricing stratification separates NSF-certified institutional units from standard commercial configurations and economy-grade portable equipment for food trucks. Price differentiation hinges on ENERGY STAR certification tier and foundry-grade material specification. Cost compression in mid-market gas configurations is intensifying because copper and cast iron input volatility erodes manufacturer margins. Independent restaurants exhibit highest price sensitivity, while hotel banquet operations prioritize total cost of ownership over capital outlay.
Supply Chain Analysis
Inventory-to-delivery cycles stretching sixteen to twenty-four weeks for heavy-duty gas components expose procurement risk for operators with compressed renovation timelines. Manufacturing concentration centers on the United States, China, and Germany for finished equipment assembly, with induction coil arrays sourcing from Shanghai and Shenzhen production bases. Supply chains draw from foundry-grade cast iron, copper gas manifolds, and power electronics modules as critical inputs. Single-source vulnerability in semiconductor components for induction controls threatens production continuity. Distribution runs through foodservice equipment dealers, direct manufacturer relationships, and emerging equipment-as-a-service rental platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service bundling transforms commercial countertop ranges from capital goods into subscription-accessed infrastructure, creating platform-economics dynamics as cloud kitchen operators consolidate procurement through rental platforms rather than traditional dealer networks.
For Market Incumbents: Consolidate upstream control over foundry operations to buffer cast iron price volatility and compress lead times against emerging induction specialists. Lock in NSF certification depth for institutional healthcare and correctional contracts where compliance barriers protect position. Defensive capacity concentration in Texas and California manufacturing footprints addresses food truck and ghost kitchen demand density while hedging municipal gas hookup moratoria in coastal markets. For New Entrants and Emerging Players: Maintenance and upgrade service layers represent under-served territory where incumbent manufacturers cede recurring revenue to third-party service networks. The institutional NSF-certified segment offers most penetrable white-space given compliance-driven procurement stickiness and incumbent complacency. A direct-to-operator digital channel bypassing traditional foodservice distribution captures independent restaurant volume in metropolitan Texas and Florida markets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parents with captive foodservice equipment divisions lacking induction technology roadmaps. Long-term viability favors power electronics specialists with captive coil engineering capabilities over pure-play gas fabricators facing regulatory obsolescence risk. Watch municipal electrification mandate expansion velocity as inflection indicator for technology migration pace and stranded asset exposure in legacy gas portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Cast iron grate production control insulates Vulcan and Garland from commodity volatility and lead-time compression. |
| NSF Certification Investment | Southbend's institutional focus captures healthcare procurement contracts requiring food safety compliance documentation. |
| Equipment-as-a-Service Platform Launch | Rental bundling in California and Texas metropolitan markets displaces traditional dealer volume for cloud kitchen operators. |
| Induction-Gas Hybrid Configuration Development | Dual-fuel systems address chef preference in jurisdictions with partial electrification mandates like New York. |
| Direct-to-Operator Digital Channel | Bypassing foodservice distribution captures independent restaurant procurement in high-permitting Texas and Florida markets. |
Study Parameters
Cross-validation between regulatory filing analysis and equipment procurement database triangulation anchors the qualitative findings in documented compliance and transaction patterns. Primary interviews with ghost kitchen facility operators, food truck fleet managers, institutional foodservice directors, and commercial equipment dealers combined with secondary validation from DOE efficiency standard filings, EPA ENERGY STAR certification records, and municipal permitting databases. Bottom-up demand modeling from operator installation counts and top-down market sizing from manufacturer shipment data converge across the analysis window.
Sensitivity analysis around electrification mandate adoption rates and foundry input cost trajectories bounds the forecast range. Segmentation dimensions span fuel technology, burner capacity tier, end-user category, and installation type, with regional regulatory cluster as an additional modeled dimension. CAGRs derive from installed base replacement cycles and new construction penetration assumptions. Food truck permitting velocity in Texas, Florida, and California and cloud kitchen facility construction pipelines in Los Angeles, Dallas, and Miami serve as industry-specific forecast inputs.
Underlying assumptions cover steady municipal electrification policy progression and stable USMCA trade provisions for cross-border equipment flows, with deviation risk concentrated in copper and cast iron commodity volatility and accelerated gas hookup moratoria. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Popcorn Makers Market
Kitchen Appliances
United States Small Kitchen Appliances Market
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
Smart Cooktop Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Warming Drawer Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
Europe Household Appliances Market
Kitchen Appliances
Electric Hobs Market