
 Global Stainless Woks Market | 2026-2036
Global Stainless Woks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stainless Woks Market Outlook
Commercial foodservice buyers is bifurcating demand away from traditional home-kitchen purchasers as ghost kitchens and quick-service Asian concepts multiply. Meyer Corporation leverages vertical integration across its Asian manufacturing footprint to sustain cost discipline in bulk restaurant supply. Zwilling J.A. Henckels anchors premium positioning through German engineering heritage and specialty retail channel control. Sanho Kitchenware competes on induction-compatible designs that dominate European commercial specifications.
Stainless woks are concave cooking vessels fabricated from chromium-nickel steel alloys, typically containing 18% chromium and 8-10% nickel, formed through deep-drawing or spinning processes and finished with brushed or mirror surfaces to resist corrosion at sustained temperatures above 200°C. Flat-bottom variants lead volume in Western residential kitchens where flat cooktops predominate, while round-bottom woks retain dominance in professional Asian kitchens where flame contact and tossing motion dictate geometry. Induction-compatible segments are expanding fastest as electrification mandates reshape commercial kitchen infrastructure across European and North American cities.
China's SAMR enforces GB 4806.9 food-contact metal standards that govern nickel and chromium migration limits, while the EU ECHA administers REACH restrictions on heavy metal content in cookware surfaces. The US FDA maintains indirect food additive regulations under 21 CFR that affect stainless steel composition claims for interstate commerce. Stakeholders must monitor diverging metallurgical standards across these three jurisdictions when configuring alloy specifications and certification documentation for cross-border supply chains.
Market Dynamics
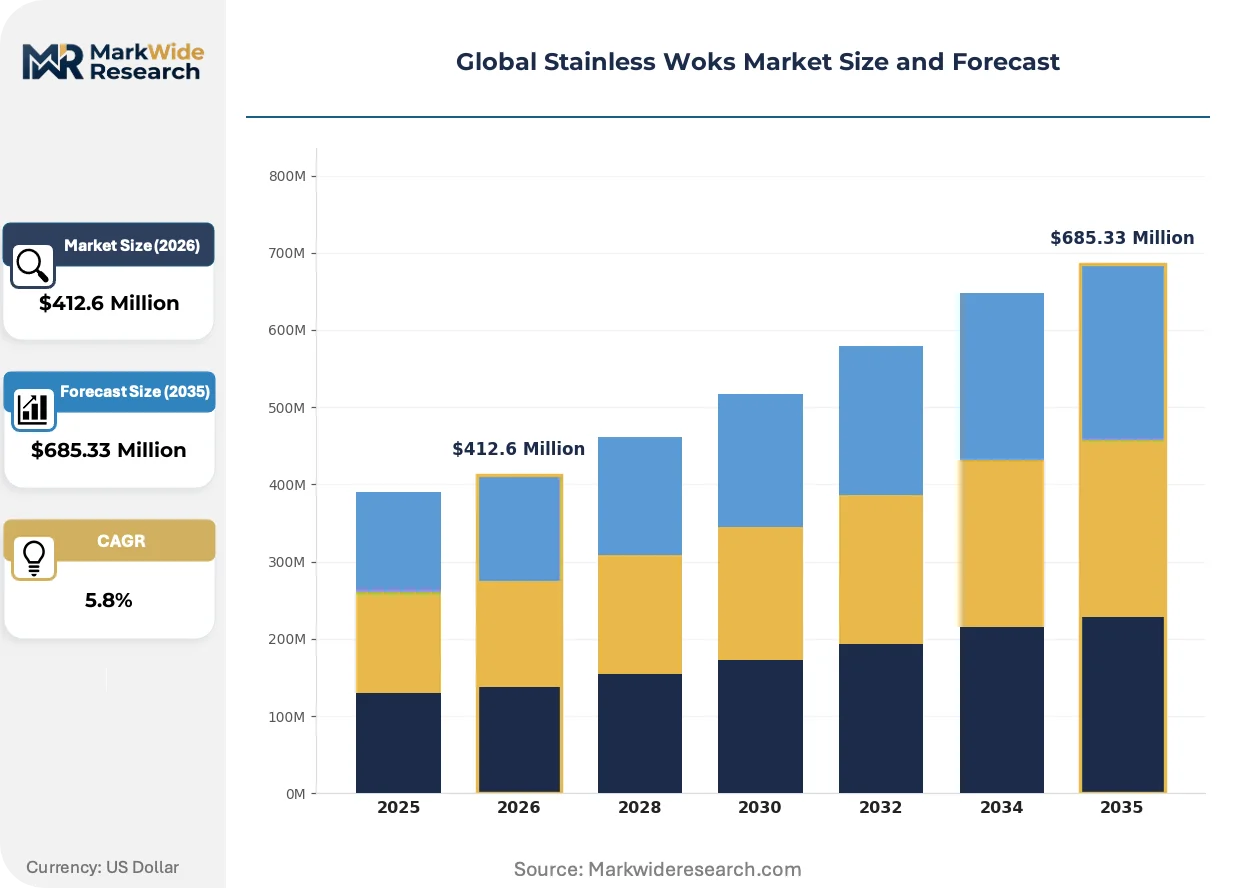
Electrification mandates across commercial kitchen infrastructure are forcing rapid alloy specification changes as induction compatibility becomes a procurement gate rather than a premium feature. This structural shift is compressing legacy carbon-steel wok volumes while elevating ferritic and austenitic stainless grades that satisfy both thermal performance and compliance documentation requirements.
Growth Catalysts
- EU Green Deal electrification mandates:Commercial kitchen retrofit deadlines in Germany, France, and the Netherlands are accelerating stainless wok replacement cycles in foodservice operations.
- Ghost kitchen proliferation:Delivery-only Asian cuisine concepts in US metropolitan markets are expanding centralized wok procurement at volumes exceeding traditional restaurant replacement rates.
- Induction-compatible alloy innovation:Magnetic 430-grade stainless formulations with copper or aluminum cores are capturing specification share in European commercial equipment tenders.
Market Restraints
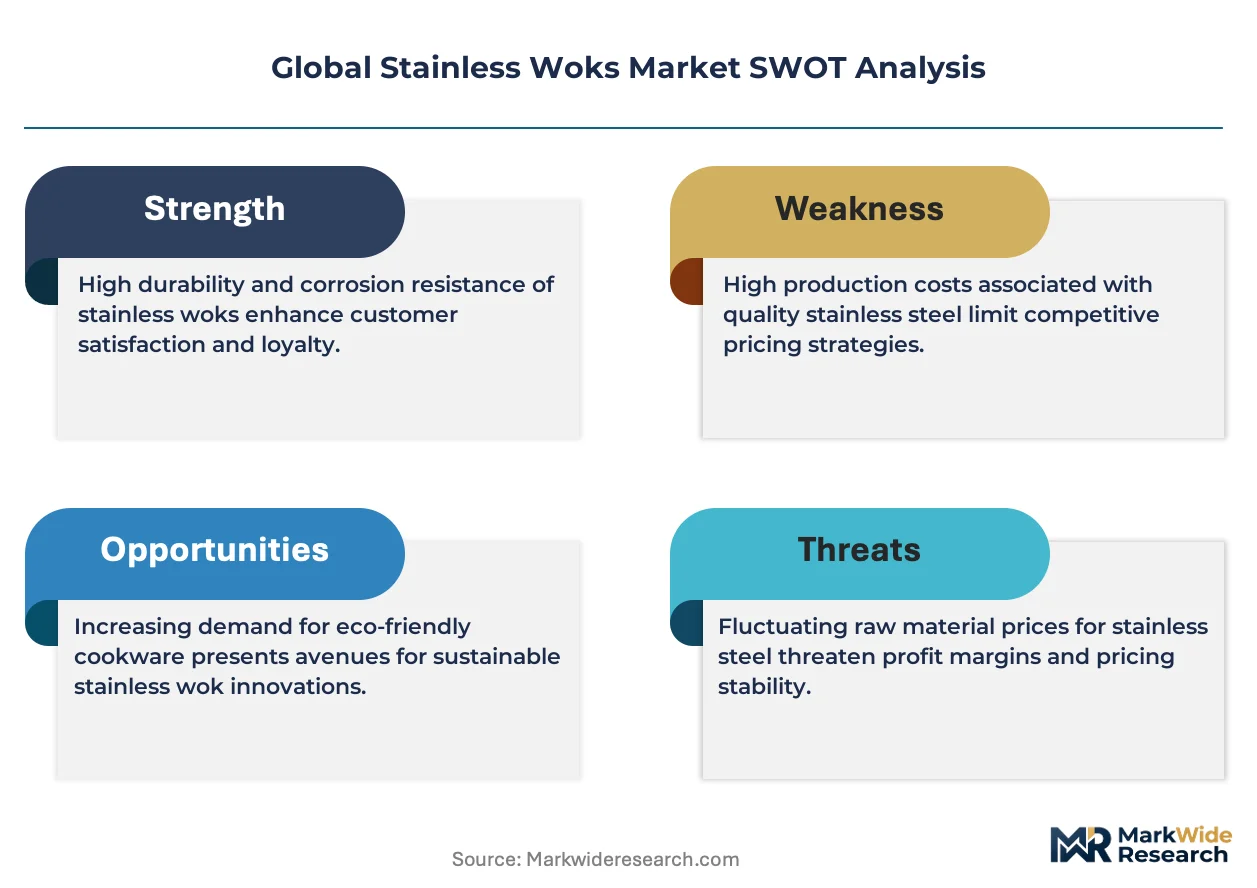
- Nickel price volatility:LME nickel contract swings directly compress margin structures for 304-grade manufacturers dependent on 8-10% nickel content.
- Guangdong supply concentration:Overreliance on a single Chinese manufacturing cluster creates geopolitical and logistics risk exposure for global buyers.
- Carbon-steel substitution persistence:Seasoned iron woks retain cost and thermal responsiveness advantages in price-sensitive Southeast Asian foodservice segments.
Strategic Opportunities
- India foodservice modernization:FSSAI food-contact metal standards are creating compliance-driven upgrade cycles in Mumbai and Bangalore commercial kitchen infrastructure.
- Hybrid induction-gas compatibility:Dual-purpose base designs that perform on both flame and magnetic cooktops address transitional kitchen configurations in European retrofit markets.
- Direct-to-restaurant digital channels:Specialized B2B platforms are disintermediating traditional restaurant supply distributors for standardized commercial-grade wok specifications.
Industry Challenges
- Metallurgical certification complexity:Divergent GB 4806.9, REACH, and FDA 21 CFR testing protocols extend product launch timelines and multiply documentation costs for multi-jurisdiction suppliers.
- Deep-drawing equipment capex:Precision forming of 2.5-3.0mm stainless blanks requires specialized hydraulic presses that mid-scale manufacturers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stainless Woks Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bottom, Round Bottom, Non-Stick, Induction Compatible End User: Home Kitchens, Restaurants, Food Trucks, Catering Services Size: Small, Medium, Large, Extra Large Sales Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale Distributors |
| Companies Covered | Staub, Meyer Corporation, Zwilling J.A. Henckels, Cooker King, Sanho Kitchenware, Heritage Steel, Yosukata, Jiangmen Anotech, Anolon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stainless Woks Market Strategic Shifts
Material science advances and regulatory pressure are converging to redefine performance benchmarks for commercial-grade cookware. Alloy engineers and kitchen equipment specifiers are co-developing solutions that satisfy both thermal efficiency targets and emerging chemical compliance frameworks.
Clad tri-ply construction with aluminum cores bonded between stainless layers is displacing single-wall designs in premium European commercial kitchens. Hotel and institutional buyers in Switzerland and Austria are specifying these configurations for thermal uniformity during high-volume service periods. The technology is compressing demand for traditional spun-steel woks that lack induction compatibility and temperature stability.
REACH restrictions on nickel migration are tightening surface finish requirements for food-contact stainless in EU member states. ECHA enforcement actions against non-compliant imports are elevating third-party certification costs for Asian manufacturers. German and French commercial distributors are now requiring batch-specific test reports as standard procurement documentation.
Consolidated purchasing by multi-unit Asian restaurant chains is restructuring supplier relationships away from fragmented dealer networks. Centralized procurement teams in US and Canadian corporate kitchens are negotiating direct supply agreements with certified manufacturers. This concentration is most visible in Texas and California metropolitan markets where ghost kitchen operators share equipment specification standards across multiple virtual brands.
Global Stainless Woks Market Segmentation
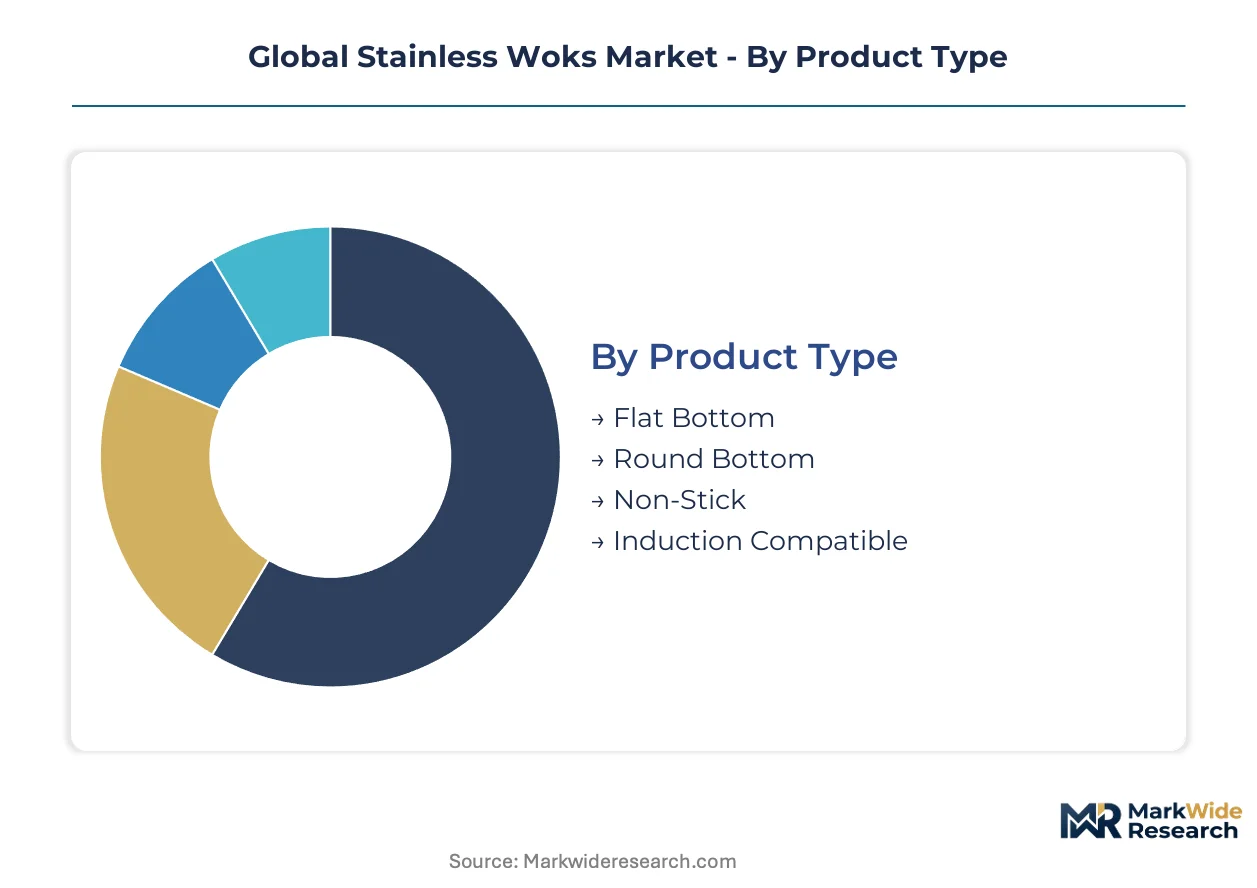
Stainless wok procurement patterns diverge sharply across product geometries, end-use environments, and channel structures. Alloy specifications and base designs must align with distinct thermal requirements and compliance frameworks governing each segment.
Product Type:
Flat-bottom variants dominate domestic Western markets where flat cooktops predominate, while round-bottom designs retain professional Asian kitchen allegiance. Export-led demand concentrates in induction-compatible formulations as electrification mandates reshape commercial specifications.
- Flat Bottom:Engineered with 2.5-3.0mm 304-grade walls and precision-machined bases for full contact with electric and induction surfaces. Demand concentrates in German and US residential markets where home cooks prioritize stability over tossing motion. Thermal efficiency limitations on flame cooktops constrain specification in professional Asian kitchens.
- Induction Compatible:Magnetic 430-grade ferritic stainless or copper-cored tri-ply constructions satisfy commercial electrification procurement gates. European ghost kitchen operators in Amsterdam and Paris specify these configurations for compliance with EU Green Deal retrofit deadlines. The segment commands premium positioning through certification documentation requirements.
- Round Bottom:Traditional spun-steel geometry optimized for flame contact and wok-tossing technique in Cantonese and Sichuan cooking traditions.
- Non-Stick:PFOA-free ceramic or diamond-infused coatings applied to 304-grade substrates for residential convenience markets.
Flat Bottom holds the largest share; momentum sits with Induction Compatible as commercial kitchen electrification accelerates.
End User:
Cost tiers separate commodity procurement for price-sensitive home kitchens from specification-driven commercial equipment investments. Volume concentration tilts toward centralized restaurant purchasing as multi-unit Asian chains consolidate supply relationships.
- Restaurants:Full-service and quick-service Asian concepts specify 14-16 inch commercial-grade woks with NSF or equivalent hygiene certifications. Centralized procurement teams in Dallas and Toronto negotiate direct manufacturer agreements, bypassing traditional dealer markups. Ghost kitchen operators share specification standards across virtual brands, amplifying order volumes.
- Home Kitchens:Residential buyers prioritize 10-12 inch formats with ergonomic handles and dishwasher compatibility. German and Japanese consumers demonstrate willingness to pay premium positioning for clad tri-ply construction. E-commerce reviews and social media demonstration content heavily influence alloy and geometry selection.
- Catering Services:High-volume event operators require stackable, lightweight configurations for transport logistics.
- Food Trucks:Space-constrained mobile kitchens favor compact 12-inch induction-compatible designs with reinforced handles.
Restaurants command the revenue concentration; Home Kitchens are climbing the fastest as pandemic-era cooking skill acquisition persists.
Size:
Application scale and cooking technique dictate diameter selection, with commercial throughput requirements driving large-format specification. Margin structures favor medium and large segments where manufacturing economies offset raw material volatility.
- Large:14-16 inch diameters standard in professional Chinese, Thai, and Vietnamese kitchens for high-heat stir-fry production. Guangdong manufacturers optimize deep-drawing equipment for this specification band, achieving cost discipline through volume concentration. European hotel kitchen tenders routinely specify this format for banquet service capacity.
- Medium:12-14 inch configurations balance residential manageability with small commercial utility. US specialty retailers position these as versatile dual-purpose investments for home cooks expanding into Asian cuisine formats. Induction compatibility features penetrate this segment fastest as mid-market consumers upgrade cooktop infrastructure.
- Small:10-12 inch formats for individual-portion cooking and compact residential kitchens.
- Extra Large:18+ inch diameters for institutional catering and theatrical display cooking in upscale Asian concepts.
Large maintains volume leadership; Medium is gaining share fastest as residential induction adoption broadens the addressable base.
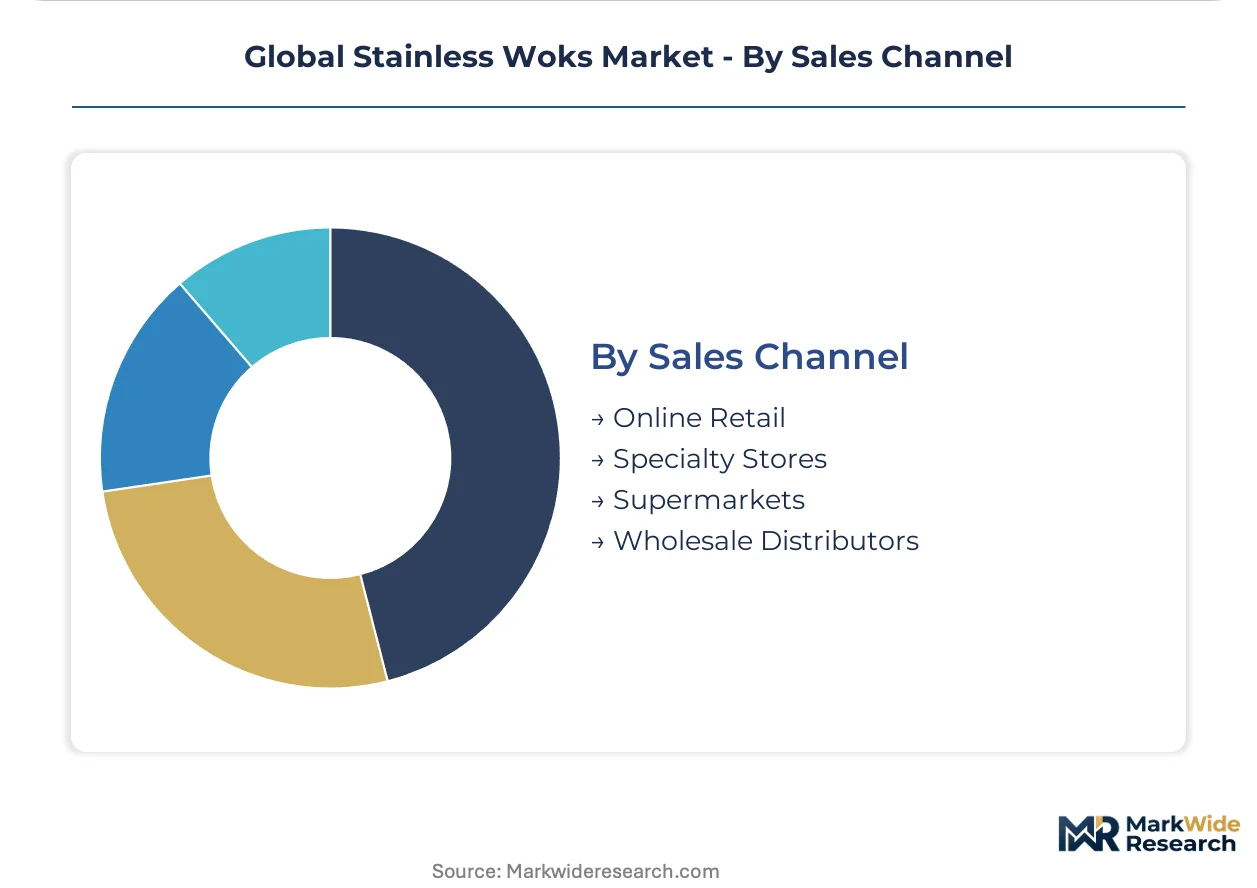
Sales Channel:
Customer type and purchase urgency determine channel selection, with commercial buyers gravitating toward direct relationships and residential purchasers fragmenting across digital and physical touchpoints. Supply concentration in wholesale distributors is eroding as specialized B2B platforms disintermediate traditional networks.
- Wholesale Distributors:Traditional restaurant supply houses maintain inventory depth for emergency replacement and specification consultation. Meyer Corporation and Zwilling J.A. Henckels anchor relationships through exclusive distribution territories and volume rebate structures. German and French distributors now mandate batch-specific REACH compliance documentation as standard procurement terms.
- Online Retail:Amazon, Alibaba, and specialized cookware platforms capture residential demand through review aggregation and comparative specification display. Sanho Kitchenware and emerging direct-to-consumer brands leverage digital channels to bypass retail margin extraction. Return logistics complexity constrains large-format commercial sales through this channel.
- Specialty Stores:Sur La Table, Williams Sonoma, and equivalent European retailers provide tactile evaluation and staff consultation for premium residential purchases.
- Supermarkets:Mass-market grocery chains stock entry-level 10-12 inch formats as impulse and gift purchases.
Wholesale Distributors retain commercial dominance; Online Retail is expanding most quickly as residential buyers prioritize convenience and price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial foodservice buyers in the United States, Germany, China, France, and India are driving divergent specification requirements as electrification mandates and Asian cuisine proliferation reshape regional demand patterns. Each market presents distinct regulatory compliance thresholds and procurement channel structures.
United States
Ghost kitchen operators in Dallas, Houston, and Los Angeles are consolidating wok procurement across multiple virtual Asian brands, amplifying order volumes beyond traditional restaurant replacement cycles. The FDA maintains indirect food additive regulations under 21 CFR that govern stainless steel composition claims for interstate commerce. Texas and California metropolitan hubs anchor this demand concentration as multi-unit chains negotiate direct manufacturer agreements.
Germany
EU Green Deal electrification deadlines are forcing commercial kitchen retrofits in Berlin, Munich, and Hamburg, accelerating replacement of carbon-steel woks with induction-compatible stainless formulations. ECHA REACH restrictions on nickel migration are tightening surface finish requirements and elevating third-party certification costs for imported cookware. Baden-Württemberg and Bavaria industrial zones are witnessing specification-driven procurement from hotel and institutional buyers.
China
Guangdong Province manufacturing clusters supply the majority of global stainless wok volume, though domestic foodservice modernization in Shanghai and Beijing is absorbing increasing share of premium induction-compatible output. SAMR enforces GB 4806.9 food-contact metal standards governing nickel and chromium migration limits. The Pearl River Delta concentration creates both scale economies and geopolitical risk exposure for international buyers.
France
Paris and Lyon commercial distributors are mandating batch-specific REACH compliance documentation as standard procurement terms, filtering non-certified Asian imports from specification tenders. The country's national hospitality regulator enforces strict food-contact material protocols in centralized kitchen operations. Île-de-France and Auvergne-Rhône-Alpes regions concentrate demand from high-volume Asian restaurant concepts and hotel banquet services.
India
FSSAI food-contact metal standards are creating compliance-driven upgrade cycles in Mumbai and Bangalore commercial kitchen infrastructure as organized foodservice expands. The central food safety authority's metallurgical testing protocols are displacing unregulated carbon-steel imports in institutional catering. Maharashtra and Karnataka states anchor this modernization wave through cloud kitchen proliferation and international hotel chain expansion.
Global Stainless Woks Market Competitive Environment
Player mix skews toward Asian contract manufacturers serving Western brand owners through OEM arrangements, with limited vertical integration among premium-tier European and North American marketers. Structure fragments across three strategic tiers: volume-driven Guangdong fabricators, brand-positioned Western distributors, and specialty induction-compatible designers. Competitive moves concentrate on certification documentation capabilities and direct-to-restaurant digital channel development rather than manufacturing scale expansion.
Among heritage-brand marketers, Zwilling J.A. Henckels and Meyer Corporation exemplify the European and North American premium positioning archetypes, while Sanho Kitchenware occupies a position within the induction-specialist tier. These three companies represent distinct competitive vectors: German engineering heritage anchoring specialty retail control, Asian manufacturing footprint enabling bulk restaurant supply economics, and magnetic-compatible design leadership capturing European commercial specification share. Each archetype faces pressure to expand compliance documentation services as multi-jurisdiction metallurgical standards diverge.
| Leading Market Players |
|---|
| Staub |
| Meyer Corporation |
| Zwilling J.A. Henckels |
| Cooker King |
| Sanho Kitchenware |
| Heritage Steel |
| Yosukata |
| Jiangmen Anotech |
| Anolon |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with LME nickel indexation lock in raw material access and price visibility for Guangdong-based manufacturers supplying European ghost kitchen operators facing EU Green Deal retrofit deadlines. These arrangements tether procurement costs to commodity benchmarks while insulating margin structures from spot market volatility in chromium-nickel alloy sourcing.
Pricing Analysis
Cost-plus contracts with LME nickel indexation dominate procurement between Guangdong fabricators and North American restaurant supply distributors. Price differentiation rests on REACH certification grade and volume scale, with batch-tested European commercial tenders commanding substantial premiums over undocumented Asian imports. Pricing pressure stems from nickel contract volatility compressing 304-grade manufacturer margins. Ghost kitchen operators demonstrate lowest price sensitivity due to centralized procurement authority, while Southeast Asian foodservice buyers remain highly price-sensitive and retain carbon-steel alternatives.
Supply Chain Analysis
China, India, and Vietnam anchor stainless wok fabrication, with Guangdong Province concentrating deep-drawing capacity and precision spinning equipment for commercial-grade output. Raw material dependencies draw from Indonesian nickel ore, South African chromium, and Australian iron ore feedstocks. Supply chain risk centers on single-source vulnerability from Pearl River Delta concentration exposed to geopolitical friction and logistics disruption. Distribution runs through wholesale restaurant supply houses in Dallas and Berlin, with direct-to-kitchen digital platforms eroding traditional dealer markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial kitchen electrification mandates are disrupting procurement patterns across three continents, creating structural repositioning opportunities as induction compatibility shifts from premium feature to compliance gate.
For Market Incumbents: Consolidate certification documentation capabilities to defend against REACH enforcement actions filtering non-compliant imports from French and German tenders. Deepen backward integration into 430-grade ferritic stainless melting capacity to offset nickel price volatility exposure. Prioritize direct digital channel development with ghost kitchen operators in Texas and California to bypass distributor margin extraction. For New Entrants and Emerging Players: REACH fast-track certification services for mid-scale Guangdong fabricators lacking ECHA documentation expertise represent immediate white-space opportunity. Target Indian cloud kitchen operators in Mumbai and Bangalore facing FSSAI compliance-driven upgrade cycles with induction-compatible 12-14 inch formats. Deploy specialized B2B platforms disintermediating traditional restaurant supply networks as primary go-to-market mechanism. For Investors and Strategic Acquirers: Induction-specialist designers with magnetic alloy formulation IP and established ECHA testing protocols represent priority acquisition archetypes for portfolio exposure to electrification tailwinds. Long-term viability hinges on regulatory compliance moats widening as GB 4806.9, REACH, and FDA 21 CFR standards diverge. Watch for nickel price sustained elevation above historical bands as inflection signal accelerating ferritic grade substitution and copper-cored tri-ply construction adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferritic Stainless Melting | Captive 430-grade supply insulates margin structures from LME nickel volatility. |
| REACH Certification Fast-Track Services | Documentation capabilities unlock German and French commercial equipment tenders. |
| Direct-to-Restaurant Digital Platform Launch | Bypasses wholesale distributor markups in Dallas and Toronto ghost kitchen procurement. |
| Hybrid Induction-Gas Base Design Introduction | Dual-purpose configurations address transitional European retrofit kitchen infrastructure. |
| Copper-Cored Tri-Ply Capacity Expansion | Hotel and institutional buyers in Switzerland and Austria specify thermal uniformity performance. |
Study Parameters
Desk research of customs trade records, SAMR GB standard filings, and ECHA enforcement action databases preceded structured interviews with Guangdong manufacturing executives, European commercial equipment distributors, and ghost kitchen procurement leads across the analysis window. Primary fieldwork with restaurant supply chain managers in Texas and California validated secondary volume estimates. Bottom-up fabrication capacity assessment triangulated against top-down foodservice equipment spending data.
Variance decomposition across product geometry, end-use environment, and channel structure informed analytical framework construction over the projection horizon. Segmentation dimensions modeled include base design configuration, induction compatibility tier, and commercial versus residential procurement authority. CAGRs derived from alloy price trajectory assumptions and electrification mandate implementation schedules. Nickel contract volatility bands and REACH enforcement intensity served as industry-specific forecast sensitivity inputs.
Underlying assumptions cover sustained EU Green Deal retrofit implementation, with deviation risk concentrated in nickel supply disruption and geopolitical friction affecting Guangdong export logistics. Forecasts reflect these documented conditions. Recalibration cycles align with material shifts in ECHA enforcement patterns and FSSAI standard adoption trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Toaster Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Smart Cooktop Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
Europe Household Appliances Market
Kitchen Appliances
Household Kitchen Appliances Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Russia Kitchen Appliances Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
Residential Cooking Grills Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Egg Boiler/Cooker Market