
 Residential Induction Cooktops Market | 2026-2036
Residential Induction Cooktops Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Induction Cooktops Market Analytics
Lease-to-own and retail financing programs are rewriting competitive access in residential induction cooktops. Robert Bosch GmbH leverages its captive finance partnerships to move premium built-in units through kitchen renovation channels. Whirlpool Corporation anchors North American volume through big-box retail installment plans that lower upfront barriers for mass-market buyers. Panasonic Corporation competes in Asia through appliance-rental subscriptions bundled with property management contracts.
Residential induction cooktops employ copper coil assemblies beneath ceramic glass surfaces to generate eddy currents that heat ferromagnetic cookware directly, achieving thermal efficiencies above 80 percent while eliminating open flames. Built-in configurations dominate margin pools in Western markets where kitchen renovations integrate these units as permanent fixtures, while portable variants sustain faster volume growth among renters and temporary household arrangements across urban Asia. Multi-zone feature sets differentiate premium offerings as homeowners seek flexible cooking surfaces that accommodate simultaneous vessel heating.
The EPA Energy Star program and EU Ecodesign requirements shape product efficiency benchmarks and testing protocols for induction cooktop manufacturers seeking market access. China's GB standards and SAMR certification enforce electromagnetic compatibility and safety thresholds that determine which models qualify for domestic sale. Stakeholders must monitor how building electrification mandates in multiple jurisdictions reclassify gas hookup restrictions and reshape new construction specifications.
Market Dynamics
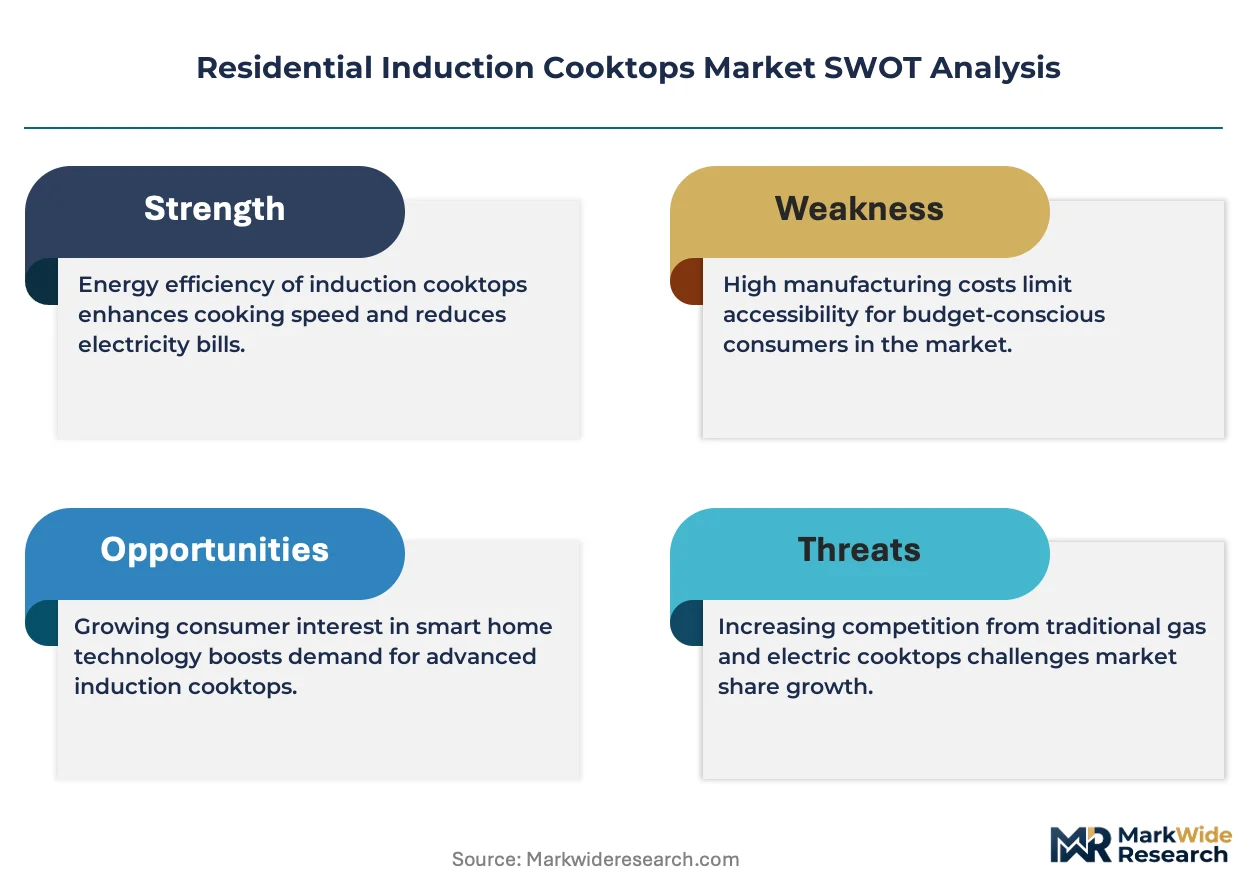
Building electrification mandates across multiple jurisdictions are systematically eliminating gas hookup infrastructure in new residential construction, forcing developers to specify induction cooktops as standard equipment and compressing the replacement cycle for existing gas installations.
Growth Catalysts
- EU Ecodesign requirements:Efficiency benchmarks for cooking appliances are accelerating the phase-out of conventional electric resistance cooktops across European member states, creating regulatory pull for induction replacements.
- Urban apartment densification:Compact kitchen footprints in high-rise residential towers across China and India favor flameless, space-efficient cooking technologies that integrate with ventilation-limited environments.
- Copper coil thermal efficiency:Direct electromagnetic heating achieves energy transfer rates above 80 percent, cutting household electricity consumption versus radiant electric alternatives and aligning with utility demand-side management programs.
Market Restraints
- Ferromagnetic cookware requirement:Induction cooktops function only with cast iron or magnetic stainless steel vessels, forcing households to replace existing aluminum and copper cookware and raising total cost of ownership.
- Ceramic glass supply concentration:Specialized crystallized glass surfaces for cooktop panels source primarily from German and Japanese specialty glass manufacturers, creating single-source vulnerability for assembly plants.
- Electromagnetic compatibility testing:China's GB standards and SAMR certification impose extended validation timelines for new models, delaying product launches and freezing inventory commitments.
Strategic Opportunities
- India's urban middle-class expansion:Metro cities including Mumbai, Bangalore, and Delhi are witnessing accelerated kitchen appliance upgrades as disposable incomes rise and gas cylinder logistics frustrate apartment dwellers.
- Multi-zone flexible surfaces:Sensor-driven cooking zones that automatically detect vessel size and position enable simultaneous preparation workflows, differentiating premium offerings from basic single-zone alternatives.
- Property management bundling:Appliance-rental subscriptions integrated with residential lease agreements create recurring revenue streams and lower upfront adoption barriers for transient urban renters.
Industry Challenges
- Electromagnetic field calibration expertise:Manufacturers face acute shortages of RF engineers capable of optimizing coil geometries for uniform heating patterns without hot spots or energy leakage.
- Retrofit electrical infrastructure:Existing residential circuits in older buildings often lack the 240V/40A capacity required for full-power induction units, requiring costly panel upgrades that stall replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Induction Cooktops Market |
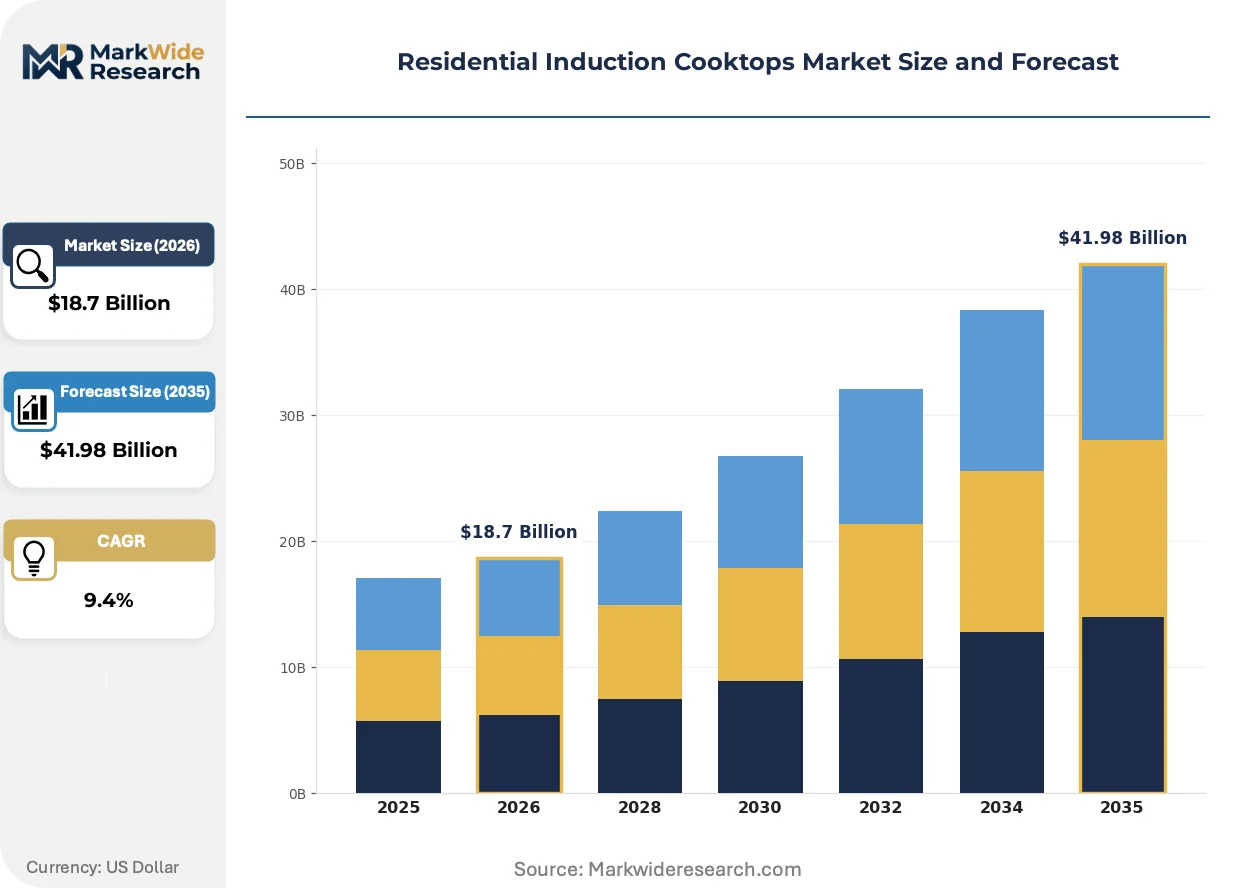
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in, Portable, Freestanding, Countertop Feature: Touch Control, Multi-Zone, Timer Function, Child Lock Size: Two Burner, Three Burner, Four Burner, Five Burner End User: Homeowners, Renters, Chefs, Kitchen Designers |
| Companies Covered | LG Electronics, Whirlpool Corporation, Panasonic Corporation, Robert Bosch GmbH, Electrolux Group, Koninklijke Philips N.V., Miele Group, SMEG S.p.A., Sub-Zero Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Induction Cooktops Market Evolving Landscape
Connected kitchen ecosystems are embedding induction cooktops into unified home automation platforms, with sensor networks and cloud-based recipe guidance transforming standalone appliances into interactive cooking assistants.
Bridge-function induction zones are digitizing how home chefs manage large-format cookware. These paired cooking surfaces recognize combined vessel footprints and distribute power dynamically across the unified area. Premium kitchen renovators in Germany and the Netherlands are specifying these configurations for paella pans and griddle plates. The technology is digitizing traditional cooktop segmentation by collapsing the distinction between standard and oversized zone specifications.
The EPA Energy Star program tightened test procedures for residential cooking equipment, requiring manufacturers to submit real-world energy consumption data rather than laboratory-only measurements. This regulatory shift elevates compliance costs for smaller appliance brands while rewarding established producers with established testing infrastructure. North American retailers are responding by prioritizing Energy Star-certified SKUs in promotional placement and inventory allocation.
Subscription-based ownership models are displacing traditional retail purchase patterns among urban renters with high mobility. Property technology platforms in Singapore and Seoul bundle induction cooktops with smart home packages, rolling hardware costs into monthly service fees. This shift is most pronounced in build-to-rent residential towers where tenant turnover averages under 24 months and capital expenditure flexibility outweighs long-term asset ownership preferences.
Residential Induction Cooktops Market Segmentation
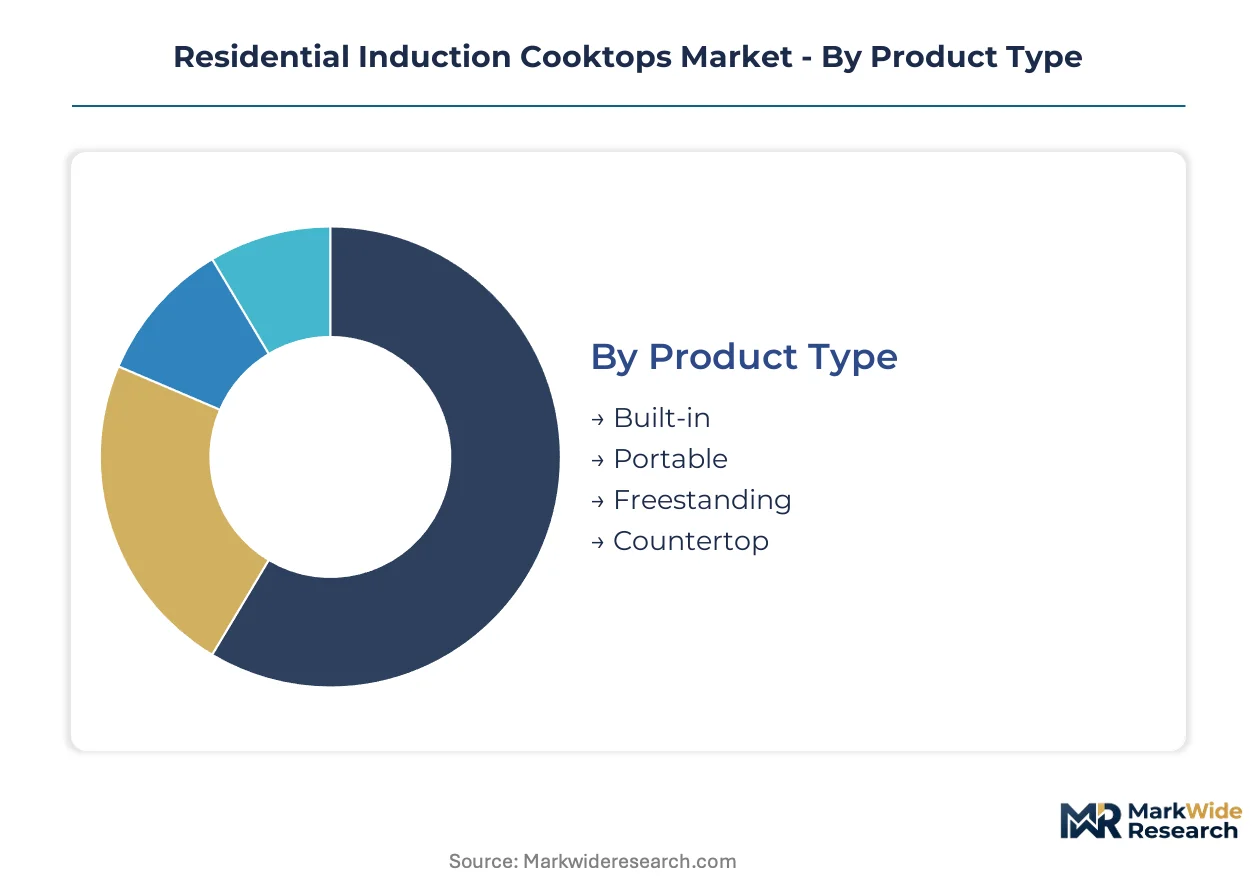
Segmentation in residential induction cooktops reveals how installation constraints, cooking workflows, and user expertise reshape hardware specifications across price tiers. Manufacturers calibrate coil configurations, control interfaces, and safety systems to match distinct household archetypes rather than pursuing one-size-fits-all platforms.
Product Type:
Cost tier separation in residential induction cooktops follows installation permanence and electrical infrastructure requirements rather than raw component quality alone.
- Built-in:These units integrate beneath stone or composite countertops with dedicated 240V/40A circuits, requiring professional electrical installation. Western kitchen renovation channels in Germany and the Netherlands concentrate demand as homeowners electrify gas legacy infrastructure under building codes.
- Portable:Lightweight single-zone units with standard 120V plugs target renters and temporary cooking arrangements. Urban apartment dwellers in Mumbai and Seoul drive volume through appliance-rental subscriptions bundled with property management contracts.
- Freestanding:Full-height units combining induction surfaces with convection ovens beneath, targeting kitchen replacements without cabinetry modifications.
- Countertop:Slim-profile multi-zone surfaces resting on existing counters, bridging portable convenience with fixed-cooktop capacity for semi-permanent household arrangements.
Built-in holds installed capacity. Portable is rotating up the share rankings.
Feature:
Application-specific cooking workflows determine which control and safety features command premium positioning versus baseline inclusion.
- Touch Control:Capacitive glass interfaces replace mechanical knobs, enabling flat-surface cleaning and programmable temperature curves. High-rise residential towers across China specify these for ventilation-limited compact kitchens where flame elimination is mandatory.
- Multi-Zone:Sensor arrays detect vessel size and position across bridgeable cooking areas, accommodating simultaneous large-format preparation. Premium kitchen designers in the Netherlands specify bridge-function configurations for paella pans and griddle plates.
- Timer Function:Integrated countdown automation with automatic shutoff, standard across mid-tier SKUs for unattended cooking safety.
- Child Lock:Control panel deactivation mechanisms, increasingly mandated by SAMR certification in China and specified by liability-conscious property managers in build-to-rent towers.
Touch control dominates baseline specifications. Multi-zone is gaining share fastest among renovation-driven replacement cycles.
Size:
Volume tiering in burner count reflects household composition and simultaneous cooking demand rather than kitchen square footage alone.
- Two Burner:Compact surfaces for studio apartments and secondary cooking stations, achieving the steepest expansion trajectory among urban renters with high mobility and limited counter space.
- Four Burner:Standard household configuration matching legacy gas cooktop footprints, dominating replacement cycles in suburban single-family homes undergoing electrification retrofits.
- Three Burner:Asymmetric layouts prioritizing one large power burner with two standard zones, targeting couples and small families with varied vessel sizes.
- Five Burner:Professional-grade surfaces with central flex zones, specified by kitchen designers for dedicated home chefs and entertaining-focused households.
Four burner anchors replacement volume. Two burner is climbing the fastest as rental housing stock densifies.
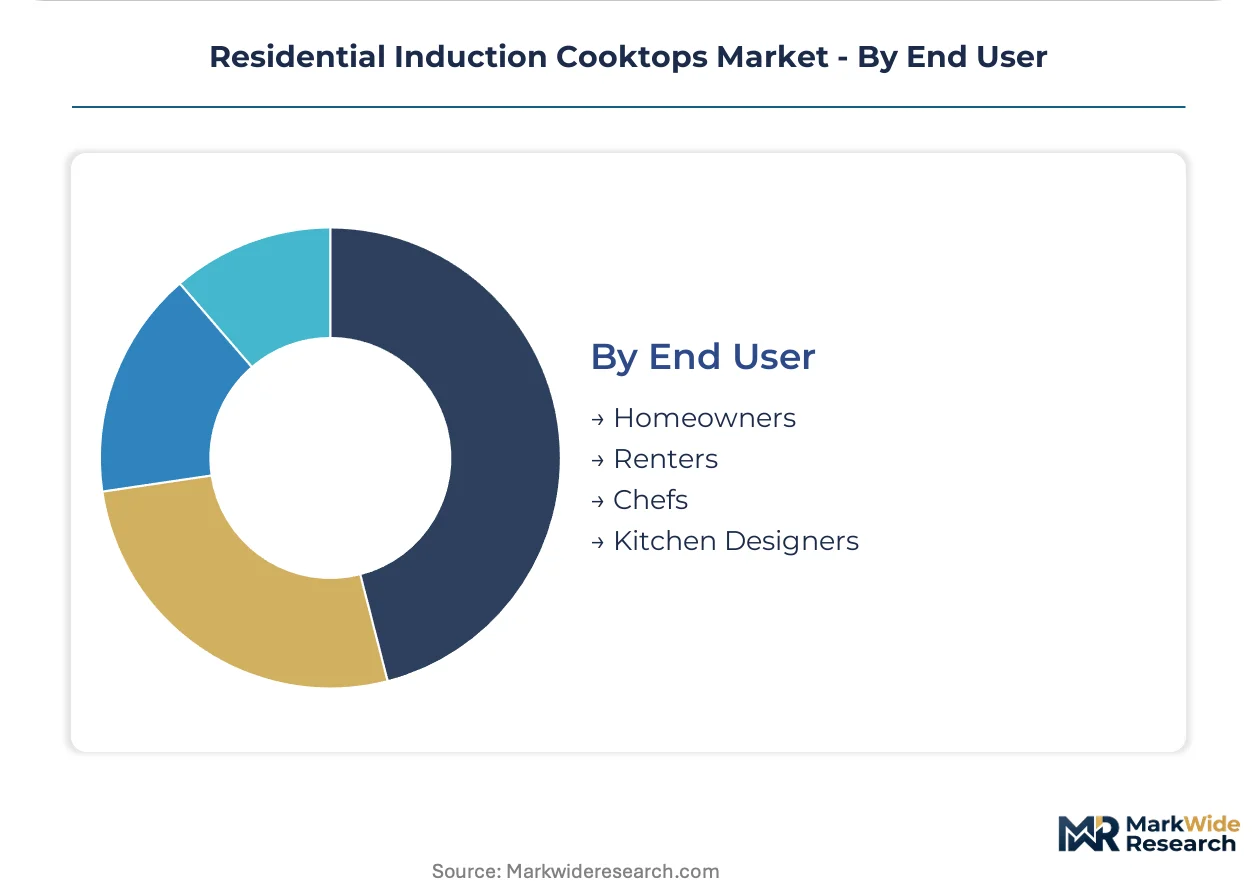
End User:
Customer type segmentation separates specification influence from purchase authorization, revealing divergent hardware priorities across decision-making chains.
- Homeowners:Permanent residents controlling renovation budgets and electrical infrastructure investments. German and Dutch households electrifying gas legacy systems prioritize built-in multi-zone units with bridge functionality.
- Renters:Transient tenants dependent on landlord-provided appliances or portable solutions. Singapore and Seoul property technology platforms bundle induction cooktops with smart home packages, rolling hardware into monthly service fees.
- Chefs:Cooking professionals influencing specifications for residential clients or home kitchen investments, prioritizing precise temperature control and rapid power modulation.
- Kitchen Designers:Specification architects controlling product placement in renovation and new construction projects, balancing aesthetic integration with electrical infrastructure constraints.
Homeowners control replacement expenditure. Renters are expanding most quickly through subscription ownership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Building electrification mandates and energy efficiency incentives are reshaping residential induction cooktop deployment across major economies, with regulatory frameworks in China, Germany, the United States, India, and Japan each creating distinct demand trajectories and compliance environments.
China
Urban densification in Shanghai and Shenzhen drives built-in induction specifications for high-rise residential towers with ventilation constraints. GB standards and SAMR certification enforce electromagnetic compatibility thresholds that filter market entry. Manufacturing clusters in Guangdong and Zhejiang provinces supply domestic demand while exporting portable units to Southeast Asian markets.
Germany
Kitchen renovation cycles in Berlin and Munich accelerate gas-to-induction conversions under the EU Ecodesign Directive's efficiency benchmarks. The Federal Environment Agency's building electrification incentives reduce retrofit electrical upgrade costs for homeowners. North Rhine-Westphalia's appliance distribution networks channel premium multi-zone units through specialist kitchen retailers.
United States
California's Title 24 building standards and New York City's gas hookup restrictions in new construction force induction specifications for residential developers. EPA Energy Star certification requirements tightened test procedures, elevating compliance burdens for smaller brands. Texas and Florida markets lag in adoption due to lower electricity costs and weaker electrification mandates.
India
Metro households in Mumbai and Bangalore replace gas cylinders with portable induction units as urban apartment construction accelerates. Bureau of Indian Standards safety certifications and state-level electricity subsidy programs reduce operating cost barriers. Gujarat and Tamil Nadu manufacturing zones produce entry-level single-zone cooktops for price-sensitive domestic consumers.
Japan
Tokyo and Osaka condominium developers specify compact two-burner induction surfaces for space-constrained kitchens. METI's Top Runner program sets efficiency standards that exceed international baselines, favoring domestic manufacturers with established testing infrastructure. Kyushu-based electronics clusters supply sensor and control module components to regional assembly plants.
Residential Induction Cooktops Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: diversified appliance conglomerates with captive distribution, specialized premium kitchen equipment fabricators, and regional contract manufacturers serving price-sensitive markets. Strategic archetypes include full-line home appliance providers leveraging retail financing partnerships, built-in kitchen specialists integrating with renovation channels, and portable unit producers targeting rental and subscription ownership models. Competitive moves concentrate on multi-zone technology licensing and backward integration into ceramic glass supply.
Within the diversified conglomerate tier, Robert Bosch GmbH and Whirlpool Corporation exemplify scale-driven positions, while Panasonic Corporation anchors the Asia-Pacific regional vector. Electrolux Group and Miele Group occupy specialist positions in European premium renovation channels. SMEG S.p.A. represents design-forward differentiation in Mediterranean markets. LG Electronics and Koninklijke Philips N.V. leverage consumer electronics distribution infrastructure for portable and countertop segments.
| Leading Market Players |
|---|
| LG Electronics |
| Whirlpool Corporation |
| Panasonic Corporation |
| Robert Bosch GmbH |
| Electrolux Group |
| Koninklijke Philips N.V. |
| Miele Group |
| SMEG S.p.A. |
| Sub-Zero Group, Inc. |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor carries crystallized glass panels and copper coil assemblies from Chinese manufacturing clusters to European assembly plants, with freight cost volatility amplifying margin compression for portable unit producers while reinforcing pricing power for built-in specialists with captive ceramic glass supply.
Pricing Analysis
Certification level under GB standards and SAMR electromagnetic compatibility thresholds creates the primary spread between premium built-in units and entry-level portable alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by installation permanence, with bridge-function multi-zone configurations commanding substantial premiums over basic single-zone models. Cost compression in the portable segment intensifies as Gujarat and Tamil Nadu contract manufacturers scale single-zone output for price-sensitive Indian metro households. Property managers in Singapore and Seoul build-to-rent towers exhibit lowest price sensitivity due to subscription bundling, while individual renters in Mumbai face acute upfront cost constraints.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for induction cooktop manufacturers with trans-Pacific distribution footprints. Production concentrates in Guangdong and Zhejiang provinces for coil assemblies, German and Japanese specialty glass manufacturers for crystallized ceramic surfaces, and Kyushu-based electronics clusters for sensor modules. Raw material dependencies center on high-purity copper for coil windings, rare-earth elements for magnetic field generation, and borosilicate glass substrates. Single-source vulnerability in ceramic glass supply creates inventory freeze risks during certification delays. Distribution runs through big-box retail installment plans in North America, specialist kitchen renovation channels in Germany and the Netherlands, and property technology platforms in urban Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among property technology platforms and build-to-rent operators, with subscription bundling consolidating procurement decisions away from individual households.
For Market Incumbents: Entrench multi-zone technology leadership through backward integration into ceramic glass supply and exclusive coil geometry IP, while defending against portable unit commoditization by locking renovation channels with captive finance partnerships. Prioritize RF engineering talent acquisition to address electromagnetic field calibration expertise shortages that constrain new model launches. For New Entrants and Emerging Players: Mid-market countertop units for semi-permanent urban renters in Southeast Asian metro cities represent the most penetrable entry point, with appliance-rental subscription infrastructure offering lower customer acquisition costs than traditional retail. Target India's Bureau of Indian Standards certification pathway as a regulatory beachhead before scaling to GB standards compliance. For Investors and Strategic Acquirers: EPA Energy Star test procedure tightening reshapes the acquisition landscape by elevating compliance infrastructure value and filtering smaller brands from North American retail placement. Long-term viability across the analysis window favors targets with established electromagnetic compatibility testing facilities and property management channel relationships. Monitor California Title 24 building standard expansion into additional states as the signal for electrification mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Bridge-Function Multi-Zone Development | Paella pan and griddle plate accommodation differentiates premium kitchen renovation specifications in Germany and the Netherlands. |
| Ceramic Glass Backward Integration | Captive crystallized glass supply insulates against Japanese and German specialty manufacturer single-source vulnerability. |
| Property Technology Platform Partnership | Subscription bundling with Singapore and Seoul build-to-rent operators locks recurring revenue streams and reduces customer churn. |
| RF Engineering Talent Acquisition | Electromagnetic field calibration expertise scarcity constrains new model launches under China's extended SAMR validation timelines. |
| Energy Star Certification Investment | EPA tightened test procedures reward established testing infrastructure with North American retail promotional placement priority. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with kitchen renovation contractors, property technology platform procurement heads, appliance retail category managers, RF engineering specialists, and regulatory compliance officers at SAMR and EPA. Secondary validation drew from customs trade data for copper coil and ceramic glass shipments, Bureau of Indian Standards certification registries, Energy Star product listings, and SEC 10-K filings from diversified appliance conglomerates. Bottom-up unit shipment estimates by product type and feature tier were triangulated against top-down market value reconstructions.
Calibration anchored volume and value outputs to observed installation rates in electrification-mandate jurisdictions, with segmentation dimensions spanning installation type, burner count, control interface, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical replacement cycle compression and building code adoption patterns. Copper price volatility and electromagnetic compatibility testing timeline distributions served as industry-specific forecast sensitivity inputs across the projection horizon.
Stress conditions across raw material cost spikes, certification timeline extensions, and electrification mandate rollout delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
Global Baking Tools Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Warming Drawer Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
Ceramic Coated Cookware Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Colombia Kitchen Appliances Market
Kitchen Appliances
India Electric Vegetable Choppers Market
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
Induction Stove Market