
 Commercial Induction Cooktops Market | 2026-2036
Commercial Induction Cooktops Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Induction Cooktops Market Analysis
Skilled commercial kitchen technician shortages are redrawing equipment procurement priorities across foodservice operations. The Vollrath Co. LLC leverages its domestic manufacturing footprint to sustain rapid fulfillment timelines for institutional buyers. Hatco Corp. competes through specialized heating-element engineering that extends equipment lifespan in high-throughput environments. Ali Group S.r.l. anchors its position via extensive distribution control across European commercial kitchen networks.
Commercial induction cooktops are electric cooking appliances that generate heat through electromagnetic induction between copper coils beneath a glass-ceramic surface and ferromagnetic cookware, achieving thermal efficiencies exceeding 90 percent while eliminating open flames in professional kitchens. Built-in units command the largest share of current revenue as permanent kitchen infrastructure investments, while portable configurations represent the fastest-expanding category among food truck operators and temporary catering setups seeking flexible deployment without gas line dependencies. Touch control interfaces dominate premium specifications, though programmable systems are gaining traction in chain restaurant settings where recipe standardization reduces training burdens.
The U.S. Department of Energy enforces minimum efficiency standards through its Commercial Kitchen Equipment program, while the EPA's ENERGY STAR certification creates preferential procurement pathways for qualifying models in federal and institutional contracts. European operators must navigate Ecodesign requirements and CE marking protocols that mandate electromagnetic compatibility testing for high-wattage induction systems. Stakeholders should monitor municipal building code amendments in major metropolitan areas, as jurisdictions compete to advance electrification mandates that directly determine replacement-cycle timing for existing gas infrastructure.
Market Dynamics
Electrification mandates from municipal building authorities are accelerating the replacement of gas-fired cooking infrastructure across commercial foodservice operations, compressing decision timelines for kitchen operators and redrawing procurement priorities toward high-efficiency induction systems.
Growth Catalysts
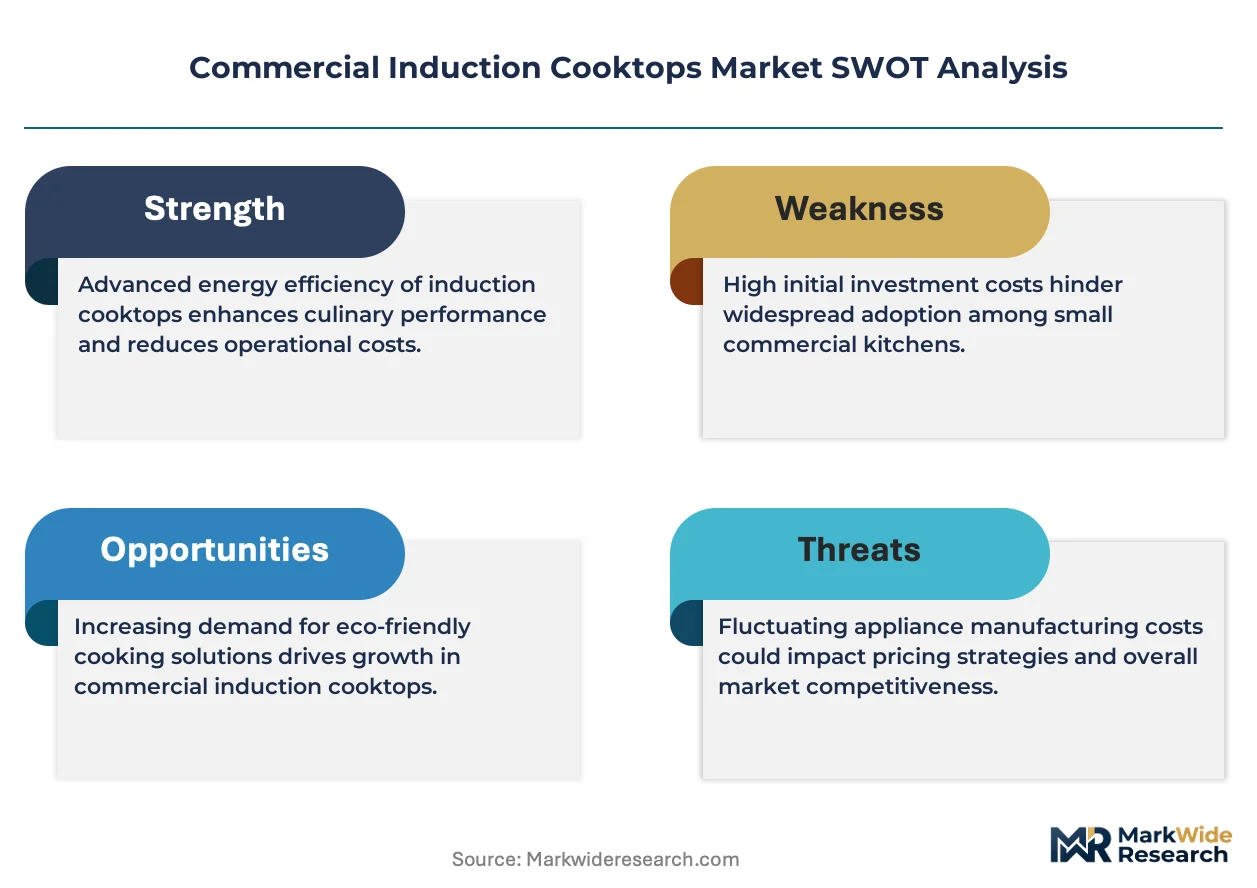
- Natural gas restrictions:Tier-one Chinese cities including Shanghai and Beijing have imposed outright bans on new gas connections for commercial buildings, forcing developers to specify electric cooking infrastructure from project inception.
- ENERGY STAR procurement pathways:The EPA's certification program creates preferential contracting access for qualifying induction models in federal cafeterias, military installations, and institutional foodservice operations across the United States.
- Food truck electrification:Mobile catering operators are abandoning propane tank dependencies in favor of battery-solar-induction configurations that eliminate ventilation requirements and expand permitted operating locations.
Market Restraints
- Copper coil supply concentration:High-purity copper winding production for induction generators clusters in Chinese smelting corridors, exposing equipment manufacturers to raw material availability shocks and tariff volatility.
- Ferromagnetic cookware compatibility:Aluminum and copper-bottomed pans common in legacy commercial kitchens fail to generate inductive heat, forcing simultaneous capital outlays for compatible vessel replacement.
- Electrical infrastructure retrofit costs:Older buildings require three-phase power upgrades and dedicated circuit installations to support high-wattage induction arrays, extending payback periods for conversion projects.
Strategic Opportunities
- Ghost kitchen standardization:Delivery-only food preparation facilities in dense urban cores favor modular induction configurations that permit rapid kitchen reconfiguration between rotating virtual restaurant brands.
- EU Ecodesign compliance services:Electromagnetic compatibility testing and CE marking consultancy for high-wattage induction systems represents an adjacent revenue stream for certification laboratories serving equipment importers.
- Programmable recipe integration:Chain restaurant operators are specifying induction cooktops with embedded temperature curve programming that enforces cooking consistency across locations while reducing line cook training duration.
Industry Challenges
- Commercial kitchen technician scarcity:Electromagnetic field diagnostics and glass-ceramic surface replacement require specialized training that vocational programs have not scaled to match equipment deployment rates.
- Legacy ventilation system incompatibility:Existing hood and makeup air configurations designed for gas combustion loads must be recalibrated for induction's reduced heat radiation profiles, complicating retrofit project scopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Induction Cooktops Market |
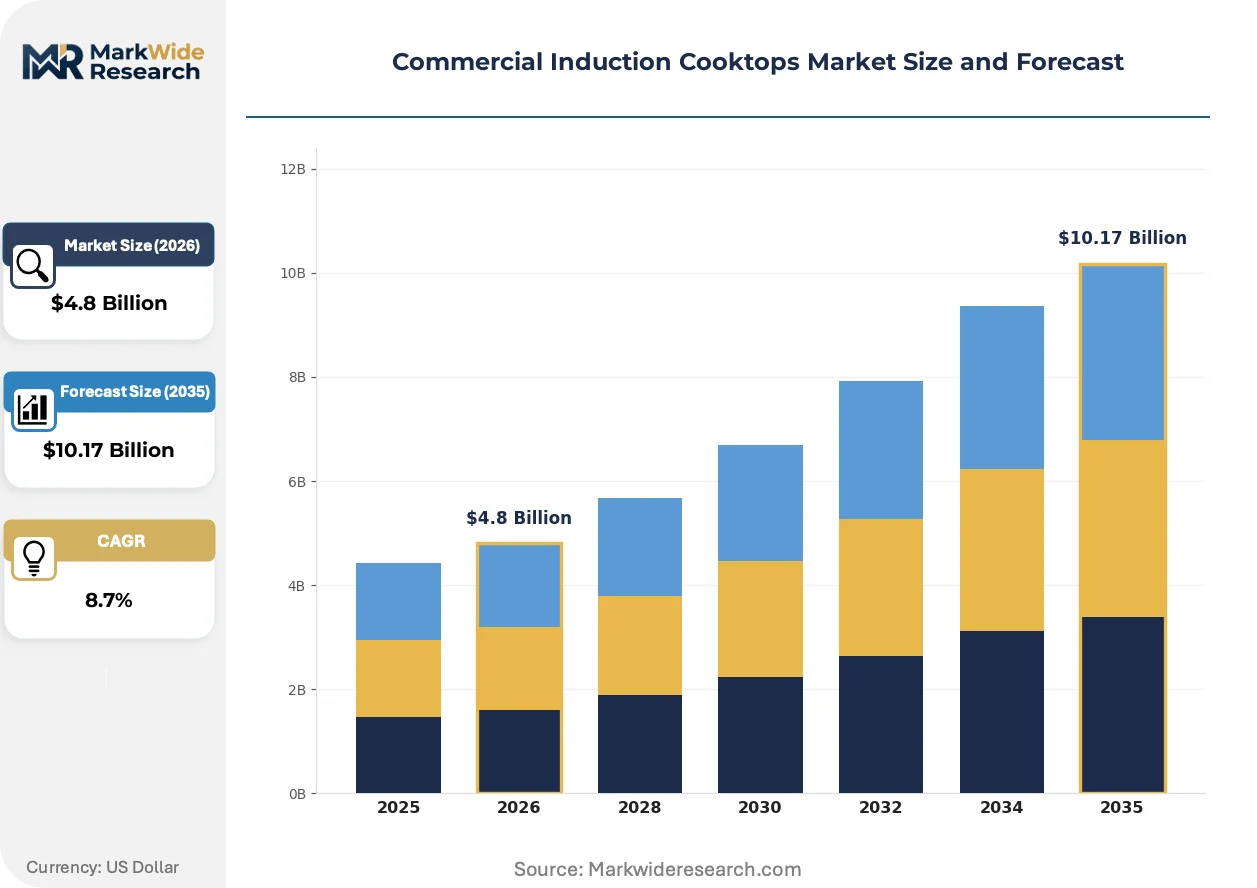
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-in, Portable, Modular End User: Restaurants, Catering Services, Food Trucks, Hotels Size: Single Burner, Double Burner, Three Burner, Multi-Burner Control Type: Touch Control, Knob Control, Remote Control, Programmable |
| Companies Covered | Dipo Induction, Hatco Corp., Admiral Craft Equipment Corp., The Vollrath Co. LLC, True Induction, Ali Group S.r.l., Equipex LLC, Garland group, Buffalo Cookware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Induction Cooktops Market Emerging Trajectories
Induction cooking technology is fragmenting into specialized configurations that address distinct operational constraints across stationary and mobile foodservice environments, with control interface design emerging as a primary competitive differentiator.
Modular coil architectures are decomposing the traditional monolithic cooktop into independently controllable heating zones that food truck operators reconfigure based on daily menu requirements. Caterers deploying temporary kitchen setups prioritize these swappable elements over fixed installations. The flexibility premium commands higher per-watt pricing while compressing equipment replacement cycles as operators refresh configurations rather than entire units.
REACH restrictions on per- and polyfluoroalkyl substances are pressuring manufacturers to reformulate the glass-ceramic surfaces that form induction cooktop interfaces. European equipment suppliers face accelerated compliance timelines under ECHA enforcement schedules. Premium product lines are migrating toward ceramic-glass composites that eliminate fluoropolymer coatings while maintaining thermal shock resistance.
Chain restaurant procurement departments are consolidating vendor relationships around equipment suppliers offering unified fleet management platforms. Multi-location operators demand remote monitoring capabilities that track energy consumption and flag maintenance needs across dispersed kitchens. This specification pattern concentrates contract awards among integrated solution providers and marginalizes standalone equipment manufacturers lacking software development capabilities.
Commercial Induction Cooktops Market Segmentation
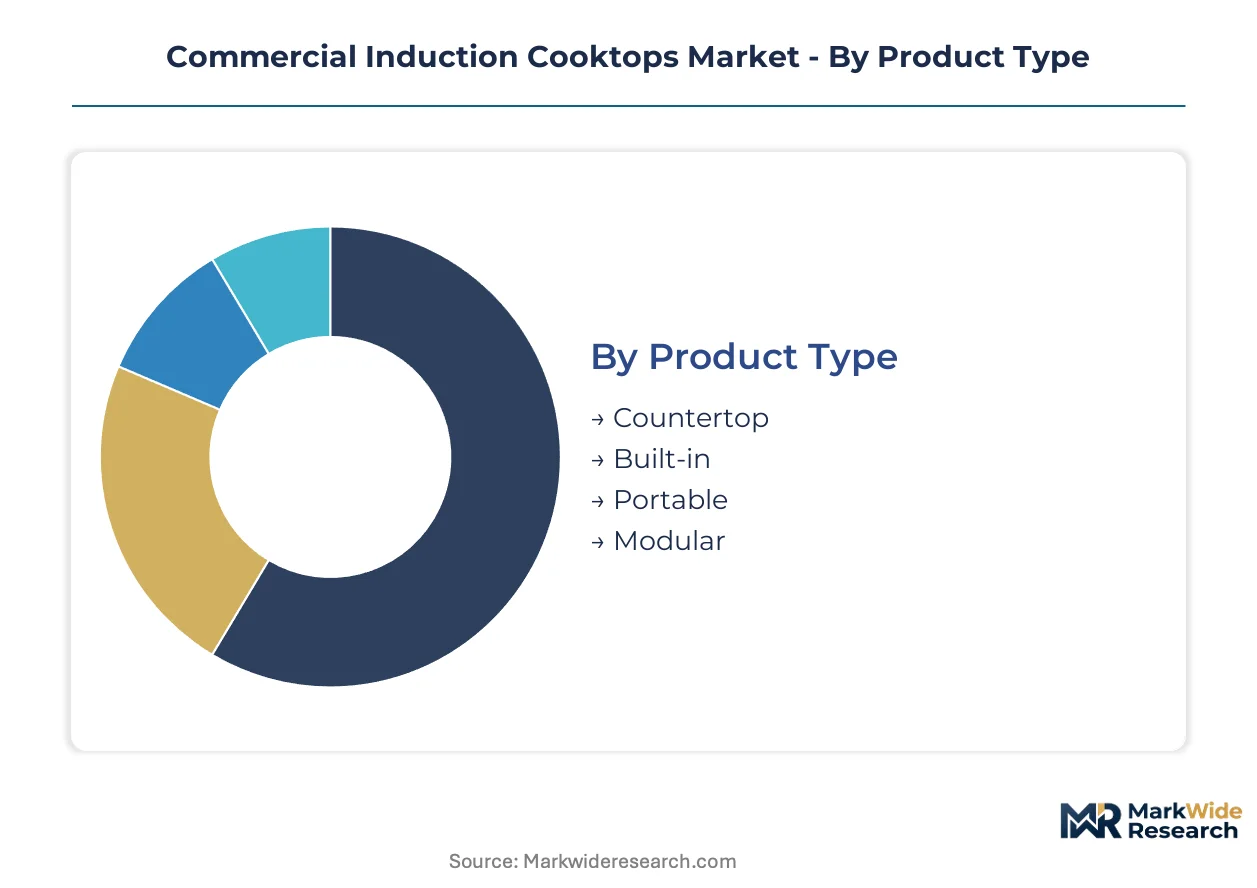
Segmentation reveals how electrification pressures fragment across equipment configurations and operational contexts. Procurement priorities diverge sharply between permanent infrastructure investments and flexible deployment options.
Product Type:
Portable configurations face the most intense substitution pressure from gas alternatives, while built-in units benefit from permanent infrastructure lock-in.
- Built-in:These units integrate permanently into commercial kitchen infrastructure with fixed electrical connections and ventilation integration. Demand concentrates in new construction projects across Shanghai and Beijing where municipal gas bans force electric specification from architectural planning stages.
- Portable:Self-contained units with plug-and-deploy flexibility serve temporary operations and retrofit scenarios. Food truck operators in California and Texas are abandoning propane configurations for battery-solar-induction setups that eliminate ventilation requirements and expand permitted operating locations.
- Countertop:Freestanding units designed for existing kitchen surfaces without permanent installation. Institutional cafeterias prioritize these for rapid kitchen reconfiguration between service periods.
- Modular:Swappable coil architectures permit independent zone reconfiguration based on daily menu requirements. Ghost kitchen operators favor these for rapid layout changes between rotating virtual restaurant brands.
Built-in units anchor the volume base while portable configurations gain share at the steepest rate.
End User:
Cost tier differentiation separates high-volume chain operators from independent establishments with constrained capital cycles.
- Restaurants:Full-service and quick-service chains dominate procurement volume with standardized equipment specifications across location networks. ENERGY STAR certification creates preferential federal contracting access for qualifying models in institutional foodservice operations.
- Food Trucks:Mobile catering operators prioritize compact, high-wattage units compatible with battery and solar generation systems. Municipal electrification mandates in Los Angeles and Austin are accelerating propane-to-induction conversions.
- Catering Services:Temporary event operators demand rapid-deployment equipment without gas line dependencies. Rental fleet operators are consolidating around standardized portable configurations.
- Hotels:Full-service properties specify built-in arrays for banquet and restaurant operations. European Ecodesign compliance requirements are reshaping procurement specifications for imported equipment.
Restaurant chains command the largest procurement volumes while food truck operators expand their segment presence most aggressively.
Size:
Application context determines burner count requirements across stationary versus mobile deployment scenarios.
- Multi-Burner:Arrays of four or more cooking zones serve high-throughput central kitchens and institutional cafeterias. Three-phase power requirements limit deployment to new construction or extensively retrofitted facilities.
- Double Burner:Two-zone configurations balance output capacity with electrical infrastructure demands. Independent restaurants favor these for flexible station assignments during peak service periods.
- Single Burner:Compact units serve specialized applications and supplementary cooking stations. Food trucks deploy these for targeted high-heat tasks within constrained electrical budgets.
- Three Burner:Mid-range arrays suit medium-volume operations with moderate space constraints. Ghost kitchens utilize these for standardized virtual brand configurations.
Multi-burner systems dominate permanent installations while single-burner units lead mobile application growth.
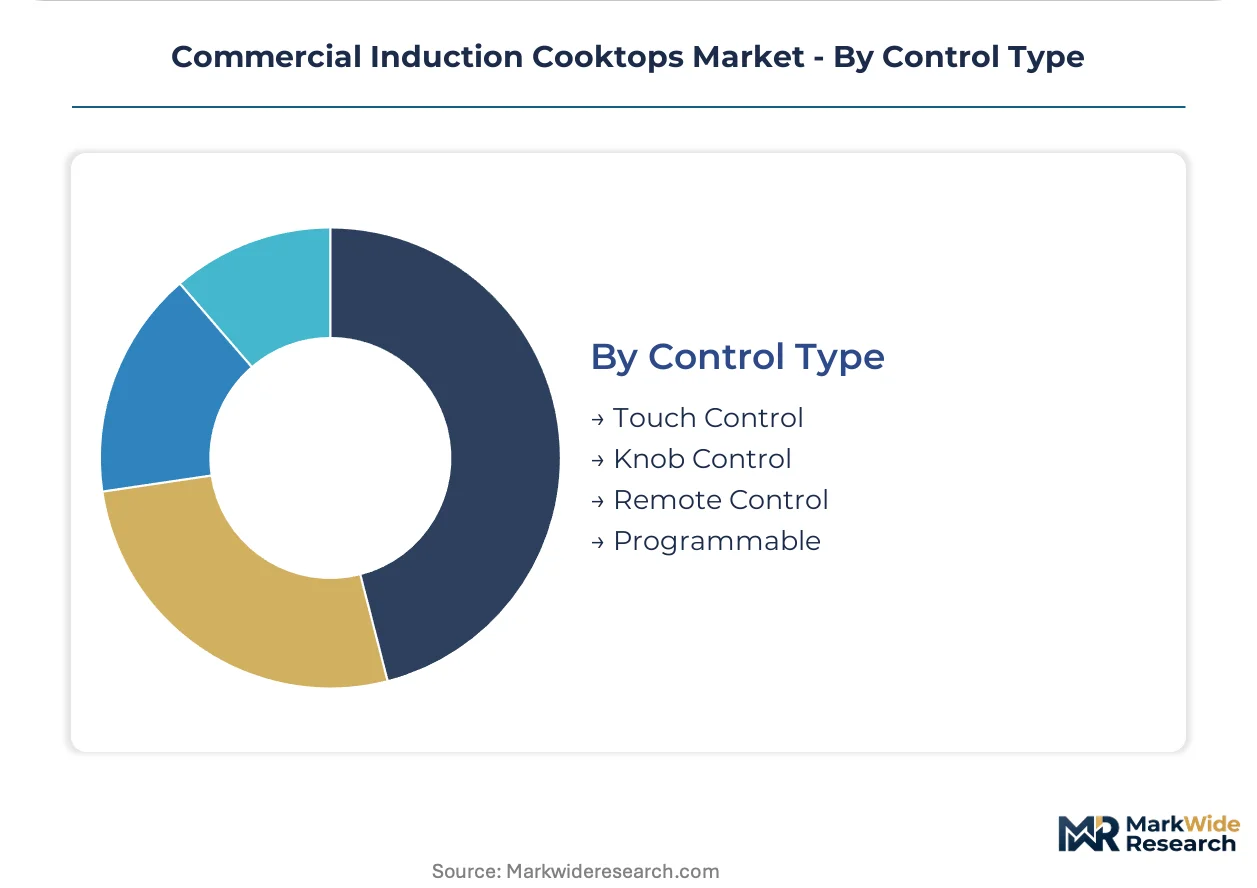
Control Type:
Technology maturity separates established interface designs from emerging programmable systems with embedded recipe management.
- Touch Control:Glass-ceramic interface panels dominate premium product specifications with intuitive temperature adjustment. REACH restrictions on fluoropolymer coatings are pressuring European manufacturers toward reformulated surface compositions.
- Programmable:Embedded temperature curve programming enforces cooking consistency across chain restaurant locations. McDonald's and Chipotle procurement departments are specifying these systems to reduce line cook training duration.
- Knob Control:Physical dial interfaces persist in cost-sensitive segments and legacy operator preferences. Institutional buyers with standardized training protocols favor these for operational familiarity.
- Remote Control:Network-connected systems enable fleet management platforms across dispersed kitchen locations. Integrated solution providers are consolidating contract awards through unified monitoring capabilities.
Touch control retains the largest installed base while programmable systems climb the fastest among chain restaurant specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA commercial kitchen equipment standards and municipal electrification mandates across multiple jurisdictions are compressing replacement timelines for gas-fired infrastructure. Equipment procurement is concentrating in jurisdictions with binding natural gas restrictions.
United States
Quick-service restaurant chains are expanding kitchen electrification programs under ENERGY STAR procurement pathways. The EPA certification creates preferential contracting access for qualifying induction models in federal cafeterias and military installations. Los Angeles and Austin municipal codes are accelerating propane-to-induction conversions among food truck operators.
China
Shanghai and Beijing have imposed outright bans on new gas connections for commercial buildings, forcing electric cooking infrastructure from project inception. MIIT efficiency standards and dual carbon goals are reshaping equipment specifications for domestic manufacturers. Yangtze River Delta kitchen equipment clusters are scaling high-purity copper coil production for induction generators.
Germany
Ecodesign requirements and CE marking protocols mandate electromagnetic compatibility testing for high-wattage induction systems imported from non-EU sources. The EU Green Deal is accelerating building electrification mandates across commercial foodservice operations. Bavarian commercial kitchen distributors are consolidating procurement relationships around integrated solution providers.
Japan
METI energy efficiency standards are tightening minimum performance requirements for commercial cooking equipment in institutional foodservice contracts. JIS certification protocols create procurement barriers for non-compliant imports. Kanto region quick-service chains are specifying programmable induction systems with embedded temperature curve management.
United Kingdom
Building regulation amendments in Greater London are advancing electrification mandates that determine replacement-cycle timing for existing gas infrastructure. The country's national energy efficiency programs are creating preferential financing for commercial kitchen retrofits. Midlands-based foodservice equipment distributors are expanding inventory allocations for portable induction configurations.
Commercial Induction Cooktops Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with domestic manufacturing footprint and distribution control serving as primary differentiation vectors. The upper tier commands federal and institutional procurement contracts through ENERGY STAR certification and rapid fulfillment capabilities. Specialist competitors compete through heating-element engineering and modular coil architectures. Consolidation pressure is intensifying as chain restaurant procurement departments demand unified fleet management platforms with remote monitoring capabilities.
Within the integrated leader tier, The Vollrath Co. LLC and Ali Group S.r.l. exemplify divergent geographic anchoring strategies. Vollrath occupies a position tied to domestic manufacturing footprint advantages for institutional buyers, while Ali Group represents European distribution control across commercial kitchen networks. Hatco Corp. sits within the specialist tier, with its company name suggesting heating-equipment specialization that aligns with extended equipment lifespan positioning in high-throughput environments.
| Leading Market Players |
|---|
| Dipo Induction |
| Hatco Corp. |
| Admiral Craft Equipment Corp. |
| The Vollrath Co. LLC |
| True Induction |
| Ali Group S.r.l. |
| Equipex LLC |
| Garland group |
| Buffalo Cookware |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Yangtze River Delta copper coil producers and induction generator manufacturers lock in both raw material access and price visibility for equipment fabricators serving institutional buyers. These contract structures insulate procurement departments from spot volatility in high-purity copper winding markets while committing volume to Chinese smelting corridors.
Pricing Analysis
Domestic manufacturing in the United States commands a 15-25% premium over imported equivalents from Chinese production hubs. Pricing stratifies across ENERGY STAR-certified premium tiers, standard commercial specifications, and economy-grade portable configurations. Cost compression in the economy tier is intensifying as Yangtze River Delta producers scale coil output for battery-solar-induction food truck bundles. Independent restaurants exhibit the highest price sensitivity, while federal procurement officers prioritize certification compliance over unit economics.
Supply Chain Analysis
China anchors high-purity copper winding production for induction generators, with secondary coil fabrication concentrated in South Korea and Japan. Equipment assembly draws from Chinese glass-ceramic substrates, German power electronics, and Taiwanese control interface components. Single-source vulnerability in Yangtze River Delta smelting corridors exposes manufacturers to tariff volatility and export license restrictions. Distribution runs through European commercial kitchen networks controlled by integrated solution providers and North American institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial induction cooktops are approaching a platform-economics inflection as chain restaurant procurement departments consolidate around unified fleet management systems with remote monitoring capabilities. Interoperability between equipment hardware and kitchen management software is becoming the primary contract award criterion.
For Market Incumbents: Compound defensive positioning through backward integration into copper coil production and captive supply of glass-ceramic substrates. The Vollrath Co. LLC's domestic manufacturing footprint provides a template for rapid fulfillment timelines that institutional buyers demand. Certification investment in ENERGY STAR and Ecodesign compliance creates procurement barriers against emerging Asian competitors lacking testing infrastructure. For New Entrants and Emerging Players: Lead with modular coil architectures targeting ghost kitchen operators in Los Angeles and Austin where municipal electrification mandates accelerate equipment refresh cycles. Food truck battery-solar-induction configurations represent the most penetrable white-space segment, with propane-to-electric conversion subsidies reducing customer acquisition costs. A rental-fleet partnership model with catering services bypasses upfront capital barriers that constrain independent restaurant adoption. For Investors and Strategic Acquirers: Capital is best deployed toward integrated solution providers with software development capabilities and established European distribution control. Long-term viability over the next decade hinges on consolidation of fragmented aftermarket service networks. The signal to watch is municipal building code amendments in tier-one Chinese cities and California municipalities, as binding natural gas restrictions determine replacement-cycle timing and contract award velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Coil Production | Yangtze River Delta smelting partnerships insulate margins from raw material volatility and tariff exposure. |
| Programmable Recipe Platform Development | McDonald's and Chipotle procurement specifications favor embedded temperature curve management for training reduction. |
| Ghost Kitchen Modular Configuration | Delivery-only facilities in Los Angeles and Austin demand rapid kitchen reconfiguration between virtual restaurant brands. |
| EU Ecodesign Compliance Services | Electromagnetic compatibility testing creates adjacent revenue for certification laboratories serving equipment importers. |
| Remote Fleet Management Capability | Unified monitoring platforms consolidate contract awards from multi-location chain restaurant operators. |
Methodological Framework
A standing panel of commercial kitchen equipment procurement directors, foodservice operations managers, copper coil supply specialists, and Ecodesign certification consultants provided ongoing calibration across the study period. Primary interviews with these stakeholders were cross-referenced against secondary validation from EPA ENERGY STAR certification databases, MIIT efficiency standard filings, EU Ecodesign regulatory texts, and commercial kitchen equipment trade customs records. Bottom-up unit economics from food truck operator surveys and top-down market sizing from institutional procurement databases were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product configuration, end-user archetype, burner count, and control interface technology. CAGRs were derived from regression analysis of historical replacement cycles correlated with municipal electrification mandate adoption curves. Forecast inputs incorporated copper price volatility indices and three-phase electrical infrastructure retrofit penetration rates in older commercial building stock.
The analysis sits within stated boundaries; outcomes outside sustained municipal electrification momentum or copper supply disruption scenarios would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and food truck battery technology cost curves. Specific risk factors that could revise projections include REACH restriction acceleration on glass-ceramic coatings and skilled technician training program scaling failures. Recalibration cycles align with material shifts in municipal building code amendments and federal procurement pathway updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
Residential Hobs Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
On-The-Go Pots Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
Ceramic Coated Cookware Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
Outdoor Kitchen Appliances Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Self-Stirring Mug Market