
 US Household Coffee Machine Market | 2026-2036
US Household Coffee Machine Market Size, Share, and Industry Trends Forecast 2026-2036
US Household Coffee Machine Market Insights
Multi-source component procurement is recalibrating how manufacturers balance cost against supply resilience. Keurig Dr Pepper Inc. leverages its captive pod ecosystem to sustain recurring revenue streams beyond hardware sales. De'Longhi Group anchors its position through Italian-designed espresso engineering that commands premium positioning. Breville Group Limited differentiates via integrated grinder-brewer systems that reduce countertop footprint for space-constrained kitchens.
US household coffee machines encompass electrically powered brewing appliances designed for residential use, typically operating at 120V with wattage ranging from 600W for compact drip units to 1,500W for thermoblock espresso systems, extracting flavor through pressurized hot water contact with ground coffee or sealed pods. Their primary purpose is delivering café-equivalent beverage quality without commercial equipment scale or operational complexity. Single serve machines lead volume shipments due to pod subscription attach rates, while espresso machines capture disproportionate margin pools through accessory and consumable ecosystems. Pump technology dominates premium tiers for pressure consistency, whereas thermal systems retain share in budget drip categories where warming plate energy costs drive replacement cycles.
FDA food-contact material regulations govern plastic and seal components in brewing chambers, while NHTSA appliance safety standards address electrical hazard prevention in countertop devices. California's Title 20 energy efficiency mandates are pushing manufacturers toward auto-shutoff and insulated carafe designs that reduce standby power draw. Stakeholders must monitor how state-level efficiency preemption debates reshape national product platform standardization decisions.
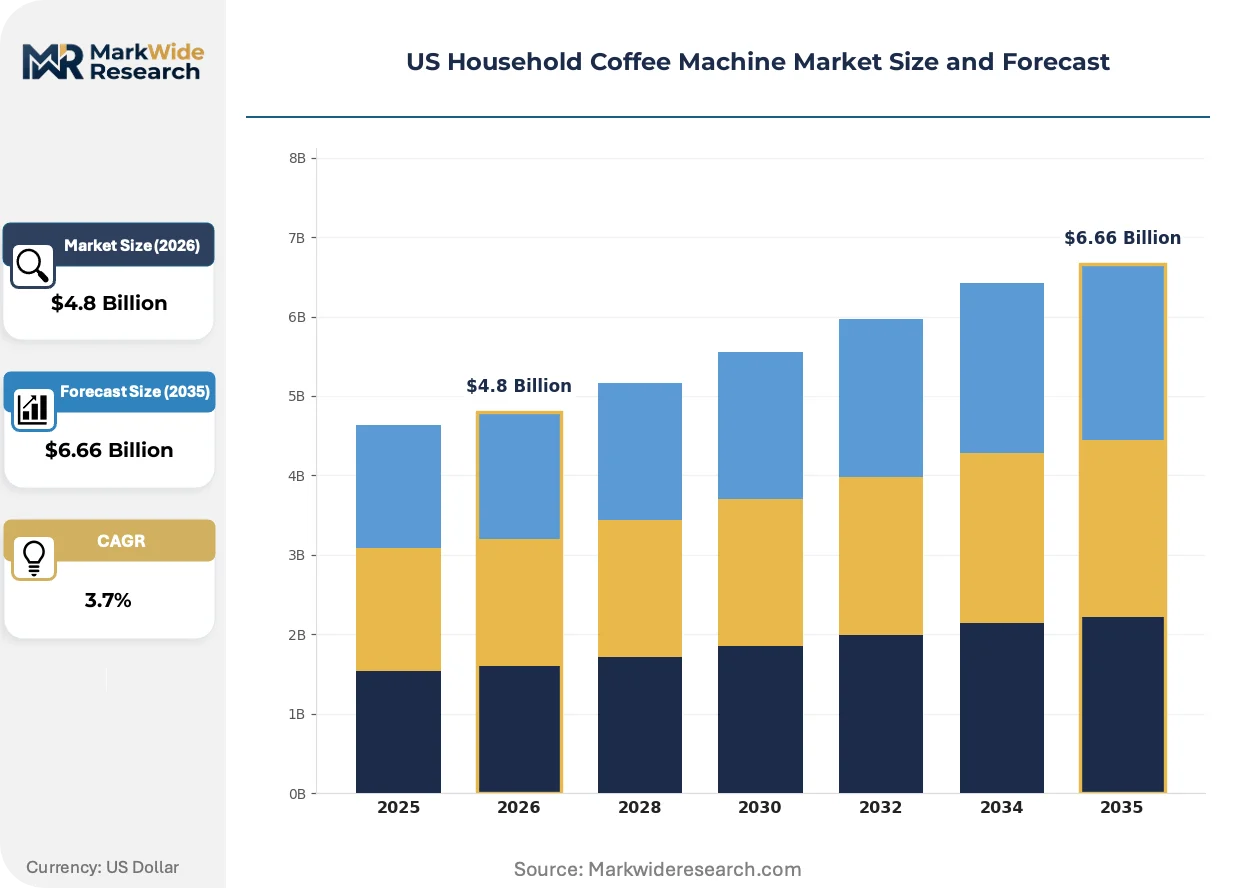
Market Dynamics
Single-serve pod ecosystem lock-in is restructuring profit pools away from hardware margins toward recurring consumable revenue, while California's Title 20 energy efficiency mandates force platform redesigns that cascade through national product lineups.
Growth Catalysts
- Suburban household formation:Sun Belt states including Florida, Texas, and Arizona are outpacing national averages in new household creation, expanding the addressable base for countertop appliances.
- Title 20 compliance innovation:California's energy efficiency regulations are accelerating auto-shutoff and insulated carafe adoption that reduces standby power draw and extends replacement cycles.
- Pod subscription attach rates:Sealed single-serve systems are capturing repeat purchase loyalty through proprietary consumable ecosystems that generate predictable revenue streams.
Market Restraints
- Aluminum and plastic resin input volatility:Pod manufacturing depends on commodity packaging materials subject to energy-cost-driven price swings that compress hardware margins.
- Thermoblock pump supply concentration:Italian and Chinese component suppliers dominate precision pressure systems, creating geographic concentration risk for domestic assemblers.
- FDA food-contact compliance friction:Plastic brewing chamber materials face extended testing timelines for heat-degradation certification that delays platform launches.
Strategic Opportunities
- Underpenetrated Mountain West households:Colorado and Utah urban corridors show lower single-serve penetration relative to income-adjusted benchmarks, presenting whitespace for targeted distribution.
- Grinder-brewer convergence:Integrated bean-to-cup systems are absorbing demand from separate appliance owners seeking countertop consolidation in space-constrained kitchens.
- IRA residential energy incentives:Federal efficiency rebate programs are creating subsidy tailwinds for smart-enabled machines with verified standby power reduction.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for connected brewing schedules and maintenance alerts competes with broader appliance IoT talent pools.
- Multi-state regulatory fragmentation:Diverging efficiency preemption debates between California and federal standards force costly dual-SKU platform maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Household Coffee Machine Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Coffee Makers, Espresso Machines, Single Serve Machines, French Presses End User: Individuals, Families, Offices, Cafés Technology: Thermal, Steam, Pump, Manual Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Keurig Dr Pepper Inc., Nestlé Nespresso SA, Hamilton Beach Brands Holding Company, De'Longhi Group, Breville Group Limited, SharkNinja Operating LLC, BUNN-O-Matic Corporation, Koninklijke Philips N.V., Newell Brands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Household Coffee Machine Market Trends and Innovations
Active reshaping in this market centers on convergence between convenience automation and energy compliance, with hardware design decisions increasingly dictated by consumable ecosystem economics and state-level regulatory preemption.
Thermoblock heating technology is absorbing development investment from traditional boiler systems due to faster heat-up cycles and reduced energy waste. Suburban families seeking morning routine compression are adopting these systems at accelerating rates. This shift is absorbing margin from lower-wattage drip categories that lack pressure-extraction capability.
California's Title 20 appliance efficiency standards are mandating auto-shutoff maximums and standby power ceilings that exceed federal baseline requirements. Manufacturers are consolidating platform architectures to meet the strictest state rule rather than maintain separate SKUs. This regulatory divergence is compressing time-to-market for new thermal system introductions.
Subscription-based pod replenishment is displacing retail basket purchasing among convenience-seeking households. Direct-to-consumer channels are capturing recurring revenue relationships that grocery and big-box intermediaries previously controlled. This channel migration is most visible in Sun Belt metro corridors with higher digital commerce penetration rates.
US Household Coffee Machine Market Segmentation
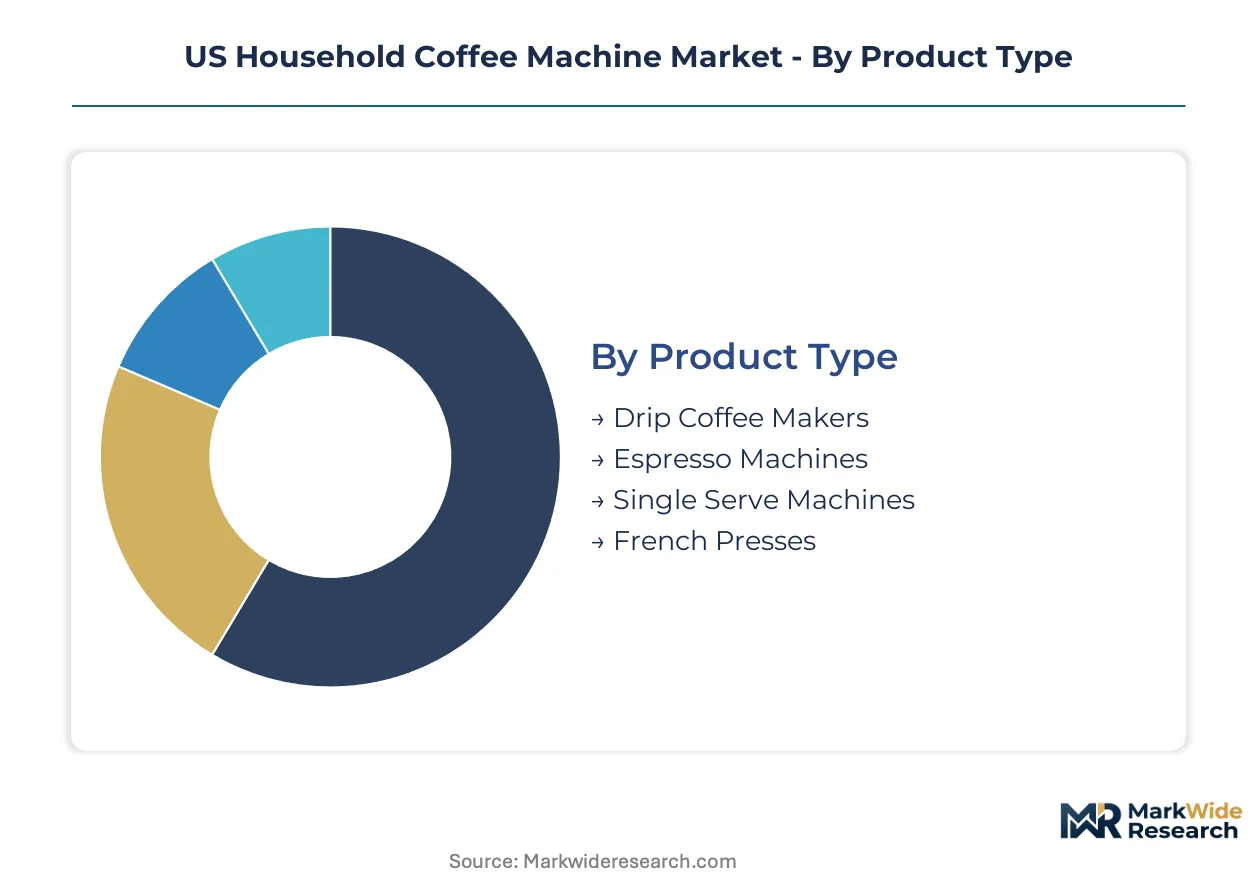
Segmentation in the US household coffee machine market reveals how brewing method preferences, household composition, and energy compliance requirements reshape manufacturer platform decisions. Understanding these divides exposes where margin pools concentrate versus where volume shipments accumulate.
Product Type:
Households choose brewing platforms based on morning routine compression versus beverage quality priorities, with convenience automation commanding suburban family budgets while pressure-extraction systems capture enthusiast spending.
- Single Serve Machines:Pod-based systems operate at 1,200-1,500W with pressurized water injection through sealed aluminum capsules. Demand clusters in Sun Belt suburban households where dual-income families prioritize speed over ritual; California Title 20 auto-shutoff mandates are accelerating thermal block redesigns that reduce standby draw.
- Espresso Machines:Thermoblock or boiler systems generate 9-bar extraction pressure through 1,400-1,500W heating elements with portafilter group heads. Arizona and Florida metro corridors show disproportionate adoption among remote professionals seeking café-equivalent quality; accessory ecosystems (tampers, scales, grinders) extend lifetime customer value.
- Drip Coffee Makers:Gravity-fed systems with warming plates or thermal carafes dominate budget-conscious Texas households and multi-generational homes.
- French Presses:Manual immersion devices with glass or stainless steel chambers attract minimalist kitchens and camping-adjacent lifestyles in Colorado mountain towns.
Volume sits with drip and single-serve platforms; growth tilts toward espresso systems absorbing grinder-brewer convergence demand.
End User:
Purchase authority and usage intensity vary sharply across residential versus commercial-adjacent settings, with household size and remote work status reshaping capacity and feature requirements.
- Families:Multi-person households with 3-5 members drive 10-12 cup carafe demand and programmable scheduling features. Texas and Florida new construction corridors show highest per-household spending on connected machines with app-based brewing.
- Individuals:Solo occupants prioritize single-serve pod systems or compact 4-cup drip units with minimal countertop footprint. Urban Arizona apartments favor machines under 12 inches width; subscription attach rates exceed family household averages.
- Offices:Small business break rooms purchase commercial-grade durability in residential form factors, with 30-40 cup daily throughput requirements.
- Cafés:Micro-roaster retail operations use prosumer espresso systems as customer demonstration tools and secondary brewing stations.
Shipment volume concentrates with individual buyers; steepest expansion trajectory belongs to family households upgrading from basic drip to feature-rich platforms.
Technology:
Heating system architecture determines energy compliance feasibility, pressure consistency, and maintenance intervals, with thermal efficiency mandates favoring specific engineering approaches.
- Pump:Electric motor-driven pressure systems deliver consistent 9-bar extraction through vibratory or rotary mechanisms. Premium tier positioning in Italian-engineered machines commands margin pools; NHTSA electrical safety standards govern motor housing insulation requirements.
- Thermal:Thermoblock heating elements with aluminum or stainless steel chambers achieve 30-second heat-up versus 10-minute boiler warm-up. California Title 20 compliance is accelerating displacement of traditional boiler systems; Sun Belt adoption leads due to energy cost sensitivity.
- Steam:Pressure generation through water vapor expansion creates lower-cost entry points for milk-frothing capable machines.
- Manual:Lever or piston systems eliminate electrical components entirely, attracting off-grid and sustainability-focused Colorado and Utah households.
Platform development investment clusters with thermal systems; manual technology gains share fastest among energy-independent lifestyle segments.
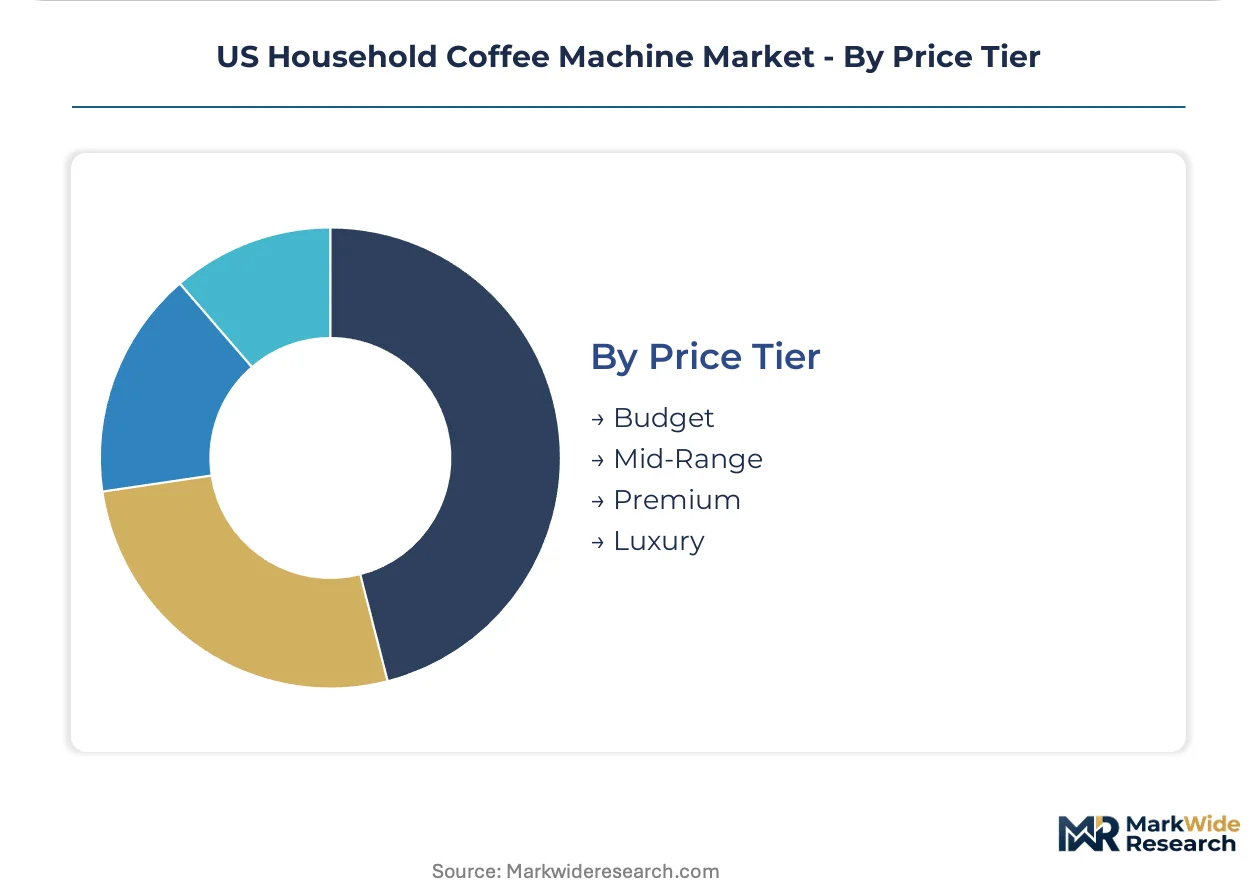
Price Tier:
Payment willingness correlates with consumable ecosystem lock-in potential and certification-grade material specifications, with federal efficiency rebates reshaping accessible price points.
- Premium:$400-$800 machines feature PID temperature control, dual boilers, and metal construction. Arizona and Florida high-income zip codes show concentration; IRA residential energy incentives are expanding addressable base for smart-enabled models with verified standby reduction.
- Mid-Range:$150-$350 segment balances programmable features with thermal carafe or single-serve versatility. Texas household formation corridors drive volume; this tier absorbs most grinder-brewer convergence demand.
- Budget:Sub-$150 drip and basic single-serve units dominate replacement cycles in multi-unit dwellings and secondary residences.
- Luxury:$800+ custom finishes and commercial-grade components target design-conscious kitchens with built-in installation requirements.
Revenue concentration rests with premium tier attach rates; mid-range platforms climb fastest on IRA subsidy eligibility and feature migration from above.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting capacity in the Pacific Northwest and petrochemical feedstock clusters along the Gulf Coast anchor component supply networks for domestic coffee machine assembly. Regional demand patterns diverge sharply between Sun Belt household formation corridors and legacy manufacturing zones undergoing industrial transition.
California
Title 20 energy efficiency mandates are accelerating auto-shutoff and insulated carafe adoption across Los Angeles and San Francisco metro corridors. CEC appliance standards exceed federal baselines, forcing platform redesigns that cascade through national product lineups. Silicon Valley firmware engineering clusters supply embedded systems talent for connected brewing schedules.
Texas
Houston and Dallas-Fort Worth household formation rates outpace national averages, expanding the addressable base for countertop appliances. ERCOT grid reliability concerns are amplifying energy cost sensitivity among suburban buyers. Austin semiconductor fabrication facilities supply control chips for smart-enabled thermal systems.
Florida
Miami and Tampa Bay remote professional concentrations are driving espresso machine adoption among café-equivalent quality seekers. NHTSA appliance safety standards govern electrical hazard prevention in high-humidity coastal environments. Orlando distribution hubs channel inventory to Caribbean and Latin American export markets.
Arizona
Phoenix and Tucson urban corridors show disproportionate single-serve penetration among dual-income families prioritizing morning routine compression. Colorado River water scarcity is tightening municipal energy efficiency incentives that favor low-wattage thermal systems. Flagstaff mountain towns anchor manual brewing device demand among outdoor lifestyle segments.
Mountain West
Colorado and Utah urban corridors exhibit lower single-serve penetration relative to income-adjusted benchmarks, presenting whitespace for targeted distribution. IRA residential energy rebates are creating subsidy tailwinds for smart-enabled machines with verified standby power reduction. Denver-Boulder tech corridors supply IoT engineering talent for maintenance alert firmware.
US Household Coffee Machine Market Competitive Landscape
Global majors compete with regional champions across pod ecosystem lock-in versus engineering heritage positioning. The vendor base stratifies into three tiers: beverage conglomerates with captive consumable platforms, European-engineered premium specialists, and Asian-scale fabricators serving private-label channels. Two dominant competitive moves are reshaping positioning: backward integration into precision pump component supply and direct-to-consumer subscription channel capture.
Within the pod-platform tier, Keurig Dr Pepper Inc. and Nestlé Nespresso SA occupy positions defined by recurring revenue attachment rather than hardware margin extraction. Among European-engineered specialists, De'Longhi Group and Breville Group Limited exemplify heritage-based premium positioning that commands price tiers through Italian and Australian design provenance respectively.
| Leading Market Players |
|---|
| Keurig Dr Pepper Inc. |
| Nestlé Nespresso SA |
| Hamilton Beach Brands Holding Company |
| De'Longhi Group |
| Breville Group Limited |
| SharkNinja Operating LLC |
| BUNN-O-Matic Corporation |
| Koninklijke Philips N.V. |
| Newell Brands |
| Others |
Pricing and Supply Chain Analysis
Firmware engineering talent concentration in Silicon Valley and Austin metro corridors creates labor-cost differentials that widen pricing-tier spreads between connected and basic thermal systems. Manufacturers absorbing embedded systems salaries into platform costs must recover through premium positioning or accept compressed margins in mid-range categories.
Pricing Analysis
Warranty and service bundling separates premium espresso platforms with multi-year coverage from budget drip units sold as-is through big-box retail. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with UL-listed thermal systems commanding spreads over uncertified imports. Cost compression in sub-$150 categories is intensifying because aluminum and plastic resin input volatility erodes hardware margins. Budget-tier buyers in multi-unit dwellings show highest price sensitivity; least sensitivity appears among Arizona and Florida remote professionals seeking café-equivalent quality.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for control chips and thermoblock assemblies, while aftermarket distribution runs through regional appliance parts distributors serving independent repair networks. Component supply concentrates in China for precision pumps, Italy for thermoblock engineering, and Mexico for final assembly serving US demand. Raw material dependencies include aluminum for heating chambers, copper for wiring harnesses, and food-grade plastics for brewing interfaces. Single-source vulnerability in Italian pump suppliers creates geographic concentration risk. Distribution downstream centers on big-box retail, direct-to-consumer subscription channels, and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California Title 20 regulatory divergence is forcing costly dual-SKU platform maintenance that weaker players cannot absorb, consolidating share among capital-rich incumbents with compliance infrastructure already deployed.
For Market Incumbents: Deploy backward integration into thermoblock component supply to reduce exposure to Italian and Chinese supplier concentration. Capture grinder-brewer convergence demand through integrated platform launches that consolidate countertop footprint. Threat from pod subscription attach rates requires defending consumable ecosystem lock-in against private-label pod encroachment. Channel control through direct-to-consumer replenishment apps reinforces recurring revenue defensibility. For New Entrants and Emerging Players: Smart-enabled thermal systems with IRA subsidy eligibility offer technology-first entry into premium tiers where firmware differentiation commands pricing power. Target Mountain West whitespace in Colorado and Utah urban corridors showing income-adjusted underpenetration relative to Sun Belt benchmarks. Grinder-brewer convergence in space-constrained kitchens presents the most penetrable application segment. Go-to-market angle should emphasize verified standby power reduction qualifying for federal efficiency rebates. For Investors and Strategic Acquirers: Re-rating potential sits with European-engineered premium specialists given IRA residential energy incentive tailwinds expanding addressable base for smart-enabled platforms. Long-term viability favors acquirers with consumable ecosystem attach rates and compliance infrastructure spanning multiple state regulatory regimes. Target acquisition archetype: mid-scale fabricators with captive pod or accessory platforms and established California Title 20 certification. Signal to watch: state-level efficiency preemption debates accelerating national platform standardization decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Migration | Direct-to-consumer pod replenishment captures recurring revenue relationships from retail intermediaries. |
| Thermoblock Technology Investment | Faster heat-up cycles and reduced energy waste absorb development funding from traditional boiler systems. |
| California Title 20 Compliance Consolidation | Single platform architecture meeting strictest state rules eliminates costly dual-SKU maintenance. |
| Grinder-Brewer Convergence Launch | Integrated bean-to-cup systems address countertop consolidation demand in space-constrained kitchens. |
| IRA Rebate Eligibility Certification | Federal efficiency subsidies expand addressable base for smart-enabled machines with verified standby reduction. |
Research Methodology
Independent corroboration across appliance manufacturing executives, retail category buyers, embedded systems engineers, and regulatory compliance officers underwrites the qualitative findings. Primary interviews with thermal system R&D directors and pod platform marketing heads combined with secondary validation from NHTSA appliance safety guidance, California CEC Title 20 standards documentation, and IRA residential energy incentive regulations. Bottom-up shipment analysis triangulates against top-down household formation data from Sun Belt state economic agencies.
Comparable-period anchoring to historical replacement cycle patterns and energy cost sensitivity trends established the forecast window baseline. Segmentation modeling spans product type, end-user household composition, heating technology architecture, and price tier positioning across the projection horizon. CAGRs derive from installed base growth, upgrade rate assumptions, and regulatory compliance-driven replacement acceleration. Industry-specific inputs include pod subscription attach rate trajectories and Title 20 auto-shutoff mandate implementation timelines.
Several conditions sit outside the modeled scope, including extreme commodity price volatility scenarios, federal preemption of state efficiency standards, and disruptive brewing technology introductions outside pressurized extraction or pod-based systems. Forecasts reflect assumptions regarding household formation continuity and regulatory stability that stress-testing should periodically validate. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Outdoor Kitchen Appliances Market
Kitchen Appliances
Small Kitchen Appliances Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Asia Pacific Induction Hobs Market
Kitchen Appliances
Household Kitchen Appliances Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Smart Kettle Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
Cookware Accessories Market
Kitchen Appliances
Canada Kitchen Appliances Market