
 GCC Dishwashers Market | 2026-2036
GCC Dishwashers Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Dishwashers Market Foresight
Stainless steel interior construction is recalibrating cost structures across the GCC Dishwashers Market as manufacturers shift from plastic tubs to corrosion-resistant alloys suited to the region's hard water conditions. Robert Bosch leverages its European engineering heritage to anchor premium positioning in Saudi Arabia's major retail channels. Samsung Electronics competes through integrated smart-home ecosystems that extend connectivity from mobile devices to kitchen appliances. LG Electronics differentiates via inverter direct-drive motor technology that reduces noise levels critical for open-plan Gulf residences.
A dishwasher is an electromechanical appliance engineered to clean dishware, utensils, and cookware through pressurized water jets, detergent chemistry, and controlled thermal cycles typically operating between 45°C and 75°C. Built-In units dominate GCC residential installations where custom kitchen cabinetry integration drives contractor specifications, while Intelligent Sensor technology captures expanding share as water-scarce economies prioritize load-adaptive consumption. The Hospitality application segment sustains above-average equipment turnover due to 24-hour operational demands across hotel chains in Dubai and Riyadh.
SASO's mandatory energy-labeling scheme and the UAE's ECAS conformity requirements shape product compliance costs for manufacturers seeking Gulf market access. The region's absence of unified appliance standards across six member states fragments certification pathways and extends time-to-market for new entrants. Stakeholders must monitor evolving water-tariff structures and municipal greywater regulations that could redefine total-cost-of-ownership calculations for commercial buyers.
Market Dynamics
Saudi Arabia's SASO energy-efficiency mandates are compressing product lifecycles across the GCC Dishwashers Market as manufacturers redesign motor systems and control electronics to meet escalating compliance thresholds.
Growth Catalysts
- SASO Energy-Labeling Mandates:Saudi Arabia's mandatory efficiency tiers for household appliances are forcing technology upgrades that cascade across GCC supply chains, accelerating replacement cycles in Riyadh and Jeddah residential developments.
- Hospitality Infrastructure Expansion:Premium hotel construction in Dubai's hospitality corridor sustains commercial equipment demand as 24-hour operational requirements drive above-average unit turnover.
- Smart-Home Integration:IoT-enabled load-sensing dishwashers are capturing share in UAE high-rise residential installations where building management systems prioritize water-consumption telemetry.
Market Restraints
- Stainless Steel Input Volatility:Corrosion-resistant alloy prices fluctuate with nickel and chromium spot markets, squeezing margins for manufacturers transitioning from plastic tub construction.
- Fragmented Certification Pathways:The absence of unified appliance standards across six GCC member states extends time-to-market for new entrants navigating SASO, ECAS, and national conformity bodies simultaneously.
- Manual Dishwashing Substitution:South Asian expatriate labor availability in Saudi Arabia and Kuwait sustains cost-competitive manual alternatives that limit household penetration in price-sensitive segments.
Strategic Opportunities
- Qatar's Hospitality Pipeline:FIFA legacy infrastructure and new luxury hotel developments in Doha create concentrated demand for commercial-grade intelligent sensor systems.
- Greywater Integration Mandates:Evolving municipal regulations in Abu Dhabi and Dubai could redefine total-cost-of-ownership calculations for developers specifying water-recycling compatible units.
- ECAS Convergence with SASO:Regulatory harmonization discussions between UAE and Saudi conformity assessment bodies may streamline certification costs for pan-GCC product strategies.
Industry Challenges
- Technical Service Network Gaps:Inverter direct-drive motor repair capabilities remain concentrated in Dubai and Riyadh, extending downtime for installations in Oman and Bahrain.
- Hard Water Calibration Complexity:Sensor-based load detection requires region-specific algorithm tuning to address calcium carbonate scaling patterns unique to Gulf desalinated water chemistry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Dishwashers Market |
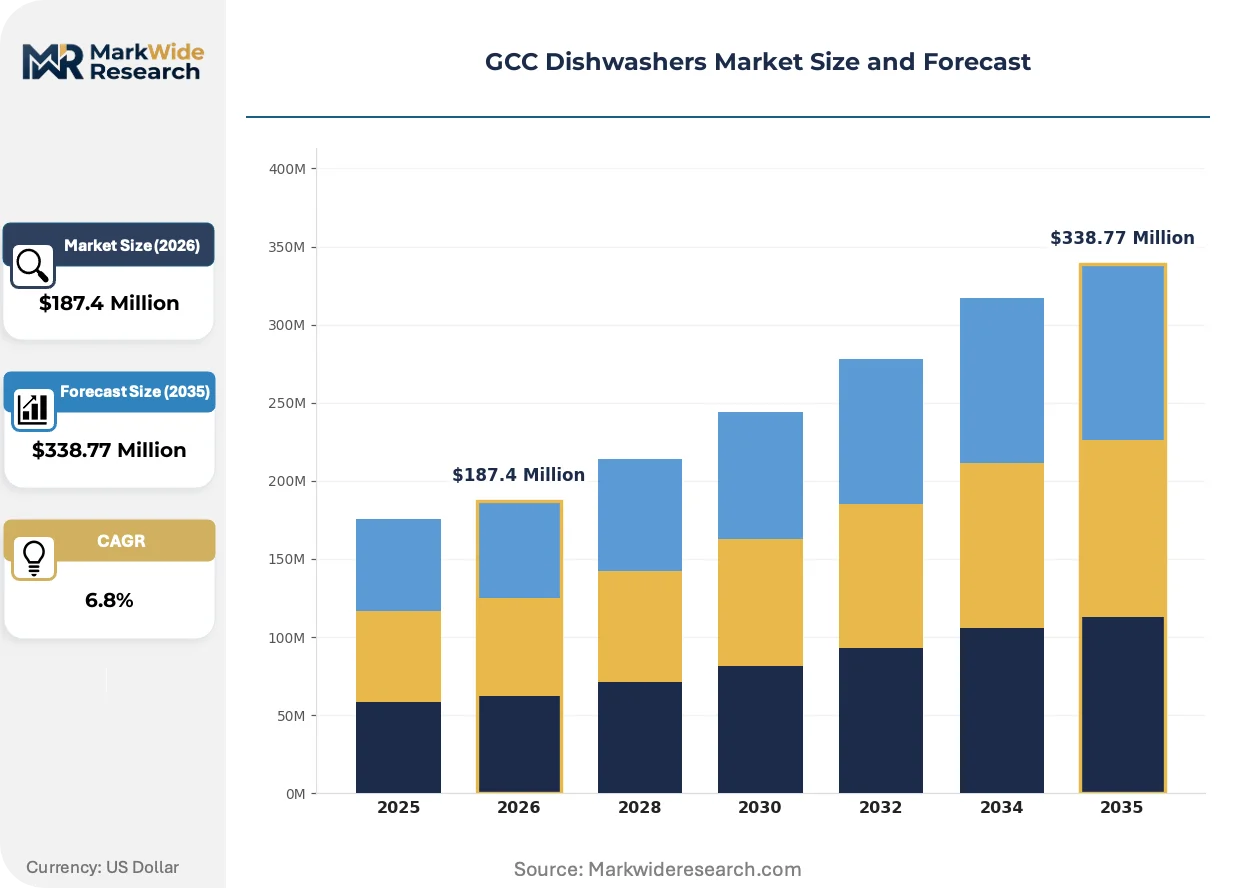
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-In, Countertop, Portable, Drawer, Compact Technology: Conventional, Intelligent Sensor, Eco-Friendly, High-Temperature Wash, Ultrasonic Application: Households, Food Service, Hospitality, Institutional, Corporate Offices Distribution Channel: Specialty Stores, Online Retail, Hypermarkets, Home Appliance Dealers, Direct Sales |
| Companies Covered | Whirlpool Corporation, Robert Bosch, Samsung Electronics, LG Electronics, Frigidaire, Evvoli, Midea, Siemens, Sharp, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Dishwashers Market Shifts & Advancements
Water-scarcity economics and labor cost inflation are reshaping equipment specifications across GCC residential and commercial installations. Technology trajectories prioritize consumption transparency and integration with building automation infrastructure.
Intelligent sensor arrays with turbidity detection and load-adaptive water cycling are overtaking timer-based mechanical controls in premium GCC installations. Hospitality procurement teams in Dubai and Riyadh specify these systems to document consumption metrics for sustainability reporting. The shift is compressing demand for entry-level electromechanical units while expanding service-revenue attachment rates for calibration and software updates.
SASO's escalating minimum efficiency performance standards are restructuring supplier qualification requirements for Saudi market access. Manufacturers must now submit third-verified test data for standby power and water consumption per place setting. The policy most acutely affects Chinese OEMs supplying value-tier distributors in Jeddah, who face redesign costs or market exit.
Developer-led bulk procurement for high-rise residential towers is consolidating purchase authority away from individual consumers in Abu Dhabi and Dubai. Master developers now specify dishwasher models during construction-phase MEP contracting, embedding appliances before unit sale. This channel shift compresses retail margin pools while elevating importance of contractor relationships and project-specification engineering teams.
GCC Dishwashers Market Segmentation
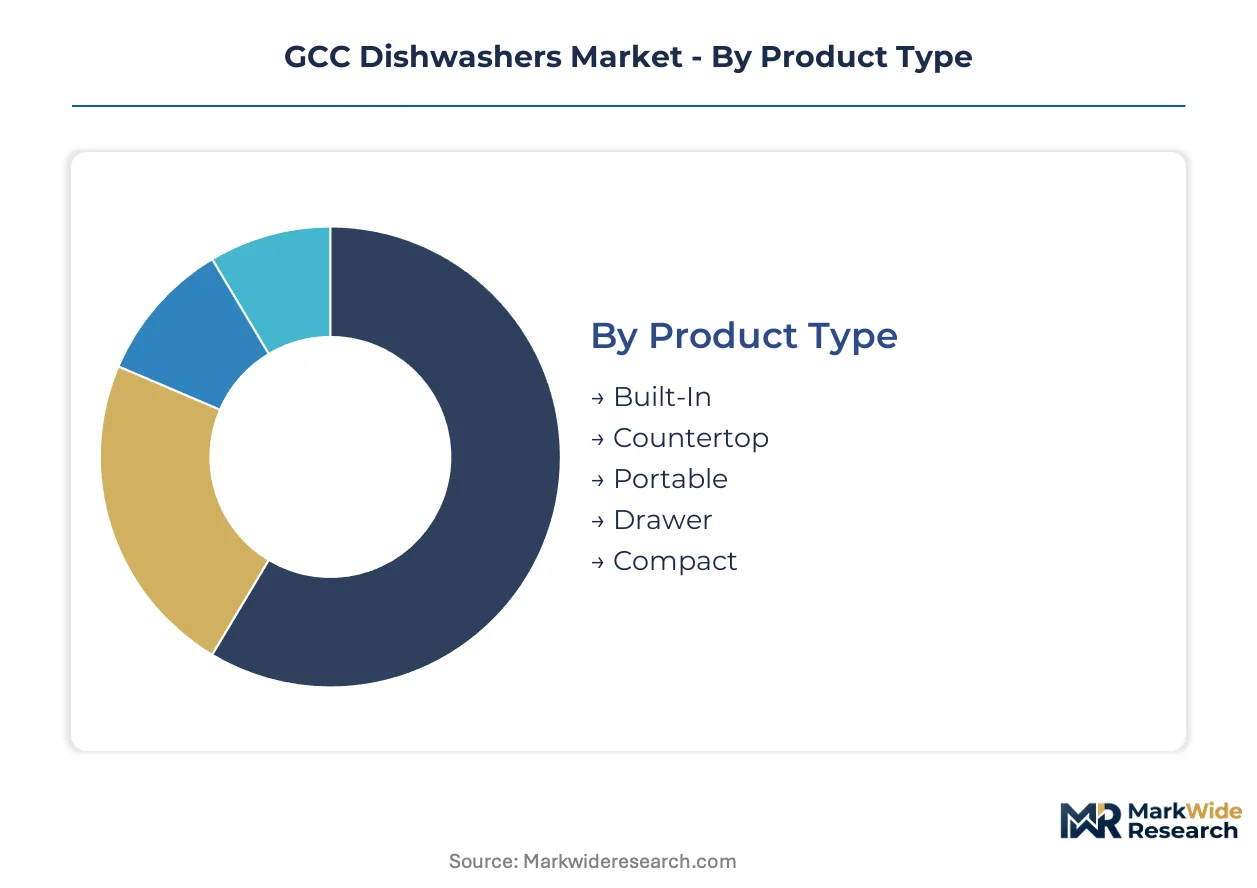
Equipment specification varies sharply across GCC installation contexts, from custom kitchen integration in Dubai high-rises to portable units serving Saudi labor camps. Segmentation reveals how water-scarcity economics and labor cost structures reshape procurement priorities across residential and commercial buyers.
Product Type:
Installation geometry determines contractor specifications and replacement economics across Gulf markets.
- Built-In:Custom cabinetry integration with permanent plumbing connections dominates UAE high-rise residential towers and Saudi villa developments. Master developers in Dubai now specify these units during MEP contracting, embedding appliances before unit handover and compressing retail channel relevance.
- Countertop:Compact freestanding units with temporary water connections serve price-sensitive segments and rental housing in Kuwait and Bahrain where permanent installation is restricted. Demand concentrates among South Asian expatriate households seeking appliance mobility.
- Portable:Wheeled units with faucet adapters address kitchen retrofit limitations in older Saudi and Omani residential stock where plumbing modification costs exceed equipment value.
- Drawer:Dual-chamber configurations with independent wash zones capture premium kitchen renovations in Abu Dhabi and Doha, where space optimization justifies unit cost premiums.
- Compact:Reduced-capacity units designed for 2-4 place settings serve smaller household formations in urbanizing Saudi second-tier cities where nuclear family structures displace extended kin arrangements.
Built-In leads on scale; Drawer leads on momentum.
Technology:
Control system sophistication separates compliance-driven replacements from discretionary upgrades across GCC regulatory environments.
- Conventional:Timer-based electromechanical controls with fixed water volumes retain share in Saudi value-tier distribution through Jeddah-based OEM suppliers, though SASO efficiency mandates are compressing product lifecycles and forcing redesign costs or market exit.
- Intelligent Sensor:Turbidity detection arrays with load-adaptive cycling are overtaking mechanical controls in premium UAE installations. Hospitality procurement teams in Dubai specify these systems to document consumption metrics for sustainability reporting and 24-hour operational efficiency.
- Eco-Friendly:Reduced water and energy consumption profiles align with Saudi SASO energy-labeling tiers and Abu Dhabi municipal greywater integration requirements, accelerating specification in new construction.
- High-Temperature Wash:Thermal sanitization cycles operating above 70°C satisfy HACCP requirements for food service operations across Riyadh and Doha commercial kitchens.
- Ultrasonic:Cavitation-based cleaning without detergent chemistry remains nascent in GCC markets, with pilot installations limited to specialized institutional applications in Dubai healthcare facilities.
Intelligent Sensor dominates value creation; Eco-Friendly climbs the fastest on regulatory tailwinds.
Application:
End-use operational intensity determines equipment durability requirements and replacement frequency.
- Households:Residential installations across Saudi Arabia and UAE drive volume, with procurement shifting from individual consumers to master developer bulk contracting in Abu Dhabi and Dubai high-rise construction.
- Food Service:Restaurant and catering operations in Riyadh and Jeddah sustain demand for high-throughput units with rapid cycle times, though manual dishwashing substitution by expatriate labor limits penetration in independent establishments.
- Hospitality:24-hour operational demands across Dubai's hotel corridor and Doha's FIFA legacy infrastructure drive above-average equipment turnover and premium specification for intelligent sensor systems.
- Institutional:Healthcare and education facilities in Saudi Arabia's Vision 2030 infrastructure program specify energy-labeled equipment to meet public procurement sustainability criteria.
- Corporate Offices:Pantry installations in UAE commercial towers integrate with building management systems for water-consumption telemetry, favoring IoT-enabled connectivity.
Households anchor volume; Hospitality generates steepest expansion trajectory on infrastructure investment.
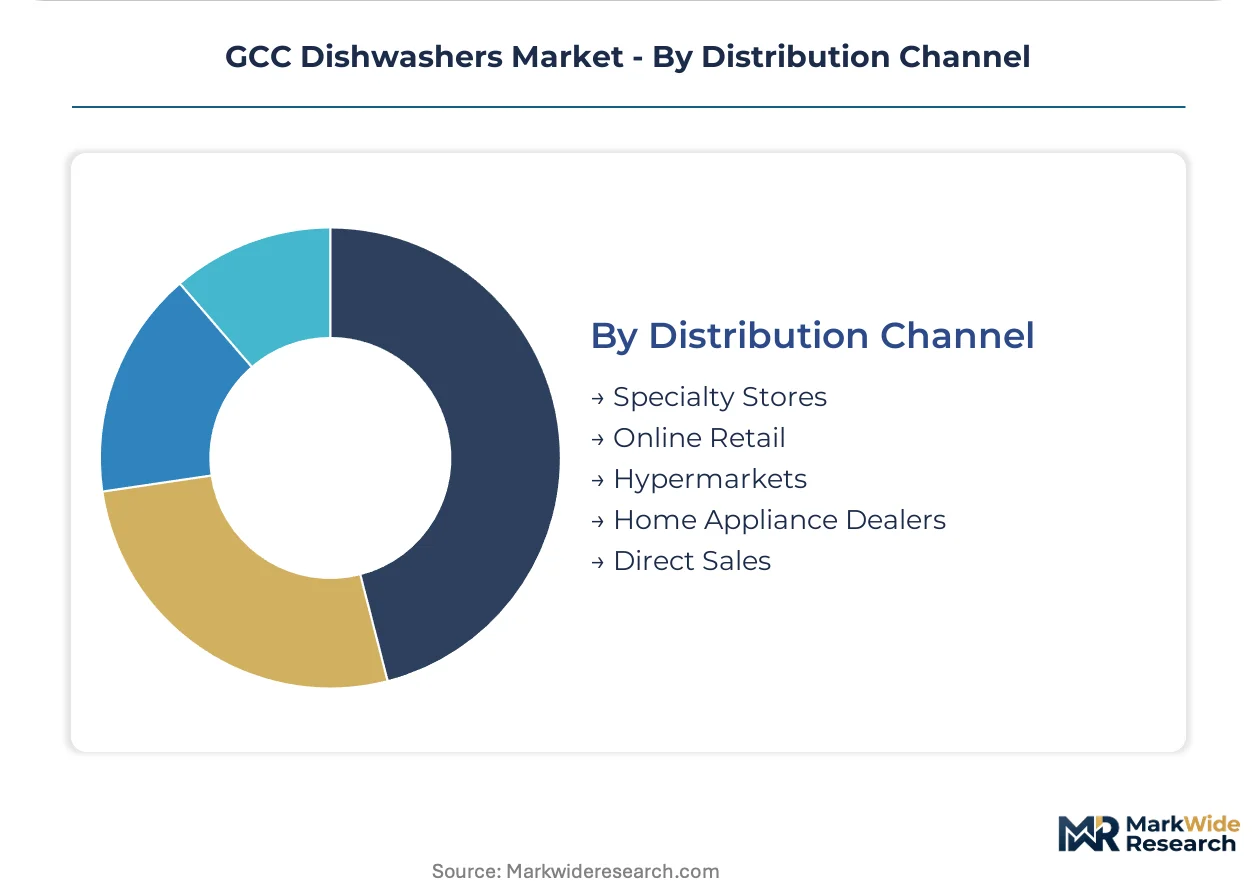
Distribution Channel:
Purchase authority migration from retail to project specification is restructuring margin capture across GCC supply chains.
- Specialty Stores:Kitchen design showrooms in Dubai's Al Quoz industrial zone and Riyadh's Olaya district serve renovation-driven replacement demand with consultation-heavy sales processes.
- Online Retail:E-commerce platforms capture growing share in Saudi Arabia's digitally native consumer segments, though large-appliance logistics complexity limits penetration relative to electronics categories.
- Hypermarkets:Carrefour and Lulu operations across UAE and Saudi Arabia serve price-comparison shoppers with visible floor displays, competing aggressively on entry-tier portable and countertop units.
- Home Appliance Dealers:Independent retail networks in Oman and Bahrain retain relevance where developer-led bulk procurement is less concentrated and individual purchase authority persists.
- Direct Sales:Manufacturer relationships with MEP contractors and master developers in Abu Dhabi and Dubai bypass retail margin entirely, embedding appliances during construction-phase specification.
Direct Sales concentrates value capture; Online Retail gains share fastest on logistics network maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's hospitality corridor anchors dishwasher demand across the Gulf Cooperation Council, with master developer bulk procurement reshaping distribution channels. SASO efficiency mandates in Saudi Arabia and ECAS conformity requirements in the UAE fragment certification pathways while accelerating technology upgrades. Water-scarcity economics and labor cost inflation drive specification shifts from entry-level mechanical controls to intelligent sensor systems.
Saudi Arabia
Vision 2030 infrastructure investment and SASO energy-labeling mandates compress product lifecycles in Riyadh and Jeddah residential developments. The Saudi Standards, Metrology and Quality Organization enforces escalating minimum efficiency performance standards for standby power and water consumption. Eastern Province industrial zones concentrate commercial food service procurement as petrochemical workforce housing expands.
United Arab Emirates
High-rise residential construction in Dubai and Abu Dhabi drives built-in unit specification through MEP contractor relationships rather than retail channels. The Emirates Conformity Assessment Scheme mandates product safety and energy efficiency verification for market access. Dubai's Al Quoz industrial zone clusters kitchen design showrooms serving renovation-driven replacement demand.
Qatar
FIFA legacy infrastructure and luxury hotel developments in Doha create concentrated demand for commercial-grade intelligent sensor systems. The Qatar General Organization for Standardization implements appliance efficiency regulations aligned with Gulf harmonization initiatives. Lusail City's master-planned districts embed smart-home ecosystems during construction-phase specification.
Kuwait
South Asian expatriate labor availability sustains manual dishwashing substitution that limits household penetration in price-sensitive segments. The Public Authority for Industry administers conformity requirements for imported appliances. Hawalli Governorate rental housing concentrates countertop and portable unit demand where permanent installation is restricted.
Oman
Technical service network gaps for inverter direct-drive motor repair extend equipment downtime outside Muscat metropolitan areas. The Ministry of Commerce, Industry and Investment Promotion oversees product standardization without unified GCC alignment. Sohar's port industrial zone attracts logistics investment for spare parts distribution serving smaller Gulf markets.
GCC Dishwashers Market Competitive Landscape
Global majors compete with regional champions across distribution channel access and certification navigation capabilities. The vendor base stratifies between European engineering heritage brands, Korean electronics conglomerates with smart-home ecosystems, and Chinese OEMs supplying value-tier distributors. Three archetypes dominate: premium positioning through European manufacturing lineage, ecosystem integration through mobile-to-appliance connectivity, and cost leadership through plastic-to-stainless steel construction transitions. Competitive moves center on MEP contractor relationship cultivation and SASO compliance engineering investments.
Among diversified appliance conglomerates, Robert Bosch and Samsung Electronics exemplify contrasting positioning strategies. Bosch leverages its European GmbH structure to anchor premium retail placement in Saudi Arabia's Olaya district showrooms. Samsung Electronics occupies the ecosystem-integration tier, extending connectivity architectures from mobile devices into kitchen automation. LG Electronics represents the noise-reduction specialization vector, with inverter direct-drive motor technology addressing open-plan Gulf residence requirements. Siemens and Whirlpool Corporation sit within the full-line manufacturer archetype, spanning residential and commercial specification ranges.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Robert Bosch |
| Samsung Electronics |
| LG Electronics |
| Frigidaire |
| Evvoli |
| Midea |
| Siemens |
| Sharp |
| Others |
Supply & Pricing Matrix
Nickel and chromium spot market volatility cascades through GCC dishwasher manufacturing cost structures, compressing margins for suppliers transitioning from plastic tub construction to corrosion-resistant alloys while fragmenting pricing power across stainless steel-dependent premium tiers and plastic-retaining value segments.
Pricing Analysis
Input-cost pass-through from alloy commodity markets fragments pricing stratification across premium, standard, and economy tiers. Stainless steel interior specifications command brand premiums in Saudi Arabia's Olaya district showrooms, while plastic-tub units compete on landed cost in Kuwait's price-sensitive expatriate segments. Pricing pressure stems from SASO efficiency-mandated redesign cycles forcing R&D recovery through upfront equipment premiums. Master developer bulk procurement in Abu Dhabi exhibits lowest price sensitivity; independent retail buyers in Bahrain demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from MEP contractors in Dubai and Riyadh mandate multi-supplier qualification for motor systems and control electronics, preventing single-source dependency despite concentration in South Korean and Chinese manufacturing bases. Stainless steel sheet feeds from Taiwan and Japan, electronic control modules from South Korea, and desalination-resistant seal polymers from Germany constitute critical input dependencies. Single-source vulnerability concentrates in inverter direct-drive motor supply where LG Electronics and Samsung Electronics dominate Gulf aftermarket service networks. Distribution runs through master developer specification channels in UAE high-rise construction, bypassing traditional retail margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO's escalating energy-labeling tiers compound demand for compliant equipment, making this market a regulatory compounder where certification engineering investments determine supplier viability.
For Market Incumbents: Extend technical service networks into Oman and Bahrain to close inverter motor repair capability gaps that extend downtime and erode hospitality contract renewals. Deepen backward integration into stainless steel component forging to offset nickel price volatility squeezing plastic-to-alloy transition margins. Anchor premium positioning through European engineering heritage narratives in Saudi Arabia's retail channel consolidation.
For New Entrants and Emerging Players: Capture specification authority in Qatar's FIFA legacy hospitality pipeline where intelligent sensor system demand concentrates and incumbent relationships remain unsettled. Target countertop and portable segments in Kuwait's South Asian expatriate rental housing where permanent installation restrictions limit built-in incumbent dominance. Pursue direct sales channel cultivation with MEP contractors in Doha's Lusail City master-planned districts.
For Investors and Strategic Acquirers: Consolidation pressure builds where technical service network gaps and certification compliance costs exceed standalone profitability for mid-tier distributors. Long-term viability favors suppliers with pan-GCC SASO-ECAS navigation capabilities and project-specification engineering teams embedded in Abu Dhabi and Dubai master developer relationships. Watch greywater integration mandate progression in Dubai and Abu Dhabi municipal regulations as inflection indicator for water-recycling compatible unit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| SASO Compliance Engineering Investment | Third-verified test data submission capabilities unlock Saudi Arabia's mandatory efficiency tier market access. |
| MEP Contractor Relationship Cultivation | Construction-phase specification authority in Dubai high-rises bypasses retail margin compression entirely. |
| Intelligent Sensor Technology Integration | Turbidity detection arrays with load-adaptive cycling capture sustainability reporting requirements in Riyadh hospitality procurement. |
| Regional Service Network Expansion | Inverter direct-drive motor repair capabilities in Oman and Bahrain reduce equipment downtime penalties in commercial contracts. |
| Greywater Compatibility Certification | Water-recycling compatible unit specifications align with evolving Abu Dhabi municipal regulations redefining total-cost-of-ownership calculations. |
Research Methodology
Bottom-up hospitality and residential installation modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with MEP specification engineers, master developer procurement directors, kitchen design showroom operators, and SASO certification consultants combined with secondary validation from customs trade records, SASO energy-labeling registry data, and ECAS conformity assessment filings. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity.
Input-output matrices mapping stainless steel alloy costs, motor system technology tiers, and regulatory compliance thresholds to end-use price elasticities structure the forecast framework across the analysis window. Segmentation dimensions span product type geometry, control system sophistication, application operational intensity, and channel purchase authority migration. CAGRs derive from regression analysis against historical replacement cycles and infrastructure investment pipelines, with hard water calibration complexity and labor cost inflation as industry-specific demand shapers.
Commodity price volatility in nickel and chromium markets, regulatory harmonization progression between SASO and ECAS frameworks, and South Asian expatriate labor availability shifts are the dominant revision risks to modeled demand trajectories. Deviation in greywater integration mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Turkey Washing Machine Market
Appliances
Global Massage Chairs Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
Global Electric Water Heaters Market
Appliances
Commercial Microwave Ovens Market
Appliances
Refrigerator Door Seal Market
Appliances
Smart Dishwasher Market
Appliances
France Household Electric Grills Market
Appliances
United States Microwave Oven Market
Appliances
Electric Hand Dryer Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Mexico Washing Machine Market
Appliances
UAE Microwave Ovens Market
Appliances
Electric Ranges Market
Appliances
Water Heater Market
Appliances
Household Side by Side Refrigerator Market