
 Malaysia Smart Kitchen Appliances Market | 2026-2036
Malaysia Smart Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Smart Kitchen Appliances Market Outlook
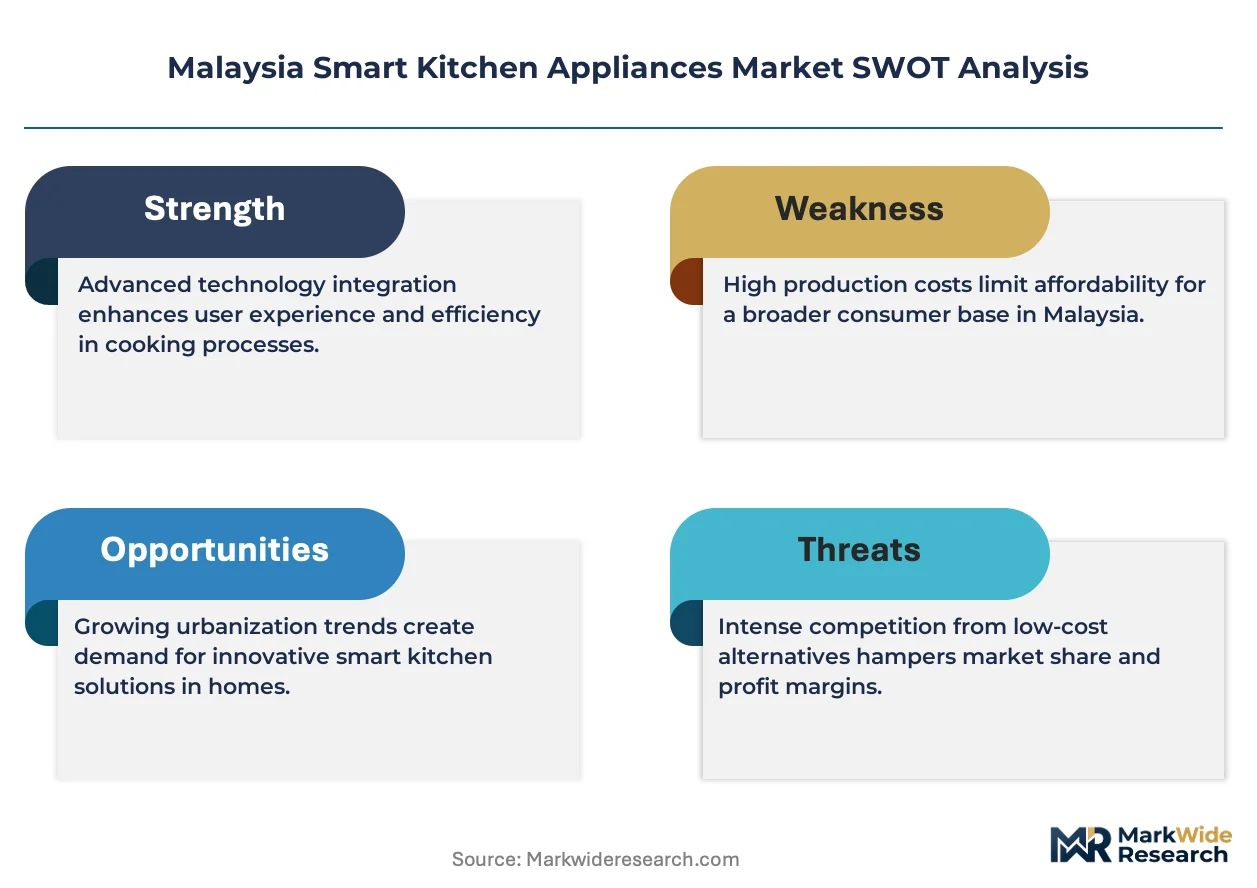
The Malaysia smart kitchen appliances category is restructuring around a widening gap between premium connected suites and entry-level Wi-Fi add-ons. Electrolux Malaysia leverages its Nordic design positioning to anchor the high-end segment through specialist retail channels. Haier Malaysia competes on manufacturing scale, sustaining cost advantages in smart refrigerator production from its regional hub operations. Xiaomi Malaysia differentiates through ecosystem bundling, extending its IoT platform into budget-conscious urban households.
Malaysia smart kitchen appliances encompass programmable cooking, refrigeration, and cleaning devices that integrate wireless connectivity, sensor arrays, and cloud-based automation to optimize food preparation and energy management. These units typically operate on 240V/50Hz mains supply with IPX4 minimum moisture ingress protection for countertop models, serving both residential efficiency goals and commercial kitchen labor reduction. Smart refrigerators lead product type value contribution due to embedded inventory tracking and variable compressor technology commanding sustained margin pools. Voice control interfaces within the technology dimension show the steepest adoption curve among younger demographics in Selangor and Johor. The hospitality end user segment demonstrates concentrated procurement scale, with hotel chains standardizing connected galley equipment across new property rollouts.
SIRIM QAS International governs electrical safety certification and electromagnetic compatibility testing, while the Energy Commission enforces minimum energy performance standards that filter non-compliant imports from regional suppliers. The Malaysia Digital Economy Blueprint and Communications and Multimedia Commission guidelines on IoT data governance additionally shape product development priorities for cloud-connected inventory. Stakeholders must monitor evolving interoperability mandates between competing smart home protocols to protect installed base investments and avoid stranded connectivity assets.
Market Dynamics
Malaysia's smart kitchen appliance sector is bifurcating around developer-specified connected suites in high-rise residential towers versus fragmented retail purchases of standalone Wi-Fi-enabled units. This structural tension between specification-driven bulk procurement and consumer-direct channels is compressing mid-market positioning and forcing vendors to choose scale or specialization.
Growth Catalysts
- SIRIM QAS certification mandates:Mandatory electrical safety testing creates compliance barriers that filter low-quality imports and protect established suppliers with certified product portfolios.
- High-rise developer specifications:Kuala Lumpur and Penang residential towers now standardize connected appliance packages as fit-out defaults, embedding smart kitchen infrastructure before occupant move-in.
- Variable compressor refrigeration:Smart refrigerators with embedded inventory tracking and adaptive cooling cycles command sustained margin pools through demonstrable energy savings.
Market Restraints
- Copper and semiconductor input volatility:Compressor motors and IoT chipsets face price instability that compresses manufacturing margins on entry-tier products.
- Single-protocol concentration risk:Heavy reliance on Wi-Fi connectivity standards creates stranded asset exposure if interoperability mandates shift toward Matter or alternative mesh protocols.
- 240V/50Hz technical limitation:Voltage-frequency specificity restricts direct import of 110V-optimized smart appliances from North American supply bases without costly redesign.
Strategic Opportunities
- Johor Bahru corridor expansion:Underpenetrated demand in southern peninsula states adjacent to Singapore offers whitespace for ecosystem bundlers targeting cross-border commuter households.
- SEDA energy efficiency labeling:Regulatory tailwinds from Sustainable Energy Development Authority incentive structures reward connected appliances with superior MEPS ratings.
- Voice-AI convergence:Integration of Bahasa Malaysia natural language processing with appliance control interfaces opens differentiation for localized software stacks.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of IoT security specialists delays product launch timelines and elevates vulnerability remediation costs.
- SIRIM certification timeline compression:Extended electromagnetic compatibility testing queues create working capital strain for seasonal product introductions.
- Legacy kitchen infrastructure retrofit complexity:Existing residential stock lacks neutral wiring and dedicated circuit capacity for high-load connected cooking equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Smart Kitchen Appliances Market |
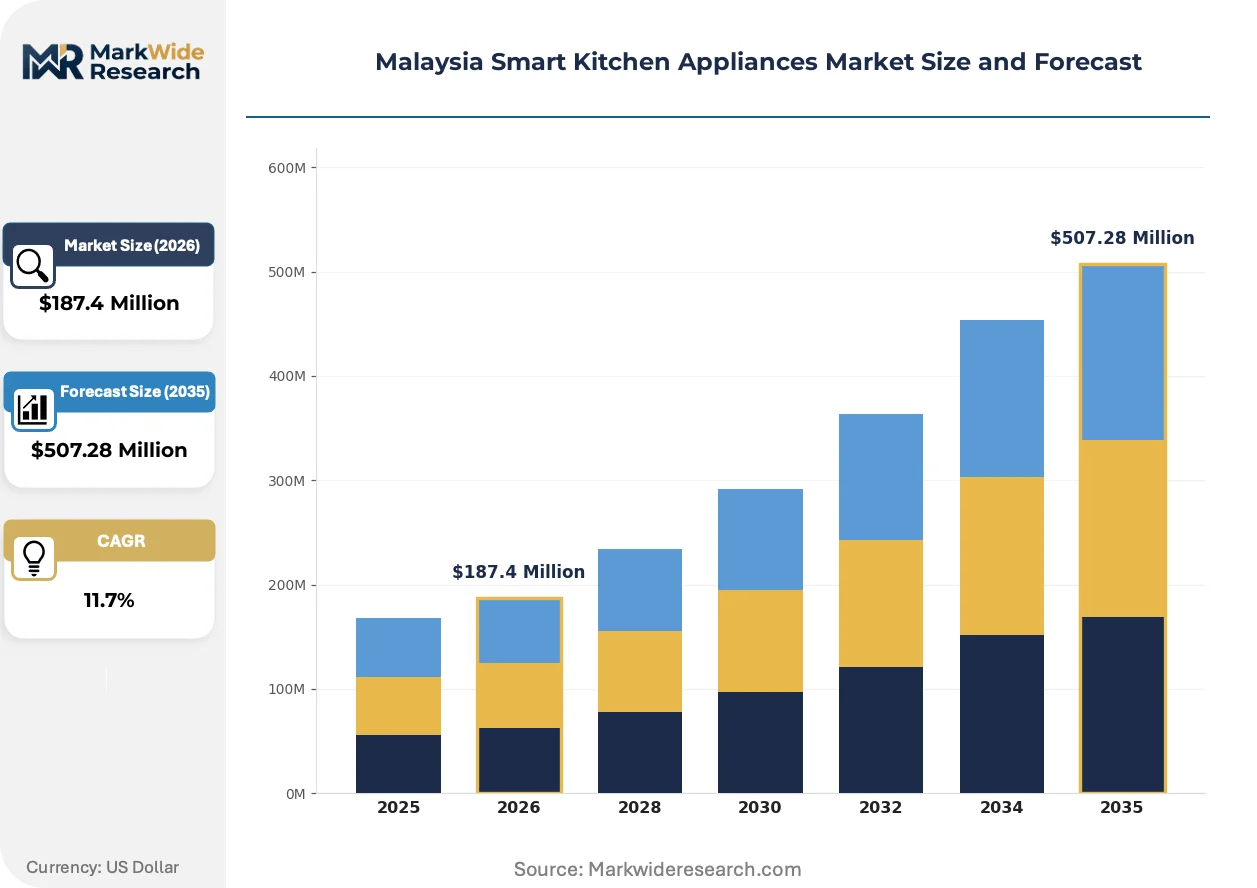
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Ovens, Smart Refrigerators, Smart Mixers, Smart Dishwashers Technology: IoT-Enabled, Wi-Fi Connectivity, Bluetooth, Voice Control End User: Residential, Commercial, Hospitality, Institutional Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Electrolux Malaysia, Haier Malaysia, Panasonic Malaysia, Teka Malaysia, Rinnai Malaysia, Samsung Malaysia, Bosch Malaysia, Xiaomi Malaysia, LG Electronics Malaysia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Smart Kitchen Appliances Market Strategic Shifts
Voice control interfaces and cloud-based automation are displacing touch-panel dominance as the primary human-appliance interaction layer. This interface shift is compressing hardware differentiation and elevating software ecosystem stickiness as the decisive competitive variable.
Matter protocol standardization is consolidating fragmented smart home connectivity architectures into unified interoperability frameworks. Appliance manufacturers in Selangor are adopting Matter certification to reduce SKU complexity across multiple retail channel requirements. This consolidation is enabling smaller vendors to compete on feature parity without maintaining proprietary cloud infrastructure.
Malaysia Digital Economy Blueprint data governance guidelines are reshaping cloud-connected inventory management architectures. Appliance firmware must now incorporate local data residency provisions and explicit user consent workflows for usage analytics transmission. Hospitality chains operating central kitchen facilities are responding by demanding on-premise edge computing options that limit cross-border data flows.
Developer-direct procurement is displacing traditional retail showroom selection for premium residential segments. Property management firms in Mont Kiara and Cyberjaya are bundling appliance specifications into design-and-build contracts with extended warranty service agreements. This channel compression is visible most acutely in new high-rise towers where fit-out decisions precede individual purchaser involvement.
Malaysia Smart Kitchen Appliances Market Segmentation
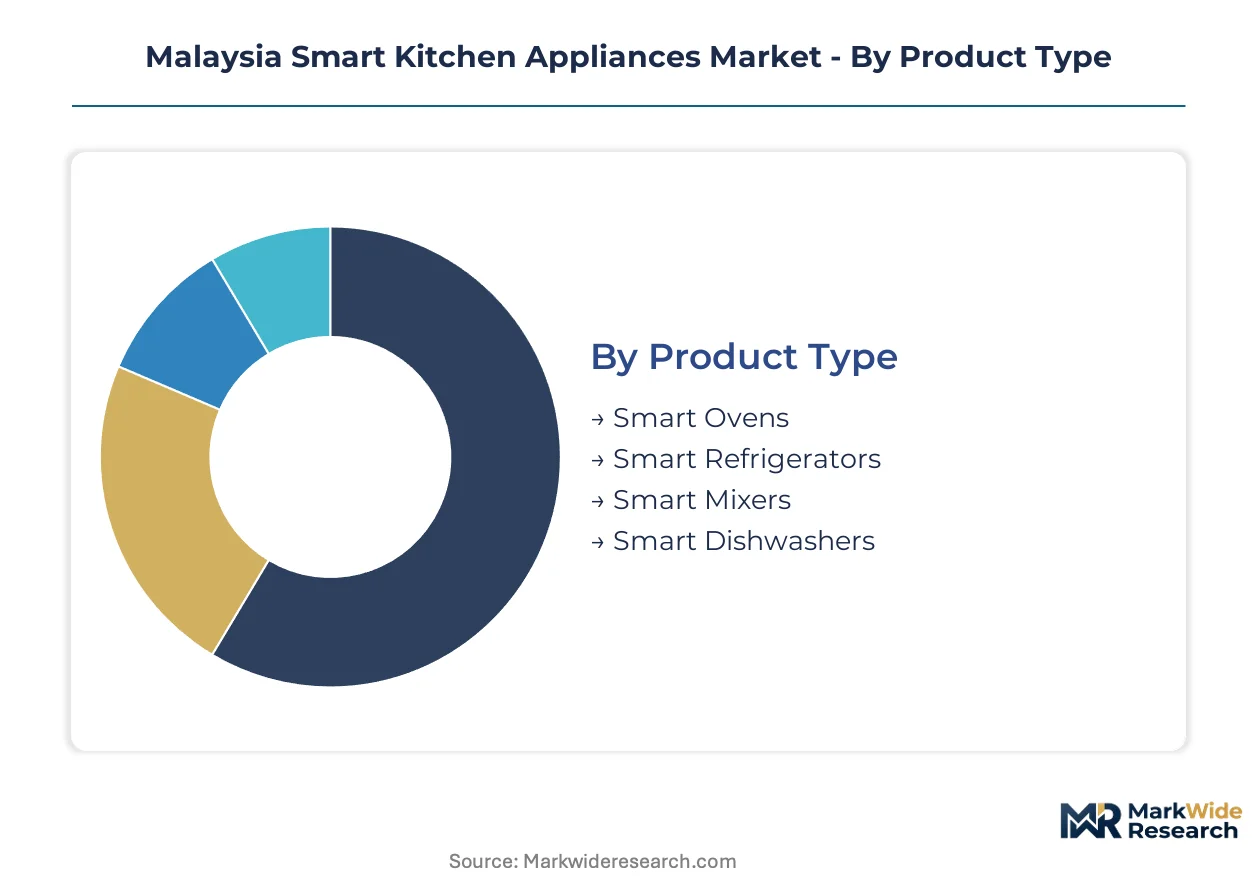
Smart kitchen appliance segmentation in Malaysia reveals divergent commercial logics between developer-specified bulk procurement and consumer-direct retail channels. Understanding these splits enables vendors to align certification investments, channel partnerships, and feature roadmaps with actual purchase decision-makers rather than assumed end-users.
Product Type:
Volume concentration sits with refrigeration and cooking platforms, while premium positioning clusters around integrated inventory management and precision thermal control systems.
- Smart Ovens:Programmable thermal chambers with embedded sensor arrays enable remote preheating, recipe-guided cooking cycles, and energy-optimized heating element modulation. Developer specifications in Cyberjaya and Mont Kiara residential towers increasingly mandate connected oven packages as standard fit-outs, compressing traditional retail showroom influence.
- Smart Refrigerators:Variable compressor units with internal cameras, barcode scanners, and adaptive cooling algorithms command sustained margin pools through demonstrable electricity savings validated under SEDA energy efficiency labeling. Hospitality procurement teams standardize these across central kitchen facilities in Kuala Lumpur hotel chains.
- Smart Mixers:Motorized food preparation devices with load-sensing speed control and app-connected recipe libraries serve residential efficiency goals in Selangor urban households.
- Smart Dishwashers:Connected cleaning units with soil-sensing wash cycles and remote start functionality address commercial kitchen labor reduction requirements in Penang food service operations.
Mature deployment sits with Smart Refrigerators. Newer deployment is concentrated in Smart Ovens.
Technology:
Connectivity architecture choices determine firmware development costs, cloud infrastructure requirements, and vulnerability to protocol obsolescence.
- IoT-Enabled:Full-stack connected appliances with proprietary cloud backends, edge computing capabilities, and over-the-air firmware update mechanisms. SIRIM electromagnetic compatibility testing creates compliance barriers that filter low-quality imports from regional suppliers lacking certified portfolios.
- Wi-Fi Connectivity:IP-based wireless communication enabling remote monitoring and control through residential broadband infrastructure. Heavy reliance on this single protocol creates stranded asset exposure for installed bases if interoperability mandates shift toward Matter standardization.
- Bluetooth:Short-range wireless pairing for localized smartphone control without internet dependency, appealing to data-privacy-conscious households in Johor Bahru corridor.
- Voice Control:Natural language processing interfaces enabling hands-free operation, with Bahasa Malaysia localization opening differentiation for software stacks targeting younger demographics in Selangor and Johor.
Established penetration sits with Wi-Fi Connectivity. Steepest expansion trajectory belongs to Voice Control.
End User:
Purchase scale and decision velocity vary sharply between individual household procurement and institutional specification processes.
- Residential:Individual household purchasers selecting connected appliances through retail channels or developer-included packages. Klang Valley corridor concentration drives demand clustering around Cyberjaya and Mont Kiara smart home integration services.
- Commercial:Independent restaurants, cafés, and food processing operations seeking labor reduction through automated cooking and cleaning equipment. Copper and semiconductor input volatility compresses manufacturing margins on entry-tier products targeting this price-sensitive segment.
- Hospitality:Hotel chains and resort operators standardizing connected galley equipment across new property rollouts, demonstrating concentrated procurement scale with extended warranty service agreements.
- Institutional:Government facilities, educational institutions, and healthcare food service operations with formal tender processes and extended replacement cycles.
Volume concentration sits with Residential. Procurement discipline is tightest in Hospitality.
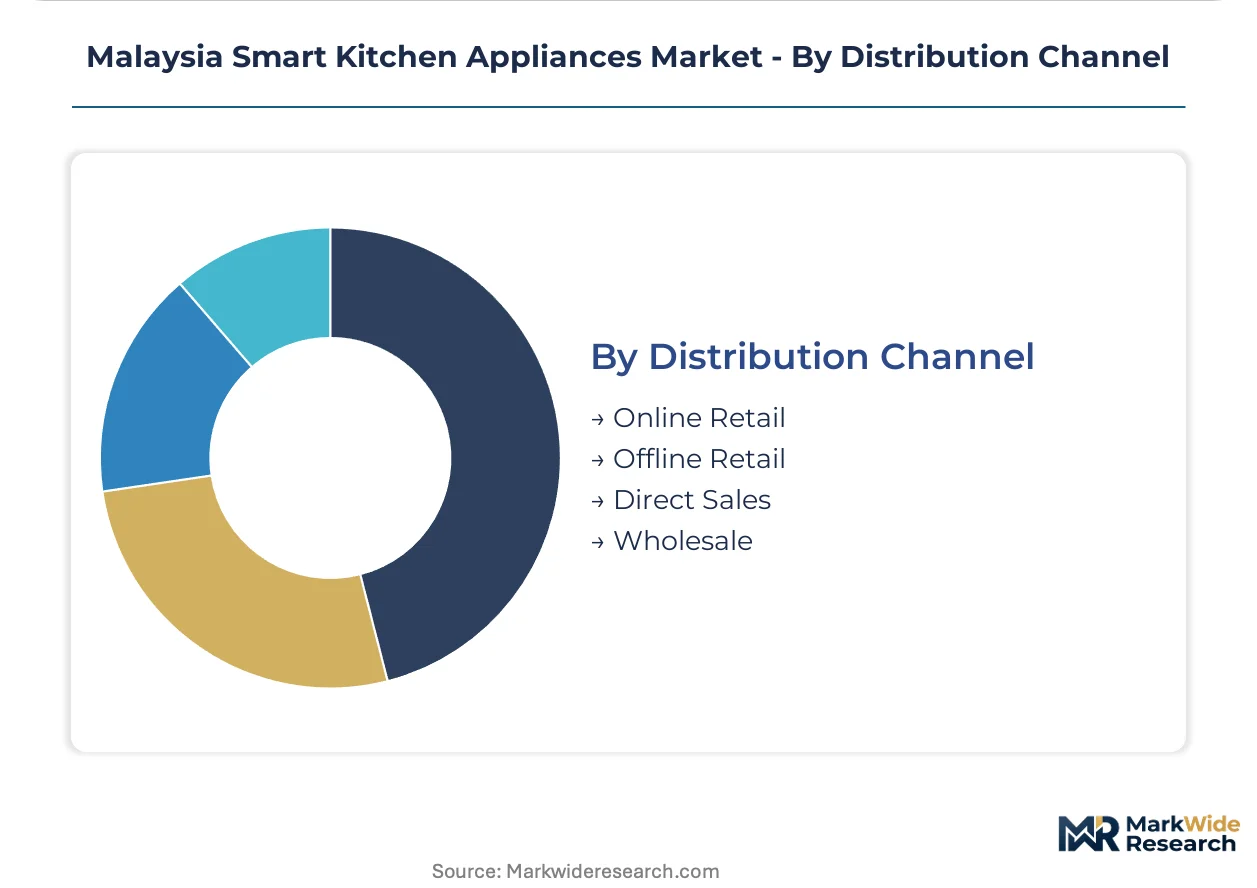
Distribution Channel:
Channel selection determines working capital intensity, certification documentation requirements, and post-sale service obligation scope.
- Online Retail:E-commerce platforms enabling direct-to-consumer sales with digital specification comparison and doorstep delivery. Xiaomi Malaysia leverages this channel for ecosystem bundling into budget-conscious urban households.
- Offline Retail:Physical showrooms with tactile product demonstration and immediate fulfillment, where Electrolux Malaysia anchors high-end positioning through specialist retail channels with Nordic design differentiation.
- Direct Sales:Manufacturer-to-developer relationships for bulk fit-out procurement, displacing traditional retail showroom selection in premium residential segments.
- Wholesale:Distributor-mediated volume sales to contractors and project developers with standardized specifications and consolidated logistics.
Margin protection is strongest in Direct Sales. Volume expansion is fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Klang Valley corridor anchors Malaysia's smart kitchen appliance demand concentration, with Cyberjaya and Mont Kiara housing the densest clusters of smart home integration services and developer-specified fit-out activity.
Selangor
Voice control interfaces and IoT-enabled cooking platforms drive adoption among younger demographics in urban Selangor households. SIRIM QAS International certification requirements filter low-quality imports while protecting established suppliers with compliant portfolios. Shah Alam and Petaling Jaya host specialist retail channels where Nordic design positioning commands premium positioning.
Kuala Lumpur
High-rise residential towers in the capital standardize connected appliance packages as default fit-outs, embedding smart kitchen infrastructure before occupant move-in. The Energy Commission enforces minimum energy performance standards that shape procurement specifications for developer-direct channels. Mont Kiara and Bangsar South concentrate property management firms bundling extended warranty service agreements into design-and-build contracts.
Penang
Commercial food service operations in George Town seek labor reduction through automated cleaning and cooking equipment with soil-sensing wash cycles. SEDA energy efficiency labeling creates regulatory tailwinds for connected appliances with superior MEPS ratings. Bayan Lepas industrial zones support component sourcing for regional smart refrigerator production.
Johor
Cross-border commuter households adjacent to Singapore generate underpenetrated demand for ecosystem bundlers targeting budget-conscious urban purchasers. The Malaysia Digital Economy Blueprint data governance guidelines reshape cloud-connected inventory architectures for privacy-conscious buyers. Johor Bahru corridor expansion offers whitespace for localized software stacks with Bahasa Malaysia natural language processing.
Malaysia Smart Kitchen Appliances Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification compliance and ecosystem integration capabilities. The vendor base organizes around three strategic archetypes: Nordic design specialists anchoring high-end specialist retail, manufacturing-scale operators sustaining cost advantages in refrigeration production, and ecosystem bundlers extending IoT platforms into budget households. Dominant competitive moves include developer-direct bulk procurement partnerships and Matter protocol certification adoption to reduce SKU complexity.
Among Malaysia-based operations, Electrolux Malaysia and Haier Malaysia occupy positions at opposing margin tiers, while Xiaomi Malaysia exemplifies the ecosystem-bundler archetype targeting online retail expansion. These three entities represent the structural segmentation between specification-driven bulk channels and consumer-direct digital sales.
| Leading Market Players |
|---|
| Electrolux Malaysia |
| Haier Malaysia |
| Panasonic Malaysia |
| Teka Malaysia |
| Rinnai Malaysia |
| Samsung Malaysia |
| Bosch Malaysia |
| Xiaomi Malaysia |
| LG Electronics Malaysia |
| Others |
Value Chain & Pricing Dynamics
Copper winding and semiconductor chipsets move from commodity exchanges through compressor motor assemblies to finished smart refrigerators, with SIRIM certification costs layering onto landed costs before final pricing to developer-direct buyers in Kuala Lumpur residential towers.
Pricing Analysis
Energy savings validated under SEDA labeling anchor value-based pricing for variable compressor refrigeration units, with three-tier pricing structure across premium connected suites, mid-market Wi-Fi-enabled models, and entry-level Bluetooth alternatives. Certification grade and after-sales service bundling drive price differentiation between Electrolux Malaysia's Nordic design positioning and Xiaomi Malaysia's ecosystem penetration. Cost compression in entry-tier products is intensifying because copper and semiconductor input volatility compresses manufacturing margins. Commercial food service operations in Penang demonstrate highest price sensitivity, while hospitality procurement teams in Kuala Lumpur hotel chains show lowest sensitivity due to extended warranty service agreements.
Supply Chain Analysis
Direct-to-developer channels handle bulk fit-out procurement for high-rise residential towers, while online retail platforms serve individual household purchasers. Manufacturing draws from China for IoT chipsets and compressor motors, South Korea for display panels and sensor arrays, and domestic Bayan Lepas zones for final assembly. Raw material dependencies center on copper for motor windings, rare earth elements for magnetic components, and silicon substrates for semiconductor fabrication. Single-source vulnerability in Wi-Fi protocol chipsets creates stranded asset exposure if interoperability mandates shift toward Matter standardization. Distribution runs through specialist retail channels in Shah Alam, direct sales to property management firms in Mont Kiara, and e-commerce platforms targeting Selangor urban households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SIRIM certification queue compression and embedded systems firmware talent scarcity constrain capacity expansion, propping pricing power for certified suppliers with compliant portfolios and established developer relationships.
For Market Incumbents: Deploy backward integration into compressor motor production to insulate margin structures from copper price volatility and semiconductor supply shocks. Anchor channel control through exclusive design-and-build partnerships with Cyberjaya and Mont Kiara property management firms, locking out ecosystem bundlers targeting budget-conscious segments. Certification investment in Matter protocol compatibility protects installed base investments against interoperability mandate shifts. For New Entrants and Emerging Players: E-commerce platform partnerships offer the lowest-friction route to Selangor and Johor Bahru households, bypassing SIRIM certification timeline strain through white-label arrangements with established manufacturers. Target the Johor corridor's underpenetrated cross-border commuter demand with Bahasa Malaysia voice-AI localization as the primary go-to-market angle, differentiating against Wi-Fi-centric incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated refrigeration specialists with captive compressor production in southern peninsula states, where logistics proximity to Singapore supports regional hub economics. Long-term viability hinges on regulatory compliance infrastructure and developer-direct relationship depth rather than retail brand recognition. Monitor SIRIM electromagnetic compatibility testing queue lengths as the inflection indicator for working capital strain among seasonal product introducers.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Reduces SKU complexity for appliance manufacturers adopting unified interoperability frameworks across retail channels. |
| Developer-Direct Bulk Procurement | Displaces traditional retail showroom influence in Mont Kiara and Cyberjaya high-rise fit-out specifications. |
| Backward Integration into Compressor Production | Insulates margin structures from copper and semiconductor input volatility affecting entry-tier manufacturing. |
| Bahasa Malaysia Voice-AI Localization | Opens differentiation for software stacks targeting younger demographics in Selangor and Johor urban households. |
| On-Premise Edge Computing Deployment | Addresses hospitality chain demands for data residency compliance under Malaysia Digital Economy Blueprint guidelines. |
Study Parameters
Independent corroboration across appliance manufacturer product managers, SIRIM QAS certification officers, property development procurement leads, and hospitality chain facility directors underwrites the qualitative findings. Primary interviews with smart home integration specialists in Cyberjaya and retail channel partners in Shah Alam combined with secondary validation from SEDA energy efficiency labeling databases, SIRIM electromagnetic compatibility test records, and developer fit-out specification documents. Bottom-up triangulation across product-type volume estimates and top-down reconciliation against corridor-level demand concentration ensures analytical consistency.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon, with analytical framework modeling product type, connectivity technology, end-user segment, and distribution channel dimensions. CAGRs derive from fitted growth curves calibrated to developer specification timelines and retail adoption patterns. Industry-specific forecast inputs incorporate SIRIM certification queue dynamics and copper price trajectory assumptions from commodity exchange data.
The model holds under stable SEDA incentive structures and sustained high-rise residential development in Klang Valley; deviation in SIRIM regulatory stringency or interoperability mandate timing would shift volume trajectories. Forecasts reflect documented assumptions about firmware talent availability and semiconductor supply normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
South Korea Kitchen Appliances Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
Household Bread Machine Market
Kitchen Appliances
France Cookware Market
Kitchen Appliances
India Electric Vegetable Choppers Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
US Household Coffee Machine Market
Kitchen Appliances
Ceramic Coated Cookware Market
Kitchen Appliances
Outdoor Kitchen Appliances Market
Kitchen Appliances
Cooktop Market
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
Bakeware Market