
 Household Kitchen Appliances Market | 2026-2036
Household Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Household Kitchen Appliances Market Insights
A widening capital-intensity gap between foundry-scale manufacturers and niche assemblers is reorganizing competitive tiers in household kitchen appliances. Whirlpool leverages captive metal-stamping and compressor production to sustain margin control across North American supply chains. Bosch differentiates through in-house induction coil fabrication and precision drive systems, while Electrolux anchors European distribution through direct retail partnerships and regional fulfillment nodes.
Household kitchen appliances comprise electromechanical devices designed for food preservation, thermal processing, and surface cleaning within residential environments, typically operating at 110–240 volts with sealed refrigerant loops or resistive heating elements rated between 1,000 and 15,000 watts. Refrigerators and dishwashers occupy the largest installed base, though smart appliances represent the fastest-expanding margin pool as connectivity modules and sensor arrays command premium positioning. Energy-efficient appliances face compressed margins in mature markets where regulatory baselines have narrowed differentiation, while induction technology gains share in professional and enthusiast segments seeking precision thermal control.
The EU Ecodesign Directive and REACH chemical standards constrain material selection and refrigerant chemistry for products entering European markets, while the US Department of Energy certification thresholds shape minimum efficiency benchmarks for domestic sales. China's GB standards and NMPA-equivalent quality markings govern import access and local manufacturing compliance. Stakeholders must monitor divergence between regional efficiency timelines and refrigerant phase-down schedules to avoid stranded inventory and compliance gaps.
Market Dynamics
The EU Ecodesign Directive's refrigerant phase-down mandates and the F-Gas Regulation are compressing replacement cycles across European markets while forcing manufacturers to redesign compressor architectures and insulation chemistries ahead of 2030 compliance deadlines.
Growth Catalysts
- Urban housing stock renewal:China, India, and the United States are seeing middle-class households replace aging refrigeration and cooking equipment as residential construction accelerates in tier-two cities and suburban corridors.
- REACH chemical standards:European regulatory pressure on refrigerant chemistry and flame-retardant materials is creating first-mover advantages for suppliers with pre-certified component portfolios.
- Sensor-integrated cooking:Precision thermal control modules and connectivity arrays are commanding premium positioning in professional and enthusiast kitchen segments seeking programmable automation.
Market Restraints
- Copper and rare-earth magnet volatility:Compressor motor laminations and induction coil substrates face input cost swings that compress margin predictability for mid-scale assemblers lacking captive metal supply.
- Foundry-scale concentration:Refrigeration compressor production clusters among three dominant suppliers, creating single-source vulnerability for niche brands without backward integration into sealed-system manufacturing.
- Refrigerant chemistry lock-in:Existing installed bases of R-134a and R-410A systems create technical barriers to retrofitting next-generation low-GWP alternatives without full appliance replacement.
Strategic Opportunities
- India's PLI scheme for white goods:Component-level incentives for compressor and motor manufacturing are attracting capital toward domestic production hubs serving South Asian demand.
- Induction-oven convergence:Hybrid appliances combining precision magnetic heating with convection airflow are opening specification wins in compact urban kitchens where footprint constraints dominate.
- Direct-to-installer channels:Bypassing traditional retail through contractor and builder networks reduces working capital intensity while capturing specification authority in new construction.
Industry Challenges
- Refrigerant handling certification:Technician licensing requirements under the F-Gas Regulation and EPA Section 608 are constraining service network expansion and extending repair timelines.
- Legacy control system integration:Smart appliance connectivity modules must interoperate with decade-old residential electrical infrastructure and fragmented home automation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Kitchen Appliances Market |
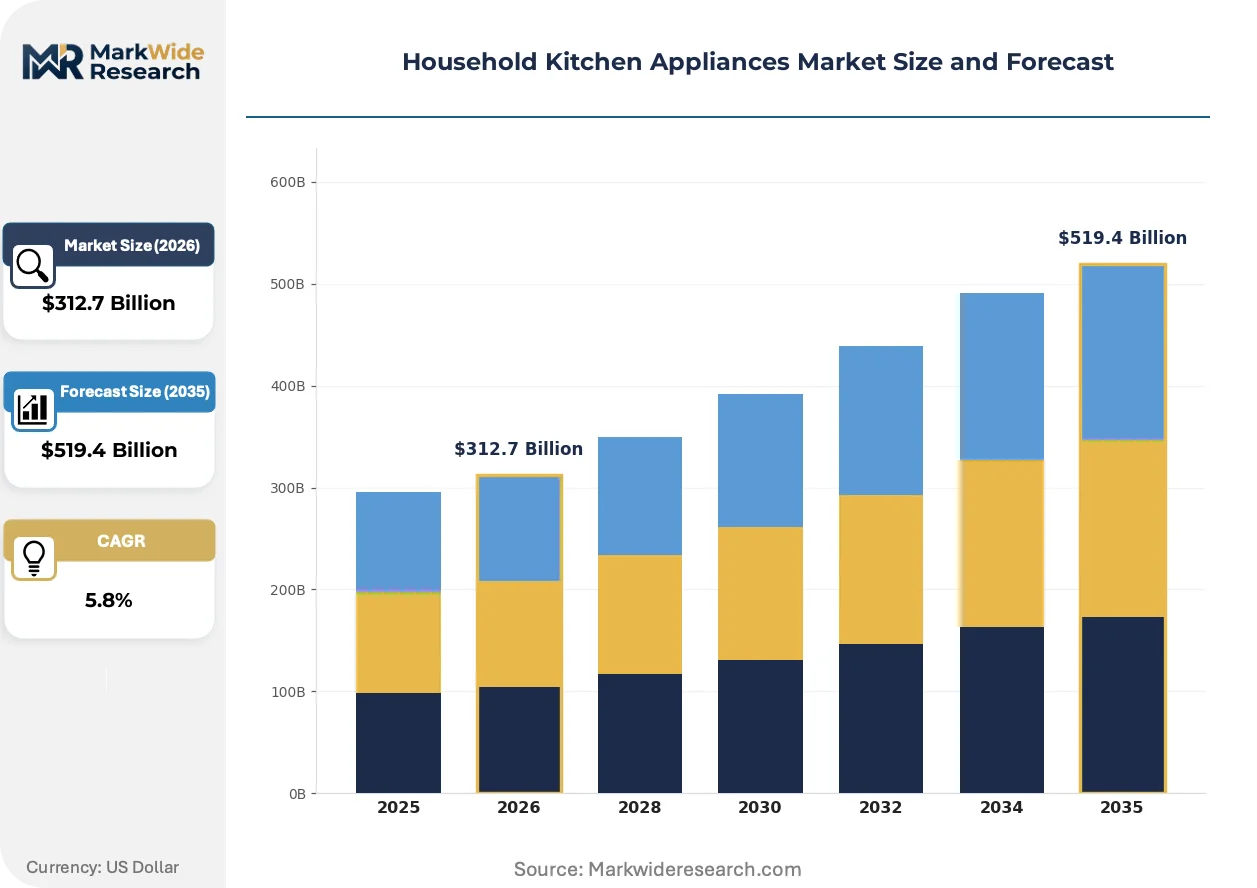
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $519.4 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Microwaves, Dishwashers Technology: Smart Appliances, Energy-Efficient Appliances, Conventional Appliances, Induction Technology End User: Residential Users, Professional Chefs, Cooking Enthusiasts, Rental Properties Distribution Channel: Online Retailers, Appliance Stores, Warehouse Clubs, Specialty Outlets |
| Companies Covered | Whirlpool, ZLINE Kitchen and Bath, Bosch, Electrolux, Miele, LG, GE, KitchenAid, Samsung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Kitchen Appliances Market Trends and Innovations
Refrigeration and cooking equipment architectures are fragmenting as modular component designs, regulatory chemistry mandates, and channel restructuring reshape how appliances are specified, assembled, and distributed.
Solid-state cooling based on thermoelectric arrays and magnetocaloric materials is decomposing the traditional vapor-compression paradigm in compact refrigeration segments. Premium wine storage and medical-grade residential units are adopting these systems to eliminate refrigerant compliance burdens entirely. The structural consequence is a bifurcation where large-capacity food preservation remains compressor-dependent while specialty cooling migrates to refrigerant-free alternatives.
The EU F-Gas Regulation's phasedown schedule is forcing refrigerant transitions toward R-600a and R-290 hydrocarbons with flammability classifications requiring redesigned safety systems. Appliance manufacturers are reengineering electrical enclosures and ventilation architectures to meet ATEX-equivalent ignition protection standards. European markets are absorbing these costs fastest, with Asian export facilities retooling to maintain market access.
Builder and developer procurement is consolidating specification authority away from retail showrooms toward centralized purchasing departments at major residential construction firms. Direct vendor relationships with Lennar, Taylor Morrison, and DR Horton are displacing traditional distributor networks in North American new-build segments. This channel shift is most visible in the United States, where multifamily housing starts concentrate demand among fewer decision-makers.
Household Kitchen Appliances Market Segmentation
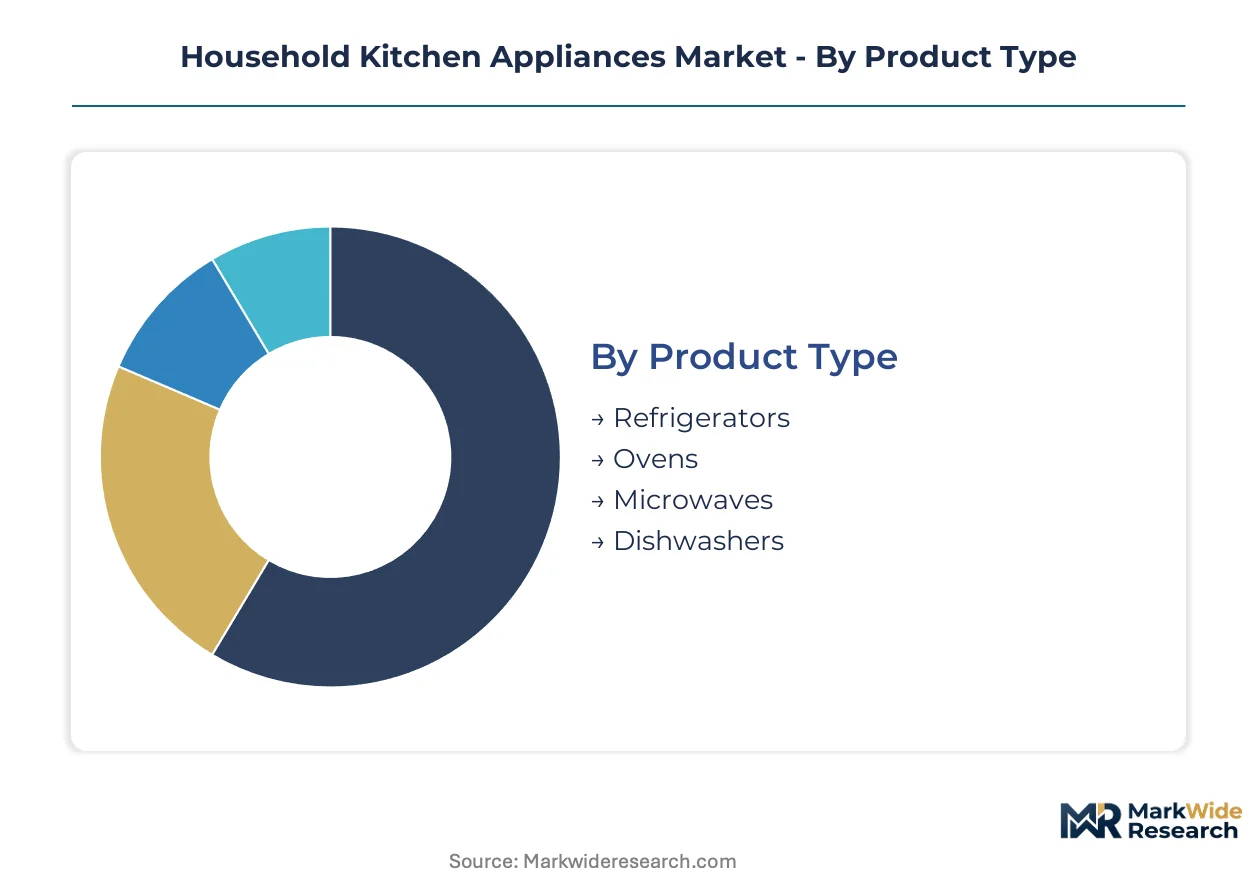
Margin concentration in household kitchen appliances diverges sharply across product architectures and connectivity tiers. Segment boundaries are blurring as induction modules integrate into conventional cooking platforms and smart sensor arrays penetrate mid-market price bands.
Product Type:
Premium positioning concentrates in built-in refrigeration and convection oven configurations, while freestanding units compete on replacement-cycle velocity and energy-label differentiation.
- Refrigerators:Sealed vapor-compression systems with hydrocarbon refrigerant transitions dominate installed base economics. Demand clusters in China and India where housing stock renewal and middle-class expansion accelerate turnover of aging R-134a units.
- Ovens:Thermal processing equipment spans resistive heating, convection airflow, and hybrid induction-convection architectures. European markets under Ecodesign Directive pressure are rotating toward precision thermal control modules that command specification wins in compact urban kitchens.
- Microwaves:Magnetron-based units face margin compression as solid-state RF heating emerges in premium segments.
- Dishwashers:Water-recirculation and soil-sensor systems anchor replacement demand in North American suburban corridors.
Refrigerators hold installed capacity. Ovens are rotating up the share rankings.
Technology:
Cost tier stratification separates refrigerant-dependent legacy platforms from refrigerant-free solid-state alternatives and connected ecosystems with recurring software revenue potential.
- Smart Appliances:Wi-Fi-enabled control modules and sensor arrays integrate with home automation protocols. Professional chefs and cooking enthusiasts in the United States drive specification authority for programmable automation and remote thermal monitoring.
- Energy-Efficient Appliances:EU Ecodesign Directive compliance thresholds and DOE certification benchmarks define minimum viable efficiency ratings. China and India are absorbing these standards fastest as GB standards converge with international baselines.
- Conventional Appliances:Electromechanical controls and non-connected resistive heating maintain volume leadership in rental property segments.
- Induction Technology:Magnetic field heating eliminates thermal lag and enables precision power modulation.
Conventional appliances hold installed capacity. Smart appliances are climbing the fastest.
End User:
Application intensity varies from daily residential cycling to commercial-grade throughput demands, with specification authority concentrating in professional and developer procurement channels.
- Residential Users:Standard 110–240 volt electromechanical devices serve food preservation and surface cleaning needs across single-family and multifamily housing. Replacement cycles in the United States are compressing as DOE efficiency mandates accelerate obsolescence of pre-2010 refrigeration stock.
- Professional Chefs:Precision thermal control and rapid recovery specifications dominate equipment selection. European markets under F-Gas Regulation pressure are rotating toward hydrocarbon-compatible compressor architectures and induction coil systems.
- Cooking Enthusiasts:Enthusiast segments seek programmable automation and connectivity integration.
- Rental Properties:Durability and service network density outweigh premium feature penetration.
Residential users hold installed capacity. Professional chefs are rotating up the share rankings.
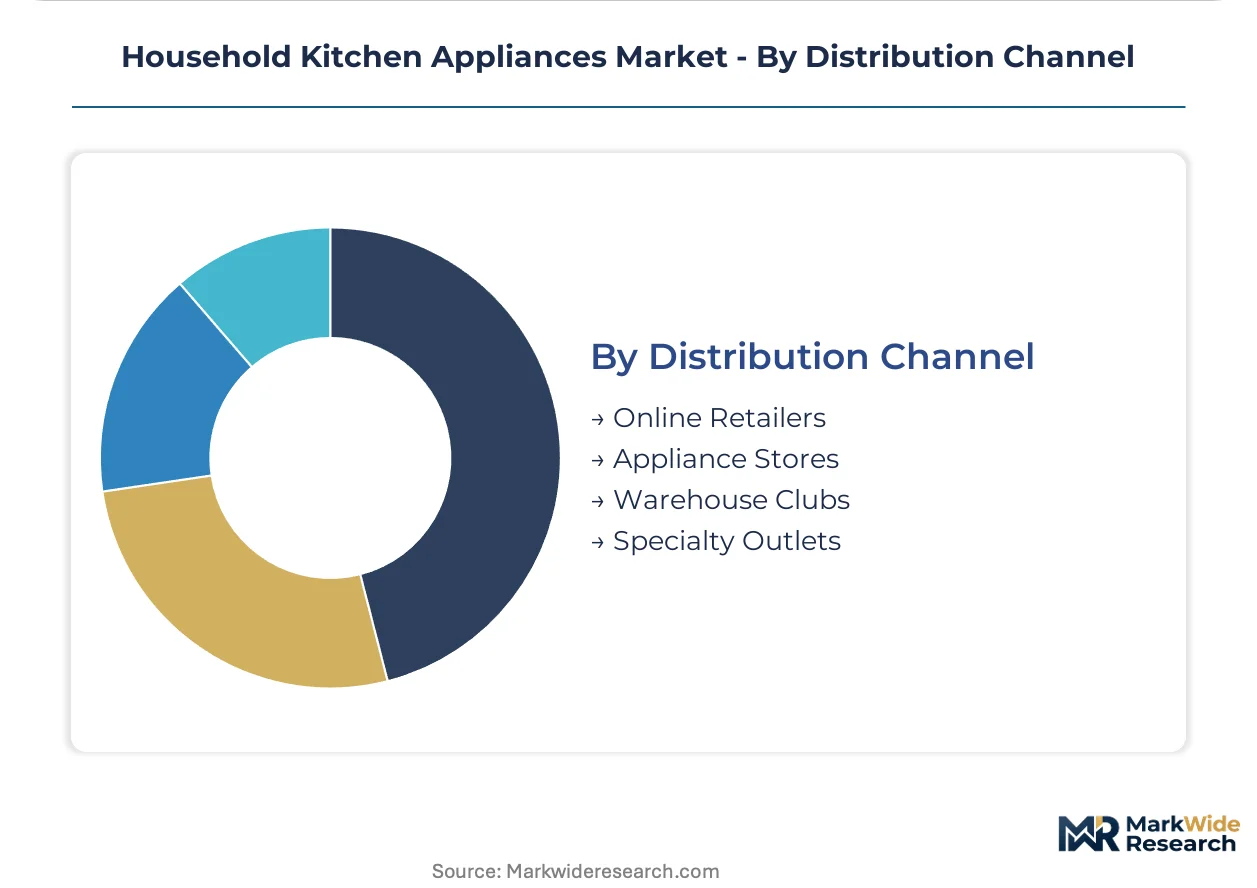
Distribution Channel:
Customer type fragmentation separates specification-driven builder procurement from transactional retail replacement and digital-native convenience purchasing.
- Online Retailers:Direct-to-consumer platforms with logistics integration capture replacement demand in suburban corridors. India and China are absorbing these channels fastest as domestic e-commerce infrastructure matures.
- Appliance Stores:Physical showrooms with installation and service bundling anchor mid-market appliance turnover. United States suburban markets maintain density advantages for regional retail chains.
- Warehouse Clubs:Volume purchasing agreements with national brands serve membership-based replacement cycles.
- Specialty Outlets:Premium positioning and specification authority concentrate in professional kitchen supply networks.
Appliance stores hold installed capacity. Online retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European markets under regulatory compression, while volume expansion tilts toward Asian manufacturing hubs serving cost-sensitive replacement cycles. This asymmetry shapes capital allocation across foundry networks and distribution infrastructure.
United States
Suburban housing starts and multifamily construction in Sun Belt corridors drive dishwasher and refrigerator turnover. DOE certification thresholds accelerate obsolescence of pre-2010 refrigeration stock. Builder procurement consolidation at Lennar and DR Horton in Florida and Texas displaces traditional retail channels.
China
Tier-two city housing renewal and middle-class appliance upgrading sustain compressor demand in Yangtze River Delta manufacturing clusters. GB standards convergence with international efficiency baselines tightens import compliance. Ningbo and Shunde production hubs retool for hydrocarbon refrigerant transitions under MEE oversight.
Germany
EU Ecodesign Directive mandates compress replacement cycles for induction cooking platforms and sealed refrigeration systems. REACH chemical standards constrain flame-retardant material selection. Bavarian engineering centers around Munich anchor precision drive system fabrication for premium appliance tiers.
India
PLI scheme incentives for compressor and motor manufacturing attract capital toward Gujarat and Tamil Nadu production hubs. BIS quality markings govern local assembly compliance. Mumbai and Delhi-NCR distribution networks absorb fastest e-commerce channel growth for replacement appliance sales.
Japan
Compact urban kitchen footprints sustain demand for hybrid induction-convection appliances. METI efficiency standards shape minimum viable product specifications. Osaka and Nagoya industrial corridors concentrate sensor-integrated cooking module development for enthusiast segments.
Household Kitchen Appliances Market Competitive Landscape
Concentration sits with diversified electromechanical conglomerates controlling captive component supply and regional distribution networks. Foundry-scale refrigeration compressor manufacturing clusters among three dominant suppliers, creating single-source vulnerability for niche assemblers. Strategic archetypes separate backward-integrated metal stampers, in-house induction coil fabricators, and direct retail partnership operators. Competitive moves center on M&A for regional distribution access and capacity expansion in South Asian manufacturing zones.
Among diversified appliance manufacturers, Whirlpool, Bosch, and Electrolux occupy positions across distinct competitive vectors. Whirlpool exemplifies the vertically integrated archetype through captive metal-stamping and compressor production. Bosch represents precision component fabrication with in-house induction coil and drive system manufacturing. Electrolux anchors European distribution architecture through direct retail partnerships and regional fulfillment nodes.
| Leading Market Players |
|---|
| Whirlpool |
| ZLINE Kitchen and Bath |
| Bosch |
| Electrolux |
| Miele |
| LG |
| GE |
| KitchenAid |
| Samsung |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day compressor lead times from Yangtze River Delta foundries concentrate pricing power among backward-integrated manufacturers with captive metal-stamping capacity, while spot-market copper and rare-earth magnet exposure compresses margin predictability for niche assemblers lacking upstream control.
Pricing Analysis
Configured-to-order built-in refrigeration commands 40-60% premiums over standard freestanding units, with three-tier pricing structure across premium, standard, and economy levels anchored by energy-label certification tiers and after-sales service bundling. Price differentiation stems from EU Ecodesign Directive compliance grades and brand equity in European markets. Cost compression in mid-market induction modules is intensifying because magnetron-to-solid-state RF transitions require retooling investments. Rental property buyers exhibit highest price sensitivity, while professional chef segments prioritize precision thermal control over unit economics.
Supply Chain Analysis
Yangtze River Delta compressor foundries and Ningbo metal-stamping clusters constitute the dominant chokepoint, with South Korean motor lamination suppliers and German precision drive fabricators providing secondary concentration nodes. Refrigeration compressor production draws from copper winding wire, rare-earth permanent magnets, and hydrocarbon refrigerant chemistry. Single-source vulnerability pervades sealed-system manufacturing where three dominant suppliers control global capacity. Distribution runs through direct-to-installer channels at Lennar and DR Horton for North American new-build segments, alongside appliance store networks for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive compressor fabrication capability separates margin-sustainable manufacturers from assembly-dependent competitors, with F-Gas Regulation compliance timelines and hydrocarbon refrigerant transitions defining the critical asset gap for European market access.
For Market Incumbents: Shield margin structures by deepening backward integration into rare-earth magnet supply through offtake agreements with Australian and Vietnamese mining operations. Compress foundry-scale concentration vulnerability by acquiring regional metal-stamping capacity in Gujarat and Tamil Nadu production hubs ahead of India's PLI scheme incentive windows. Prioritize ATEX-equivalent ignition protection certification for hydrocarbon-compatible architectures. For New Entrants and Emerging Players: Differentiate on solid-state thermoelectric cooling modules for premium wine storage and medical-grade residential segments where refrigerant compliance burdens drive specification shifts. Target India's tier-two city housing renewal corridors through e-commerce platform partnerships with Flipkart and Amazon India. Penetrate professional chef equipment specifications via direct-to-installer channels bypassing traditional retail working capital intensity. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Ecodesign Directive and F-Gas Regulation phase-down schedules create stranded-inventory risk for non-compliant legacy portfolios while rewarding pre-certified component portfolios. Acquisition targets should exhibit captive induction coil fabrication or precision drive system manufacturing. Monitor divergence between regional refrigerant phase-down timelines and compressor inventory positioning as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive sealed-system production insulates margin control against foundry-scale concentration among dominant suppliers. |
| Hydrocarbon Refrigerant Architecture Redesign | ATEX-equivalent ignition protection systems unlock European market access under F-Gas Regulation compliance deadlines. |
| Direct-to-Installer Channel Development | Bypassing retail through Lennar and DR Horton procurement networks reduces working capital intensity in Sun Belt construction corridors. |
| Solid-State Cooling Module Commercialization | Thermoelectric arrays eliminate refrigerant chemistry compliance burdens in premium wine storage and medical-grade segments. |
| India PLI Scheme Capacity Positioning | Gujarat and Tamil Nadu production hubs capture component-level incentives for compressor and motor manufacturing serving South Asian demand. |
Research Methodology
A standing panel of appliance manufacturing executives, procurement leads at major residential construction firms, compressor foundry operations managers, and channel distribution heads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through SEC 10-K filings, EU Ecodesign Directive regulatory databases, customs and trade data from China and India, and GB standards documentation. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value estimates.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework segmented by product architecture, connectivity tier, refrigerant chemistry compliance status, and procurement channel authority. CAGRs were derived from replacement-cycle velocity modeling, housing stock renewal rates, and regulatory compliance deadline impacts. Forecast inputs incorporated compressor manufacturing capacity utilization, copper and rare-earth magnet price trajectories, and builder procurement consolidation trends.
Material uncertainties — refrigerant phase-down schedule acceleration, rare-earth export restriction imposition, and housing construction cyclicality — sit outside the modeled envelope. Forecasts reflect documented assumptions about middle-class expansion trajectories and regulatory convergence timelines. Practitioners should keep alternative scenarios live as EU-Asia regulatory divergence and supply chain regionalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market
Kitchen Appliances
Colombia Kitchen Appliances Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
Asia Pacific Induction Hobs Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Residential Induction Cooktops Market