
 Electric Hobs Market | 2026-2036
Electric Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Hobs Market Foresight
Commercial kitchen operators is bifurcating from residential buyers as the faster-growing demand archetype across the electric hobs landscape. BSH Home Appliances Group leverages its vertical integration into component manufacturing to command premium positioning in European project channels. Electrolux AB anchors its competitiveness through specialized fabrication lines serving high-turnover hospitality accounts. Whirlpool Corporation sustains broad distribution density across North American replacement cycles.
Electric hobs are flat-surface cooking appliances that convert electrical energy into heat through induction coils, radiant elements, or halogen lamps, typically operating at power ratings between 1.2 kW and 3.7 kW per zone to deliver precise temperature control for commercial and residential food preparation. Induction technology leads the product type hierarchy on energy efficiency metrics, while smart technology integration across touch control and multi-zone configurations captures the fastest expansion in margin pools. The capacity dimension tilts toward multi-burner formats in hospitality procurement, whereas single and double burner units dominate residential retrofit demand.
The EU Ecodesign Directive and REACH frameworks in Europe, alongside DOE appliance standards enforced by US regulators, progressively tighten allowable standby power and material composition thresholds for cooking equipment. These efficiency mandates directly shift procurement specifications toward induction platforms and constrain market access for legacy coil-element designs. Stakeholders must monitor regulatory harmonization between efficiency standards and circular economy material recovery requirements as the decisive pivot point for product portfolio allocation.
Market Dynamics
EU Ecodesign regulations are compressing the viable product architecture for electric hobs toward induction-only platforms, eliminating radiant and coil-element alternatives from new construction specifications across member states.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency thresholds for cooking appliances in Germany and France are accelerating gas-to-electric retrofit cycles in residential buildings.
- Induction coil technology:Energy conversion efficiency above 90% is capturing specification share from legacy radiant elements in commercial kitchen procurement.
- Western European retrofit demand:Building energy renovation subsidies in France and Italy are channeling replacement spending toward electric hobs.
Market Restraints
- Copper and ferrite magnet cost volatility:Input price swings for induction coil materials are compressing margin stability for mid-tier manufacturers.
- Power grid capacity constraints:Residential electrical infrastructure in older UK and German buildings limits simultaneous multi-zone induction operation without panel upgrades.
- Gas cooking substitution inertia:Established chef preferences for flame-based heat control in Southern European hospitality segments slow platform switching.
Strategic Opportunities
- Smart home integration:WiFi-enabled hobs with app-based energy monitoring are opening premium positioning in Netherlands and Scandinavian new-build residential markets.
- Commercial hospitality electrification:Hotel and restaurant chains in Spain and Portugal face mounting pressure to eliminate on-site gas infrastructure for insurance and safety compliance.
- EU Green Deal renovation wave:National building decarbonization targets are expanding subsidy pools for appliance replacement in Poland and Czech Republic.
Industry Challenges
- Electromagnetic compatibility certification:CE marking requirements for interference suppression are extending product development timelines by 4-6 months for new induction platforms.
- Installation skill scarcity:Qualified electricians capable of high-amperage circuit upgrades are concentrated in urban centers, creating service bottlenecks in rural retrofit markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Hobs Market |
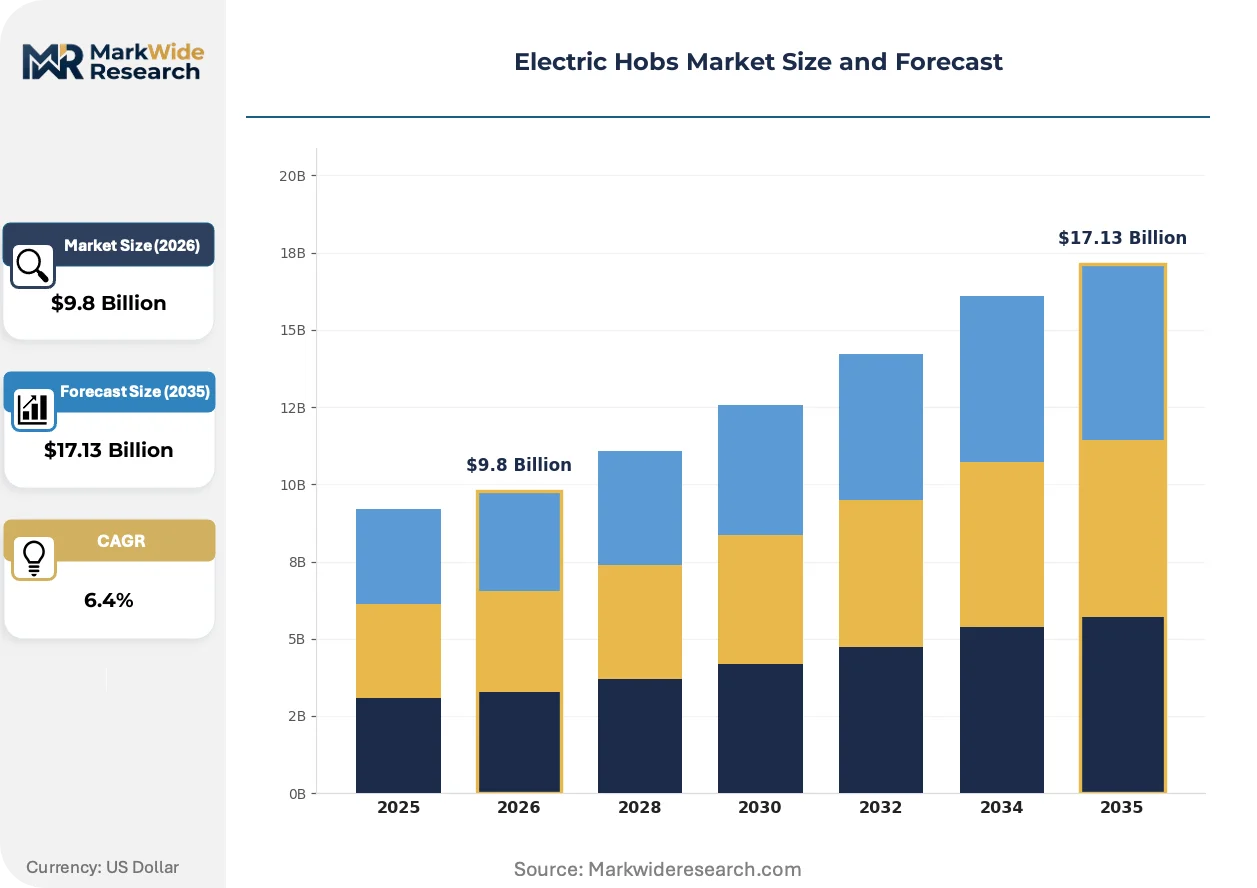
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction, Radiant, Halogen, Coil Technology: Smart Technology, Touch Control, Timer, Multi-Zone End User: Residential, Commercial, Hospitality, Catering Capacity: Single Burner, Double Burner, Triple Burner, Multi-Burner |
| Companies Covered | BSH Home Appliances Group, Robert Bosch GmbH, Whirlpool Corporation, Miele & Cie. KG, Haier Group Corporation, Electrolux AB, Samsung Electronics Co., Ltd, SMEG S.p.A., LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Hobs Market Shifts & Advancements
Technology convergence between cooking appliances and building energy management systems is redefining product value propositions, with connectivity and efficiency metrics now outweighing thermal performance in specification decisions.
Bridge induction systems combining zoneless full-surface heating with pan-detection sensors are supplanting traditional defined-burner configurations in premium residential and commercial installations. Kitchen designers in Denmark and Sweden specify these platforms for open-plan layouts where cooking surface flexibility outweighs legacy zone constraints. The shift is compressing demand for conventional four-zone hobs in new construction above 150 square meters.
REACH frameworks governing substance restrictions in electrical equipment are forcing reformulation of glass-ceramic cooktop compositions and coil insulation materials. Manufacturers serving EU markets must validate alternative fluoropolymer-free coatings by 2026 to maintain market access. Hospitality procurement teams in Germany and Austria now require full material disclosure documentation as a standard tender precondition.
Specification authority is migrating from individual property owners to facilities management contractors and kitchen design studios with certified sustainability credentials. These intermediaries in France and Belgium bundle appliance selection into broader energy performance contracts, consolidating purchasing volume among fewer specification gatekeepers. The channel shift favors suppliers with dedicated project sales teams over traditional retail-dominant brands.
Electric Hobs Market Segmentation
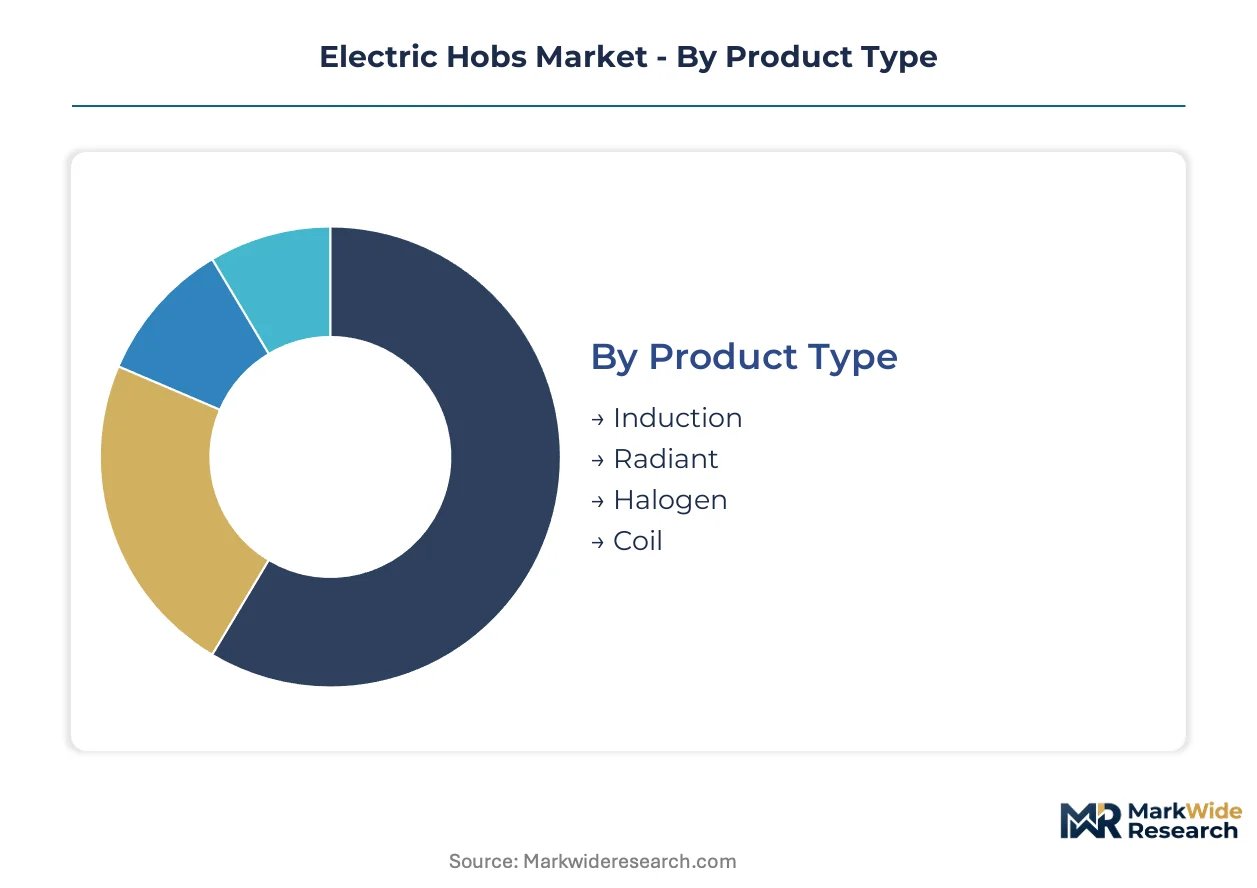
Electric hobs segment across four dimensions that shape procurement specifications and margin structures. Product type and technology tiers determine regulatory compliance pathways, while end-user and capacity configurations dictate channel access and installation requirements.
Product Type:
EU Ecodesign Directive thresholds differentiate compliance pathways across heating technologies, with efficiency mandates eliminating lower-performing architectures from new construction specifications.
- Induction:Electromagnetic coils generate heat directly in ferromagnetic cookware with conversion efficiency exceeding 90%. Residential retrofit demand in Germany and France concentrates here as building renovation subsidies require minimum efficiency ratings that exclude radiant alternatives. REACH material disclosure requirements for coil insulation and glass-ceramic compositions add certification burden but protect premium positioning.
- Radiant:Resistive heating elements beneath glass-ceramic surfaces deliver consistent thermal output but at 60-70% energy conversion efficiency. Replacement demand in older UK housing stock with limited electrical panel capacity sustains this segment where simultaneous multi-zone operation would require expensive infrastructure upgrades.
- Halogen:Tungsten-halogen lamps provide rapid response heating for specialized commercial applications. Institutional kitchens in France specify these for precise temperature control in sauce preparation.
- Coil:Exposed resistive wire elements represent legacy architecture with minimal compliance pathway under tightening EU efficiency standards. Budget residential replacement in Eastern European markets with delayed regulatory enforcement maintains residual demand.
Induction handles the majority of throughput; Halogen is gaining share fastest in specialized commercial niches.
Technology:
Connectivity and control sophistication stratify pricing tiers, with smart features commanding premium positioning in new-build residential markets and hospitality procurement.
- Smart Technology:WiFi-enabled hobs integrate with building energy management systems and mobile applications for remote monitoring and automated cooking programs. Netherlands and Scandinavian new-build residential markets specify these platforms as standard, with energy consumption data feeding into household carbon accounting dashboards required by national building codes.
- Touch Control:Capacitive glass interfaces replace mechanical knobs for cleanable surfaces and precise power adjustment. Hospitality operators in Spain prioritize these for front-of-house cooking stations where aesthetic integration matters.
- Timer:Programmable shut-off functions address safety compliance for institutional settings. School kitchens in Italy require these features under national fire prevention regulations.
- Multi-Zone:Flexible burner configurations allow combined heating areas for oversized cookware. Bridge induction systems in Denmark and Sweden deploy this technology for zoneless full-surface operation.
Touch Control dominates current installation volumes; Smart Technology shows the steepest expansion trajectory as building automation integration becomes mandatory.
End User:
Procurement authority and specification complexity diverge sharply between residential decision-makers and institutional purchasing departments with certified sustainability credentials.
- Residential:Individual homeowners and landlords drive replacement cycles influenced by subsidy availability and installer recommendations. French building energy renovation subsidies channel spending toward induction platforms with documented efficiency ratings.
- Commercial:Independent restaurants and food service operations balance capital constraints with operational efficiency. Electromagnetic compatibility certification delays of 4-6 months disadvantage smaller manufacturers serving this price-sensitive segment.
- Hospitality:Hotel and restaurant chains face mounting pressure to eliminate on-site gas infrastructure for insurance and safety compliance. Procurement teams in Germany and Austria now require full REACH material disclosure documentation as standard tender precondition.
- Catering:Mobile and event-based food service requires portable single and double burner units with rapid deployment capability. Festival operators in Portugal specify induction for temporary installations to satisfy fire safety inspectors.
Residential accounts for the largest absolute volume; Hospitality is climbing the fastest as electrification mandates eliminate gas alternatives.
Capacity:
Burner count determines electrical load requirements and installation complexity, with infrastructure constraints in older buildings limiting multi-zone adoption.
- Single Burner:Compact units serve small households, rental properties, and supplemental cooking applications. Urban apartments in Paris and Milan with severe space constraints specify these for kitchenette installations.
- Double Burner:Standard replacement configuration for residential retrofit markets where existing electrical circuits cannot support higher loads without panel upgrades. UK Victorian housing stock with original wiring sustains demand here.
- Triple Burner:Intermediate format gaining traction in mid-market residential renovations. Italian kitchen design studios bundle these into energy performance contracting arrangements.
- Multi-Burner:Four or more cooking zones dominate hospitality procurement and premium residential new construction. Hotel chains in Spain specify these for centralized kitchen operations requiring simultaneous high-volume production.
Double Burner remains the workhorse for replacement cycles; Multi-Burner is expanding most quickly in hospitality electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea-Baltic electricity interconnectors enable German and Danish grid operators to stabilize renewable loads for high-amperage cooking infrastructure. France and Spain leverage Mediterranean LNG terminals to buffer residential electrification programs against pipeline constraints.
Germany
Residential builders in Bavaria and Baden-Württemberg specify induction hobs at rising rates as KBA efficiency thresholds tighten. The EU Ecodesign Directive eliminates radiant-element alternatives from new construction specifications. Stuttgart's kitchen design studios bundle appliance selection into energy performance contracting arrangements.
France
Building energy renovation subsidies channel replacement spending toward electric hobs in Île-de-France and Auvergne-Rhône-Alpes. ANSM material disclosure requirements force reformulation of glass-ceramic compositions by 2026. Lyon-based facilities management contractors consolidate purchasing volume among certified sustainability credential holders.
United Kingdom
Victorian housing stock with original wiring sustains demand for double-burner radiant units in London and the Midlands. Power grid capacity constraints in older buildings limit simultaneous multi-zone induction operation without panel upgrades. Manchester's installer networks face qualified electrician scarcity for high-amperage circuit upgrades.
Italy
School kitchens in Lombardy and Emilia-Romagna require programmable timer features under national fire prevention regulations. Italian kitchen design studios bundle triple-burner configurations into energy performance contracting. Milan's hospitality procurement teams prioritize touch control interfaces for front-of-house cooking stations.
Spain
Hotel and restaurant chains in Madrid and Barcelona face mounting pressure to eliminate on-site gas infrastructure for insurance compliance. Commercial hospitality electrification accelerates as building decarbonization targets expand subsidy pools. Valencia's festival operators specify induction for temporary installations to satisfy fire safety inspectors.
Electric Hobs Market Competitive Landscape
Listed leaders compete with private specialists across project channel access and component manufacturing depth. The vendor base stratifies into three tiers: integrated conglomerates with captive coil production, appliance-focused multinationals with outsourced fabrication, and regional specialists serving price-sensitive replacement cycles. Strategic differentiation concentrates on backward integration into ferrite magnet supply and certification speed for electromagnetic compliance.
Among European-integrated conglomerates, BSH Home Appliances Group and Robert Bosch GmbH exemplify archetypes with upstream control over component manufacturing. Electrolux AB occupies a position within the hospitality-focused fabrication tier. These anchors illustrate how specification authority migration toward facilities management contractors favors suppliers with dedicated project sales teams over retail-dominant brands.
| Leading Market Players |
|---|
| BSH Home Appliances Group |
| Robert Bosch GmbH |
| Whirlpool Corporation |
| Miele & Cie. KG |
| Haier Group Corporation |
| Electrolux AB |
| Samsung Electronics Co., Ltd |
| SMEG S.p.A. |
| LG Electronics Inc. |
| Others |
Supply & Pricing Matrix
CE marking requirements for electromagnetic compatibility gate both supplier qualification timelines and price differentiation across induction platform tiers simultaneously. Manufacturers bearing extended certification cycles of 4-6 months capture premium positioning in project channels, while uncertified alternatives compete solely on transactional spot pricing in replacement markets.
Pricing Analysis
Volume-discount tiering structures stratify procurement across hospitality chains, facilities management contractors, and individual residential buyers. Three-tier pricing separates REACH-compliant induction platforms with full material disclosure from standard efficiency-rated units and residual coil-element alternatives. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in mid-tier radiant segments intensifies because copper and ferrite magnet input volatility erodes margin stability. Hospitality procurement teams exhibit lowest price sensitivity due to insurance compliance mandates, whereas Eastern European residential retrofit buyers prioritize unit economics above efficiency metrics.
Supply Chain Analysis
China and Germany anchor ferrite magnet and glass-ceramic cooktop substrate production for induction coil assemblies. Component sourcing draws from Malaysian wire-winding facilities and Italian control system integrators. Single-source vulnerability concentrates in rare-earth magnet supply chains subject to export licensing restrictions. Distribution runs through kitchen design studios and facilities management contractors in Western Europe, bypassing traditional retail dominance in project channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: efficiency mandates and material disclosure requirements create switching costs that cement incumbent positions while raising capital barriers for new platform entrants.
For Market Incumbents: Shield premium positioning by deepening backward integration into ferrite magnet supply chains before raw material volatility destabilizes mid-tier competitors. Accelerate REACH-compliant material certification pipelines to capture specification share migrating toward facilities management contractors. Electromagnetic compatibility certification delays threaten market access for product lines lacking dedicated compliance teams.
For New Entrants and Emerging Players: Rural retrofit installation service gaps expose white-space opportunities where qualified electrician scarcity creates bottlenecks for high-amperage circuit upgrades. Bridge induction systems for zoneless full-surface heating remain under-penetrated in mid-market residential renovations. Partner with regional electrical contractor networks to bypass studio-dominated specification channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from appliance-focused multinationals with outsourced coil fabrication seeking to shed non-core manufacturing assets. Long-term viability favors suppliers with captive component production and certified sustainability credentials. Watch for harmonization between EU Ecodesign efficiency thresholds and circular economy material recovery requirements as the decisive inflection signal for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Magnet Supply | Captive magnet production insulates BSH and Bosch from raw material volatility compressing mid-tier margins. |
| REACH Material Disclosure Certification | Full documentation compliance opens tender access for German and Austrian hospitality procurement teams. |
| Bridge Induction Platform Development | Zoneless full-surface configurations capture specification share from Danish and Swedish kitchen designers. |
| Project Sales Team Expansion | Dedicated channels penetrate facilities management contractors consolidating purchasing volume in France and Belgium. |
| Rural Installation Service Network Buildout | Qualified electrician partnerships address infrastructure upgrade bottlenecks in UK and German retrofit markets. |
Research Methodology
A standing panel of kitchen design studio specification leads, facilities management procurement directors, electrical contractor network heads, and appliance manufacturer product managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Ecodesign Directive implementation reports, REACH substance restriction databases, national building energy renovation subsidy registries in France and Italy, and customs trade data for ferrite magnet and glass-ceramic imports. Bottom-up shipment estimates triangulated against top-down construction completion and renovation permit data.
Consistency checks validated volume and value outputs against external benchmarks including household appliance trade association statistics and national energy agency equipment penetration surveys. Segmentation modeling spanned product type, technology tier, end-user archetype, and capacity configuration across the projection horizon. CAGRs derived from regression analysis of historical efficiency standard adoption curves and subsidy program uptake rates. Forecast inputs incorporated electrical infrastructure upgrade cost elasticity and hospitality electrification mandate compliance timelines.
Forecasts assume regulatory continuity in EU Ecodesign and REACH frameworks; material policy shifts toward accelerated phase-out timelines or expanded substance restrictions would require re-modeling. Specific risks include copper and rare-earth magnet price volatility, grid capacity constraints in older building stock, and electromagnetic compatibility certification backlog extensions. Recalibration cycles align with material shifts in efficiency threshold announcements and building decarbonization subsidy program renewals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
United Kingdom Kitchen Appliances Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Residential Cooking Grills Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
Russia Household Electric Grill Market
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Electric Grill Market