
 Built-In Coffee Machine Market | 2026-2036
Built-In Coffee Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Built-In Coffee Machine Market Outlook
High-end residential buyers is rotating toward super-automatic built-in systems as commercial hospitality procurement moderates in select metros. Bosch leverages in-house production of precision brewing modules to control component quality across European supply chains. Miele sustains premium positioning through R&D intensity focused on grinder integration and milk foam consistency. Siemens competes aggressively on connected-kitchen ecosystems, embedding Wi-Fi diagnostics into cabinet-integrated units.
A built-in coffee machine is a permanently installed appliance designed to integrate flush with kitchen cabinetry, typically operating at 15-bar pump pressure with stainless steel brewing groups and dedicated water line connections for continuous operation. The primary purpose is delivering café-grade espresso and milk-based beverages within residential or commercial kitchen environments without countertop footprint. Espresso machines lead product type revenue due to established consumer preference for concentrated extraction, while super-automatic technology commands the fastest expansion as buyers prioritize one-touch operation over manual control. Residential users anchor end-user demand, though high-end hotels represent concentrated margin pools where durability specifications and service contracts elevate lifetime value per unit.
The EU Ecodesign Directive and REACH chemical standards constrain heating element materials and power standby thresholds for machines sold across Europe. The US Department of Energy appliance standards and FCC wireless certification requirements shape product development timelines for connected models targeting North American kitchens. Stakeholders must monitor how evolving energy labeling regimes and smart-home interoperability standards reshape R&D allocation between mechanical reliability and digital feature sets.
Market Dynamics
The EU Ecodesign Directive is compressing heating element power budgets and forcing simultaneous redesigns of thermal management systems across European manufacturing footprints. This regulatory pressure is reshaping competitive positioning between established European appliance brands and Asian challengers seeking cabinet-integration certification.
Growth Catalysts
- Residential kitchen renovation cycles:High-net-worth homeowners in Germany and Italy are prioritizing super-automatic built-in units during whole-home remodeling projects.
- EU Ecodesign Directive compliance:Mandated standby power thresholds below 0.5W are accelerating replacement of legacy heating architectures in machines sold across Europe.
- Milk foam system integration:One-touch cappuccino functionality is displacing manual steam wand operation in premium residential specifications.
Market Restraints
- Stainless steel brewing group costs:Volatility in nickel alloy prices compresses margin on entry-level integrated units.
- Precision grinder supply concentration:Ceramic burr manufacturing clusters in Southern China create single-source vulnerability for mid-tier OEMs.
- Commercial hospitality substitution:Pod-based countertop systems capture hotel breakfast service contracts from built-in espresso installations.
Strategic Opportunities
- Underpenetrated US secondary markets:Dallas, Denver, and Austin residential construction lacks dedicated built-in coffee appliance specification compared to coastal metros.
- Wi-Fi diagnostics convergence:Connected-kitchen ecosystems integrating Miele and Siemens protocols enable predictive maintenance revenue streams.
- Hotel service contract unbundling:Separate leasing of machines from technical support creates recurring revenue pools in luxury hospitality.
Industry Challenges
- Dual certification timelines:FCC wireless approval for North American models and CE marking for European variants extend product launch cycles by 8-14 months.
- Legacy 15-bar pump integration:Cabinet-depth constraints complicate vibration isolation for existing Italian pump architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Built-In Coffee Machine Market |
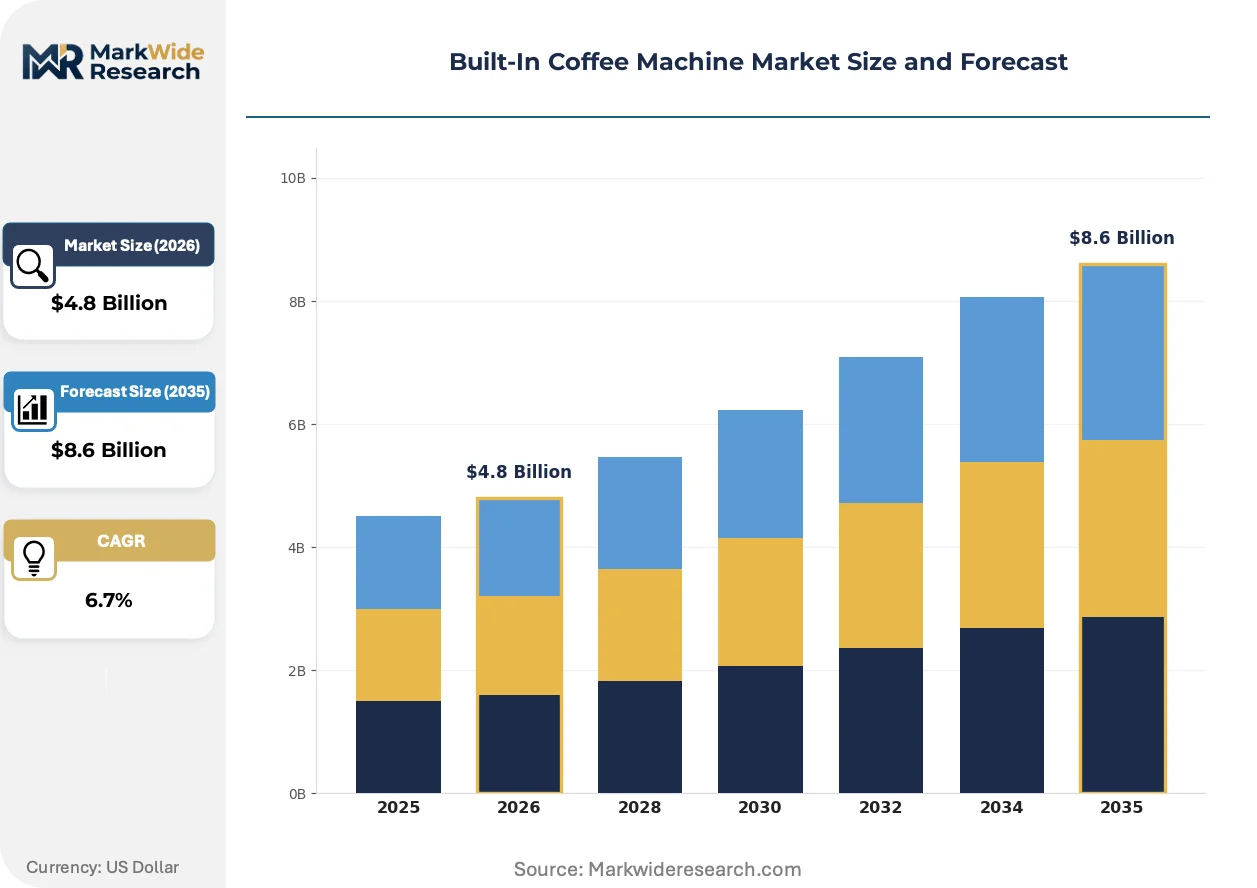
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Espresso Machines, Cappuccino Makers, Drip Coffee Machines, Brew Bar End User: Residential Users, Commercial Establishments, High-End Hotels, Cafés Installation: Wall-Mounted, Cabinet-Integrated, Countertop, Built-In Technology: Manual, Semi-Automatic, Fully Automatic, Super-Automatic |
| Companies Covered | Bosch, Miele, Siemens, Smeg, JennAir, Fisher & Paykel, Thermador, Gaggenau, Whirlpool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Built-In Coffee Machine Market Strategic Shifts
Built-in coffee machine architecture is compressing around three vectors: thermal system efficiency mandates, connected-kitchen protocol standardization, and super-automatic user experience expectations. These forces are converging to privilege integrated module suppliers over standalone component vendors.
Thermocoil heating technology is miniaturizing. This compact thermal architecture replaces traditional boiler systems in space-constrained cabinet installations. Premium residential buyers in Milan and Munich are specifying thermocoil-equipped units for 24-inch cabinet depths. The technology is miniaturizing heating footprints while maintaining 93°C brew temperature stability, enabling slimmer chassis designs that displace bulkier European legacy platforms.
REACH chemical standards are constraining heating element coatings. ECHA restrictions on chromium compounds in resistive wire insulation are forcing reformulation of coil materials. Manufacturers targeting European distribution are accelerating ceramic-coated alternatives through validation. This regulatory pressure elevates production costs for entry-tier suppliers while insulating premium brands with existing R&D budgets.
Buyer specification patterns are rotating toward one-touch beverage programming. High-end residential architects are embedding super-automatic units into kitchen islands as entertainment focal points. This behavior is displacing separate grinder and espresso machine countertop arrangements. The shift is most visible in California and Florida custom home markets where appliance showrooms influence build specifications.
Built-In Coffee Machine Market Segmentation
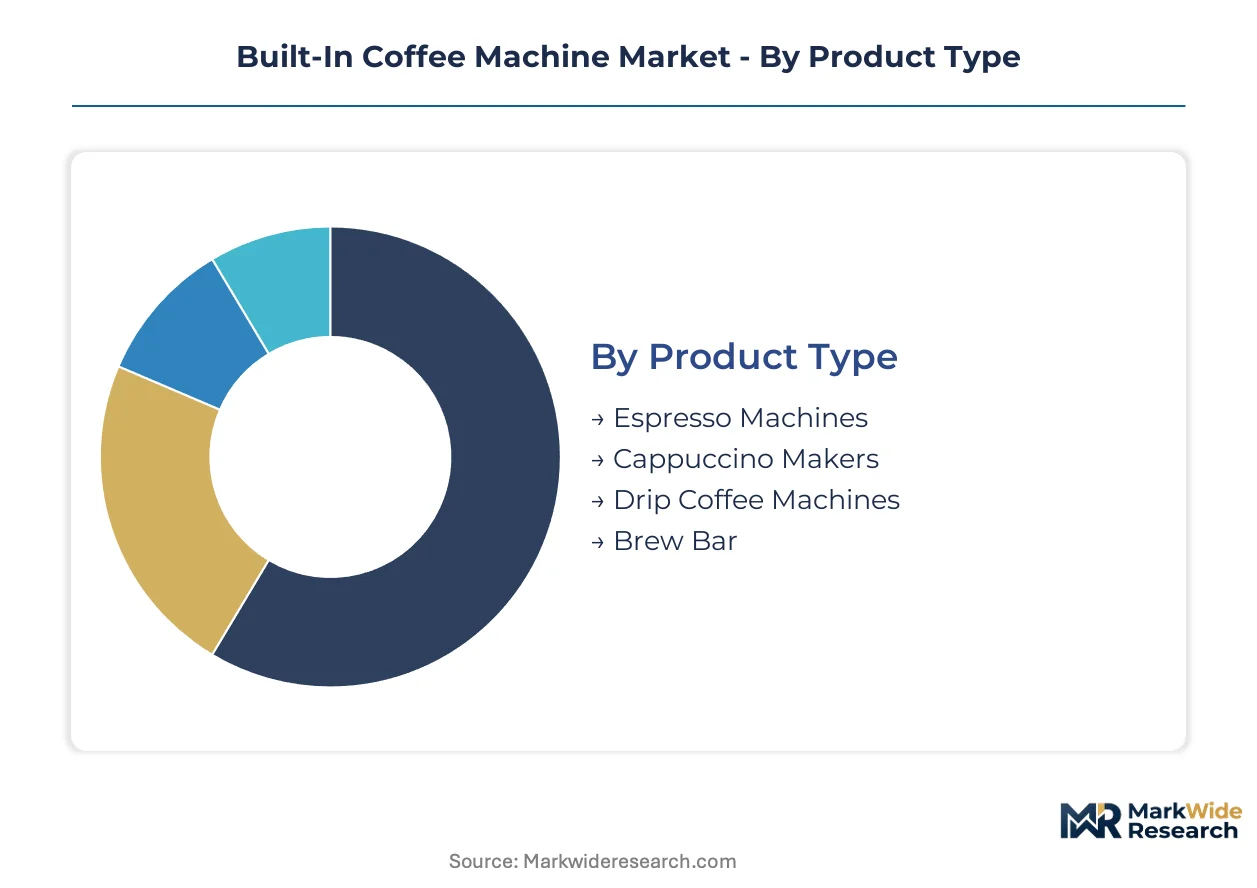
Built-in coffee machine segmentation reveals how cabinet integration requirements fragment across brewing technologies and installation constraints. Substitution pressures from countertop pod systems and manual espresso equipment reshape competitive intensity differently across each dimension.
Product Type:
Countertop pod systems exert the strongest substitution threat against lower-complexity built-in categories, while high-pressure espresso architectures defend their installed base through specification lock-in during kitchen renovations.
- Espresso Machines:These systems deploy 15-bar rotary pumps and stainless steel brewing groups to deliver concentrated extraction at stable temperatures. Demand concentrates in German and Italian residential renovations where architects specify flush-mounted units as standard in luxury kitchen packages. The category defends against substitution through permanent water line integration and custom cabinetry coordination.
- Cappuccino Makers:Integrated milk foam systems combine thermoblock heating with automated frothing chambers for one-touch beverage completion. High-end hotels in Miami and Los Angeles prioritize these units for breakfast service consistency, though pod-based alternatives capture budget hospitality contracts.
- Drip Coffee Machines:Gravity-fed brewing with thermal carafe retention serves volume-oriented residential users.
- Brew Bar:Modular configurations accommodate multiple brewing methods within single cabinet footprints.
Espresso Machines retain volume leadership; Super-Automatic technology holds the steepest expansion curve.
End User:
Margin concentration varies sharply across customer types, with hospitality procurement emphasizing durability specifications and service contracts over upfront equipment cost.
- Residential Users:High-net-worth homeowners drive specification during whole-home remodeling cycles, particularly in California and Florida custom build markets. These buyers prioritize one-touch operation and connected-kitchen integration over manual control sophistication.
- Commercial Establishments:Corporate break rooms and boutique offices represent fragmented, price-sensitive procurement with shorter replacement cycles.
- High-End Hotels:Luxury properties in Dallas and Austin specify built-in units for suite kitchenettes, though breakfast service pods displace some lobby espresso installations.
- Cafés:Independent coffee shops rarely specify cabinet-integrated equipment due to flexibility requirements and lease constraints.
Residential Users anchor absolute volume; High-End Hotels deliver the highest lifetime value per installed unit.
Installation:
Physical integration depth determines thermal system design constraints and regulatory compliance pathways across European and North American certification regimes.
- Cabinet-Integrated:Flush-mounted units operating at standard 24-inch depths dominate premium residential specification in Milan and Munich. Thermocoil heating miniaturization enables these slim chassis designs while maintaining brew temperature stability.
- Wall-Mounted:Vertical installation above counter surfaces serves space-constrained urban kitchens with dedicated plumbing access.
- Countertop:Surface-placed units blur category boundaries with non-built-in equipment and face intense pod system competition.
- Built-In:Generic permanent installation category encompasses multiple mounting configurations without specificity.
Cabinet-Integrated formats command premium positioning; Wall-Mounted alternatives expand most quickly in dense metropolitan construction.
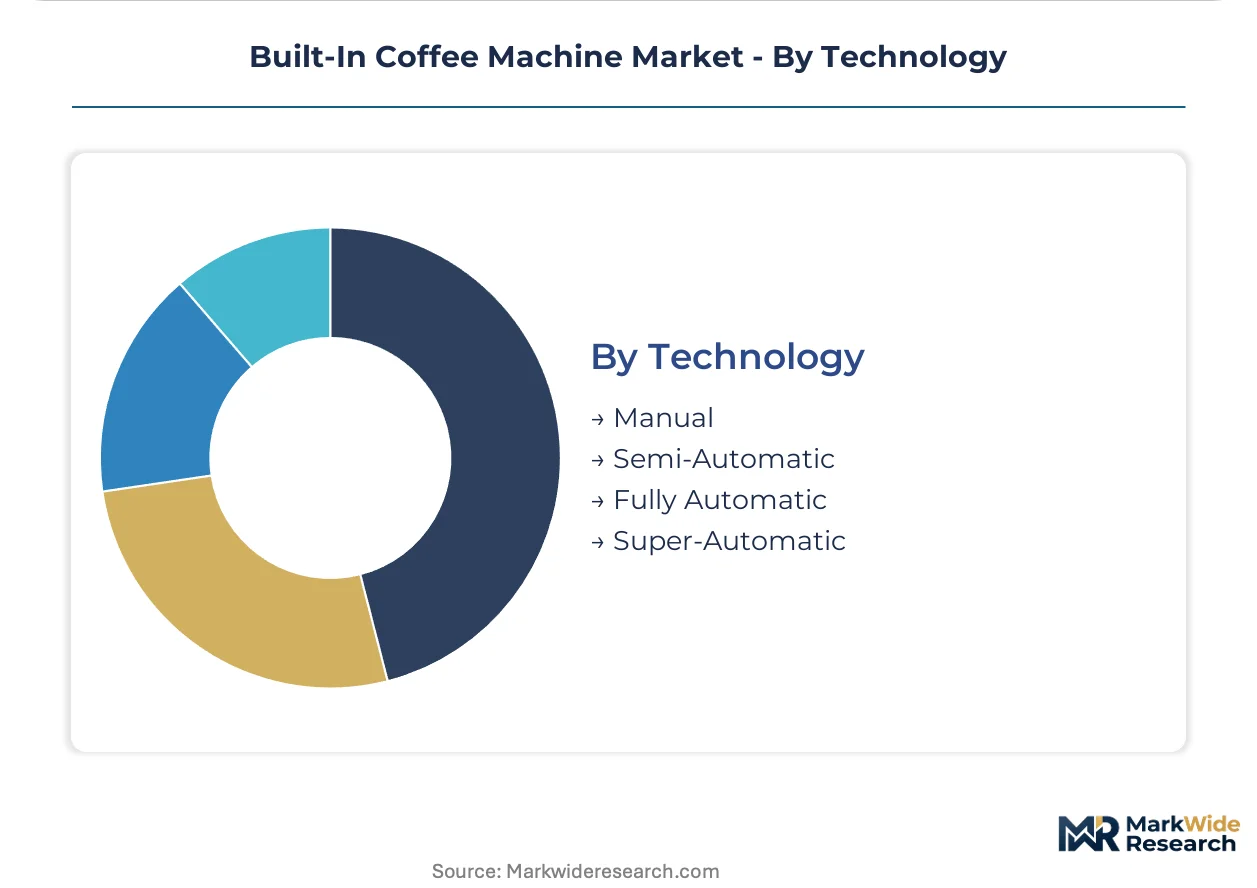
Technology:
Automation intensity separates price tiers and determines R&D allocation between mechanical reliability and digital feature development.
- Super-Automatic:One-touch beverage programming with integrated grinders and milk systems displaces manual countertop arrangements in California custom home markets. Architects specify these units as kitchen island focal points.
- Fully Automatic:Programmable shot volumes and automated tamping reduce user intervention while preserving some customization control.
- Semi-Automatic:Manual shot initiation with automated pressure maintenance attracts enthusiast residential users.
- Manual:Lever-operated and direct lever systems retain niche specification among purist buyers.
Super-Automatic technology gains share fastest; Semi-Automatic equipment retains enthusiast loyalty despite volume contraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European appliance distribution networks. German and Italian manufacturing clusters feed premium built-in coffee systems through this logistics corridor into North American and Asian markets.
Germany
Bavarian kitchen appliance clusters in Munich and Nuremberg drive super-automatic specification during residential renovations. The EU Ecodesign Directive mandates sub-0.5W standby thresholds, forcing heating system redesigns across Baden-Württemberg production lines. Stuttgart-area engineering firms specialize in thermocoil miniaturization for 24-inch cabinet depths.
United States
Dallas, Denver, and Austin construction markets show underpenetration relative to coastal metros, creating specification gaps for cabinet-integrated units. FCC wireless certification requirements extend product launch timelines for connected-kitchen models. California custom home markets in Orange County and Silicon Valley rotate toward one-touch beverage programming as kitchen island focal points.
Italy
Milanese residential architects specify flush-mounted espresso systems as standard in luxury kitchen packages. REACH chemical standards from ECHA constrain chromium compounds in resistive wire insulation, accelerating ceramic-coated alternatives through validation. Turin and Bologna manufacturing districts concentrate 15-bar rotary pump production for European supply chains.
China
Shanghai and Shenzhen appliance OEMs compete on cabinet-integration certification for export markets. The country's national quality regulator enforces GB standards for electrical safety in built-in kitchen equipment. Guangdong Province ceramic burr manufacturing clusters create single-source vulnerability for mid-tier grinder supply.
United Kingdom
London and Southeast England high-net-worth renovations prioritize connected-kitchen ecosystems with Wi-Fi diagnostics. CE marking requirements align UK product compliance with EU thermal efficiency mandates. Midlands distribution hubs channel German and Italian imports into residential specification pipelines.
Built-In Coffee Machine Market Competitive Environment
Concentration sits with diversified appliance conglomerates controlling precision brewing module production. European heritage brands occupy premium positioning through grinder integration R&D, while Asian contract manufacturers compete on cabinet-depth thermal system cost engineering. Three archetypes dominate: vertically integrated European majors, specialist super-automatic technology licensors, and scale-driven Asian OEMs. Competitive moves center on backward integration into ceramic burr supply and predictive maintenance software licensing.
Among German diversified appliance manufacturers, Bosch, Miele, and Siemens exemplify distinct competitive vectors. Bosch represents in-house production control over European supply chains. Miele occupies a position emphasizing R&D intensity around grinder consistency. Siemens anchors the connected-kitchen ecosystem tier with Wi-Fi diagnostic integration. These three entities collectively illustrate how heritage European appliance groups defend premium positioning against Asian challengers seeking cabinet-integration certification.
| Leading Market Players |
|---|
| Bosch |
| Miele |
| Siemens |
| Smeg |
| JennAir |
| Fisher & Paykel |
| Thermador |
| Gaggenau |
| Whirlpool |
| Others |
Value Chain & Pricing Dynamics
CE marking requirements gate both European market access and price tier qualification simultaneously, compressing margins for uncertified Asian contract manufacturers while insulating premium brands with existing compliance infrastructure. This dual function of certification creates pricing power concentration among heritage appliance groups with captive testing capabilities.
Pricing Analysis
Volume-discount tiering structures separate Miele and Gaggenau premium positioning from mid-tier Siemens and entry-level Asian OEM offerings. Price differentiation hinges on ceramic burr grinder integration quality and Wi-Fi diagnostic certification levels. Pricing pressure stems from nickel alloy volatility in stainless steel brewing groups, compressing entry-tier margins most severely. Corporate break room buyers exhibit highest price sensitivity; luxury hospitality procurement prioritizes lifetime service value over upfront equipment cost.
Supply Chain Analysis
Strait of Malacca transit underwrites ceramic burr distribution from Guangdong Province manufacturing clusters to European assembly plants. Component sourcing draws from Italian pump specialists in Bologna, German thermocoil engineering in Stuttgart, and Chinese grinder production in Shenzhen. Single-source vulnerability concentrates in Southern China ceramic burr supply. Distribution runs through Rotterdam port logistics for European appliance brands and Long Beach container terminals for North American specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision grinder engineering talent scarcity constrains mid-tier OEM expansion, privileging incumbents with captive ceramic burr validation capabilities and punishing new entrants lacking thermal system miniaturization expertise.
For Market Incumbents: Consolidate backward integration into ceramic burr supply chains to neutralize Guangdong single-source vulnerability. Capture Dallas and Austin specification pipelines through architect showroom partnerships before Asian challengers achieve cabinet-integration certification. Thermocoil R&D intensity separates defensible premium positioning from commoditized thermal architectures. For New Entrants and Emerging Players: Lead with super-automatic technology licensing to corporate break room distributors, bypassing residential renovation cycle dependence. Target Denver and Austin residential construction markets where coastal brand penetration remains shallow. Position around predictive maintenance software as recurring revenue wedge against transactional equipment sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermocoil miniaturization and REACH-compliant heating element development. Viable acquisition targets include specialist grinder engineering firms with ECHA-validated ceramic coating processes. Watch FCC wireless certification backlog duration as signal for connected-kitchen ecosystem consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Burr Backward Integration | Captive grinder supply neutralizes Guangdong concentration risk for European majors. |
| Thermocoil Miniaturization R&D | Stuttgart engineering clusters enable 24-inch cabinet depth compliance for Milan architects. |
| Wi-Fi Diagnostic Platform Launch | Predictive maintenance revenue streams displace pure equipment margins in hospitality. |
| Architect Showroom Partnership | Orange County and Silicon Valley specification pipelines lock in California custom home demand. |
| REACH-Compliant Heating Validation | ECHA ceramic coating approval gates European market access against uncertified competitors. |
Study Parameters
Cross-validation between appliance manufacturer engineering directors and luxury kitchen architect specifications anchors the qualitative findings. Primary interviews with thermocoil R&D leads at Stuttgart firms, ceramic burr procurement managers at Guangdong OEMs, and hospitality FF&E directors at Dallas hotel groups combined with secondary validation from EU Ecodesign Directive compliance filings, FCC equipment authorization databases, and ECHA REACH restriction updates. Bottom-up segment sizing and top-down macro constraint triangulation produced convergent estimates.
Sensitivity analysis across grinder supply disruption scenarios and nickel alloy price volatility bands stress-tested projection robustness. Segmentation dimensions modeled include brewing technology architecture, installation depth requirements, automation intensity tiers, and regional regulatory cluster alignment. CAGRs derived from renovation cycle frequency analysis and replacement rate assumptions across German, Italian, and US metropolitan construction pipelines. Forecast inputs incorporated EU standby power threshold enforcement timelines and thermocoil patent expiration schedules.
The analysis sits within stated boundaries; outcomes outside sustained high-net-worth residential construction velocity or stable ECHA chemical restriction frameworks would require recalibration. Forecasts reflect documented assumptions regarding super-automatic technology adoption curves and hospitality service contract unbundling penetration. Practitioners should keep alternative scenarios live as FCC wireless certification processing durations and REACH coating material substitution timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market
Kitchen Appliances
United States Small Kitchen Appliances Market
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Ceramic Coated Cookware Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Europe Smart Cooker Market
Kitchen Appliances
US Household Coffee Machine Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
Modular Zero-Waste Kitchen Appliance Market
Kitchen Appliances
Electric Pizza Oven Market