
 Kitchen Knife Market | 2026-2036
Kitchen Knife Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Knife Market Intelligence
E-commerce and direct-to-consumer channels is tilting how kitchen knives reach buyers, bypassing traditional brick-and-mortar kitchenware retailers. Wüsthof leverages its Solingen heritage to sustain premium pricing in European and North American specialty stores. Victorinox anchors its position through multi-channel distribution spanning professional culinary supply houses and mass-market e-commerce platforms. Kai Corp. competes by specializing in Japanese laminated steel techniques that differentiate its Shun line from Western forged alternatives.
A kitchen knife is a handheld cutting implement with a blade typically measuring 8 to 36 centimeters, constructed from martensitic stainless steel, high-carbon steel, or sintered ceramic, heat-treated to Rockwell hardness ratings between 54 and 66 HRC for edge retention and corrosion resistance. Its primary commercial purpose spans food preparation in residential kitchens, professional restaurants, and institutional culinary training environments. Chef's knives and Santoku knives dominate value generation due to universal application across Western and Asian cooking techniques, while ceramic blades represent the fastest-growing material niche driven by weight-sensitive home cooking segments. Professional chef use cases command the highest margin pools through recurring replacement cycles and brand loyalty, whereas home cooking volumes scale through entry-level stainless steel offerings.
FDA food-contact substance regulations govern blade and handle material safety for US-bound products, while EU REACH restrictions on nickel and chromium migration shape alloy formulation choices for European market access. Japan's Ministry of Economy, Trade and Industry (METI) administers JIS standards for blade hardness and corrosion testing that define export-grade quality thresholds. Stakeholders must monitor evolving food-contact chemical restrictions across major import jurisdictions to preempt reformulation costs and certification delays.
Market Dynamics
Professional chef adoption is compressing replacement cycles while e-commerce disintermediation erodes traditional kitchenware retailer margins, forcing heritage manufacturers to defend positioning through direct channels.
Growth Catalysts
- Culinary tourism expansion:Restaurant density in urban centers is accelerating professional-grade knife procurement, with Tokyo, New York, and Berlin anchoring demand concentration.
- EU REACH compliance:Nickel and chromium migration restrictions are filtering out low-grade alloy suppliers, consolidating market share among certified manufacturers.
- Laminated steel techniques:Japanese san-mai construction methods are displacing Western forged alternatives in premium residential segments seeking edge retention performance.
Market Restraints
- High-carbon steel volatility:Scrap metal pricing swings compress margin predictability for forged blade producers dependent on virgin alloy inputs.
- Solingen supply concentration:German blade manufacturing clusters create geographic vulnerability to energy cost shocks and logistics bottlenecks.
- Ceramic blade substitution:Sintered zirconia alternatives are capturing weight-sensitive home cooking segments with zero-maintenance value propositions.
Strategic Opportunities
- Indian urban middle-class expansion:Underpenetrated metropolitan markets present white space for mid-tier stainless steel offerings through Flipkart and Amazon India.
- Subscription sharpening services:Direct-to-consumer blade maintenance programs are creating recurring revenue attachment to one-time knife purchases.
- ISO 8442-5 certification:International food-contact material standards are enabling export-grade positioning for compliant manufacturers in secondary markets.
Industry Challenges
- Heat-treatment skill scarcity:Rockwell hardness calibration expertise is concentrating among aging European and Japanese master craftsmen, constraining quality-scaled production.
- FDA certification timelines:Food-contact substance notification delays average 180 days, freezing new alloy formulations from US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Knife Market |
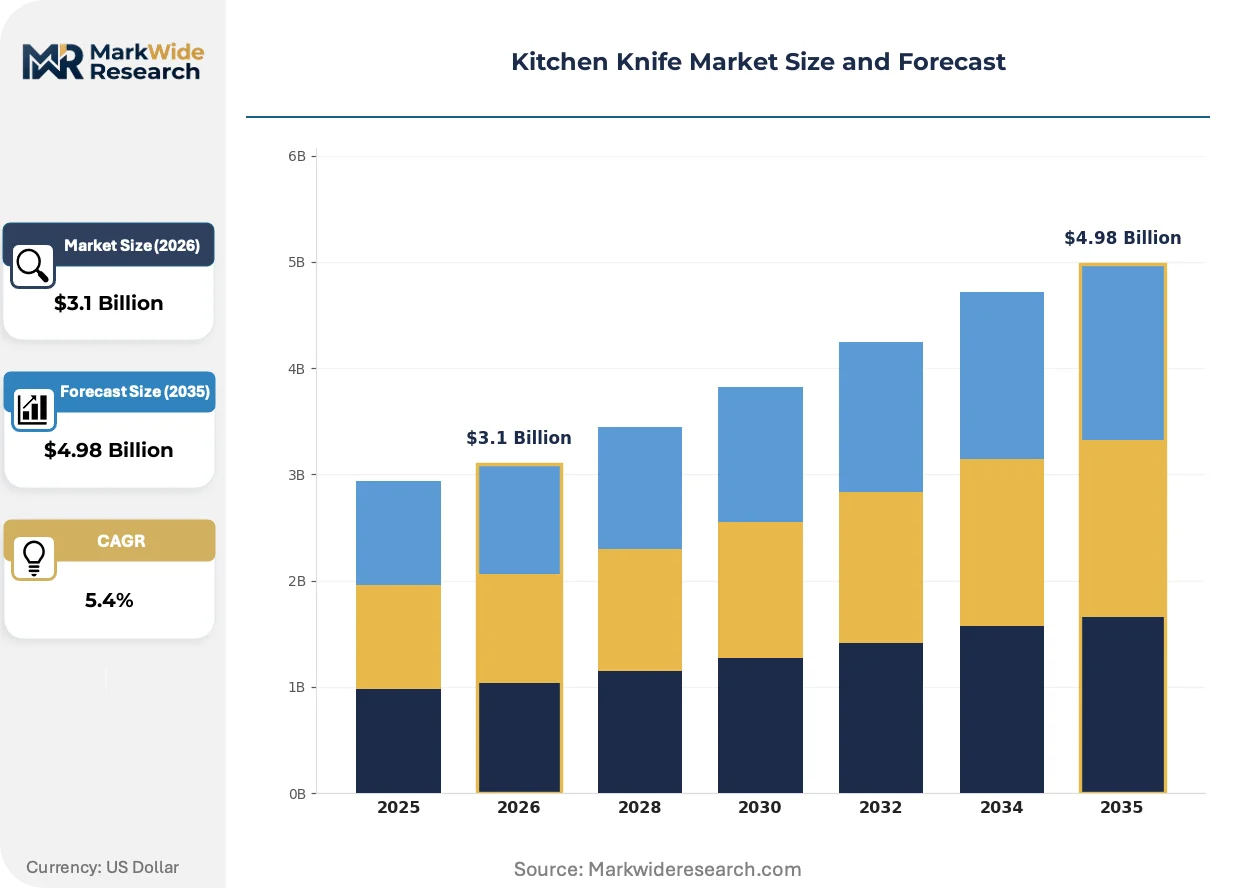
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Chef's Knife, Paring Knife, Serrated Knife, Santoku Knife Material: Stainless Steel, Carbon Steel, Ceramic, Plastic Use Case: Home Cooking, Professional Chefs, Food Preparation, Culinary Schools Brand: Wüsthof, Shun, Victorinox, Global |
| Companies Covered | Friedr. Dick GmbH and Co. KG, Stanley Black and Decker Inc., Victorinox AG, Opinel, Messermeister Inc., Wüsthof, Kai Corp., Spyderco, Shun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Knife Market Strategic Shifts & Innovations
Digital configuration tools and predictive maintenance platforms are restructuring how buyers evaluate blade performance, compressing the traditional tactile purchase process into data-driven selection workflows.
AI-powered edge geometry simulation software is virtualizing the traditional hand-forging design process. Professional cutlery buyers in high-volume restaurant groups are adopting these platforms to specify custom blade profiles without physical prototyping. This technology is virtualizing the role of master smiths in early-stage product development, compressing design-to-production timelines from months to weeks.
Japan's METI is tightening JIS G 4303 martensitic stainless steel standards for export-grade cutlery, mandating stricter corrosion resistance testing protocols. Domestic manufacturers must retest legacy product lines, creating temporary supply constraints. European importers are accelerating alternative sourcing from South Korean MFDS-certified facilities to preempt certification gaps.
Home cooks are unbundling knife purchases from brick-and-mortar tactile evaluation, relying instead on video content and third-party Rockwell hardness verification data. Specialty e-commerce platforms are displacing kitchenware department stores as the primary discovery channel. This behavioral shift is most pronounced in US and German metropolitan markets where same-day delivery logistics have matured.
Kitchen Knife Market Segmentation
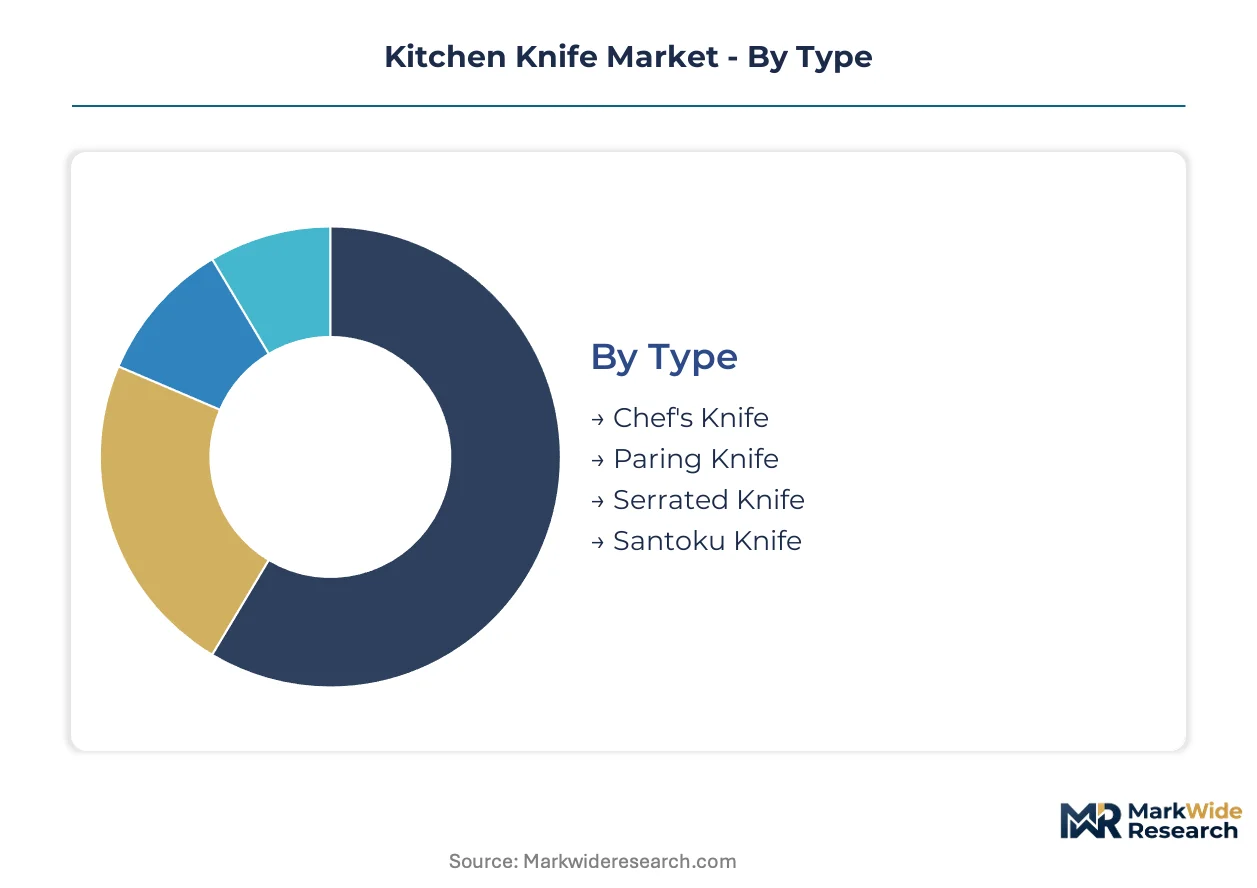
Blade geometry, alloy composition, and end-use intensity create distinct margin pools across kitchen knife segments. Manufacturers calibrate heat-treatment protocols and distribution channels to match the performance expectations and replacement cadence of each buyer category.
Type:
Application determines blade profile, edge geometry, and pricing tier within professional and residential kitchens.
- Chef's Knife:Versatile 8-12 inch blade with curved edge supporting rock-chopping motion. Professional kitchens in New York, Tokyo, and Berlin drive replacement cycles through intensive daily use and edge maintenance requirements.
- Santoku Knife:Japanese-origin blade with granton edge and sheep's foot tip optimized for vertical chopping. North American and European home cooks seeking Asian cooking techniques are expanding this segment's residential penetration.
- Paring Knife:Compact 3-4 inch blade for precision tasks. Secondary tool in most knife sets with lower individual ASP but consistent attachment rates.
- Serrated Knife:Scalloped edge designed for crusty bread and soft-skinned produce. Niche utility limits standalone purchase frequency outside complete block sets.
Chef's Knife holds installed capacity. Santoku Knife is rotating up the share rankings.
Material:
Cost tier and performance characteristics stratify across alloy chemistry, hardness ratings, and maintenance demands.
- Stainless Steel:Martensitic alloys with 13-18% chromium content deliver corrosion resistance for residential users prioritizing low maintenance. German Solingen and Japanese Seki City manufacturers dominate volume production through automated heat-treatment lines.
- Ceramic:Sintered zirconium dioxide blades achieve Rockwell hardness exceeding 65 HRC with zero corrosion risk. Weight-sensitive home cooking segments and medical-adjacent food preparation facilities are adopting this material for its hygienic properties.
- Carbon Steel:Higher carbon content enables sharper initial edges but demands active maintenance to prevent oxidation. Professional chefs and culinary enthusiasts accept the trade-off for superior cutting feel.
- Plastic:Injection-molded polypropylene blades for disposable or educational applications. Institutional procurement in school cafeterias and airline catering drives volume at minimal unit economics.
Stainless Steel commands current volume leadership. Ceramic is climbing the fastest among material alternatives.
Use Case:
Customer type dictates purchase frequency, brand sensitivity, and channel preference across the value chain.
- Professional Chefs:High-velocity users replacing primary blades every 12-18 months. Restaurant group procurement managers specify Rockwell hardness minimums and NSF certification for insurance compliance.
- Home Cooking:Discretionary purchasers influenced by video content and third-party hardness verification. E-commerce platforms and direct-to-consumer brands are capturing share from department store kitchenware sections.
- Culinary Schools:Standardized kit requirements with institutional pricing and durability specifications. Accreditation bodies influence approved vendor lists for student equipment.
- Food Preparation:Industrial and contract catering operations with volume-based procurement and sanitization protocol requirements.
Professional Chefs anchor premium margin pools. Home Cooking is expanding most quickly as content-driven discovery accelerates.
Brand:
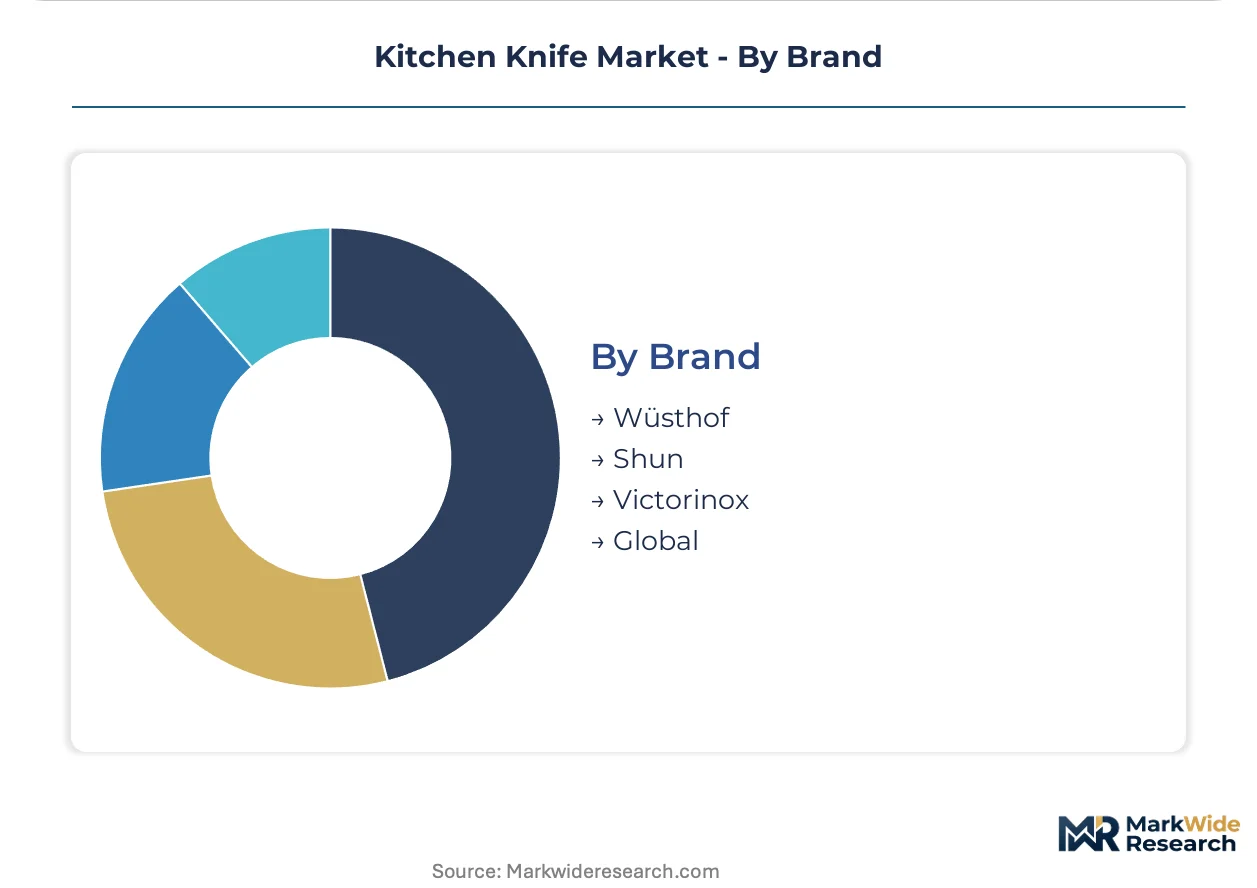
Heritage positioning and manufacturing geography create differentiated value propositions across price tiers.
- Wüsthof:Solingen-forged heritage brand with PEtec precision edge technology. European and North American specialty retail placement sustains premium positioning through tactile evaluation environments.
- Shun:Kai Corp.'s Japanese laminated steel line leveraging san-mai construction and Damascus patterning. North American premium residential segments respond to the Japanese craftsmanship narrative.
- Victorinox:Swiss manufacturer spanning professional supply houses and mass-market channels. Fibrox handle line dominates entry-level commercial procurement through NSF certification and price accessibility.
- Global:Yoshikin cutlery with distinctive Cromova 18 stainless steel and dimpled handle design. Professional kitchens seeking lightweight alternatives to traditional Western forged blades drive adoption.
Wüsthof and Victorinox hold parallel installed bases across premium and commercial tiers. Shun is rotating up the share rankings in North American residential markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers command pricing premiums through Solingen heritage positioning, while Chinese producers compete on scale-driven cost efficiency. This asymmetry shapes procurement patterns across residential and commercial segments.
Germany
Professional chef demand from Berlin and Munich restaurants drives premium blade procurement. EU REACH restrictions on nickel migration filter out uncertified alloy suppliers. Solingen's blade manufacturing cluster concentrates heat-treatment expertise and precision forging capacity.
United States
Restaurant density in New York and Chicago accelerates replacement cycles for commercial-grade cutlery. FDA food-contact substance regulations govern blade and handle material safety for domestic distribution. California's culinary tourism hubs anchor West Coast demand concentration.
Japan
Tokyo's fine-dining density sustains demand for laminated steel techniques. METI administers JIS G 4303 standards for export-grade martensitic stainless steel. Seki City's blade manufacturing tradition supports san-mai construction expertise.
India
Urban middle-class expansion in Mumbai and Delhi creates white space for mid-tier stainless steel offerings. BIS certification requirements shape alloy formulation choices for domestic market access. Flipkart and Amazon India logistics networks enable e-commerce penetration.
South Korea
Professional kitchen procurement in Seoul drives demand for NSF-certified commercial lines. MFDS food-contact material standards enable export-grade positioning for certified manufacturers. Busan-Ulsan manufacturing corridor supplies secondary market production capacity.
Kitchen Knife Market Key Industry Players
Heritage forgers and multi-channel specialists split the market into distinct positioning tiers. Solingen-based manufacturers leverage geographic certification marks to sustain premium pricing in specialty retail. Japanese laminated steel producers compete on edge retention performance in residential segments. Competitive moves concentrate on direct-to-consumer channel expansion and subscription-based blade maintenance services.
Within the heritage-forger tier, Friedr. Dick GmbH and Co. KG and Wüsthof represent Solingen's precision-forging tradition. Victorinox AG occupies a position spanning professional supply houses and mass-market channels. Kai Corp. exemplifies Japanese laminated steel specialization through its export-oriented product architecture.
| Leading Market Players |
|---|
| Friedr. Dick GmbH and Co. KG |
| Stanley Black and Decker Inc. |
| Victorinox AG |
| Opinel |
| Messermeister Inc. |
| Wüsthof |
| Kai Corp. |
| Spyderco |
| Shun |
| Others |
Cost & Logistics Intelligence
Scrap metal volatility in virgin alloy inputs compresses margin predictability for forged blade producers while simultaneously widening spreads between premium laminated steel offerings and entry-level stainless alternatives, reshaping how manufacturers calibrate heat-treatment capacity investments against pricing tier positioning.
Pricing Analysis
The customization-premium spread separates configured-to-order chef's knives with specified Rockwell hardness ratings from standard retail SKUs by margins exceeding three-to-one. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade, with NSF-certified commercial lines commanding premiums over uncertified residential equivalents. Cost compression in entry-level stainless steel intensifies because Chinese scale producers flood mass-market channels, eroding Solingen-forged positioning at the economy tier. Restaurant group procurement managers exhibit lowest price sensitivity due to insurance compliance requirements, while home cooking segments show highest elasticity to promotional discounting.
Supply Chain Analysis
Contract-manufacturing concentration rests with Solingen-based precision forgers, Seki City laminated steel specialists, and Yangjiang volume producers for economy-tier output. Geographic supply concentrates in Germany, Japan, and China, with raw material dependencies drawing from Swedish Sandvik steel mills, Chinese zirconia suppliers for ceramic blanks, and South African chromium ore processors. Single-source vulnerability concentrates in master heat-treatment craftsmen whose aging expertise constrains quality-scaled production expansion. Distribution runs through professional culinary supply houses for commercial procurement and direct-to-consumer platforms for residential discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sintered ceramic blade substitution threatens forged steel incumbents with zero-maintenance value propositions, forcing heritage manufacturers to defend replacement-cycle attachment through service bundling and performance differentiation.
For Market Incumbents: Insulate core margin pools by deepening backward integration into proprietary alloy formulation and captive heat-treatment capacity in Solingen or Seki City clusters. Accelerate subscription sharpening service deployment to create recurring revenue attachment that ceramic alternatives cannot replicate, while pursuing ISO 8442-5 certification to filter out uncertified competitors from professional procurement channels.
For New Entrants and Emerging Players: Pursue white-space penetration in Indian metropolitan markets through Flipkart and Amazon India logistics partnerships, targeting mid-tier stainless steel segments where heritage brand recognition remains underdeveloped. Establish beachheads in culinary school institutional procurement with standardized kit offerings, leveraging BIS certification as a compliance wedge against unqualified imports.
For Investors and Strategic Acquirers: EU REACH nickel migration restrictions reshape the acquisition landscape by consolidating market share among pre-certified manufacturers and stranding legacy inventory held by non-compliant suppliers. Long-term viability favors vertically integrated specialists with captive alloy supply and multi-channel distribution architecture. The signal to watch is FDA food-contact substance notification backlogs, which freeze new alloy formulations and create acquisition windows for cleared product portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Bypasses eroding brick-and-mortar margins and captures video-driven discovery behavior in US and German metros. |
| Subscription Sharpening Service Launch | Creates recurring revenue attachment that defends against ceramic substitution and extends customer lifetime value. |
| ISO 8442-5 Certification Investment | Enables export-grade positioning and filters uncertified competitors from professional procurement shortlists. |
| Backward Integration into Alloy Supply | Reduces scrap metal price exposure and secures proprietary formulation control for premium laminated steel lines. |
| Indian E-Commerce Market Entry | Captures urban middle-class expansion through Flipkart and Amazon India before heritage brands establish presence. |
Research Approach
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. The research team conducted structured conversations with executive chefs, restaurant group procurement managers, cutlery manufacturing engineers, and specialty retail buyers across Germany, Japan, and the United States. Secondary validation drew from FDA food-contact substance notifications, EU REACH compliance databases, METI JIS standard revisions, and customs trade records for alloy and finished blade movements. Bottom-up segment sizing triangulated against top-down market value estimates derived from manufacturer revenue disclosures.
Calibration against historical replacement cycle data and professional kitchen penetration rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include blade geometry type, alloy composition tier, end-use intensity, and geographic regulatory cluster. CAGRs were derived from regression analysis of correlated variables including restaurant density growth, e-commerce penetration curves, and certification requirement tightening. Industry-specific forecast inputs incorporated culinary tourism expansion indices and master craftsman demographic projections.
Macroeconomic conditions sit as an overlay; deviation in scrap metal pricing, energy cost shocks affecting Solingen cluster operations, or abrupt FDA notification delays would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and professional chef employment growth. Quarterly review of EU REACH amendment proposals, METI standard revision timelines, and Indian BIS certification queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Modular Zero-Waste Kitchen Appliance Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market
Kitchen Appliances
United States Small Kitchen Appliances Market
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Residential Cooking Grills Market
Kitchen Appliances
Electric Countertop Griddles Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
Temperature Controlled Mug Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
France Cookware Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market