
 Smart Kitchen Appliances Market | 2026-2036
Smart Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Kitchen Appliances Market Intelligence
The direct-to-consumer sales channel, amplified by digital retail platforms, is rewriting traditional appliance distribution models. Samsung leverages its strong brand recognition and digital ecosystem to engage customers directly. Miele sustains its premium positioning through controlled, high-touch online and offline experiences. Haier Group competes on a global scale by adapting its multi-brand strategy to various regional e-commerce ecosystems.
Smart kitchen appliances are household devices enhanced with connectivity and computational capabilities. These products integrate sensors and Wi-Fi or Bluetooth modules, allowing remote control, monitoring, and automation via smartphone apps or voice assistants. Within the product landscape, Smart Refrigerators and Smart Ovens command significant value due to their complexity and high price points. Among technologies, Wi-Fi and IoT Integration are foundational, while Voice Control represents the fastest-growing interface for Residential Users.
Product design is shaped by a confluence of international regulations. In the United States, devices must comply with FCC standards for wireless communication and EPA Energy Star criteria. European market entry requires CE marking for safety and adherence to GDPR for user data protection. Navigating the fragmented landscape of data privacy protocols and interoperability standards remains a critical strategic challenge for manufacturers.
Market Dynamics
The market's central dynamic is the tension between rapid feature expansion, driven by IoT integration, and the increasing friction from fragmented data privacy regulations like GDPR, which complicates global product design and deployment for manufacturers.
Growth Catalysts
- Energy Efficiency Mandates:Regulations like the EPA Energy Star criteria in the United States steer Residential Users toward smart appliances designed to optimize power consumption.
- IoT Technology Maturation:The widespread availability of residential Wi-Fi provides the foundational connectivity for remote control and automation features demanded by modern consumers.
- Voice Control Ecosystems:Integration with popular voice assistants simplifies user interaction, serving as a key purchase driver for consumers in developed markets like Germany.
Market Restraints
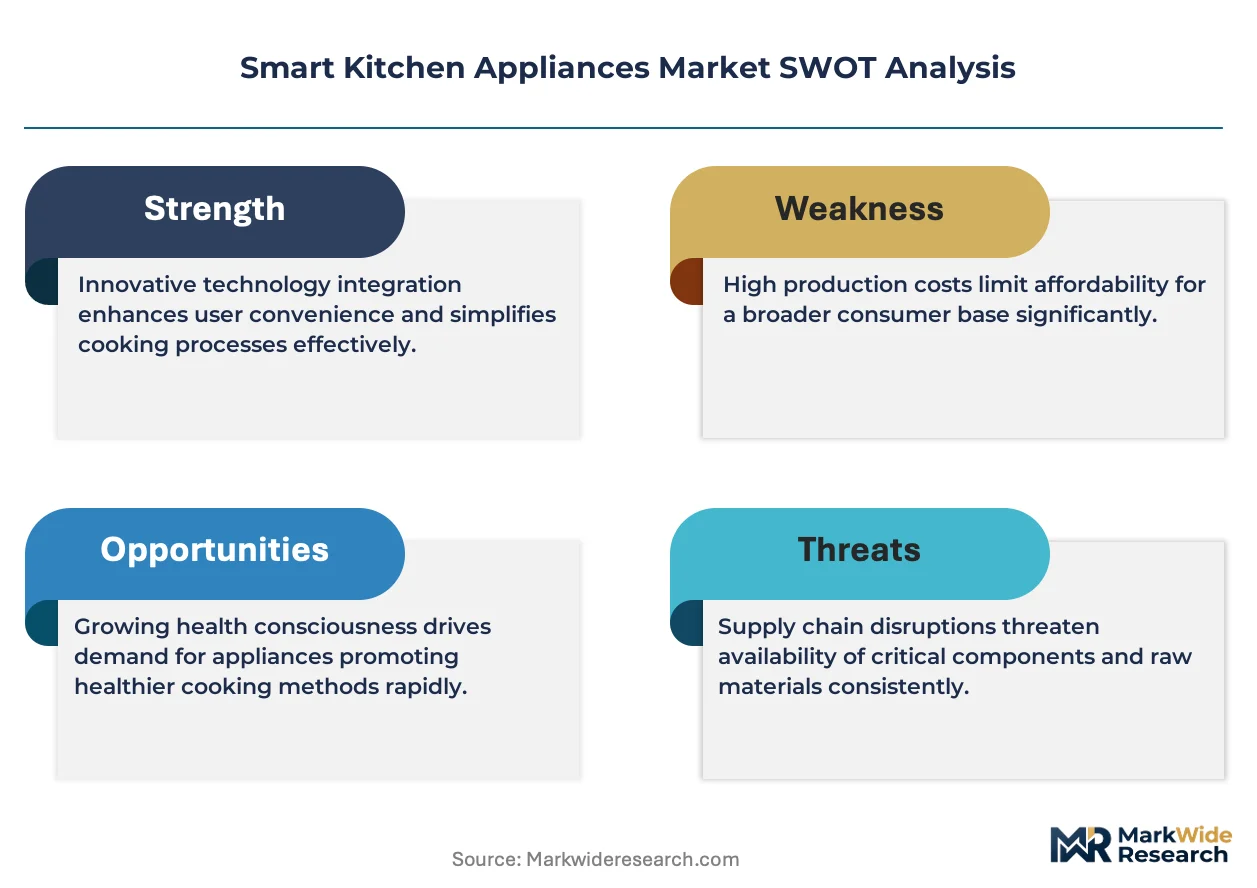
- High Price Points:The inclusion of sensors, connectivity modules, and advanced software results in a significant price premium over traditional appliances, limiting adoption to less price-sensitive households.
- Interoperability Failures:A lack of universal communication standards creates fragmented ecosystems where devices from different manufacturers often fail to communicate, diminishing the overall value proposition for users.
- Data Privacy Regulations:Strict regulations such as Europe's GDPR create compliance burdens and development delays, limiting the types of data-driven services manufacturers can offer.
Strategic Opportunities
- Predictive Maintenance Services:Leveraging sensor data to offer subscription-based services that predict component failure and schedule proactive repairs represents a new recurring revenue stream.
- AI-Powered Nutrition:Integrating AI for personalized meal planning and dietary tracking, connecting smart refrigerators with smart ovens to automate cooking processes, offers significant value.
- Underpenetrated Geographies:Expanding into emerging urban middle-class populations in countries like Brazil and India presents a substantial opportunity for volume growth.
Industry Challenges
- Regulatory Fragmentation:Manufacturers face significant overhead in ensuring products comply with a patchwork of disparate standards, including FCC rules in the US and CE marking in Europe.
- Cybersecurity Threats:The increasing connectivity of appliances creates new attack vectors, requiring constant software updates and robust security protocols to protect user data and prevent device hijacking.
- Third-Party Platform Dependency:Reliance on external voice assistant and smart home ecosystems creates a risk of platform policy changes or API deprecation impacting appliance functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Kitchen Appliances Market |
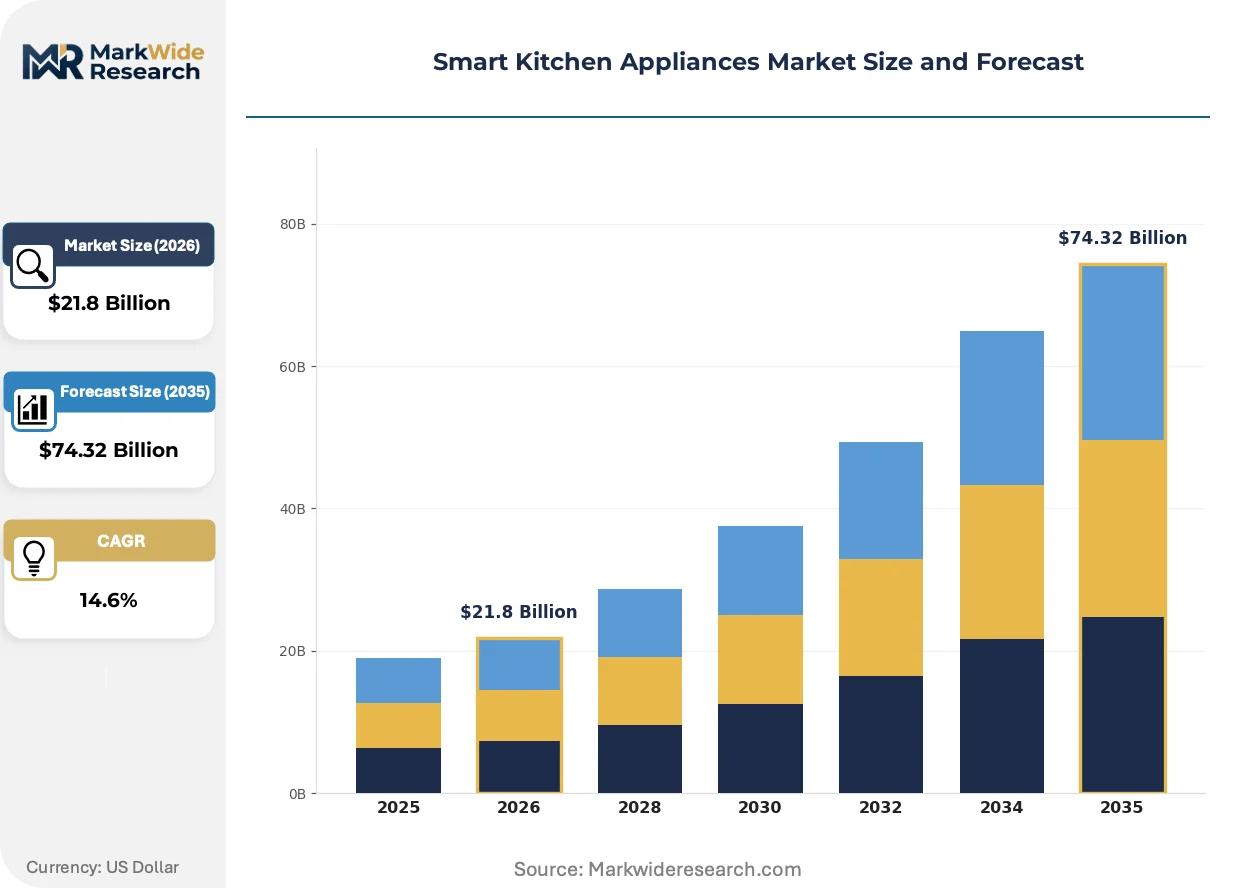
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $74.32 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Ovens, Smart Refrigerators, Smart Dishwashers, Smart Cookware Technology: Wi-Fi, Bluetooth, Voice Control, IoT Integration End User: Residential Users, Professional Chefs, Food Enthusiasts, Hospitality Industry Installation: Built-in, Freestanding, Modular, Connected |
| Companies Covered | Haier Group, Miele, Samsung, GE Appliances, Panasonic Holdings Corporation, LG Electronics, Whirlpool Corporation, Koninklijke Philips N.V., Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Kitchen Appliances Market Strategic Shifts & Innovations
The market is shifting from selling discrete, connected hardware to cultivating integrated digital ecosystems. This evolution redefines product value around software-driven services, data-driven personalization, and long-term user engagement rather than just mechanical performance.
Edge AI processing in appliances allows for on-device machine learning for complex tasks like food item recognition. Premium product lines are seeing adoption by tech-forward Residential Users seeking enhanced privacy and responsiveness. This on-device intelligence is rendering obsolete the sole reliance on cloud processing for core smart features, reducing latency and data security risks.
Europe's General Data Protection Regulation (GDPR) mandates strict controls on how personal data from connected devices is managed. The regulation forces manufacturers to embed privacy-by-design principles, impacting software development and data storage architecture. Smart refrigerators are most affected, requiring redesigned user interfaces for transparent data consent before collecting dietary or usage habits.
Consumer purchasing decisions are coalescing around smart home software ecosystems. This shift disrupts traditional brand loyalty, as appliance selection now often depends on compatibility with a preferred platform like those from Google or Amazon. This behavior is most visible among urban consumers in the United States and South Korea, where smart home adoption is highest.
Smart Kitchen Appliances Market Segmentation
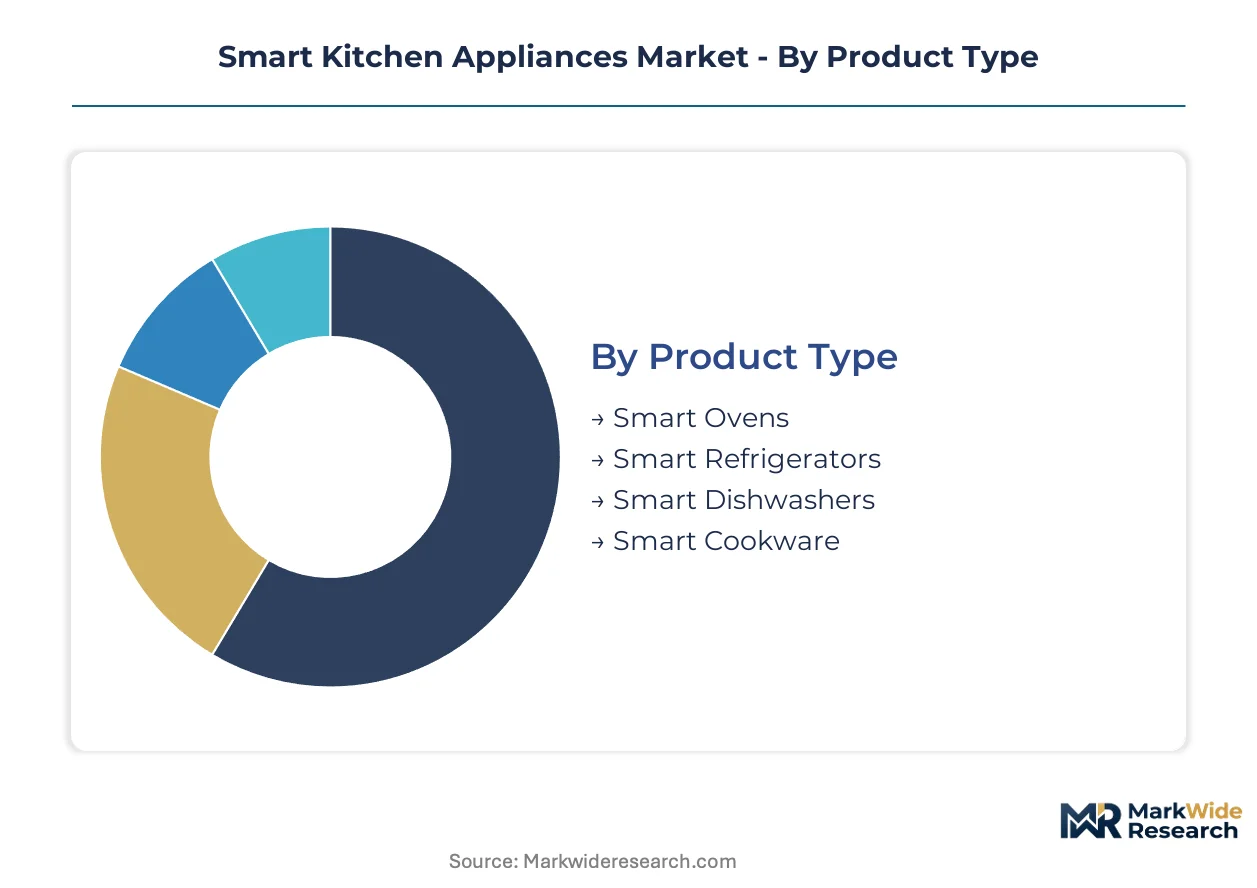
The Smart Kitchen Appliances Market is diverse, with distinct segments reflecting varying consumer needs, technological advancements, and integration preferences. Understanding these classifications is crucial for manufacturers to tailor product development and market strategies effectively.
Product Type:
Product types in smart kitchen appliances exhibit varied replacement cycles, influencing market velocity.
- Smart Refrigerators:These large appliances integrate advanced sensors, cameras, and connectivity for inventory management and personalized recommendations. Urban consumers in the United States and Germany prioritize these units for convenience and energy efficiency, driving demand.
- Smart Ovens:Connected ovens feature precision temperature control, automated cooking programs, and remote preheating capabilities via smartphone applications. Residential Users in South Korea increasingly adopt smart ovens for automated cooking and integration with broader smart home ecosystems.
- Smart Dishwashers:These appliances offer optimized wash cycles, remote start, and detergent reordering through integrated Wi-Fi modules.
- Smart Cookware:Connected pots and pans provide real-time temperature feedback and recipe guidance, enhancing precision for home cooks.
Smart Refrigerators dominate the installed appliance base. Smart Ovens are where expansion concentrates.
Technology:
Technology components within smart kitchen appliances span foundational elements to rapidly maturing interfaces.
- Wi-Fi:Wi-Fi modules enable high-bandwidth data exchange, facilitating remote control, firmware updates, and cloud-based service integration for appliances. Residential Users across urban centers in the United States rely on Wi-Fi for seamless interaction with their smart home ecosystems.
- IoT Integration:IoT integration embeds sensors and software into appliances, allowing them to collect data, communicate with other devices, and automate tasks. Manufacturers prioritize IoT integration to offer predictive maintenance services and AI-powered nutrition platforms, attracting tech-forward consumers.
- Voice Control:Voice control interfaces, often leveraging third-party ecosystems, simplify hands-free operation and recipe navigation for appliances.
- Bluetooth:Bluetooth modules provide short-range, low-power connectivity for local device pairing and direct control via nearby smartphones.
Wi-Fi connectivity remains ubiquitous. Voice Control interfaces are gaining share most quickly among user interaction methods.
End User:
End user segments vary by their scale of appliance deployment and specific functional requirements.
- Residential Users:Individual households seeking convenience, energy efficiency, and integrated smart home experiences for daily cooking and food management. Urban consumers in Germany and the United States drive significant volume, prioritizing appliances that align with energy efficiency mandates like EPA Energy Star.
- Hospitality Industry:Hotels, restaurants, and catering services deploying smart appliances for operational efficiency, precise cooking, and waste reduction. Large-scale commercial kitchens adopt smart ovens and refrigerators to streamline processes and optimize resource consumption, particularly in developed markets.
- Professional Chefs:Culinary experts utilize smart appliances for precise temperature control, consistent results, and advanced cooking techniques in high-end settings.
- Food Enthusiasts:Consumers with a passion for cooking invest in smart cookware and specialized appliances to experiment with new recipes and enhance culinary skills.
Residential Users represent the largest volume segment. The Hospitality Industry offers significant value expansion opportunities.
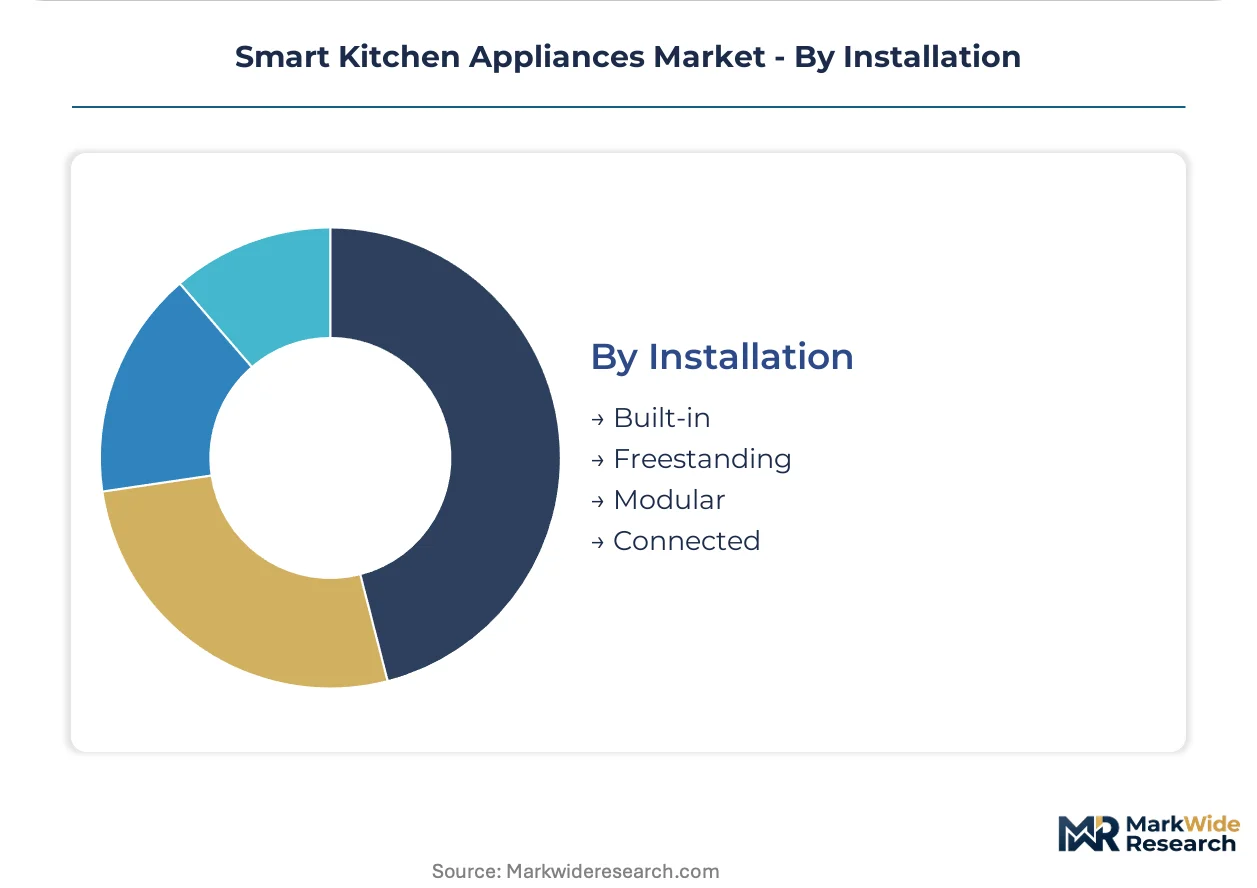
Installation:
Installation types dictate the level of integration and flexibility within diverse kitchen designs.
- Built-in:Appliances designed for seamless integration into cabinetry and countertops, offering a sleek, unified kitchen aesthetic. Premium households in Germany invest in built-in smart ovens and refrigerators for sophisticated kitchen designs and long-term property value enhancement.
- Freestanding:Self-contained units that can be placed independently, offering flexibility in kitchen layout and easier installation or replacement. Residential Users in urban centers across the United States favor freestanding smart appliances for their adaptability and ease of upgrade.
- Modular:Component-based systems allowing users to customize and expand their smart kitchen setup incrementally with specialized units.
- Connected:Appliances designed primarily for network connectivity and remote operation, often as standalone or portable smart kitchen gadgets.
Built-in solutions cater to aesthetic integration. Freestanding options provide greater functional flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy efficiency mandates and stringent data privacy regulations significantly influence smart kitchen appliance adoption globally. These policies steer residential users toward devices designed for optimized power consumption and secure data handling. Governments actively promote smart home integration through various initiatives, shaping market development.
United States
Residential users in the United States prioritize convenience and energy efficiency in smart kitchen appliances, seeking seamless integration. Devices must comply with FCC standards for wireless communication and EPA Energy Star criteria for energy optimization. Urban centers across the US, particularly tech hubs like Silicon Valley, drive demand for advanced integrated smart home ecosystems.
Germany
German consumers seek premium smart kitchen appliances with high-touch user experiences and robust build quality. European market entry requires CE marking for safety and adherence to GDPR for user data protection. Munich and Berlin urban areas show strong demand for sophisticated built-in smart ovens and refrigerators, reflecting a preference for integrated design.
South Korea
South Korean households increasingly adopt smart ovens for automated cooking and seamless integration with broader smart home ecosystems. The national data privacy protocols, enforced by MFDS, shape product design for connected devices and user consent. Seoul's tech-forward population drives innovation in smart appliance functionality, particularly for AI-powered features.
Japan
Japanese consumers demand high-tech home appliances and space-efficient designs tailored for urban living environments. Manufacturers must comply with JIS standards for product quality and safety across the appliance range. Tokyo's dense metropolitan areas concentrate demand for advanced smart refrigerators and integrated kitchen systems, valuing both innovation and compactness.
Smart Kitchen Appliances Market Key Industry Players
On the supply side, the industry is characterized by a blend of established appliance manufacturers and emerging technology innovators. This creates a tiered structure, with global conglomerates competing alongside specialized smart home solution providers. Key strategic archetypes include diversified electronics giants leveraging broad digital ecosystems, premium lifestyle brands focused on high-touch experiences, and value-oriented multi-brand players. Companies are actively pursuing digital ecosystem development, direct-to-consumer sales models, and strategic partnerships to capture market share.
At the scale-driven end, Haier Group exemplifies a multi-brand strategy, adapting its offerings to diverse regional e-commerce ecosystems globally. Samsung, a diversified electronics giant, leverages its strong brand recognition and extensive digital ecosystem to engage customers directly, focusing on integrated smart home experiences. Miele represents the premium segment, sustaining its high-end positioning through controlled, high-touch online and offline experiences for discerning consumers. These players anchor different market segments, driving innovation in connectivity, user interface design, and service offerings across the smart kitchen appliance landscape.
| Leading Market Players |
|---|
| Haier Group |
| Miele |
| Samsung |
| GE Appliances |
| Panasonic Holdings Corporation |
| LG Electronics |
| Whirlpool Corporation |
| Koninklijke Philips N.V. |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
South Korea's advanced manufacturing clusters for electronics significantly influence smart kitchen appliance production capacity. This concentration of specialized component suppliers and assembly expertise dictates potential pricing leverage for global brands.
Pricing Analysis
Certification compliance, including CE marking in Europe and EPA Energy Star in the United States, creates the primary pricing spread. The pricing model often follows a tiered premium-mid-economy differentiation, reflecting brand premium and advanced feature sets. High component costs from IoT integration and advanced software create upward pricing pressure. Residential users seeking energy efficiency show less price sensitivity for premium, compliant models.
Supply Chain Analysis
Fragmented data privacy regulations, such as Europe's GDPR, act as a control on smart appliance technology flows, complicating global product deployment. Supply concentration centers on South Korea, China, and Mexico for electronics manufacturing and assembly. Key dependencies include sensors, Wi-Fi modules, and specialized AI processors. Regulatory fragmentation poses a structural risk to product development and market entry. Distribution runs through direct-to-consumer channels and digital retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart kitchen appliance market requires specialized capabilities in navigating complex regulatory landscapes and ensuring seamless interoperability. This scarcity of cross-functional expertise limits manufacturers' ability to scale globally.
For Market Incumbents: Entrench market position by deepening digital ecosystem integration and investing in proprietary AI-powered services. Leverage strong brand recognition to counter third-party platform dependency risks. Accelerate R&D into universal interoperability standards to mitigate fragmentation, thereby strengthening customer loyalty against emerging tech-focused entrants.
For New Entrants and Emerging Players: Pursue underpenetrated geographies like Brazil and India, targeting urban middle-class populations with value-oriented smart solutions. Focus on subscription-based predictive maintenance services as a go-to-market angle, offering recurring revenue streams. Develop platform-agnostic devices that integrate with multiple voice control ecosystems to reduce user friction.
For Investors and Strategic Acquirers: Long-term, this sits as a software-driven ecosystem play because product value increasingly derives from data-driven services and digital engagement. Target specialized AI/IoT software firms or niche hardware developers with strong interoperability intellectual property. The signal to watch is the widespread adoption of standardized communication protocols across different appliance brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Universal Interoperability Standard | Reduces user friction and expands smart home ecosystem compatibility, driving broader adoption. |
| Launch AI-Powered Nutrition Platform | Offers personalized meal planning and dietary tracking, creating new value-added services for consumers. |
| Expand Direct-to-Consumer Channels | Strengthens brand control and customer relationships, bypassing traditional retail intermediaries. |
| Invest in Edge AI Processing | Enhances device responsiveness and user data privacy by reducing reliance on cloud processing. |
| Target Urban Centers in Emerging Markets | Captures volume growth from new middle-class populations in previously untapped geographies. |
Research Approach
Cross-validation between extensive primary interviews and robust secondary research anchors the qualitative findings and quantitative projections. Primary data collection involved conversations with product managers, R&D directors, and supply chain executives. Secondary sources included regulatory filings (FCC, CE marking), industry association reports, and patent databases. This approach ensures comprehensive bottom-up and top-down triangulation for market sizing.
Volume and value projections undergo rigorous calibration across the analysis window, utilizing a multi-layered analytical framework. Segmentation dimensions modeled include product type, technology, end user, installation, and regional regulatory compliance. Historical growth rates and future projections inform compound annual growth rates. Forecast inputs incorporate IoT integration costs and voice assistant ecosystem penetration.
Sensitivities concentrate around evolving regulatory fragmentation, rapid technological breakthroughs in AI, and platform policy changes by major tech companies. Forecasts reflect current market assumptions and known industry dynamics. Material shifts in data privacy regulations or interoperability standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Europe Household Appliances Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
Ceramic Coated Cookware Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Europe Small Kitchen Appliances Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
India Electric Vegetable Choppers Market