
 Kitchen Appliances Market | 2026-2036
Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Appliances Market Intelligence
Multi-source component procurement is rebalancing toward vertically integrated in-house manufacturing of compressors and control systems. Whirlpool Corporation leverages captive production of refrigeration platforms to shield margin pools from semiconductor volatility. Bosch anchors its European supply base through precision-motor manufacturing in Germany. Samsung Electronics competes by controlling display panel and IoT module sourcing for its smart appliance lineup.
Kitchen appliances encompass electrically or gas-powered equipment designed for food preservation, preparation, cooking, and cleaning, typically operating at 110-240V with energy consumption ratings measured in kilowatt-hours annually. Their primary commercial purpose spans residential meal production through high-volume foodservice operations requiring standardized output and safety compliance. Refrigerators and dishwashers occupy the mature volume core where replacement cycles and efficiency regulations sustain steady revenue. Smart connectivity and sensor technology represent the fastest-expanding technology dimension, as Wi-Fi-enabled diagnostics and automated cooking programs command premium positioning. The foodservice operator customer segment concentrates margin pools, with restaurants and catering companies prioritizing durability certifications and rapid-service throughput over upfront cost.
The US Department of Energy enforces minimum efficiency standards under ENERGY STAR certification, directly limiting market access for non-compliant refrigeration and cooking equipment. The EU Ecodesign Directive and REACH chemical safety framework jointly reshape material selection and end-of-life recyclability requirements for appliances sold across Europe. China's GB standards and MIIT circular economy mandates are accelerating domestic manufacturer consolidation around modular, repairable designs. Stakeholders must monitor how divergent efficiency timelines across Washington, Brussels, and Beijing fragment product platform strategies and certification costs.
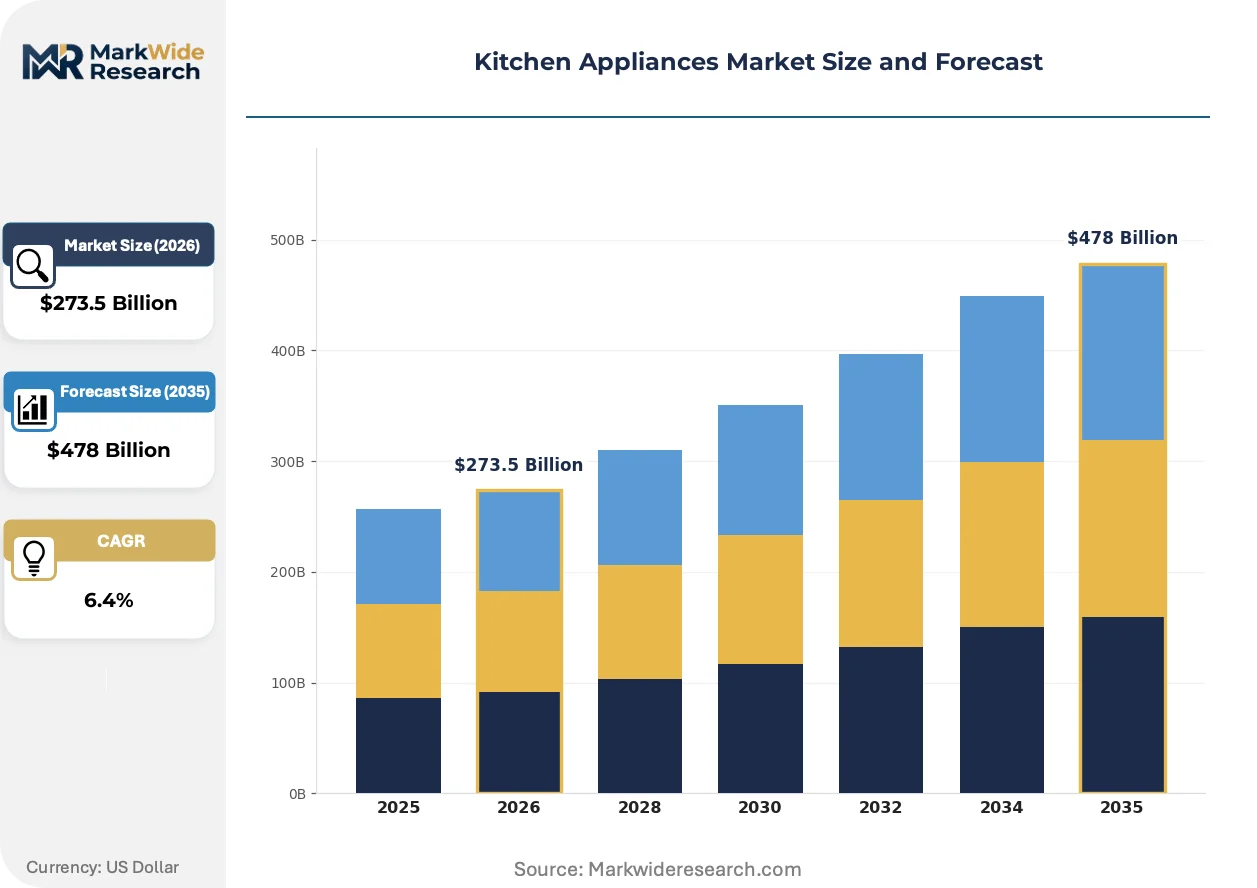
Market Dynamics
Connected cooking ecosystems are reconfiguring demand patterns as residential buyers prioritize Wi-Fi-enabled diagnostics and automated meal programs over standalone functionality. This shift compresses replacement cycles and elevates software integration to a primary purchase criterion.
Growth Catalysts
- EU Ecodesign Directive:Efficiency mandates for refrigerators and dishwashers force technology upgrades across member states, accelerating premium product turnover.
- Urban middle-class concentration:Tier-one Chinese cities drive penetration of smart kitchen systems as household formation rates sustain appliance expenditure.
- Sensor-enabled automation:Precision temperature control and predictive maintenance capabilities command price premiums in residential segments.
Market Restraints
- Semiconductor supply volatility:Control chip shortages disrupt compressor and IoT module availability, extending order lead times for manufacturers dependent on external foundries.
- REACH chemical compliance:European material restrictions limit coating and insulation options, raising reformulation costs for export-bound product lines.
- Natural gas infrastructure decay:Aging distribution networks in mature markets constrain gas-powered cooking equipment placement in new residential construction.
Strategic Opportunities
- Modular repairable designs:China's MIIT circular economy mandates reward manufacturers with standardized component architectures and extended service lifecycles.
- Foodservice durability certification:Rapid-service restaurants prioritize throughput-validated equipment, creating margin pools distinct from price-sensitive residential channels.
- Voice-activated recipe integration:Convergence of natural language processing with cooking automation opens subscription revenue streams for appliance-software bundles.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for real-time cooking algorithms outpaces available talent pools in traditional appliance manufacturing regions.
- Cross-border efficiency standard misalignment:Divergent ENERGY STAR, Ecodesign, and GB certification timelines fragment platform strategies and inflate testing expenditure.
- Legacy kitchen footprint retrofit complexity:Smart appliance installation demands electrical and connectivity infrastructure upgrades in aging housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Appliances Market |
| Market Size in 2026 | $273.5 Billion |
| Market Size in 2035 | $478 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Microwaves, Dishwashers, Coffee Makers, Blenders, Food Processors Technology: Smart Connectivity, Energy Efficient, Touch Control, Voice Activated, Sensor Technology, Induction Application: Home Kitchens, Commercial Kitchens, Outdoor Cooking, Cafeterias, Catering Services, Food Trucks Customer Type: Individual Consumers, Restaurants, Hotels, Cafes, Catering Companies, Foodservice Operators |
| Companies Covered | Whirlpool Corporation, GE Appliances, Bosch, Gaggenau, Electrolux, LG Electronics, Miele, Frigidaire, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Appliances Market Strategic Shifts & Innovations
Software-defined functionality is displacing hardware differentiation as the primary competitive axis. Appliance manufacturers now compete on algorithm quality and ecosystem integration rather than mechanical reliability alone.
Induction heating technology is rewriting energy transfer economics in residential cooking. High-efficiency magnetic coil systems reduce heat loss by ninety percent versus conventional resistive elements. Premium kitchen renovators specify induction ranges as standard equipment. This compression of energy consumption is rewriting cost-of-ownership calculations and accelerating gas-to-electric switching in European and East Asian markets.
The EU F-Gas Regulation tightens hydrofluorocarbon phase-down schedules for refrigeration insulation and cooling circuits. Appliance manufacturers reformulate foam blowing agents and compressor refrigerants to maintain market access. Cold-chain equipment and domestic refrigerators face disproportionate compliance burden, driving consolidation toward scale players with captive chemistry capabilities.
Direct-to-consumer configuration platforms now displace traditional retail specification. Buyers customize finish, sensor packages, and connectivity tiers through manufacturer websites before fulfillment. This channel compression is most visible in North American and Western European premium segments where brand-owned experience design commands loyalty and reduces price transparency.
Kitchen Appliances Market Segmentation
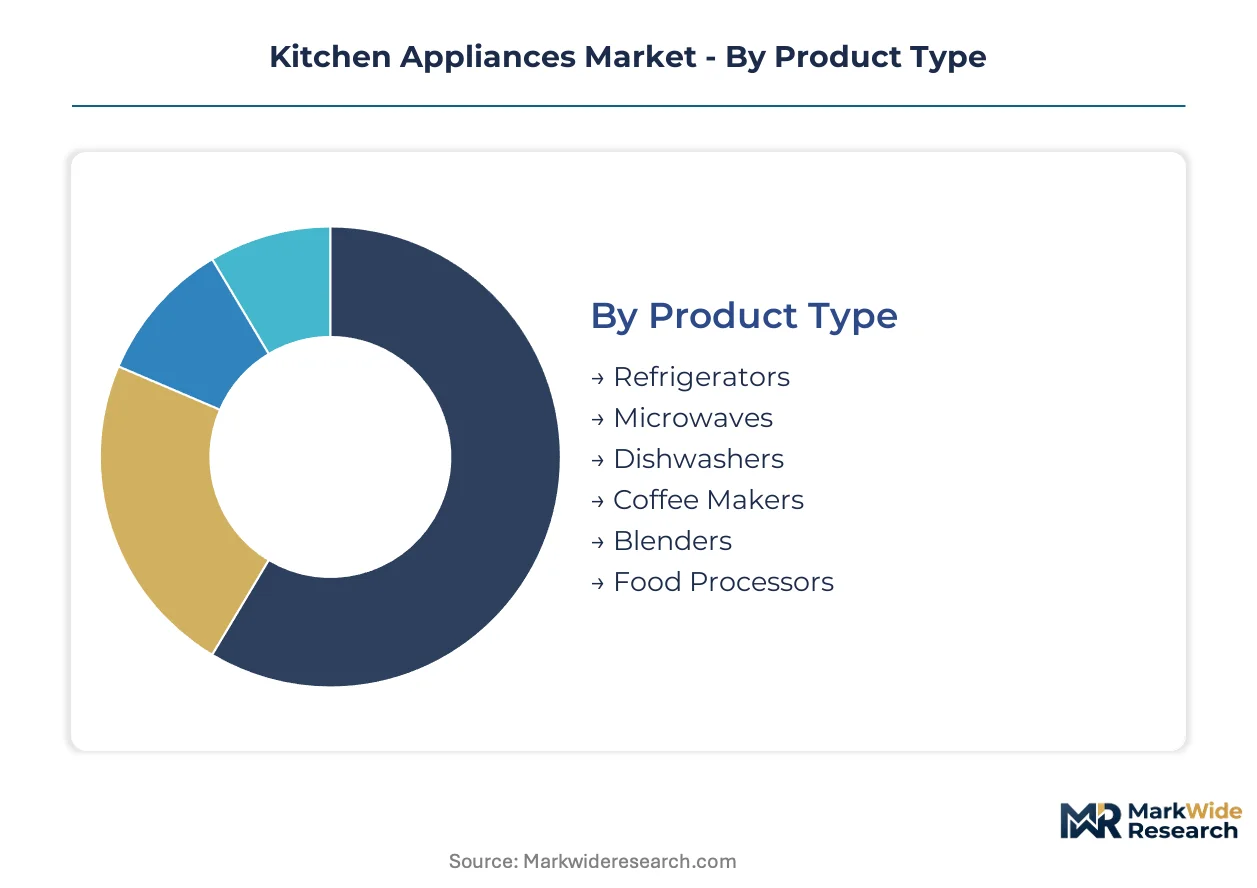
Kitchen appliances fragment across four intersecting dimensions. Product type determines replacement cadence and margin structure. Technology tier separates premium positioning from commodity competition.
Product Type:
Cooling platforms anchor volume, while convenience appliances capture discretionary upgrade cycles.
- Refrigerators:Compressor-based cooling systems with variable-speed drives and multi-zone temperature management. Demand concentrates in Chinese tier-one cities where urban middle-class households prioritize connected inventory management systems. EU Ecodesign Directive efficiency minimums accelerate premium turnover.
- Dishwashers:Pump-and-spray systems with soil sensors and water-recirculation architecture. Foodservice operators in North America and Western Europe drive commercial-grade specification for throughput-validated durability certifications.
- Microwaves:Magnetron-based rapid heating with inverter power control.
- Coffee Makers:Pressure-brewing and precision-temperature extraction systems.
- Blenders:High-torque motor platforms with variable-speed blade assemblies.
- Food Processors:Multi-function cutting and mixing attachments with safety-interlock mechanisms.
Mature deployment sits with refrigerators. Newer deployment is concentrated in coffee makers and smart-enabled convenience appliances.
Technology:
Control interfaces and energy transfer mechanisms now dominate purchase criteria over mechanical reliability.
- Smart Connectivity:Wi-Fi-enabled diagnostics, remote monitoring, and ecosystem integration through proprietary apps. Residential buyers in premium segments prioritize automated meal programs and predictive maintenance alerts.
- Energy Efficient:ENERGY STAR-certified platforms with optimized compressor cycles and insulation chemistry. US Department of Energy minimums limit market access for non-compliant refrigeration equipment.
- Touch Control:Capacitive interface panels with haptic feedback.
- Voice Activated:Natural language processing integration for hands-free operation.
- Sensor Technology:Precision temperature and occupancy detection for automated adjustment.
- Induction:Magnetic coil energy transfer reducing heat loss versus resistive elements.
Volume concentration remains with energy-efficient baseline specification. Sensor-enabled automation is climbing the fastest among technology tiers.
Application:
End-use context dictates durability requirements, connectivity infrastructure, and certification standards.
- Home Kitchens:Residential meal production environments with standardized electrical infrastructure. Individual consumers in developed markets drive replacement cycles through renovation activity and efficiency upgrade incentives.
- Commercial Kitchens:High-throughput foodservice operations requiring NSF sanitation certification and rapid-recovery thermal systems. Restaurants prioritize durability-validated equipment over upfront cost minimization.
- Outdoor Cooking:Weather-resistant portable and built-in equipment for exterior installation.
- Cafeterias:Institutional-scale batch preparation with standardized portion control.
- Catering Services:Mobile equipment platforms with rapid deployment and breakdown requirements.
- Food Trucks:Space-constrained mobile kitchens with generator or battery power compatibility.
Replacement demand concentrates in home kitchens. Commercial kitchens generate the steepest expansion trajectory for connected equipment with throughput analytics.
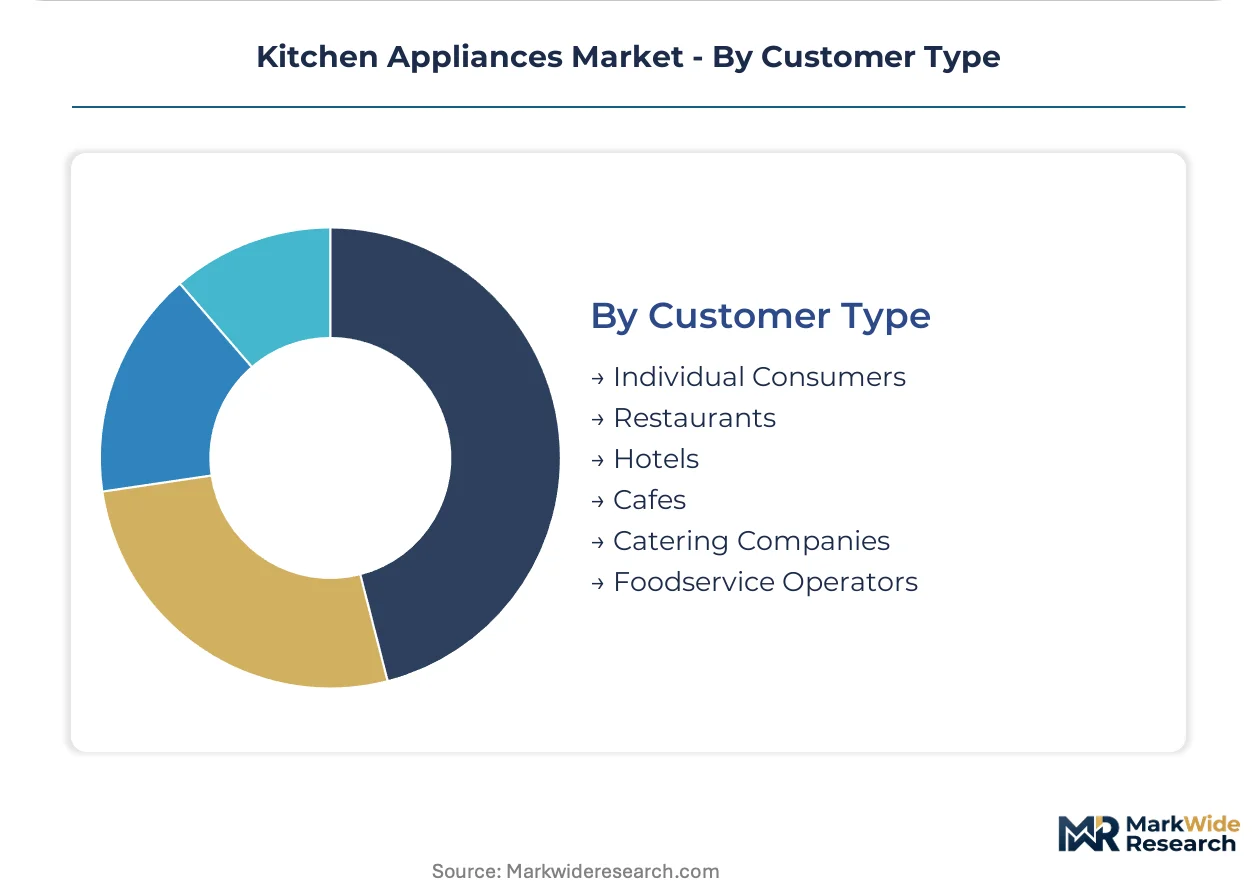
Customer Type:
Procurement authority separates price-sensitive residential buyers from margin-prioritizing institutional purchasers.
- Individual Consumers:End-users making discretionary purchase decisions based on feature differentiation and brand positioning. Direct-to-consumer configuration platforms now displace traditional retail specification in North American and Western European premium segments.
- Restaurants:Rapid-service and full-service operators with equipment standardization requirements across multi-unit footprints. Foodservice operators concentrate margin pools through volume procurement and durability certification prioritization.
- Hotels:Hospitality groups with in-room and back-of-house equipment standardization needs.
- Cafes:Beverage-focused operators with specialized coffee equipment requirements.
- Catering Companies:Event-service providers with mobile equipment and rapid-deployment specifications.
- Foodservice Operators:Institutional and contract food management companies with centralized procurement.
Volume ownership sits with individual consumers. Margin capture is concentrating fastest among foodservice operators with standardization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and aluminum feedstock availability from Chinese and German industrial bases anchors regional manufacturing capacity for compressor housings and cooking surfaces.
United States
Residential renovation cycles and ENERGY STAR rebate programs drive refrigerator and dishwasher replacement demand. The US Department of Energy enforces minimum efficiency standards that limit market access for non-compliant equipment. Michigan and Ohio industrial corridors host captive compressor manufacturing for major appliance brands.
Germany
Premium kitchen renovation spending and commercial foodservice standardization sustain demand for durability-certified equipment. The EU Ecodesign Directive and REACH chemical safety framework reshape material selection and end-of-life recyclability requirements. Bavaria and Baden-Württemberg precision-motor manufacturing clusters supply European appliance assembly networks.
China
Urban middle-class household formation in tier-one cities accelerates smart appliance penetration and connected cooking ecosystem adoption. MIIT circular economy mandates and GB standards reward modular, repairable design architectures. Yangtze River Delta manufacturing bases concentrate refrigerator compressor and IoT module production.
Japan
Space-constrained residential kitchens and aging housing stock drive compact, high-efficiency appliance specification. METI energy conservation standards and JIS certification requirements constrain import competition. Kansai region industrial corridors maintain specialized motor and sensor component fabrication.
South Korea
Apartment-dwelling households and government-led smart home initiatives expand connected appliance deployment. MFDS electrical safety regulations and energy labeling frameworks govern product market entry. Seoul Capital Area technology corridors integrate display panel and semiconductor sourcing for smart kitchen equipment.
Kitchen Appliances Market Key Industry Players
Backward integration into core components dominates the current landscape as manufacturers seek insulation from semiconductor volatility and refrigerant supply constraints. The vendor base organizes around three tiers: diversified conglomerates with captive electronics supply, specialized premium fabricators with regional manufacturing depth, and scale-driven assemblers competing on procurement efficiency. Strategic archetypes include ecosystem integrators bundling software subscriptions with hardware, efficiency specialists capturing regulatory upgrade cycles, and foodservice durability validators. M&A activity and capacity expansion represent the dominant competitive moves, with particular concentration around compressor technology and IoT platform assets.
Among diversified conglomerates, Samsung Electronics and LG Electronics occupy positions exemplifying ecosystem integration through display and semiconductor captive supply. Whirlpool Corporation anchors the North American manufacturing archetype with in-house refrigeration platform production. Miele represents the premium-tier specialist fabricator, situating within German precision-engineering traditions. Bosch occupies a position bridging European regulatory compliance leadership with commercial foodservice certification depth.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| GE Appliances |
| Bosch |
| Gaggenau |
| Electrolux |
| LG Electronics |
| Miele |
| Frigidaire |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
Captive production of compressors and control systems anchors both supply security and pricing power for manufacturers shielding margin pools from semiconductor volatility. This backward integration into core components allows premium-tier players to maintain price discipline while commodity assemblers face cost compression from external foundry dependencies.
Pricing Analysis
Warranty and predictive maintenance bundling now separates premium positioning from unbundled transactional sales in residential channels. Three-tier pricing structure across premium, standard, and economy levels reflects ENERGY STAR certification grade and smart connectivity integration. Pricing pressure stems from semiconductor supply constraints extending order lead times for IoT-enabled models. Individual consumers in developed markets exhibit highest price sensitivity, while foodservice operators prioritize durability certification over upfront cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for control chip fabrication, compressing availability for compressor motor drives and Wi-Fi modules. Component sourcing draws from China for steel housings, Germany for precision motors, and Japan for sensor assemblies. Tariff exposure on Chinese steel feedstock threatens margin stability for North American assembly operations. Distribution runs through manufacturer-direct configuration platforms displacing traditional retail specification in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Induction heating technology is displacing conventional gas and resistive cooking platforms, compressing replacement cycles and rewriting energy transfer economics across residential and commercial installations.
For Market Incumbents: Deepen captive production of refrigeration compressors and IoT control modules to insulate margin pools from foundry volatility. Invest in ENERGY STAR and EU Ecodesign certification ahead of tightening efficiency minimums to defend premium positioning against emerging Asian competitors.
For New Entrants and Emerging Players: Voice-activated recipe integration offers a technology-first wedge into subscription revenue streams currently unexploited by hardware-centric incumbents. Target foodservice durability certification as the most penetrable segment, where rapid-service restaurants prioritize throughput validation over brand heritage.
For Investors and Strategic Acquirers: Exit pathways concentrate in ecosystem integrators bundling software subscriptions with hardware platforms. Long-term viability favors manufacturers with modular, repairable design architectures aligned with China's MIIT circular economy mandates. Monitor F-Gas Regulation compliance timelines as the critical inflection signal for refrigeration chemistry capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive production of refrigeration platforms shields margins from semiconductor supply volatility. |
| Smart Appliance Platform Launch | Wi-Fi-enabled diagnostics and automated cooking programs command premium residential positioning. |
| Foodservice Durability Certification Investment | NSF and throughput validation opens margin pools distinct from price-sensitive consumer channels. |
| Direct-to-Consumer Channel Expansion | Manufacturer-owned configuration platforms reduce price transparency and build brand loyalty. |
| Sustainability Repositioning Around F-Gas Compliance | Reformulated foam blowing agents and refrigerants maintain EU market access against phase-down schedules. |
Research Approach
Trade association filings, customs and import-export databases, and regulatory submission records formed the secondary backbone for this analysis. Primary fieldwork encompassed interviews with appliance manufacturing executives, foodservice procurement directors, retail category buyers, and component supply specialists. Bottom-up unit economics triangulated against top-down macroeconomic indicators to establish market sizing across product type, technology tier, and application dimensions.
Historical trendline analysis of replacement cycles, efficiency upgrade patterns, and premium penetration rates informed the projection framework. Segmentation modeling spanned cooling platforms, cooking equipment, convenience appliances, and cleaning systems crossed with smart connectivity, energy efficiency, and sensor technology tiers. CAGRs derived from regression analysis of installed base growth, regulatory mandate timelines, and household formation trajectories. Inputs included ENERGY STAR certification adoption curves and EU Ecodesign Directive implementation schedules.
Several conditions sit outside the modeled scope, including geopolitical trade policy shifts, raw material price spikes, and pandemic-scale supply disruptions. Forecasts reflect documented assumptions around semiconductor supply normalization and efficiency regulation enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
Warming Drawer Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
Household Kitchen Appliances Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
India Electric Vegetable Choppers Market
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
Popcorn Makers Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Cooktop Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
Sandwich Maker Market