
 European Built-In Refrigerator Market | 2026-2036
European Built-In Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
European Built-In Refrigerator Market Foresight
Energy-efficiency class upgrades toward A+++ and beyond is redrawing competitive stakes across the European built-in refrigerator landscape. BSH Hausgeräte leverages its vertical integration into compressor and control-system manufacturing to sustain margin structures in premium cabinetry-integrated lines. Liebherr-Hausgeräte anchors its position through specialized biofresh compartments and alpine-market cold-chain expertise. Miele & Cie. KG differentiates via sensor-driven temperature zones and extended warranty architectures that command price premiums in German and Swiss markets.
A European built-in refrigerator denotes a refrigeration appliance engineered for flush installation within kitchen cabinetry, typically operating through vapor-compression cycles with refrigerants constrained to sub-150 GWP ratings under EU F-Gas phasedowns, and designed to maintain 0-4°C fresh-food compartments alongside -18°C freezer zones for residential and commercial food preservation. Multi-door configurations with independent climate zones capture the fastest expansion in margin contribution as consumers trade up from single-door integrated units. Smart technology features, including Wi-Fi-enabled inventory tracking and energy-optimization algorithms, are gaining traction fastest among hospitality and high-end residential customer types, while compressor-based systems retain dominant share against thermoelectric alternatives due to superior cooling density in constrained cabinet depths.
The EU F-Gas Regulation and Ecodesign Directive jointly mandate refrigerant transitions and minimum efficiency thresholds, forcing OEMs to requalify supply chains around propane-isobutane blends and variable-speed compressors. CE marking under the MDR-equivalent appliance safety framework governs electrical and thermal safety for cabinet-integrated installations, creating compliance barriers for non-European entrants. Stakeholders must monitor refrigerant-phaseout timetables and efficiency-tier migrations to anticipate which product architectures will retain distribution access across EU member states.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choices across the European built-in refrigerator supply base, forcing compressor redesigns around propane-isobutane blends and variable-speed architectures before 2030 phaseout milestones.
Growth Catalysts
- Premium Kitchen Renovations:Residential replacement cycles in Germany and France are shortening as consumers prioritize cabinetry-integrated refrigeration during whole-kitchen overhauls.
- Ecodesign Directive Efficiency Tiers:Minimum energy performance standards are pulling demand toward A+++ rated units, expanding addressable market for high-efficiency compressor systems.
- Modular Kitchen Integrations:Italian and Spanish kitchen manufacturers are specifying built-in refrigeration as standard in new residential developments.
Market Restraints
- Refrigerant Transition Costs:R&D and retooling expenses for lower-GWP compressor systems are concentrating among mid-tier OEMs with limited captive engineering capacity.
- Supply Concentration in Compressor Motors:Sourcing of variable-speed drive components remains concentrated among a narrow supplier base in Central Europe.
- Installation Complexity:Flush-mount cabinetry integration requires certified technician labor, creating friction in markets with installer shortages.
Strategic Opportunities
- Smart Technology Convergence:Wi-Fi-enabled inventory tracking and energy-optimization algorithms are creating new value pools in hospitality and high-end residential segments.
- Spain and Italy Corridor Expansion:Underpenetrated modular kitchen markets in Southern Europe offer white space for multi-door configuration penetration.
- CE Marking Compliance Services:Non-European entrants facing MDR-equivalent appliance safety barriers create demand for third-party certification support.
Industry Challenges
- Refrigerant Requalification Timelines:Compressed F-Gas phaseout schedules are forcing simultaneous supply chain reconfiguration and product recertification.
- Cross-Border Installation Standards:Divergent national electrical and thermal safety requirements for cabinet-integrated units complicate pan-European product planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | European Built-In Refrigerator Market |
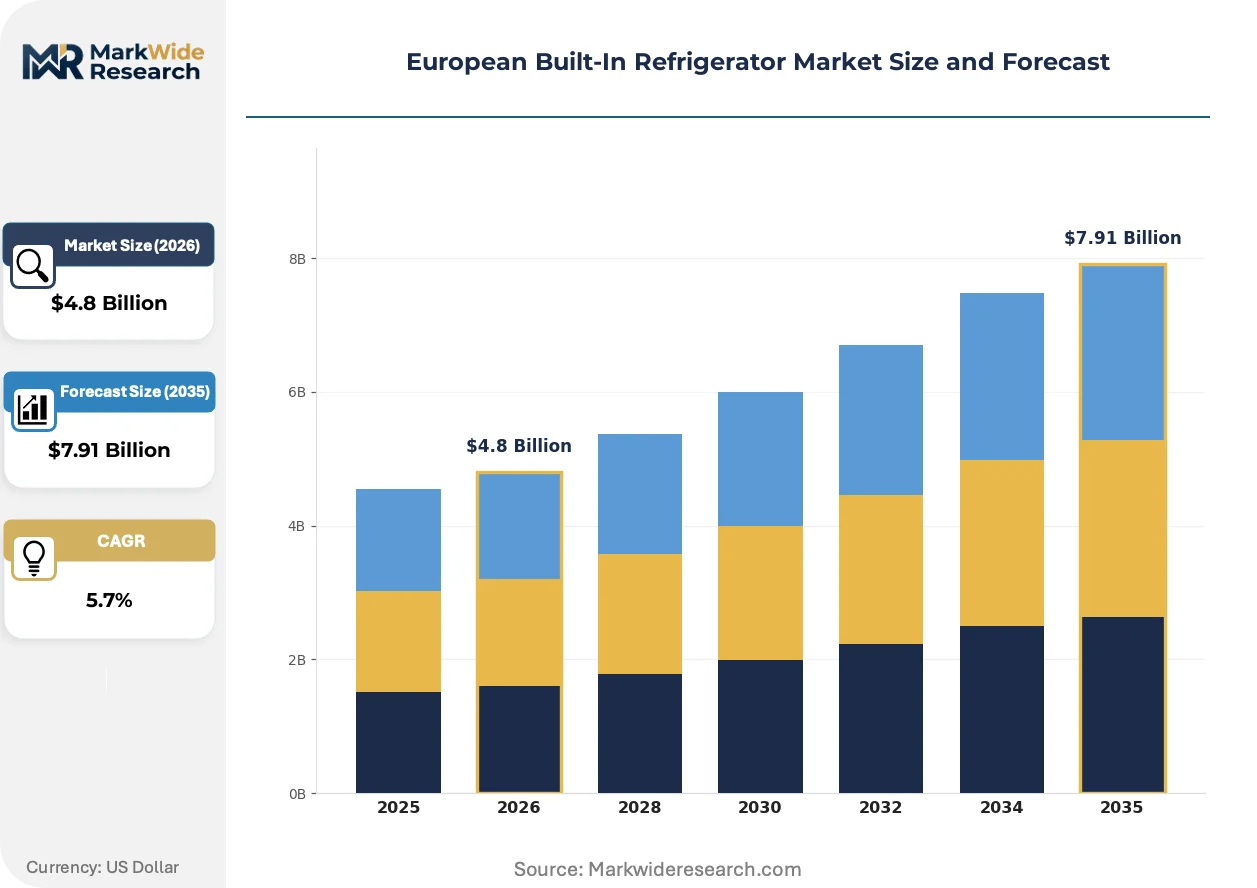
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Door, Double Door, Multi-Door, French Door Technology: Compressor, Thermoelectric, Solar, Hybrid Feature: Smart Technology, Energy Efficient, Adjustable Shelves, Quick Cooling Customer Type: Residential, Commercial, Retail, Hospitality |
| Companies Covered | BSH Hausgeräte, Electrolux AB, Whirlpool Corp., Haier Europe, LG Electronics, Liebherr-Hausgeräte, Miele & Cie. KG, Beko, Smeg S.p.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
European Built-In Refrigerator Market Shifts & Advancements
Technology trajectories across the European built-in refrigerator market are diverging between efficiency-maximizing hardware architectures and digitally-enabled service layers, with regulatory pressure acting as the forcing function.
Propane-isobutane refrigerant blends are displacing hydrofluorocarbon systems in compressor designs for sub-150 GWP compliance. German and Swiss premium residential buyers are specifying these units at accelerating rates. The technology is bifurcating the supply base between OEMs with in-house compressor capabilities and those dependent on external component sourcing.
EU F-Gas Regulation phaseout timetables are mandating refrigerant transitions ahead of hardware replacement cycles. OEMs must requalify supply chains and redesign thermal management systems simultaneously. Variable-speed compressor architectures are capturing preference in Western European markets where energy labeling drives purchasing decisions.
Sensor-driven temperature zone management is reshaping buyer expectations for food preservation performance. Hospitality operators in France and Benelux are unbundling after-sales service contracts from equipment procurement, favoring OEMs with dedicated technical service networks. This pattern is most visible in commercial kitchen renovations where uptime guarantees outweigh capital cost considerations.
European Built-In Refrigerator Market Segmentation
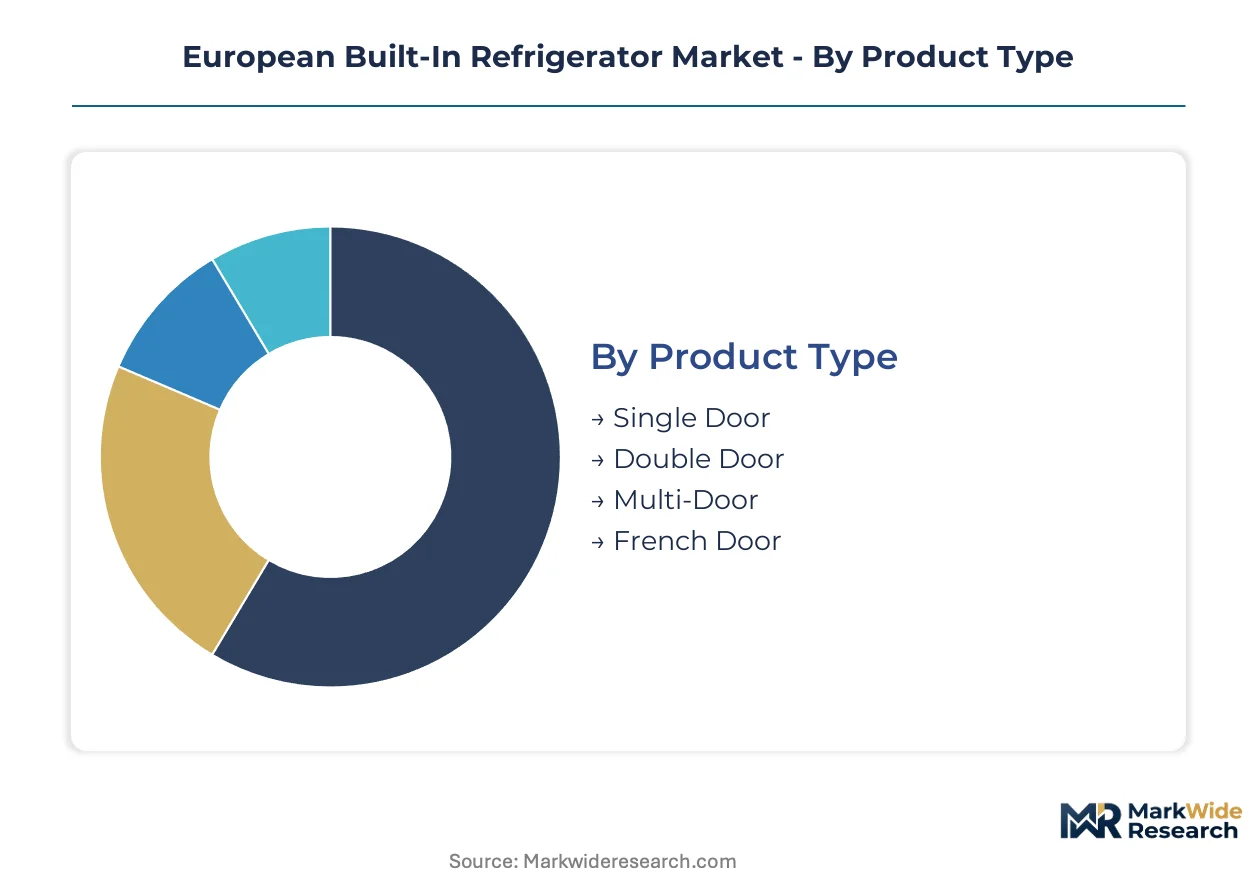
Segmentation across the European built-in refrigerator market reveals how regulatory pressure and renovation cycles concentrate value in specific product configurations. Understanding these divisions clarifies where procurement budgets flow and which technical specifications command price premiums.
Product Type:
Margin pools concentrate in multi-door and French Door configurations where climate-zone complexity justifies higher price points.
- Multi-Door:Independent temperature zones with dedicated compressors for fresh, biofresh, and freezer compartments. German and French residential buyers specify these during premium kitchen renovations where cabinetry integration demands precise dimensional fit. The EU F-Gas Regulation accelerates adoption as these units accommodate larger propane-isobutane charge volumes required for sub-150 GWP compliance.
- French Door:Bottom-freezer architecture with side-by-side fresh food access above. Italian and Spanish modular kitchen manufacturers specify French Door units in new residential developments where wide cabinet openings suit Mediterranean cooking patterns. The configuration captures hospitality procurement in France and Benelux where service access and inventory visibility matter.
- Single Door:Compact integrated units for space-constrained urban apartments. Paris and Milan studio renovations drive replacement cycles.
- Double Door:Traditional top-freezer or side-by-side configurations. Retains share in mid-tier residential renovations across Spain.
The dominant share belongs to Multi-Door, while French Door is closing the gap fastest.
Technology:
Technology choice determines compliance trajectories under EU F-Gas phaseout schedules and Ecodesign efficiency tiers.
- Compressor:Vapor-compression systems with variable-speed drives dominate cooling density in constrained cabinet depths. German OEMs with in-house compressor manufacturing control supply chains for propane-isobutane blends. Benelux hospitality operators specify these for uptime guarantees in commercial kitchen renovations.
- Thermoelectric:Solid-state cooling without refrigerant charge suits compact wine storage and specialty compartments. Swiss premium residential buyers specify thermoelectric zones for temperature-sensitive inventory where vibration elimination matters.
- Solar:Photovoltaic-integrated units for off-grid or sustainability-marketed installations. Limited penetration in Mediterranean coastal developments.
- Hybrid:Combined compressor-thermoelectric architectures optimizing energy draw across load conditions. Emerging in A+++ efficiency tier products.
Compressor technology holds the installed base, though Hybrid systems are expanding most quickly in new efficiency-tier migrations.
Feature:
Feature differentiation separates premium procurement from replacement-driven standard purchases.
- Smart Technology:Wi-Fi-enabled inventory tracking and energy-optimization algorithms. French hospitality operators unbundle after-sales service contracts from equipment procurement, favoring OEMs with connected diagnostics. German high-end residential buyers specify smart features for integration with home energy management systems.
- Energy Efficient:A+++ rating and beyond under Ecodesign Directive thresholds. Mandatory for distribution access across EU member states.
- Adjustable Shelves:Modular interior configurations for varying load profiles. Standard in Italian modular kitchen integrations.
- Quick Cooling:Boost modes for temperature recovery after door opening. Specified in commercial retail applications.
Energy Efficient features constitute baseline requirements, whereas Smart Technology is climbing the fastest in hospitality and premium residential segments.
Customer Type:
Customer type determines installation complexity tolerance and after-sales service expectations.
- Residential:Cabinetry-integrated installations during whole-kitchen overhauls. Germany and France drive replacement cycle compression.
- Hospitality:Commercial kitchen renovations where uptime guarantees outweigh capital cost considerations. France and Benelux concentrate demand.
- Commercial:Retail and foodservice back-of-house applications. Spain and Italy emerging corridors for specification.
- Retail:Display refrigeration in premium food retail. CE marking compliance creates barriers for non-European entrants.
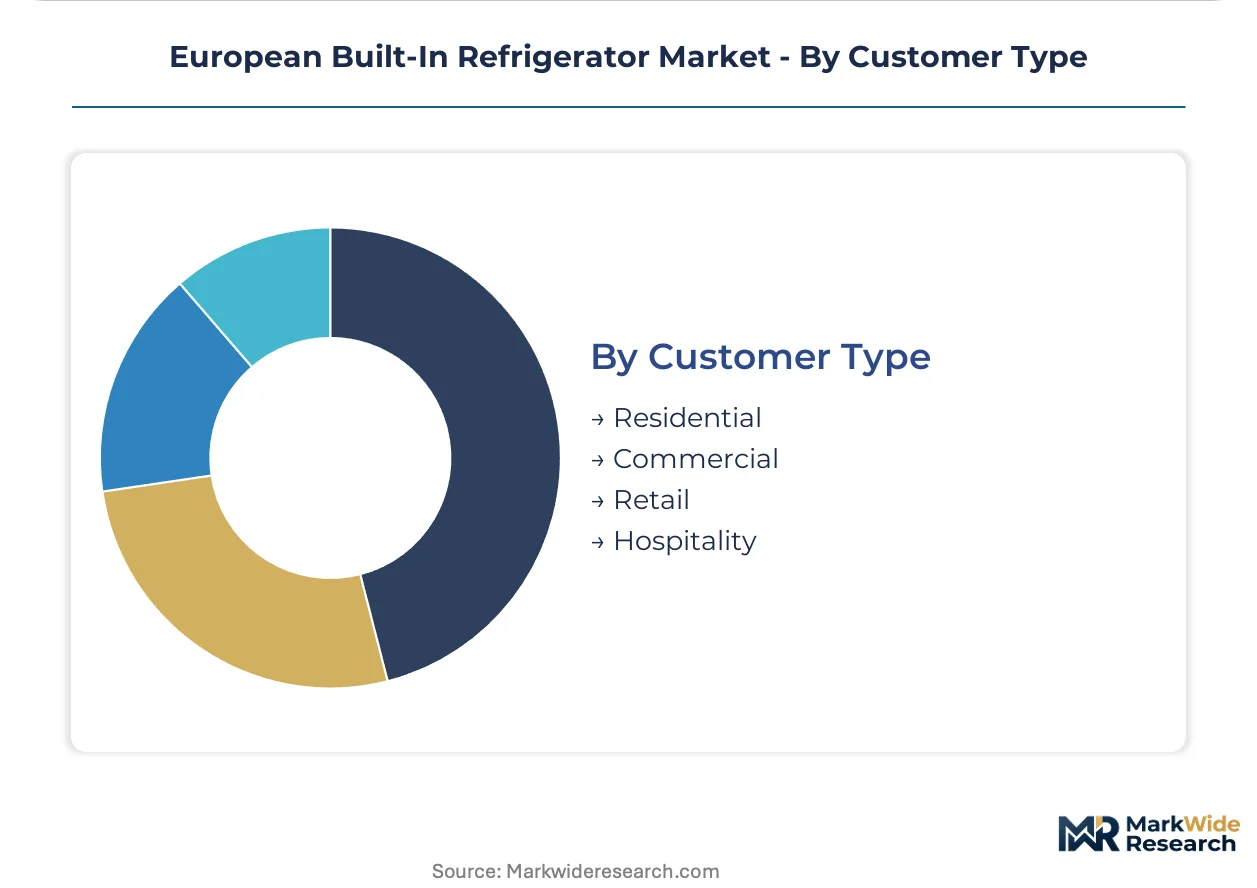
Residential customers command volume leadership, though Hospitality procurement is gaining share fastest through outcome-based service contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor manufacturing and control-system engineering cluster in Germany and Italy, with regulatory compliance capabilities concentrating among established Western European appliance makers. This supply-side geography shapes where product development investments flow and which national markets capture early access to next-generation efficiency tiers.
Germany
Premium kitchen renovations in Munich and Hamburg compress replacement cycles for cabinetry-integrated units. The EU F-Gas Regulation forces domestic OEMs to requalify supply chains around propane-isobutane blends before 2030 deadlines. Bavaria anchors manufacturing concentration, with Stuttgart-area engineering clusters driving variable-speed compressor innovation.
France
Hospitality procurement in Paris and Lyon prioritizes uptime guarantees over capital expenditure, accelerating smart-feature adoption. Ecodesign Directive efficiency tiers pull residential demand toward A+++ rated systems. The Île-de-France region concentrates commercial kitchen renovation activity, with Benelux-bordering corridors emerging as specification hubs for multi-door configurations.
Italy
Modular kitchen manufacturers in Lombardy and Veneto specify built-in refrigeration as standard in new residential developments. CE marking requirements under MDR-equivalent frameworks create compliance barriers for non-European entrants. Milan-area industrial design clusters shape aesthetic specifications that propagate across Southern European markets.
Spain
Underpenetrated modular kitchen markets in Madrid and Barcelona offer white space for French Door configuration penetration. Installer shortages in Valencia and Seville create friction for flush-mount cabinetry integration. Mediterranean coastal developments test photovoltaic-integrated refrigeration for sustainability-marketed installations.
Switzerland
Thermoelectric specialty compartments gain traction among Zurich and Geneva premium residential buyers seeking vibration elimination for temperature-sensitive inventory. Swissmedic-equivalent safety frameworks govern electrical integration standards. Alpine-market cold-chain expertise from refrigeration OEMs transfers into residential biofresh compartment specifications.
European Built-In Refrigerator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European built-in refrigerator landscape. The market structure tiers between premium specialists with captive compressor capabilities and scale-driven diversified appliance makers sourcing components externally. Three archetypes dominate: vertically integrated German engineering houses, Scandinavian-heritage mass-market brands, and Asian electronics conglomerates with European distribution arms. Competitive moves concentrate on supply chain requalification for F-Gas compliance and geographic expansion into underpenetrated Southern European corridors.
Among German-based engineering specialists, BSH Hausgeräte and Liebherr-Hausgeräte occupy positions exemplifying captive manufacturing depth, while Miele & Cie. KG represents the warranty-architecture differentiation archetype. These three entities anchor the premium tier where backward integration into compressor and control-system production sustains margin structures against regulatory cost pressures.
| Leading Market Players |
|---|
| BSH Hausgeräte |
| Electrolux AB |
| Whirlpool Corp. |
| Haier Europe |
| LG Electronics |
| Liebherr-Hausgeräte |
| Miele & Cie. KG |
| Beko |
| Smeg S.p.A. |
| Others |
Supply & Pricing Matrix
CE marking under the MDR-equivalent appliance safety framework gates both supply qualification and price differentiation simultaneously. Manufacturers must absorb certification costs before accessing distribution channels, while compliance tier separates premium cabinetry-integrated lines from standard replacement units. This regulatory threshold compresses margin structures for non-European entrants lacking established conformity assessment pathways.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across the European built-in refrigerator landscape. Three-tier pricing structure across premium, standard, and economy levels reflects compressor architecture sophistication and after-sales service bundling. Cost compression in mid-tier configurations is intensifying because R&D retooling for propane-isobutane blends concentrates among OEMs with limited captive engineering capacity. Residential buyers in Germany and Switzerland exhibit lowest price sensitivity, prioritizing warranty architectures and sensor-driven temperature zones, while Spanish and Italian modular kitchen specifiers drive volume through standard-efficiency procurement.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam has elevated inbound logistics costs for variable-speed drive components sourced from East Asian semiconductor foundries. Compressor motor manufacturing concentrates in Germany, Italy, and Slovakia, with control-system engineering clustering in Stuttgart-area and Milan industrial districts. Supply chains draw from copper winding suppliers in Poland, rare-earth magnet processors in China, and precision aluminum extruders in Austria. Single-source vulnerability persists for propane-isobutane refrigerant charge certification equipment. Distribution runs through kitchen manufacturer specification channels and certified installer networks rather than traditional appliance retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are multiplying as modular kitchen integration standards diverge across national markets. The unbundling of after-sales service contracts from equipment procurement creates niche openings for specialized technical service providers.
For Market Incumbents: Fortify backward integration into compressor and control-system manufacturing to defend margin structures against regulatory cost pressures. BSH Hausgeräte and Liebherr-Hausgeräte demonstrate how captive supply of propane-isobutane-compatible architectures preserves pricing power. Capacity addition in Bavaria and Baden-Württemberg secures proximity to German premium renovation demand while insulating against variable-speed drive component shortages.
For New Entrants and Emerging Players: Lead with CE marking compliance services for Asian electronics conglomerates lacking MDR-equivalent appliance safety expertise. Spain and Italy offer the most penetrable geography, with underdeveloped modular kitchen markets in Madrid and Barcelona creating white space for French Door configuration penetration. Partner with Lombardy-based kitchen manufacturers to secure specification access before incumbent service networks solidify.
For Investors and Strategic Acquirers: The 2030 F-Gas phaseout milestone reshapes the acquisition landscape toward OEMs with completed refrigerant requalification. Five-to-ten year viability favors vertically integrated engineering houses over component-dependent assemblers. Target mid-tier specialists with in-house compressor capabilities but limited geographic footprint. Monitor propane-isobutane charge volume certification timelines as the inflection indicator for distribution access retention.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Completion | Secures distribution access under EU F-Gas phasedown schedules ahead of 2030 deadlines. |
| Variable-Speed Compressor Integration | Captures A+++ efficiency tier demand from German and French residential renovation cycles. |
| Smart Technology Platform Launch | Enables outcome-based service contracting with French hospitality operators seeking uptime guarantees. |
| Southern European Distribution Expansion | Penetrates underdeveloped modular kitchen markets in Spain and Italy through specification partnerships. |
| CE Marking Compliance Investment | Removes MDR-equivalent appliance safety barriers for non-European market entry attempts. |
Research Methodology
Operator-level perspectives from kitchen manufacturer specification managers, certified installation technicians, hospitality procurement directors, and refrigerant compliance engineers anchored the qualitative base. Primary interviews triangulated with secondary validation from EU F-Gas Regulation implementation reports, Ecodesign Directive efficiency tier databases, and CE marking conformity assessment records. Customs data on compressor motor imports, kitchen furniture production statistics, and appliance safety framework documentation provided quantitative anchors. Bottom-up unit economics modeled across product configurations reconciled with top-down market sizing from renovation expenditure surveys.
Sensitivity analysis tested forecast robustness against refrigerant phaseout acceleration scenarios and modular kitchen penetration variance across Southern Europe. Segmentation dimensions modeled include product configuration complexity, cooling technology architecture, feature bundling intensity, and customer type installation requirements. CAGRs derived from replacement cycle compression rates, efficiency tier migration patterns, and geographic expansion coefficients. Forecast inputs incorporated F-Gas requalification timelines, certified installer capacity constraints, and hospitality service contract unbundling velocity.
Forecasts assume regulatory continuity in EU F-Gas and Ecodesign regimes; material policy shifts would require re-modeling. Specific risk factors include compressed refrigerant requalification deadlines, cross-border installation standard divergence, and variable-speed drive component supply concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Electric Fireplace Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
United Kingdom Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
China Small Home Appliances Market
Home Appliances
Saudi Arabia Small Home Appliances Market
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
Electric Household Appliances Market
Home Appliances
Germany Major Home Appliance Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Oman Small Home Appliances Market