
 Europe Smart Cooker Market | 2026-2036
Europe Smart Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Cooker Market Foresight
Subscription-based recipe and remote monitoring services is pivoting how manufacturers monetize smart cooker hardware. Electrolux AB leverages its Nordic design heritage to sustain premium positioning across Scandinavian markets. Bosch anchors German engineering credibility through integrated Home Connect ecosystems. Samsung Electronics competes by extending its SmartThings platform into kitchen automation, creating cross-device loyalty.
A smart cooker combines precision heating elements, embedded sensors, and wireless connectivity to automate cooking cycles via smartphone or voice command, typically operating between 40°C and 250°C with programmable pressure and temperature curves for consistent food preparation. Multi-cooker configurations capture the widest addressable base by consolidating pressure cooking, slow cooking, and sauté functions in single units. Wi-Fi-enabled models outpace Bluetooth-only alternatives as consumers prioritize remote start and cloud-based recipe synchronization. Voice control integration remains nascent but attracts tech-forward segments seeking hands-free kitchen operation.
The EU Ecodesign Directive and CE marking requirements shape minimum efficiency standards and electromagnetic compatibility for connected cooking appliances sold across member states. Germany's KBA-adjacent consumer safety frameworks and France's ANSM-influenced product quality expectations further elevate compliance thresholds for market entry. Stakeholders must monitor whether Brussels extends digital product passport mandates to small domestic appliances, as this would force supply chain traceability investments before competitors adapt.
Market Dynamics
The EU Ecodesign Directive is compressing product development cycles across European smart cooker manufacturers as energy efficiency mandates tighten ahead of 2027 compliance deadlines, forcing redesigns of heating elements and control systems.
Growth Catalysts
- CE marking convergence:Unified electromagnetic compatibility standards across member states reduce fragmentation costs for multi-cooker platforms entering France, Germany, and Italy simultaneously.
- Voice control integration:Amazon Alexa and Google Assistant compatibility is accelerating hands-free kitchen automation adoption among tech-forward households in Nordic markets.
- Cloud recipe synchronization:Wi-Fi-enabled models pull demand from subscription-based meal planning services that monetize recurring revenue beyond hardware margins.
Market Restraints
- Semiconductor supply concentration:Microcontroller shortages from Asian foundries delay production ramps for sensor-embedded pressure cooking units.
- GDPR compliance friction:Data localization requirements for connected appliance telemetry increase cloud infrastructure costs for remote monitoring features.
- Induction hob substitution:Built-in induction cooktops with app control capture countertop space in German kitchen renovations.
Strategic Opportunities
- Polish and Romanian expansion:Smart home penetration lags Western Europe by 40 percentage points, creating first-mover windows for Wi-Fi multi-cookers.
- CSRD-aligned circular design:Digital product passport mandates under Brussels sustainability frameworks reward repairable appliance architectures with preferential retail placement.
- Aging-in-place applications:Safety-automated cooking for elderly households intersects with France's ANSM-influenced assisted living procurement channels.
Industry Challenges
- Firmware security certification:IEC 62443 compliance for industrial cybersecurity extends timelines for over-the-air update rollouts.
- Cross-platform integration:Fragmented smart home protocols force manufacturers to maintain parallel development tracks for Home Connect, SmartThings, and proprietary ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Cooker Market |
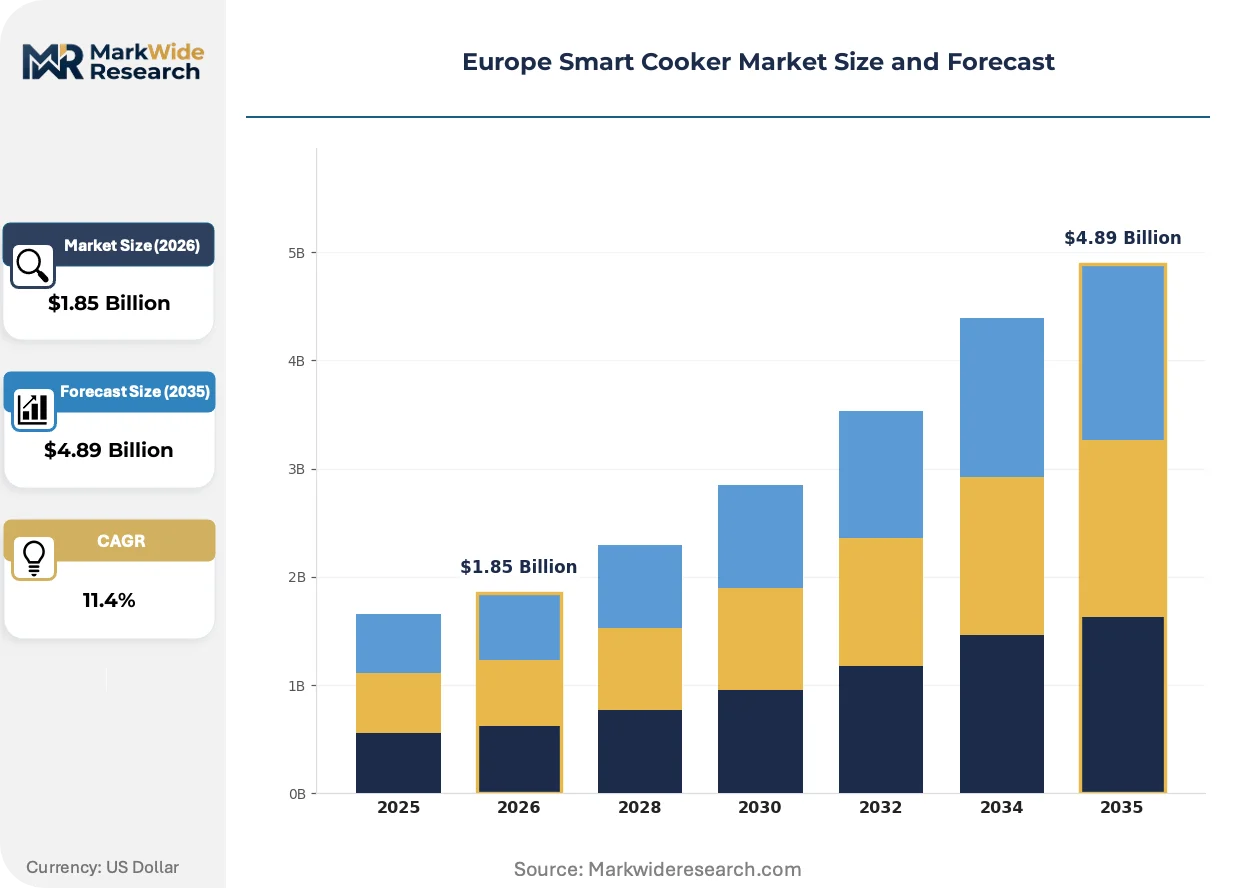
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Cooker, Induction Cooker, Pressure Cooker, Multi-Cooker End User: Residential, Commercial, Caterers, Restaurants Technology: Wi-Fi, Bluetooth, NFC, Voice Control Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Samsung Electronics, Whirlpool Corporation, Panasonic Corporation, Electrolux AB, Prestige, Bosch, Miele, LG Electronics, Gaggenau, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Cooker Market Shifts & Advancements
Smart cooker architectures are fragmenting into interoperable subsystems as manufacturers decouple hardware from software monetization, while regulatory pressure on energy consumption accelerates sensor density in heating elements.
Precision thermal management is modularizing around distributed temperature sensing arrays that replace single-point probes. Premium German appliance buyers are specifying multi-zone heating control for sous-vide and pressure sequences in single sessions. This sensor distribution is modularizing what were monolithic cooking programs into recombinable micro-routines that third-party developers can license.
The EU Green Deal's extended producer responsibility frameworks now capture small domestic appliances, requiring smart cooker manufacturers to finance end-of-life collection networks. Industrial consequence: redesign for disassembly is elevating fastener standardization and modular heating element replacement over sealed-unit construction. Scandinavian markets demonstrate earliest compliance, with Electrolux piloting take-back programs that recover rare earth magnets from induction coils.
Households are unbundling appliance purchases from recipe content, subscribing to cloud cooking libraries independently of hardware brands. This disintermediation compresses manufacturer margins on entry-level Wi-Fi models while amplifying lifetime value for platform-agnostic premium players. United Kingdom grocery retailers are capturing this shift through bundled meal-kit and smart cooker financing offers that displace traditional electronics retail channels.
Europe Smart Cooker Market Segmentation
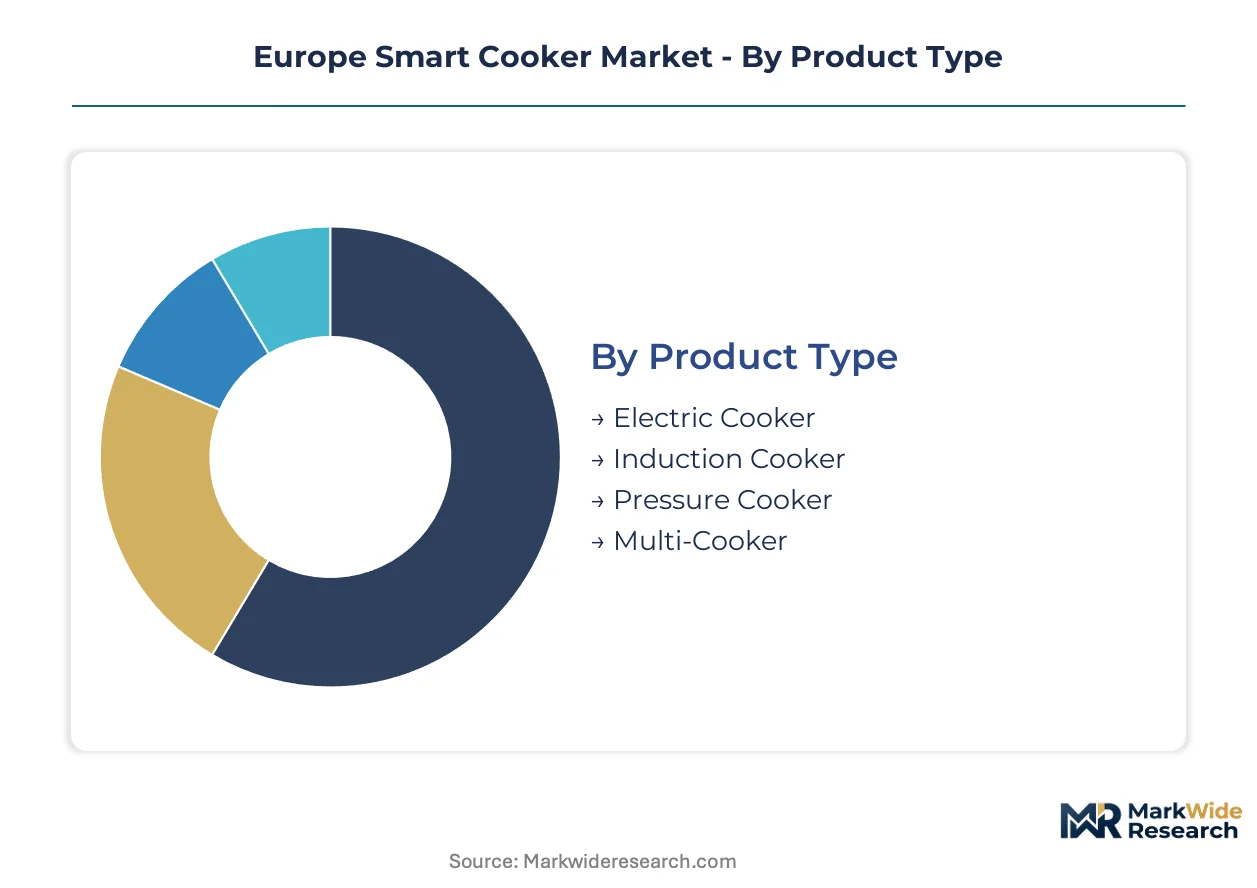
Smart cooker segmentation reveals how hardware specifications, connectivity depth, and procurement channels fragment addressable demand across European households and foodservice operations. Manufacturers must align product architectures with distinct technical requirements and purchasing behaviors that vary sharply between connected home ecosystems and commercial kitchen procurement.
Product Type:
Standalone countertop units dominate residential installations, while built-in configurations embed within modular kitchen systems for premium renovations.
- Electric Cooker:Conventional resistive heating elements deliver temperature ranges between 40°C and 250°C through analog or basic digital controls. German mass-market retailers move volume through private-label electric cookers priced below Wi-Fi-enabled alternatives, though energy efficiency mandates under the EU Ecodesign Directive are compressing margins on non-connected models.
- Multi-Cooker:Consolidated pressure cooking, slow cooking, sauté, and steaming functions operate through programmable microcontrollers with sensor feedback loops. French and British households prioritize multi-cooker purchases for space-constrained urban kitchens, with cloud recipe synchronization driving replacement cycles faster than single-function appliances.
- Induction Cooker:Electromagnetic coil systems achieve rapid thermal response through ferromagnetic cookware detection. Scandinavian markets show strongest penetration where electricity costs favor efficiency over resistive heating.
- Pressure Cooker:Sealed-vessel steam pressure systems reduce cooking duration through elevated boiling points. Safety-automated variants with lid-lock sensors attract elderly-care applications in France's assisted living procurement channels.
Volume placements concentrate in Multi-Cooker configurations; the faster expansion belongs to Induction Cooker variants with app-integrated thermal management.
End User:
Procurement authority splits between individual household decision-makers and institutional purchasing managers with divergent total-cost-of-ownership calculations.
- Residential:Individual households purchase countertop units through retail or direct channels, prioritizing Wi-Fi connectivity and voice control compatibility. United Kingdom smart home penetration rates drive replacement of conventional appliances with connected alternatives.
- Restaurants:High-throughput foodservice operations demand commercial-grade stainless steel construction with HACCP-aligned temperature logging. German restaurant chains specify multi-cookers with batch programming for menu standardization across locations.
- Commercial:Corporate cafeteria and institutional kitchen procurement emphasizes durability certifications and service network coverage over consumer-oriented features.
- Caterers:Mobile and event-based foodservice requires portable units with rapid heat-up cycles and generator-compatible power draw.
Residential channels move the highest unit volumes; Restaurants represent the steepest expansion trajectory as labor automation pressures intensify.
Technology:
Connectivity architecture determines feature depth, with cloud-dependent systems requiring ongoing infrastructure investment versus local-only protocols.
- Wi-Fi:Continuous internet connectivity enables remote start, over-the-air firmware updates, and cloud-based recipe libraries. Nordic and British households prioritize Wi-Fi models for integration with broader smart home ecosystems.
- Bluetooth:Proximity-limited pairing with smartphones delivers basic remote control without cloud dependency. Entry-level positioning targets price-sensitive segments in Polish and Romanian markets where smart home penetration lags Western Europe.
- Voice Control:Amazon Alexa and Google Assistant integration enables hands-free operation through natural language commands. Tech-forward segments in urban France and Germany adopt voice control despite higher hardware cost.
- NFC:Near-field communication enables tap-to-pair configuration and authenticated recipe downloads from retail packaging.
Wi-Fi-enabled models dominate current placements; Voice Control integration is climbing the fastest as platform competition intensifies.
Distribution Channel:
Channel strategy must reconcile discovery-driven online commerce with tactile evaluation requirements for premium appliance purchases.
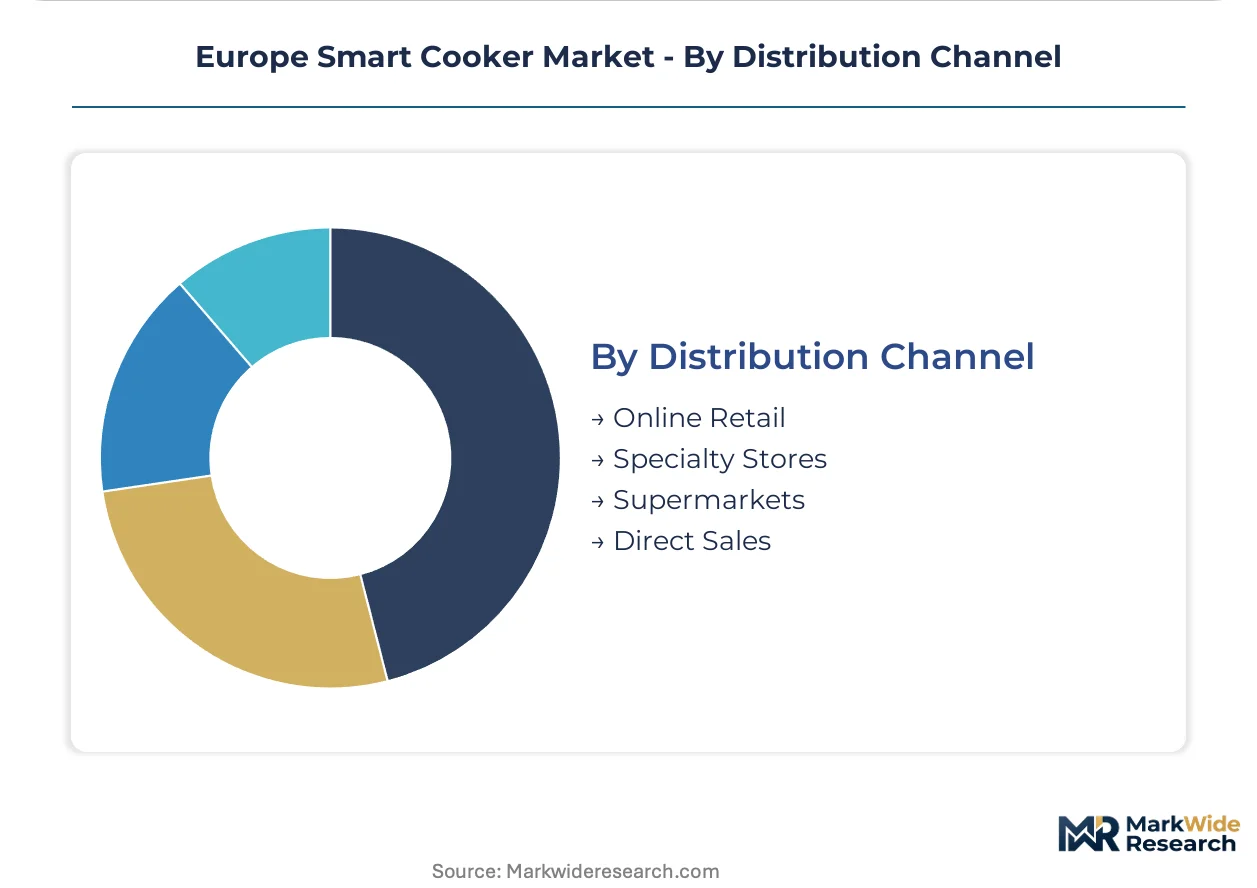
- Online Retail:Amazon and dedicated appliance platforms capture comparison-shopping behavior with review aggregation and financing integration. United Kingdom grocery retailers are bundling meal-kit subscriptions with smart cooker financing to displace electronics retail.
- Specialty Stores:Kitchen design showrooms and department store appliance galleries enable tactile evaluation and staff consultation. German consumers rely on specialty channels for Electrolux and Bosch premium positioning.
- Supermarkets:Mass-market grocery and hypermarket chains move entry-level electric and basic multi-cooker models through impulse placement.
- Direct Sales:Manufacturer-owned channels and subscription bundling capture lifetime value through recurring recipe service revenue.
Online Retail channels capture the greatest volume velocity; Direct Sales models are gaining share fastest through hardware-software bundling experiments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and Scandinavia while consumption spreads across Western European households. Eastern European markets lag in smart home penetration but show accelerating replacement cycles. Regulatory harmonization under Brussels frameworks enables cross-border distribution with reduced compliance fragmentation.
Germany
Engineering-intensive households prioritize multi-cooker platforms with Home Connect ecosystem integration. The KBA-adjacent consumer safety frameworks elevate electromagnetic compatibility thresholds for connected kitchen appliances. Bavarian industrial clusters around Munich anchor precision sensor manufacturing for temperature control modules.
United Kingdom
Cloud recipe synchronization drives replacement of conventional appliances in London and Southeast England smart home installations. GDPR compliance requirements shape data localization investments for remote monitoring service providers. Midlands manufacturing corridors supply heating element subassemblies to pan-European assembly plants.
France
ANSM-influenced quality expectations elevate safety-automated pressure cooker specifications for assisted living procurement. The EU Ecodesign Directive compresses development timelines for energy-efficient heating architectures. Île-de-France retail channels bundle meal-kit subscriptions with Wi-Fi-enabled multi-cooker financing.
Italy
Space-constrained urban kitchens in Milan and Rome favor consolidated multi-function appliances over single-purpose units. CE marking convergence reduces fragmentation costs for manufacturers entering Southern European markets simultaneously. Lombard appliance design studios specialize in modular heating element architectures.
Poland
Smart home penetration gaps of 40 percentage points versus Western Europe create first-mover windows for entry-level Wi-Fi multi-cookers. The EU Green Deal's extended producer responsibility frameworks begin capturing small domestic appliance collection networks. Warsaw logistics hubs enable distribution into neighboring Romanian and Baltic markets.
Europe Smart Cooker Market Competitive Landscape
Top-tier vendors anchor premium positioning through integrated smart home ecosystems, while mid-tier specialists compete on price-accessible Wi-Fi connectivity. The vendor base stratifies across three tiers: ecosystem integrators with platform control, appliance specialists with design heritage, and electronics conglomerates with semiconductor supply advantages. Two dominant competitive moves are emerging: ecosystem lock-in through proprietary cloud services and modular hardware architectures that enable third-party software licensing.
Within the ecosystem integrator tier, Electrolux AB and Bosch exemplify divergent geographic anchoring strategies. Samsung Electronics occupies a position spanning consumer electronics and connected appliance domains. These three entities represent distinct competitive archetypes: Nordic design heritage, German engineering credibility, and Korean platform scale.
| Leading Market Players |
|---|
| Samsung Electronics |
| Whirlpool Corporation |
| Panasonic Corporation |
| Electrolux AB |
| Prestige |
| Bosch |
| Miele |
| LG Electronics |
| Gaggenau |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists across Northern Italy and Southern Germany anchor component sourcing for European smart cooker assembly, translating concentrated supplier relationships into disciplined pricing power over resistive heating elements and microcontroller modules. Their long-tenured financing structures—often backed by regional development banks rather than private equity—enable patient capital allocation that resists margin erosion even as CE marking compliance costs escalate.
Pricing Analysis
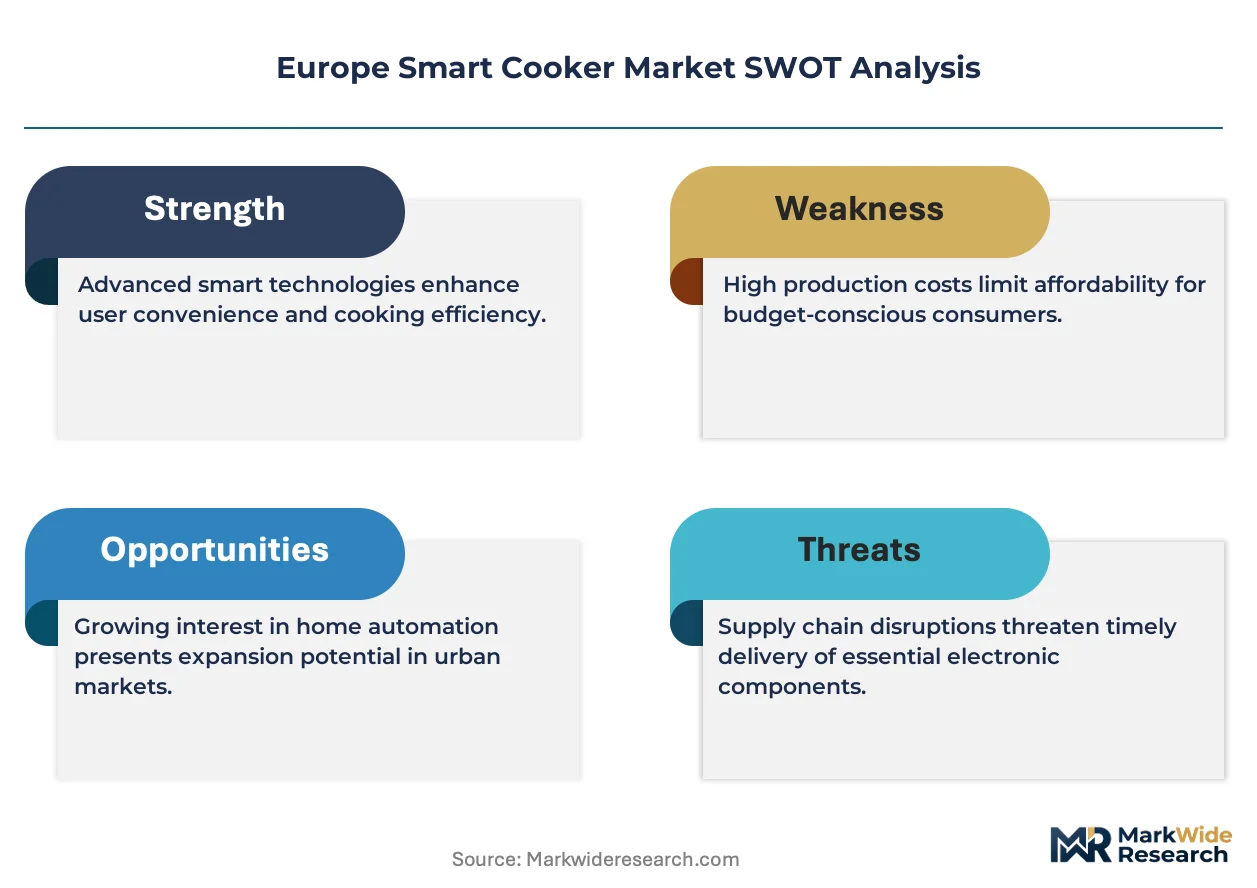
Margin tightening in entry-level Wi-Fi multi-cookers reflects semiconductor cost pass-through from Asian foundries and the EU Ecodesign Directive's forced redesign cycles. Three-tier pricing structure across premium, standard, and economy levels separates Home Connect-integrated Bosch units from private-label supermarket alternatives, with certification grade and after-sales service bundling as primary differentiation drivers. Polish and Romanian households exhibit highest price sensitivity, while Scandinavian consumers absorb premiums for repairable modular architectures aligned with CSRD circularity mandates.
Supply Chain Analysis
CE marking and IEC 62443 cybersecurity certification gating compresses qualified supplier pools for sensor-embedded heating elements to Bavarian precision manufacturers and Lombard electromechanical specialists. Raw material dependencies center on rare earth magnets for induction coils, ferrite cores from Chinese ceramic producers, and microcontroller wafers from Taiwanese foundries. Single-source vulnerability in semiconductor supply creates production ramp delays, while distribution runs through German logistics hubs serving pan-European retail networks and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into cloud recipe platforms and captive sensor manufacturing is accelerating as incumbents seek to capture recurring revenue streams and insulate margins from semiconductor volatility.
For Market Incumbents: Extend Home Connect and SmartThings ecosystem lock-in through exclusive cloud recipe licensing agreements that raise switching costs for multi-cooker households. Consolidate position by acquiring Lombard heating element specialists to secure modular component supply as EU Green Deal extended producer responsibility mandates intensify. Bosch and Electrolux should prioritize firmware security certification investments ahead of IEC 62443 compliance deadlines to delay competitor over-the-air update rollouts. For New Entrants and Emerging Players: Voice-first cooking automation interfaces offer a technology-first wedge into tech-forward Nordic households where Amazon Alexa penetration exceeds smart cooker adoption. Target Poland and Romania's 40-percentage-point smart home penetration gap with entry-level Wi-Fi multi-cookers bundled through grocery retail financing partnerships. Partner with United Kingdom meal-kit subscription services for hardware-software go-to-market velocity that bypasses established electronics retail channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular hardware architecture specialists in Italy and Germany with repairable design IP transferable across CSRD-aligned circular economy frameworks. Long-term viability hinges on platform-agnostic software licensing revenue rather than hardware margin capture. Monitor Brussels digital product passport mandate extensions to small domestic appliances as the inflection signal for supply chain traceability investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Recipe Platform Integration | Bosch's Home Connect ecosystem locks in recurring subscription revenue beyond hardware sales cycles. |
| Modular Heating Element Sourcing | Lombard and Bavarian specialist acquisition secures repairable component supply under EU Green Deal mandates. |
| Cybersecurity Certification Investment | IEC 62443 compliance delays competitor firmware update capabilities and extends incumbent product cycles. |
| Eastern European Retail Partnership | Polish grocery financing bundles capture first-mover advantage in 40-point smart home penetration gaps. |
| Circular Design Architecture Development | Fastener standardization and disassembly-ready construction qualify for preferential retail placement under CSRD. |
Research Methodology
Multi-period observation of Wi-Fi multi-cooker replacement cycles, smart home penetration rates, and EU regulatory filing timelines anchored the trend analysis, supplemented by interviews with connected appliance product managers, CE marking compliance consultants, supermarket category buyers, and cloud platform engineers. Secondary validation drew from SEC filings of listed appliance manufacturers, Ecodesign Directive implementation reports, customs trade data for heating element subassemblies, and Nordic smart home adoption surveys. Bottom-up unit shipment modeling triangulated against top-down household penetration projections.
Segment-weighting across product type, connectivity architecture, and procurement channel dimensions structured the analytical framework across the analysis window. CAGRs derived from logistic diffusion curves fitted to smart home ecosystem adoption patterns, with cross-elasticity adjustments for induction hob substitution effects. Industry-specific forecast inputs incorporated EU Ecodesign Directive compliance cost trajectories and semiconductor lead time volatility indices.
Several conditions sit outside the modeled scope, including potential Brussels digital product passport mandate extensions to small domestic appliances and geopolitical disruptions to Taiwanese foundry supply. Forecasts reflect assumptions about steady smart home ecosystem platform competition and stable GDPR data localization cost structures. A model refresh is warranted upon material change in EU Green Deal extended producer responsibility enforcement timelines or IEC 62443 cybersecurity certification scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
US Induction Cookware Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
Cookware Accessories Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
Global Stainless Woks Market