
 Electric Lunch Box Market | 2026-2036
Electric Lunch Box Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Lunch Box Market Intelligence
The gap between premium stainless steel builds and commodity plastic units is hardening as material costs diverge. Hamilton Beach leverages its appliance heritage to sustain brand recognition in AC-powered segments. Crock-Pot anchors its position through thermal engineering specialization that differentiates its double-layer designs from generic alternatives.
An electric lunch box is a portable, self-heating food container incorporating embedded heating elements typically rated between 40W and 75W, designed to warm pre-cooked meals to serving temperature without external microwave access. Stainless steel variants command premium positioning due to thermal retention properties and food-grade compliance, while BPA-free plastic occupies volume-tier channels where cost sensitivity dominates procurement decisions. USB rechargeable power sources represent the fastest-growing configuration as mobile workforce patterns normalize cordless operation, whereas AC powered units retain maturity in stationary workplace settings.
The US Consumer Product Safety Commission and FDA food-contact regulations shape material compliance requirements for manufacturers targeting North American distribution. China's SAMR enforces GB standards for electrical safety in small household appliances, creating divergent certification burdens for multi-region suppliers. REACH compliance in Europe restricts certain polymer additives, directly influencing silicone and plastic formulation choices across export-oriented production. Stakeholders must monitor evolving battery transportation regulations as lithium-ion powered variants expand across air travel and commuter segments.
Market Dynamics
USB-C power delivery protocols are compressing product development cycles as manufacturers race to replace proprietary charging architectures with standardized 45W-100W input ranges compatible with laptop power bricks.
Growth Catalysts
- Remote work normalization:Hybrid office schedules in the United States and Germany sustain demand for portable meal warming among employees splitting time between home and corporate campuses.
- Battery chemistry advances:Lithium iron phosphate (LiFePO4) cells are displacing cobalt-based alternatives in premium electric lunch boxes due to thermal stability advantages during extended heating cycles.
- Food-contact compliance mandates:FDA 21 CFR standards for polypropylene and stainless steel interfaces are accelerating material upgrades across import-dependent supply chains.
Market Restraints
- Polymer feedstock volatility:BPA-free copolyester resin prices fluctuate with paraxylene and PTA spot markets, compressing margin buffers for plastic-tier manufacturers.
- Heating element sourcing concentration:PTC ceramic thermistor production clusters in Guangdong and Zhejiang provinces create single-region dependency risks for Western brands.
- Air transport restrictions:IATA lithium battery shipping regulations limit cross-border e-commerce fulfillment of USB-rechargeable variants above 100Wh capacity thresholds.
Strategic Opportunities
- India urban commuter expansion:Metro rail network extensions in Mumbai, Delhi, and Bengaluru create first-time addressable demand among 25-35 minute commute cohorts.
- Smart kitchen ecosystem integration:Bluetooth-enabled temperature logging and app-based meal scheduling are converging with existing home automation platforms.
- EU Green Deal procurement incentives:Public sector canteen modernization programs in France and Italy specify repairable appliance criteria favoring modular electric lunch box designs.
Industry Challenges
- Thermal engineering talent scarcity:Competent heat transfer modeling for confined 40-75W enclosures remains concentrated among small appliance specialists in Dongguan and Ningbo manufacturing zones.
- Multi-jurisdiction certification timelines:Simultaneous UL, CE, and GB standard testing extends product launch windows by 8-14 months for multi-region distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Lunch Box Market |
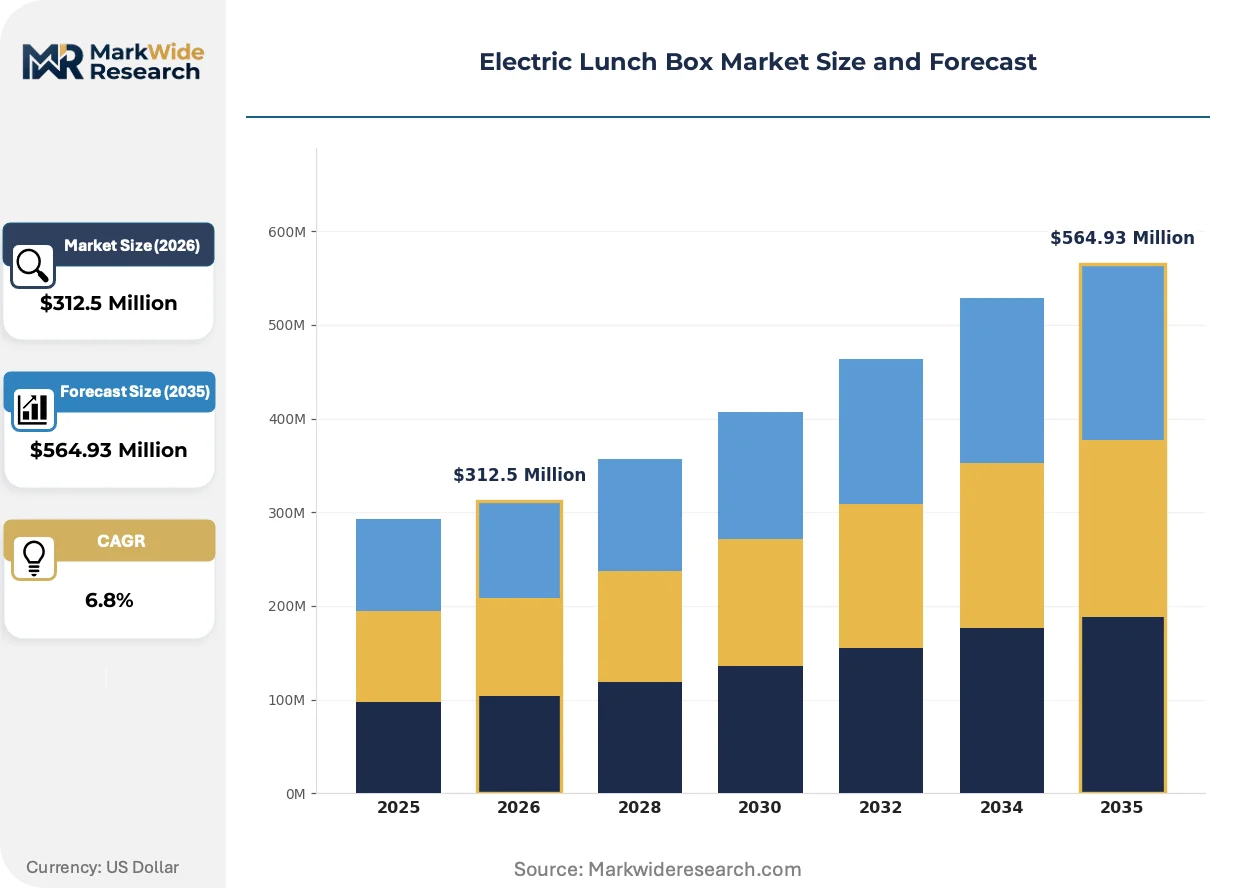
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Layer, Double Layer, Microwave Safe, Container with Power Bank Material: Stainless Steel, BPA-Free Plastic, Glass, Silicone Power Source: Battery Operated, USB Rechargeable, AC Powered, Solar Powered End User: Students, Office Workers, Travelers, Healthcare Professionals |
| Companies Covered | Buddew, Hamilton Beach, Crock-Pot, Hot Bento, Geveniss, EAST OAK, LunchEAZE, Nifogo, TRAVELISIMO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Lunch Box Market Strategic Shifts & Innovations
Product architectures are bifurcating between corded AC efficiency and cordless lithium portability, with interface standardization emerging as the unifying technical priority across both branches.
Graphene-enhanced heating films are integrating into mid-tier electric lunch boxes as a replacement for wire-wound resistor elements. Office workers in Japanese corporate districts are adopting these variants for silent operation during desk-side meal warming. The technology is integrating temperature uniformity controls that eliminate hot-spot scorching risks in rice and pasta applications.
REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of silicone sealing gaskets and polypropylene lid components. European manufacturers face 18-month material qualification cycles to maintain CE marking compliance. German distributors are responding by consolidating supplier bases to verified ISO 10993 biocompatibility-certified compounders.
Subscription-based meal kit bundling is altering B2B procurement patterns for electric lunch boxes. Corporate wellness programs in United States tech clusters are replacing bulk appliance purchases with employee stipend models. This shift is most visible in Seattle and Austin, where HR departments negotiate volume pricing with direct-to-consumer brands rather than traditional office supply channels.
Electric Lunch Box Market Segmentation
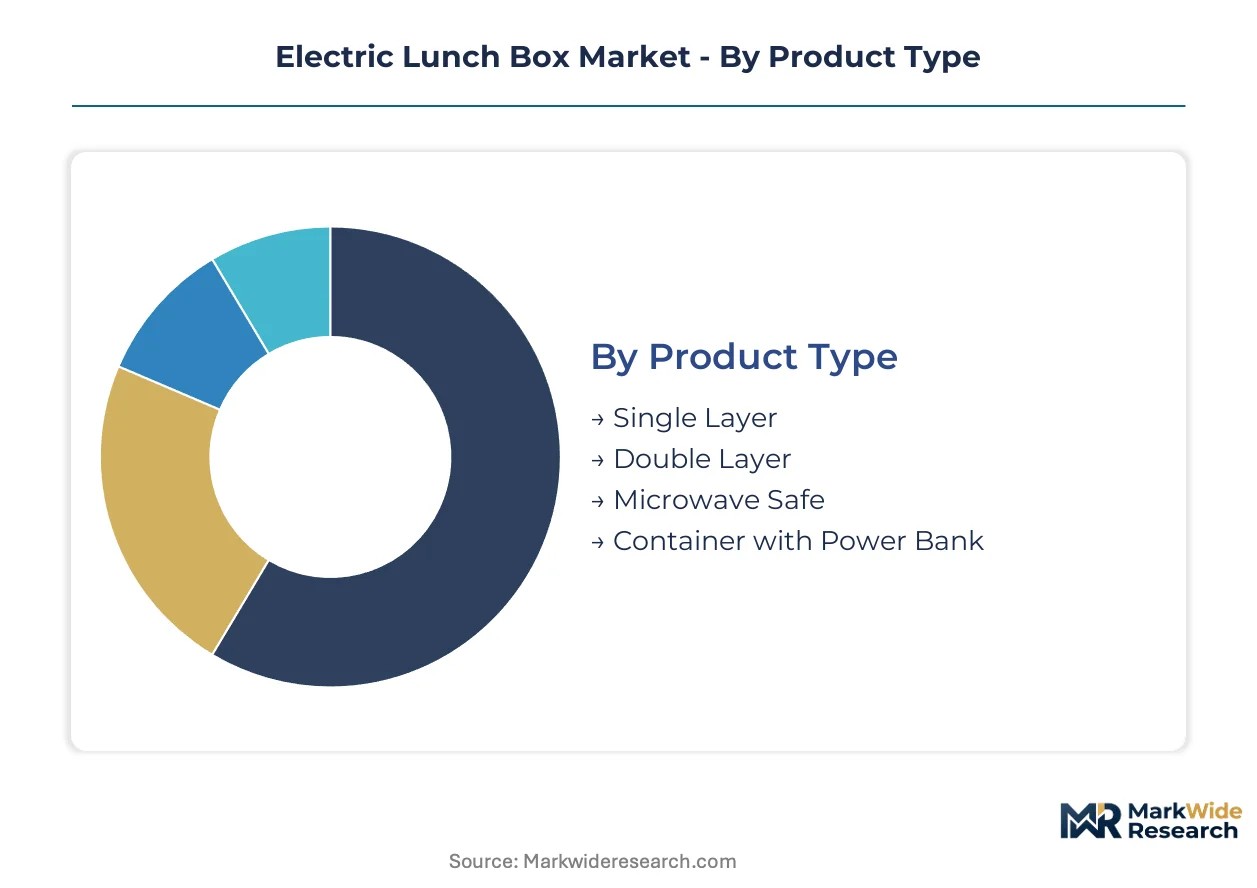
Segmentation in the electric lunch box market reveals divergent capital requirements across product architectures. Manufacturers must calibrate tooling investments against power system complexity and material certification burdens.
Product Type:
Capital intensity peaks with integrated power bank configurations requiring lithium-ion cell sourcing and battery management circuitry.
- Single Layer:Simple stamped stainless steel enclosures with embedded 40W-55W PTC heating elements dominate entry-level procurement. Demand clusters among students in India and Southeast Asia where cost sensitivity overrides thermal performance requirements.
- Double Layer:Vacuum-insulated dual-chamber designs with separate heating zones for rice and side dishes command premium positioning. Office workers in Japanese corporate districts favor these variants for bento-style meal separation without flavor transfer.
- Microwave Safe:Polypropylene-based containers with detachable heating bases address regulatory constraints in healthcare and educational settings. These units trade thermal efficiency for institutional compliance flexibility.
- Container with Power Bank:Lithium iron phosphate cell integration with 65W-100W output capability requires the steepest upfront engineering investment. USB-C PD compatibility is becoming mandatory for cross-device charging standardization.
Single layer configurations absorb the bulk of installed capacity; containers with power banks are expanding most quickly.
Material:
Cost tier stratification separates food-grade certified inputs from commodity polymer alternatives.
- Stainless Steel:304-grade and 316-grade variants with electropolished interiors dominate premium channels. German and US buyers prioritize these materials for thermal retention and dishwasher durability in daily commuter use.
- BPA-Free Plastic:Copolyester and Tritan formulations occupy volume-tier distribution through mass retail. REACH compliance costs in Europe are compressing margins for non-certified Asian compounders.
- Glass:Borosilicate containers with silicone sleeve protection address health-conscious segments willing to accept weight penalties. Demand concentrates among remote workers prioritizing microwave reheat flexibility.
- Silicone:Collapsible designs with platinum-cured sealing gaskets target space-constrained travelers. Fold-flat storage geometry commands 40% volume reduction for airline carry-on optimization.
Stainless steel commands the highest unit economics; silicone variants are climbing the fastest as travel normalization accelerates.
Power Source:
Application context determines power architecture selection across stationary and mobile use cases.
- Battery Operated:Removable lithium-ion packs with 50Wh-100Wh capacity enable cordless operation across full heating cycles. IATA shipping restrictions above 100Wh thresholds constrain cross-border e-commerce fulfillment.
- USB Rechargeable:USB-C PD input compatibility with 45W-100W range leverages existing laptop charging infrastructure. This configuration is gaining share fastest among hybrid workforce segments in the United States and Germany.
- AC Powered:Direct 110V-240V input with integrated voltage switching retains dominance in fixed workplace installations. Chinese manufacturing clusters in Guangdong supply 70% of global AC adapter integration.
- Solar Powered:Photovoltaic panel integration with 15W-25W trickle charging addresses off-grid and outdoor worker applications. Performance limitations restrict adoption to supplementary rather than primary heating functions.
AC powered units retain the largest installed base; USB rechargeable configurations show the steepest expansion trajectory.
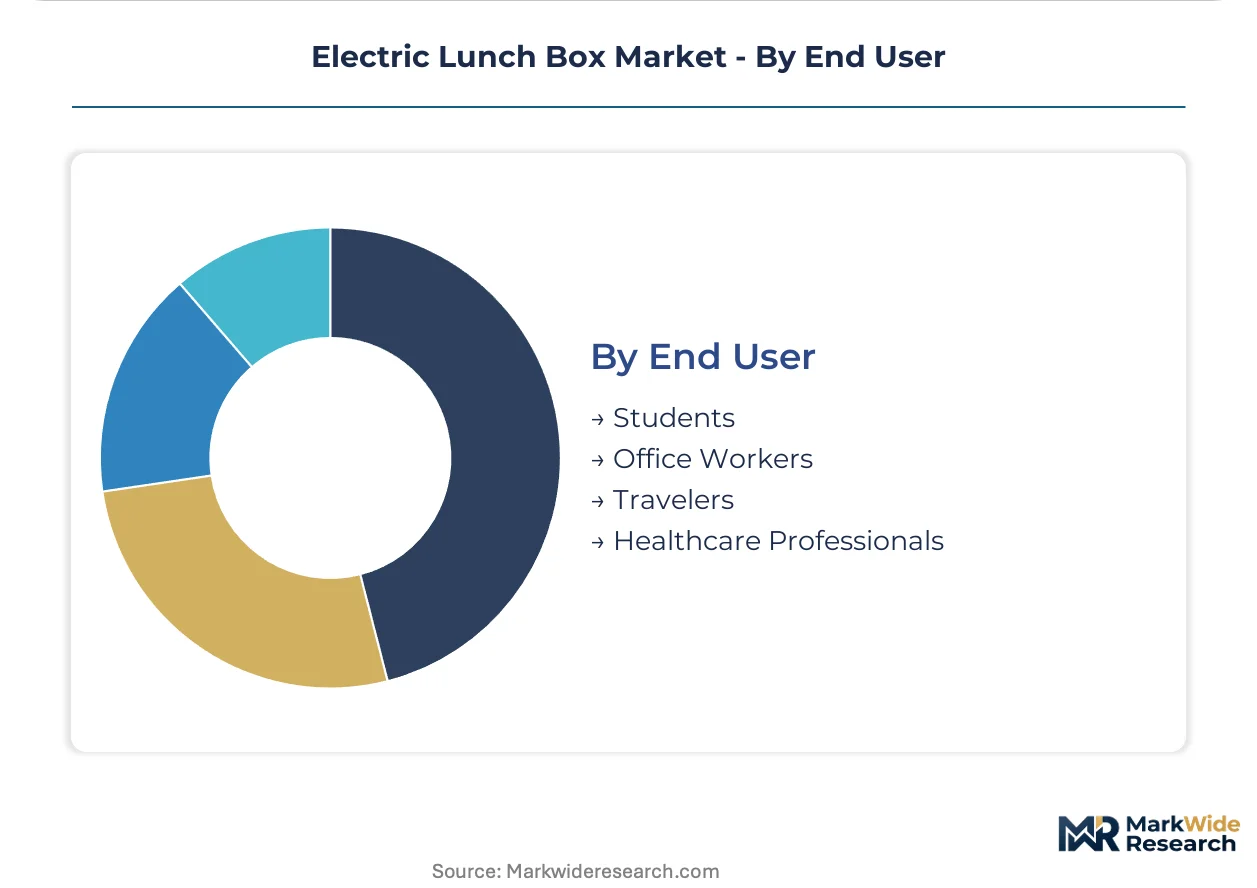
End User:
Customer type segmentation maps directly to usage intensity and replacement cycle frequency.
- Students:Price-optimized single-layer plastic units with 12-month replacement horizons dominate this segment. Campus bookstore and online marketplace channels capture bulk procurement timing around academic calendars.
- Office Workers:Premium stainless steel and double-layer configurations with silent operation features command sustained demand. Corporate wellness stipend models in US tech clusters are shifting procurement from bulk purchase to individual reimbursement.
- Travelers:Collapsible silicone and lightweight battery-operated variants prioritize portability over thermal performance. Airline crew and long-haul truck drivers represent high-frequency use subsegments.
- Healthcare Professionals:FDA 21 CFR compliant materials with autoclave-compatible sterilization cycles address hospital canteen and shift-work requirements. Infection control protocols mandate sealed-lid designs with minimal crevices.
Office workers generate the highest revenue per user; healthcare professionals are expanding most quickly as hospital modernization programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dongguan and Ningbo manufacturing corridors anchor electric lunch box production capacity, with demand dispersion tracking urban commuter density across three continents.
United States
Hybrid office schedules in Seattle and Austin sustain procurement through corporate wellness stipend models rather than bulk purchasing. FDA 21 CFR food-contact regulations enforce polypropylene and stainless steel material standards for import distribution. West Coast technology clusters concentrate demand for USB-C PD compatible units among laptop-carrying professionals.
Germany
Metro rail commuters in Berlin and Munich normalize electric food warming as daily practice for 25-35 minute transit cohorts. EU Green Deal procurement incentives specify repairable appliance criteria favoring modular designs in public sector canteen modernization. REACH Annex XVII restrictions on phthalate plasticizers force 18-month silicone gasket reformulation cycles among domestic distributors.
China
SAMR enforces GB electrical safety standards creating certification divergence from Western UL and CE requirements. Guangdong and Zhejiang provinces cluster 70 percent of global PTC ceramic thermistor production for heating element supply. Shenzhen engineering teams concentrate USB-C PD protocol integration expertise as manufacturers replace proprietary charging architectures.
India
Mumbai, Delhi, and Bengaluru metro extensions create first-time addressable demand among emerging urban commuter segments. BIS certification requirements for small household appliances add regulatory lead time for multi-region suppliers targeting domestic distribution. Campus bookstore channels in Maharashtra and Karnataka capture student segment bulk procurement timing around academic calendars.
Japan
Corporate district office workers in Tokyo and Osaka adopt graphene-enhanced heating films for silent desk-side operation. METI energy efficiency guidelines influence heating element wattage specifications in domestic product development. Kanto region thermal engineering specialists concentrate heat transfer modeling expertise for confined 40-75W enclosure design.
Electric Lunch Box Market Key Industry Players
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base separates between integrated manufacturers with captive molding and assembly operations versus brand marketers outsourcing to contract foundries. Three archetypes dominate: heritage appliance brands leveraging existing distribution, direct-to-consumer specialists optimizing digital acquisition funnels, and contract manufacturers white-labeling for retail private labels. Competitive moves concentrate on USB-C standardization races and lithium iron phosphate battery chemistry transitions.
Within the heritage appliance tier, Hamilton Beach and Crock-Pot anchor positions through existing small appliance retail relationships. Among direct-to-consumer specialists, LunchEAZE exemplifies the cordless lithium-portability vector. Zhengzhou-based Buddew Co., Ltd. and Shenzhen-region contract fabricators occupy the private-label supply base serving volume-tier retail channels.
| Leading Market Players |
|---|
| Buddew |
| Hamilton Beach |
| Crock-Pot |
| Hot Bento |
| Geveniss |
| EAST OAK |
| LunchEAZE |
| Nifogo |
| TRAVELISIMO |
| Others |
Cost & Logistics Intelligence
Corporate wellness stipend models in United States tech clusters are redirecting procurement volumes toward direct-to-consumer channels, forcing manufacturers to absorb last-mile fulfillment costs that bulk B2B contracts previously offset. This demand-side restructuring compresses margin buffers for mid-tier producers while rewarding brands with captive e-commerce infrastructure.
Pricing Analysis
Meal warming throughput per watt-hour serves as the dominant value-based pricing anchor across cordless configurations. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel FDA-grade builds from BPA-free plastic variants and unbranded commodity units. Price differentiation hinges on certification tier and USB-C PD compatibility. Pricing pressure stems from copolyester resin volatility in paraxylene spot markets. Students in India exhibit highest price sensitivity; office workers in Germany show lowest.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Los Angeles anchor hub-and-spoke patterns for European and North American fulfillment. Manufacturing concentrates in China, Vietnam, and Malaysia. PTC ceramic thermistors, lithium iron phosphate cells, and USB-C PD controller chips constitute critical input dependencies. Single-source vulnerability clusters in Guangdong province for heating element supply. Distribution runs through contract fabricators serving private-label retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive lithium iron phosphate cell sourcing to secure thermal stability advantages and margin control against commodity battery price swings.
For Market Incumbents: Anticipate direct-to-consumer specialists eroding traditional retail shelf space through corporate wellness channel partnerships. Defend position by consolidating supplier bases to verified ISO 10993 biocompatibility-certified compounders. Accelerate USB-C PD protocol integration through Shenzhen engineering partnerships to maintain charging standardization leadership. For New Entrants and Emerging Players: Direct-to-consumer subscription bundling with meal kit providers offers the lowest customer acquisition cost route. White-space targets include collapsible silicone variants for airline crew segments and Bluetooth-enabled temperature logging for smart kitchen ecosystem integration. India urban commuter expansion presents the most penetrable geography. For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with captive molding operations and multi-jurisdiction certification capabilities. Long-term viability centers on modular repairable designs qualifying for EU Green Deal procurement incentives. Watch IATA lithium battery shipping regulation revisions as inflection indicator for cordless variant cross-border fulfillment economics.| Strategic Initiative | Industry Significance |
|---|---|
| USB-C PD Standardization | 45W-100W input compatibility leverages existing laptop charging infrastructure across hybrid workforce segments. |
| LiFePO4 Battery Transition | Thermal stability advantages during extended heating cycles displace cobalt-based alternatives in premium tiers. |
| REACH Compliance Reformulation | 18-month silicone gasket qualification cycles secure CE marking for European distribution channels. |
| Direct-to-Consumer Channel Shift | Corporate wellness stipend models in Seattle and Austin bypass traditional office supply procurement. |
| Modular Repairable Design | EU Green Deal criteria favor component replacement over disposal in French and Italian public canteen tenders. |
Research Approach
Document review covered customs records, SAMR GB standard filings, and FDA 21 CFR food-contact guidance, complemented by interviews with product development executives at heritage appliance brands, procurement leads at direct-to-consumer specialists, thermal engineering specialists in Dongguan manufacturing zones, and category buyers at mass retail chains. Secondary validation drew from SEC 10-K filings, EU REACH Annex XVII restriction updates, and IATA lithium battery shipping guidelines. Bottom-up unit economics modeling and top-down category sizing were cross-referenced for triangulation.
Cross-reference between historical shipment data and expert panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, material certification tier, power source configuration, and end-user commute duration. CAGRs were derived from slope analysis of normalized adoption curves. Industry-specific forecast inputs incorporated metro rail network extension timelines and corporate return-to-office policy trajectories.
Inputs from SAMR certification databases and EU procurement tender portals were available through the study window; gaps in real-time BIS approval timelines for India introduce uncertainty bands for South Asia penetration assumptions. Forecasts reflect documented assumptions regarding battery chemistry transition rates and USB-C protocol adoption velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
France Cookware Market
Kitchen Appliances
Europe Smart Cooker Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Household Kitchen Appliances Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Portable Sandwich Maker Market