
 Tabletop Kitchen Products Market | 2026-2036
Tabletop Kitchen Products Market Size, Share, and Industry Trends Forecast 2026-2036
Tabletop Kitchen Products Market Intelligence
Asset-light leasing models for commercial equipment is tilting the competitive landscape toward service-oriented suppliers. Steelite International leverages its extensive distribution network to serve the global hospitality industry. Villeroy & Boch AG sustains its market position through premium brand recognition and a dual focus on commercial and retail channels, while The Vollrath Company, LLC specializes in durable products for food service operations.
Tabletop kitchen products encompass items designed for serving, dining, and culinary presentation. These products, such as vitrified ceramic dinnerware, are engineered for specific performance attributes like durability, chip resistance, and low water absorption to meet rigorous commercial-use standards. Their primary purpose is to combine functional food containment with the aesthetic enhancement of the dining experience. The Dinnerware and Drinkware segments constitute the largest product categories, while materials like Melamine gain traction over traditional Ceramic in high-volume settings like cafés due to superior durability.
Product safety and material composition are governed by a complex set of international standards. Regulations such as the US FDA's Food Code, the EU's REACH framework for chemical safety in glazes, and China's GB standards for food contact materials dictate market access. Navigating these divergent material compliance requirements while optimizing for aesthetics and cost is the central challenge for manufacturers. Success will depend on managing supply chain costs for both commodity and premium product tiers across multiple regulatory jurisdictions.
Market Dynamics
The market's structure is defined by the tension between global hospitality's demand for aesthetic novelty and the fragmented, stringent regulatory landscape for food-contact materials, led by the US FDA, Europe's EFSA, and China's GB standards.
Growth Catalysts
- Hospitality Expansion:Rapid hotel and restaurant development in urban centers across India and the United Arab Emirates creates concentrated pockets of high-volume demand for durable, commercial-grade tabletop products.
- Material Innovation:The adoption of melamine over traditional ceramic in high-turnover environments like cafes and institutional catering enhances durability, reduces long-term replacement costs, and lowers breakage rates.
- Catering Sector Growth:The global expansion of corporate and event catering services necessitates larger, standardized inventories of professional-grade dinnerware and drinkware that meet rigorous commercial-use standards.
Market Restraints
- Input Cost Volatility:Fluctuations in energy prices and the cost of raw materials like high-purity clays and specialty resins for melamine production create significant margin pressure for manufacturers.
- Regulatory Divergence:Manufacturers face high compliance costs navigating disparate chemical safety rules for glazes and base materials under frameworks like the EU's REACH and the US FDA's Food Code.
- Substitution from Disposables:In quick-service and fast-casual dining, high-quality disposable tableware presents a persistent substitution threat, especially where operational efficiency is prioritized over dining experience aesthetics.
Strategic Opportunities
- Emerging Market Penetration:Targeting the growing tourism and hospitality sectors in Southeast Asian and Latin American countries offers new avenues for growth beyond traditionally dominant markets.
- Smart Tableware Development:Integrating RFID tags into dinnerware allows large-scale operators like hotels and convention centers to automate inventory management, track usage patterns, and reduce theft.
- D2B E-Commerce Channels:Building direct-to-business e-commerce platforms enables manufacturers to service small and medium-sized hospitality businesses, bypassing traditional, multi-layered distribution networks.
Industry Challenges
- Multi-Jurisdictional Compliance:Managing a global supply chain that sources materials and sells finished goods across different regulatory zones like the EU and China requires significant investment in compliance and logistics expertise.
- Performance-Aesthetic Trade-off:Engineers face the constant challenge of developing products that satisfy the aesthetic demands of premium restaurants while meeting non-negotiable commercial standards for chip resistance and low water absorption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tabletop Kitchen Products Market |
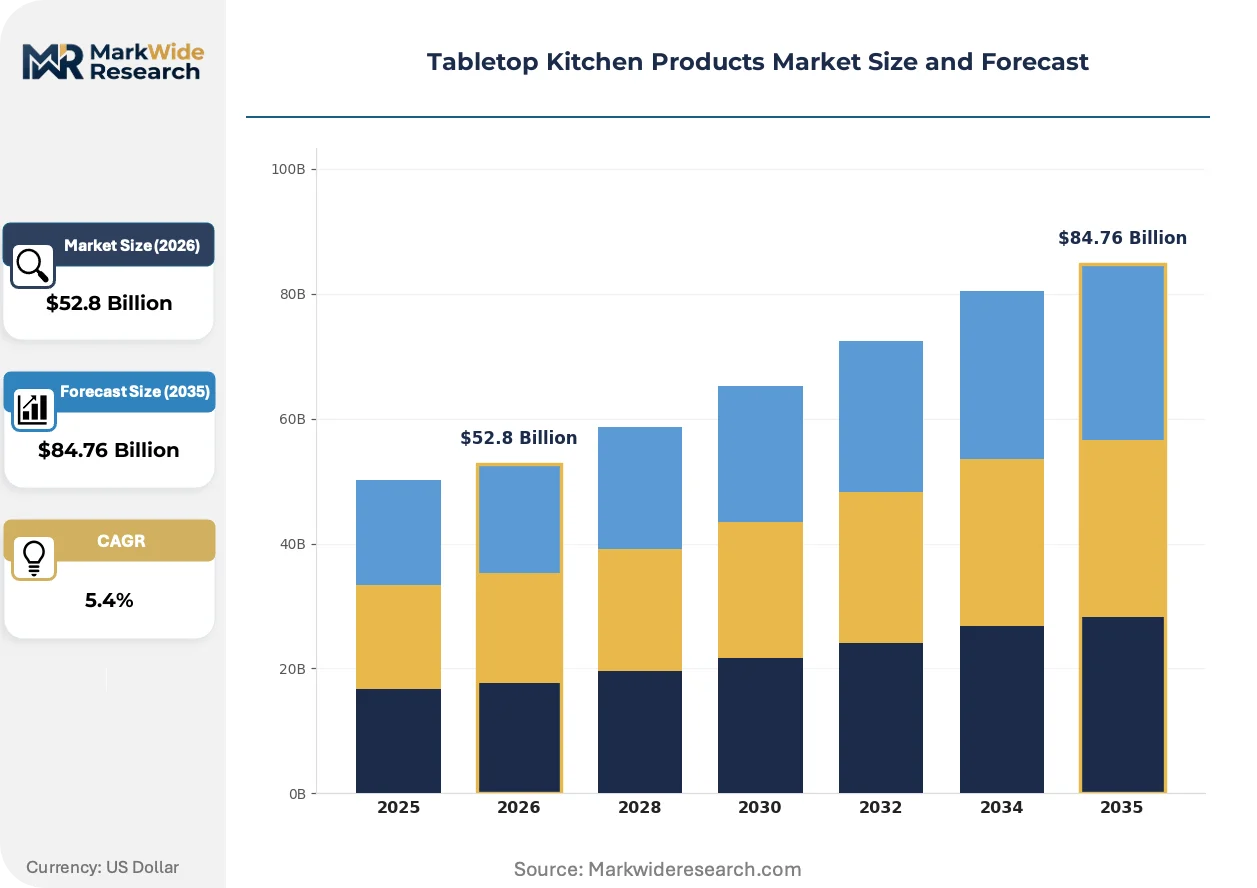
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $84.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dinnerware, Drinkware, Flatware, Serveware Material: Ceramic, Glass, Stainless Steel, Melamine Form: Round, Square, Oval, Rectangular End User: Restaurants, Cafés, Home Users, Catering Services |
| Companies Covered | Arc International, The Oneida Group, Inc., Villeroy & Boch AG, Lenox Corporation, Steelite International, Libbey, Inc., Noritake Co., Limited, The Vollrath Company, LLC, Haier Smart Home Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tabletop Kitchen Products Market Strategic Shifts & Innovations
Material science advancements are intersecting with circular economy principles, compelling manufacturers to innovate beyond aesthetics and durability. This shift prioritizes products with verifiable sustainability credentials and lower lifecycle environmental impact across the industry.
Embedded RFID and NFC technology in vitrified ceramic dinnerware provides a unique identifier for each item. Large hospitality chains and event rental companies are the primary adopters, seeking to minimize loss and automate stock-taking processes. This integration is digitizing back-of-house asset management, replacing manual inventory counts with real-time, automated tracking systems for greater operational efficiency.
The EU's REACH framework, along with similar chemical safety regulations, imposes strict limits on heavy metals like lead and cadmium in ceramic glazes. This forces manufacturers to invest in R&D for compliant, non-toxic formulations that do not compromise the product's aesthetic quality or durability. The premium dinnerware segment is most affected, as it relies on complex glazes for unique visual effects.
A notable behavioral change is the move toward asset-light equipment leasing models, particularly for new hotel openings and large event caterers. This model disrupts traditional upfront capital sales through distributors, favoring suppliers that offer bundled service, replacement, and maintenance contracts. The trend is most prominent in mature hospitality markets in North America and Western Europe where operational expenditure models are preferred.
Tabletop Kitchen Products Market Segmentation
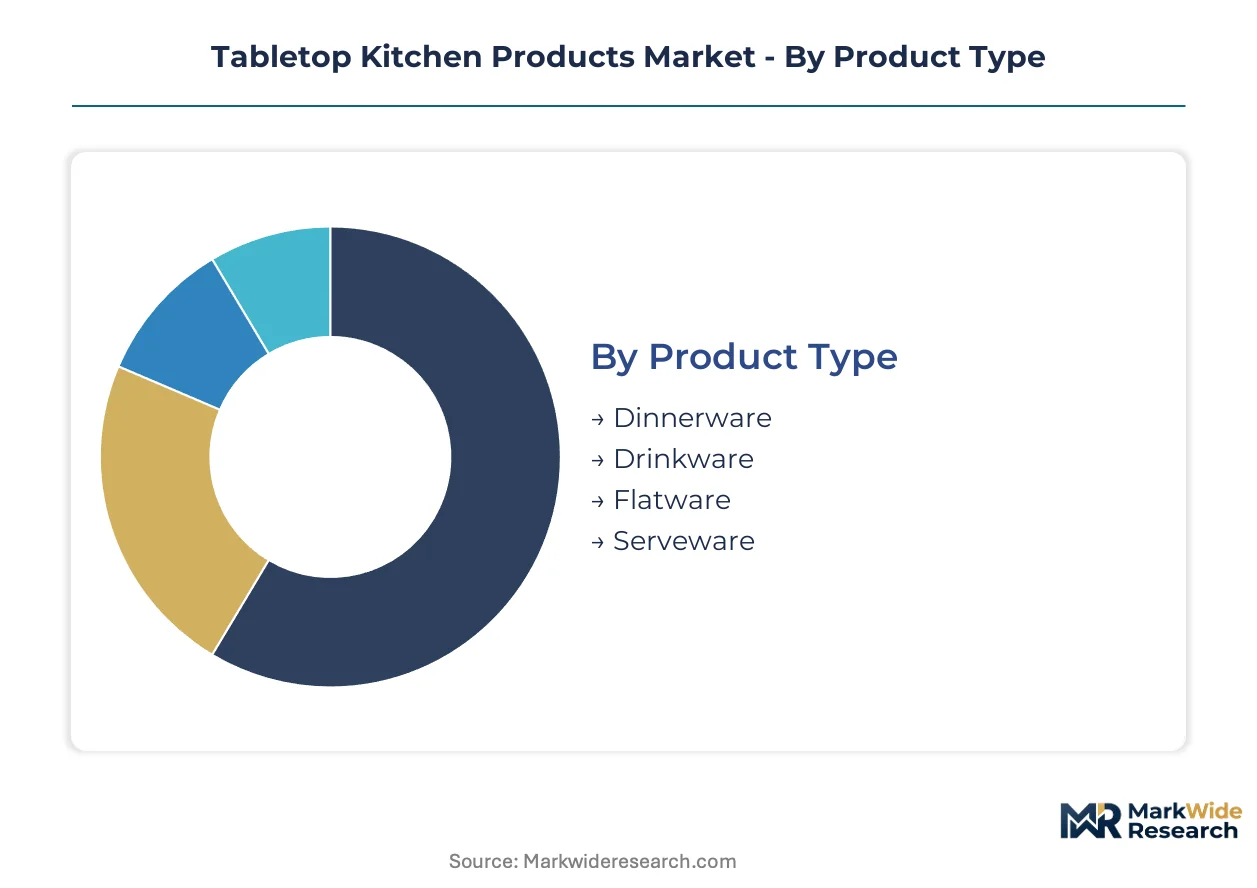
The Tabletop Kitchen Products market segmentation illuminates specific demand patterns and operational requirements across diverse user groups. Understanding these distinctions helps manufacturers align product development with commercial imperatives. This granular view informs strategic decisions on material innovation and distribution channel optimization.
Product Type:
The intensity of after-sales service and replacement cycles significantly influences procurement decisions within product type categories.
- Dinnerware:Vitrified ceramic plates, bowls, and platters are engineered for chip resistance and low water absorption in commercial settings. Demand is concentrating in urban centers of the United Arab Emirates and India, driven by new hotel and restaurant openings requiring durable, aesthetically pleasing sets.
- Drinkware:Glassware, cups, and mugs designed for beverage service often prioritize clarity, thermal shock resistance, and stackability for high-volume operations. The catering services sector globally necessitates large, standardized inventories of professional-grade drinkware for event scalability and consistent presentation.
- Flatware:Utensils like forks, knives, and spoons are typically made from stainless steel, emphasizing ergonomic design and resistance to corrosion from frequent washing.
- Serveware:Serving dishes, platters, and bowls facilitate food presentation, often requiring heat retention properties and compatibility with buffet systems.
By volume, Dinnerware leads. By growth pace, Drinkware is ahead.
Material:
Different material compositions carry distinct cost tiers, impacting initial investment and long-term operational expenses for hospitality businesses.
- Melamine:This durable, lightweight plastic is favored for its superior break resistance and lower replacement costs compared to traditional ceramics in high-volume environments. Cafés and institutional catering operations are adopting melamine over traditional ceramic due to its enhanced durability and reduced breakage rates.
- Ceramic:Comprising vitrified china and porcelain, ceramic products offer premium aesthetics, heat retention, and a traditional dining experience. The premium dinnerware segment is most affected by EU REACH regulations, necessitating R&D into compliant, non-toxic glazes without compromising visual effects.
- Stainless Steel:Known for its strength and corrosion resistance, stainless steel is primarily used in flatware and certain serveware items requiring high durability and hygiene.
- Glass:Used extensively in drinkware, glass provides transparency and elegance, with specialized formulations offering improved chip resistance for commercial use.
Melamine is gaining favor due to its durability, while Ceramic retains its premium market position.
Form:
The chosen form factor for tabletop products often aligns with specific culinary presentations and aesthetic themes in hospitality venues.
- Round:This classic shape provides versatility and familiarity, seamlessly integrating into diverse dining environments from casual to formal. Restaurants globally consistently demand round dinnerware and drinkware for its universal appeal and ease of stacking in commercial kitchens.
- Square:Offering a contemporary and architectural aesthetic, square forms are popular in modern fine dining establishments and boutique hotels. Designers in urban hospitality centers, particularly in Europe and North America, frequently specify square tableware to achieve distinct visual impact.
- Oval:Oval shapes provide an elegant alternative for serving platters and specialized dishes, often enhancing food presentation for shared plates.
- Rectangular:Rectangular forms are commonly used for serving boards, buffet displays, and some contemporary plate designs, optimizing space on tables and counters.
Round forms maintain broad appeal, while Square forms capture modern design preferences.
End User:
The volume and frequency of product usage vary significantly across different end-user segments, dictating durability and inventory requirements.
- Restaurants:Commercial restaurants require extensive inventories of durable, chip-resistant products that withstand frequent washing and heavy use. Hospitality expansion in India and the United Arab Emirates fuels concentrated demand for professional-grade dinnerware and drinkware in this segment.
- Catering Services:Event and corporate catering operations necessitate large, standardized sets of professional-grade products for mobility, consistent presentation, and inventory management. The global expansion of the catering sector drives demand for standardized, easily replaceable items that meet rigorous commercial-use standards.
- Cafés:Cafés prioritize durable, often melamine-based, products that can withstand high turnover and frequent washing, balancing cost-effectiveness with aesthetic appeal.
- Home Users:This segment focuses on retail sales, where aesthetic variety, brand recognition, and price points cater to individual consumer preferences for personal dining.
Commercial end-users like Restaurants and Catering Services drive significant volume, with Home Users representing a distinct retail channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's REACH framework and similar global regulations are compelling manufacturers to innovate materials and processes for tabletop kitchen products. These stringent standards, particularly for food-contact materials, reshape product development and market access across key regions. Compliance with diverse chemical safety rules drives significant investment in research and development for non-toxic formulations.
United Arab Emirates
Rapid hotel and restaurant development fuels concentrated demand for durable, commercial-grade tabletop items. MOHAP (Ministry of Health and Prevention) regulations ensure food safety and material compliance for hospitality products. Dubai and Abu Dhabi's burgeoning hospitality sectors are concentrating high-volume demand for aesthetically pleasing and robust dinnerware.
India
Hospitality expansion in urban centers creates concentrated demand for professional-grade dinnerware and drinkware. FSSAI (Food Safety and Standards Authority of India) mandates specific material safety for food contact applications. Major urban centers like Mumbai and Delhi are experiencing significant demand for standardized, easily replaceable items in catering services.
Germany
Premium brand recognition and a dual focus on commercial and retail channels sustain market demand for high-quality products. The EU's REACH framework significantly influences material choices for ceramic glazes and production processes. Major cities like Berlin and Munich, with their mature hospitality markets, increasingly adopt asset-light equipment leasing models.
United States
Large-scale hospitality operations and the quick-service dining sector drive demand for durable and innovative tabletop solutions. The US FDA's Food Code sets rigorous standards for food-contact materials and product safety. Urban hubs such as New York and Los Angeles are early adopters of RFID-integrated dinnerware for automated inventory management.
China
The expanding catering sector and rapid hospitality growth create substantial demand for high-volume tabletop products. China's GB standards for food contact materials dictate market access and material composition for manufacturers. Major metropolitan areas like Shanghai and Beijing drive demand for durable, commercial-grade items in their expanding hospitality sectors.
Tabletop Kitchen Products Market Key Industry Players
On the supply side, the industry is characterized by a mix of established players and emerging specialists. The competitive landscape includes premium brand manufacturers, volume-driven producers, and service-oriented suppliers leveraging asset-light models. Companies differentiate through material innovation, distribution network strength, and regulatory compliance expertise. Dominant competitive moves include strategic partnerships for market access and continuous investment in research and development for product durability and aesthetics.
On the premium-tier vector, Villeroy & Boch AG sustains its market position through strong brand recognition and a dual focus on commercial and retail channels. Steelite International exemplifies a service-oriented supplier, leveraging its extensive distribution network to serve the global hospitality industry with asset-light leasing models. The Vollrath Company, LLC occupies a position specializing in durable products for high-volume food service operations, emphasizing longevity and functional performance. These entities collectively anchor distinct segments, from high-end commercial dining to robust institutional catering, responding to varied end-user requirements across different material and aesthetic preferences.
| Leading Market Players |
|---|
| Arc International |
| The Oneida Group, Inc. |
| Villeroy & Boch AG |
| Lenox Corporation |
| Steelite International |
| Libbey, Inc. |
| Noritake Co., Limited |
| The Vollrath Company, LLC |
| Haier Smart Home Co., Ltd. |
| Others |
Cost & Logistics Intelligence
China's extensive manufacturing capacity for ceramic and melamine products significantly influences global tabletop kitchen product pricing. This supply concentration creates cost efficiencies that impact market entry points and competitive dynamics.
Pricing Analysis
Certification level (such as US FDA Food Code compliance and EU REACH conformity) creates the primary spread in tabletop product pricing. The dominant pricing model is per-unit transactional, with some asset-light leasing models emerging for large commercial buyers. Price differentiation stems from material quality, brand recognition, and after-sales service bundles. Pricing softness runs through the high-volume, standard-tier segment due to intense competition and material cost volatility. Commercial end-users like catering services are highly price-sensitive, while premium restaurants prioritize brand and aesthetic quality.
Supply Chain Analysis
Manufacturing concentration in China and India drives global supply for many tabletop kitchen product categories. This supply chain draws from high-purity clays, specialty resins for melamine, and stainless steel as primary raw materials. Commodity price volatility, particularly for energy and resins, represents a structural supply chain risk. Distribution runs through established networks of commercial distributors, increasingly supplemented by direct-to-business e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tabletop kitchen products market presents a fragmentation opportunity, driven by the diverse aesthetic demands of global hospitality and varied regional regulatory requirements. This creates niches for specialized product offerings.
For Market Incumbents: Harden supply chain resilience by diversifying raw material sourcing beyond single-country dependencies, especially for high-purity clays and specialty resins. Invest in R&D for compliant, non-toxic glazes to mitigate regulatory threats like EU REACH. Expand asset-light leasing models to counter traditional sales disruption and attract new hotel openings. Control over distribution networks remains a critical lever against emerging D2B e-commerce platforms.
For New Entrants and Emerging Players: Southeast Asian hospitality markets represent a geographic underpenetration, offering white-space for durable, commercial-grade dinnerware. Target small and medium-sized hospitality businesses with D2B e-commerce channels, bypassing traditional distributors. Focus on material innovation, like advanced melamine formulations, to offer superior durability and lower replacement costs in high-volume settings. This go-to-market angle leverages operational efficiency as a primary value proposition.
For Investors and Strategic Acquirers: Long-term, this sits as a stable infrastructure play because of consistent demand from the global hospitality sector and catering services. Acquisition targets should be vertically integrated mid-cap specialists with strong regional distribution networks and regulatory compliance expertise. Focus on companies that possess proprietary material science for chip resistance or low water absorption. The signal to watch is the adoption rate of smart tableware technology in large hotel chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in RFID/NFC Integration | Automates inventory management for large hospitality operators, reducing loss and streamlining stock-taking processes. |
| Develop REACH-Compliant Glazes | Secures market access in Europe for premium ceramic dinnerware, meeting stringent chemical safety regulations. |
| Expand Asset-Light Leasing Models | Attracts new hotel openings and event caterers in mature markets by shifting capital expenditure to operational expenditure. |
| Penetrate Southeast Asian Markets | Captures new demand from rapidly expanding tourism and hospitality sectors beyond traditionally dominant regions. |
| Enhance D2B E-commerce Platforms | Directly services small and medium-sized hospitality businesses, bypassing multi-layered traditional distribution networks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with extensive secondary validation. Stakeholder roles included hospitality procurement managers, material scientists, regulatory compliance officers, and distribution channel executives. Secondary data sources comprised government food safety regulations (e.g., US FDA, EU EFSA), industry association reports, and corporate financial filings from key market players. Bottom-up and top-down triangulation ensured data accuracy and market sizing.
The analytical framework's calibration approach synthesized historical trends with projected market dynamics across the analysis window. Segmentation dimensions modeled included product type, material composition, end-user category, geographic region, and regulatory compliance tiers. Compound annual growth rates were derived through a regression analysis of demand drivers and supply-side capacity. Urbanization rates in India and UAE, alongside global catering service expansion, served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global premium brands or volume-driven producers would shift outcomes. Fluctuations in raw material costs or unforeseen regulatory shifts could also impact market trajectory. Quarterly review of hospitality investment trends and material science patents is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market
Kitchen Appliances
Residential Hobs Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
Electric Countertop Griddles Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
US Induction Cookware Market
Kitchen Appliances
Asia Pacific Induction Hobs Market
Kitchen Appliances
France Cookware Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
United Kingdom Kitchen Appliances Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market
Kitchen Appliances
United States Electric Vegetable Choppers Market