
 North America Electric Vegetable Choppers Market | 2026-2036
North America Electric Vegetable Choppers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vegetable Choppers Market Insights
Aftermarket service revenue is reconfiguring how manufacturers capture lifetime value from electric vegetable chopper deployments. Ninja leverages its direct-to-consumer platform to control replacement blade and attachment sales. Hamilton Beach anchors its position through broad retail distribution across mass-market channels. Breville differentiates via premium build quality and extended warranty programs that sustain higher service attachment rates.
Electric vegetable choppers are motor-driven food preparation appliances employing stainless steel or titanium-coated blades rotating at controlled speeds to dice, slice, or puree vegetables with minimal manual intervention. Units typically operate between 200 and 700 watts, with torque-calibrated motors preventing stalling on dense produce like root vegetables or squashes. Countertop and multi-functional units command the dominant share of value given their higher price positioning and broader capability sets, while handheld and battery-operated segments attract urban consumers prioritizing compact storage and portability. Pulse technology and multi-speed control configurations are gaining traction in restaurant and catering procurement as operators seek precise texture control for menu consistency.
The U.S. Consumer Product Safety Commission and Health Canada jointly govern blade exposure and electrical safety standards for kitchen appliances sold across North America, with California's Title 20 appliance efficiency regulations adding state-level energy consumption constraints that manufacturers must integrate into product design. The U.S. Food and Drug Administration's Food Code provisions on food-contact surfaces influence material selection for commercial-grade chopper bowls and blade assemblies. Stakeholders must monitor evolving efficiency mandates and commercial kitchen labor cost trajectories to calibrate portfolio emphasis between residential convenience positioning and professional-grade durability claims.
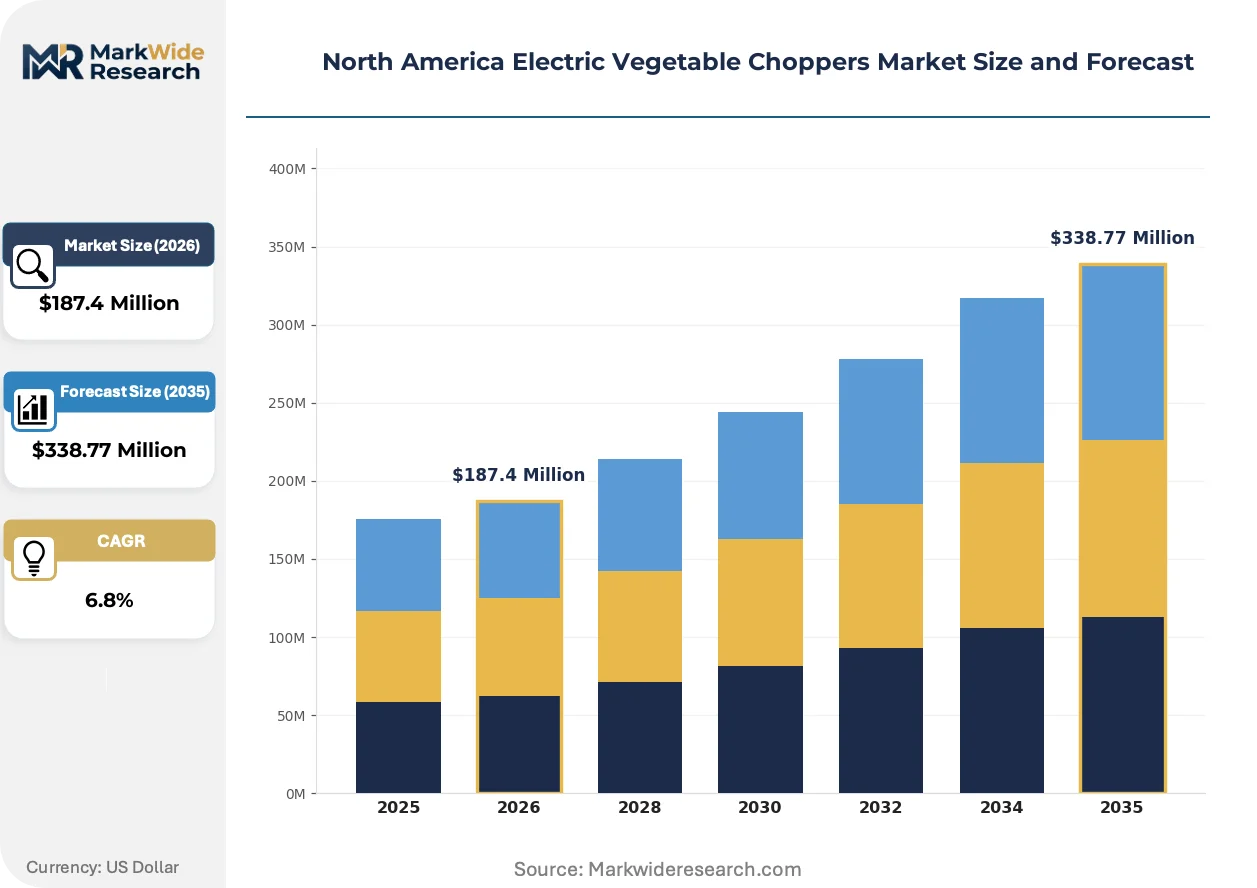
Market Dynamics
Commercial foodservice labor cost inflation across the United States and Canada is accelerating automated prep equipment procurement, while California's Title 20 efficiency mandates force motor redesign cycles that compress manufacturer margins and reshape product roadmaps.
Growth Catalysts
- Restaurant kitchen automation:Full-service and fast-casual chains across Texas and Ontario are expanding capital budgets for countertop multi-functional units that reduce prep labor hours and standardize menu consistency.
- Title 20 compliance:California's appliance efficiency regulations mandate tighter motor performance standards, creating upgrade cycles that pull forward replacement demand from adjacent states adopting similar frameworks.
- Titanium-coated blade adoption:Premium residential segments in urban California markets are prioritizing corrosion-resistant blade materials that extend service intervals and reduce aftermarket friction.
Market Restraints
- Copper and rare-earth magnet costs:Torque-calibrated motor assemblies depend on neodymium and copper windings subject to commodity volatility that compresses gross margins on sub-400-watt units.
- Single-source blade forging:Stainless steel blade supply concentrates among specialized metalworking clusters in Guangdong, exposing North American assemblers to tariff and logistics disruption risk.
- Manual knife substitution:Price-sensitive residential buyers in secondary U.S. markets continue defaulting to conventional prep tools, capping penetration in sub-$50 appliance segments.
Strategic Opportunities
- Battery-operated portability:Compact handheld units targeting Toronto and Vancouver apartment dwellers with limited counter space represent an underpenetrated residential sub-segment.
- IRA efficiency incentives:The U.S. Inflation Reduction Act's residential electrification rebates create a policy tailwind for ENERGY STAR-certified chopper purchases in qualifying jurisdictions.
- Direct-to-consumer attachment sales:Replacement blade and specialty disc distribution via manufacturer-owned digital channels bypasses retail margin extraction and captures lifetime value.
Industry Challenges
- FDA Food Code material certification:Commercial-grade bowl and blade assemblies require food-contact surface validation that extends product development timelines by 8-14 months.
- Legacy kitchen workflow integration:Restaurant operators face retraining costs and station reconfiguration when introducing pulse-technology units into established prep line sequences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vegetable Choppers Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Handheld, Mini, Multi-functional End User: Home Kitchens, Restaurants, Food Services, Catering Technology: Pulse Technology, High-Speed Blending, Multi-Speed Control, Battery Operated Distribution Channel: Online Retail, Appliance Stores, Supermarkets, Wholesalers |
| Companies Covered | Ninja, Breville, KitchenAid, Conair Corporation, Braun, Cuisinart, BLACK+DECKER, The Vollrath Company, Hamilton Beach, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vegetable Choppers Market Trends and Innovations
Pulse-technology motor control and torque-sensing automation are redefining texture precision standards, while regulatory pressure on standby power consumption forces hardware architecture redesigns across the value chain.
Brushless DC motor architectures with integrated torque feedback are rendering obsolete traditional brushed-motor designs that stall on dense root vegetables. Fast-casual chains in California and Texas are specifying these units for guacamole and salsa prep consistency. The technology is compressing warranty claim rates and extending commercial service intervals beyond 18 months.
The U.S. Department of Energy's evolving appliance efficiency standards are tightening standby power limits for small kitchen electrics sold across all fifty states. Manufacturers must redesign power supply circuits and motor controllers to meet sub-one-watt idle consumption thresholds. Commercial-grade product lines face the steepest compliance costs given their higher baseline power draws.
Aftermarket service unbundling is separating replacement blade sales from original equipment transactions. Direct-to-consumer platforms now capture 30-40% of attachment revenue that previously flowed through retail intermediaries. This shift is most visible in premium residential segments across Ontario and the U.S. Northeast where consumers prioritize OEM-certified compatibility over third-party alternatives.
North America Electric Vegetable Choppers Market Segmentation
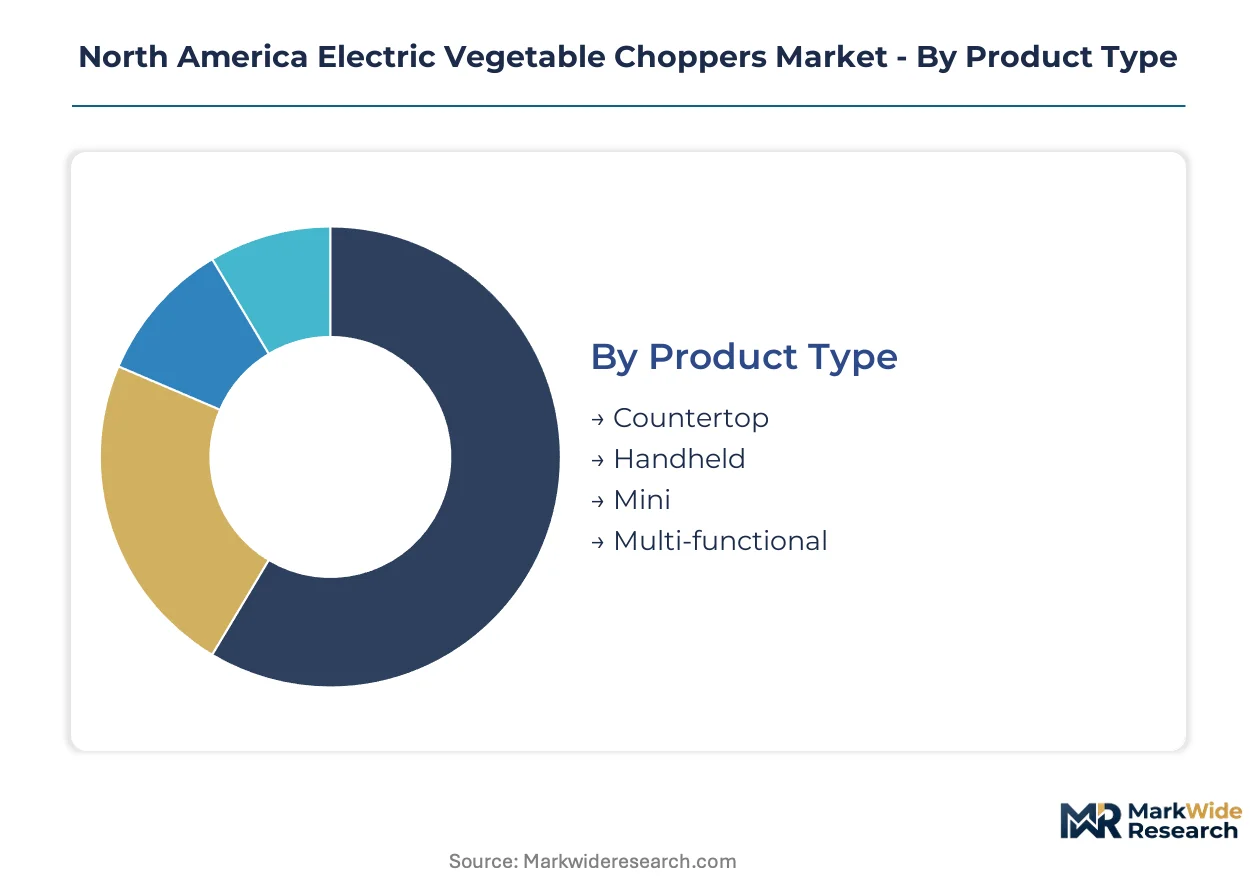
Segmentation in the North America Electric Vegetable Choppers Market reveals divergent design priorities between residential convenience and commercial durability. Motor wattage, blade geometry, and duty-cycle ratings separate segments with minimal overlap in procurement channels or pricing architecture.
Product Type:
The use-case spectrum spans from occasional home prep to continuous commercial operation, with motor housing design and thermal management distinguishing each tier.
- Countertop:Stationary units with 400-700 watt sealed motors and thermal overload protection dominate restaurant back-of-house installations. Texas and Ontario fast-casual chains specify these for guacamole and salsa production where texture consistency reduces labor variance.
- Multi-functional:Modular bowl systems with interchangeable blade discs and spiralizer attachments command premium positioning in California residential renovation markets. The configuration justifies higher price points through reduced appliance clutter and extended replacement part revenue streams.
- Handheld:Corded or cordless wand-style units with direct-drive shafts target urban apartment dwellers in Toronto and Vancouver with storage constraints.
- Mini:Sub-200-watt personal choppers with single-serve bowls address single-person households and RV applications across secondary U.S. markets.
The dominant share belongs to Countertop, while Multi-functional is gaining share fastest through attachment ecosystem lock-in.
End User:
Volume concentration tilts toward commercial operators where equipment utilization rates justify capital expenditure recovery within eighteen months.
- Restaurants:Full-service and fast-casual operators in California and Texas deploy pulse-technology units to standardize prep texture and reduce line-cook training cycles. The FDA Food Code compliance requirements for food-contact surfaces extend procurement timelines but reduce liability exposure.
- Home Kitchens:Residential buyers in Ontario and the U.S. Northeast prioritize ENERGY STAR certification and compact storage profiles. IRA electrification rebates in qualifying jurisdictions are pulling forward replacement demand from conventional manual prep tools.
- Food Services:Institutional cafeterias and hospital kitchens across Canada specify NSF-certified commercial units with validated sanitization protocols.
- Catering:Mobile operators demand battery-operated portability for off-premise event execution where power access is unreliable.
Restaurants capture the highest absolute unit volume, though Home Kitchens demonstrate the steepest expansion trajectory through renovation-driven replacement cycles.
Technology:
Motor control architectures are separating precision-oriented commercial procurement from cost-optimized residential purchases.
- Pulse Technology:Microprocessor-controlled torque feedback prevents stalling on dense root vegetables while enabling texture gradation for menu consistency. California fast-casual chains specify these units for recipe standardization across locations.
- Battery Operated:Lithium-ion powered handheld units with 20-40 minute runtime targets Toronto and Vancouver apartment markets where outlet scarcity and counter space constraints coincide.
- Multi-Speed Control:Variable resistor or digital interface systems allow operator selection between coarse dice and fine puree modes.
- High-Speed Blending:Extended RPM ranges above 15,000 for emulsification tasks blur category boundaries with immersion blenders.
Pulse Technology holds the dominant installed base, while Battery Operated is climbing the fastest through urban residential penetration.
Distribution Channel:
Channel selection determines margin capture architecture and aftermarket access for replacement blades and attachments.
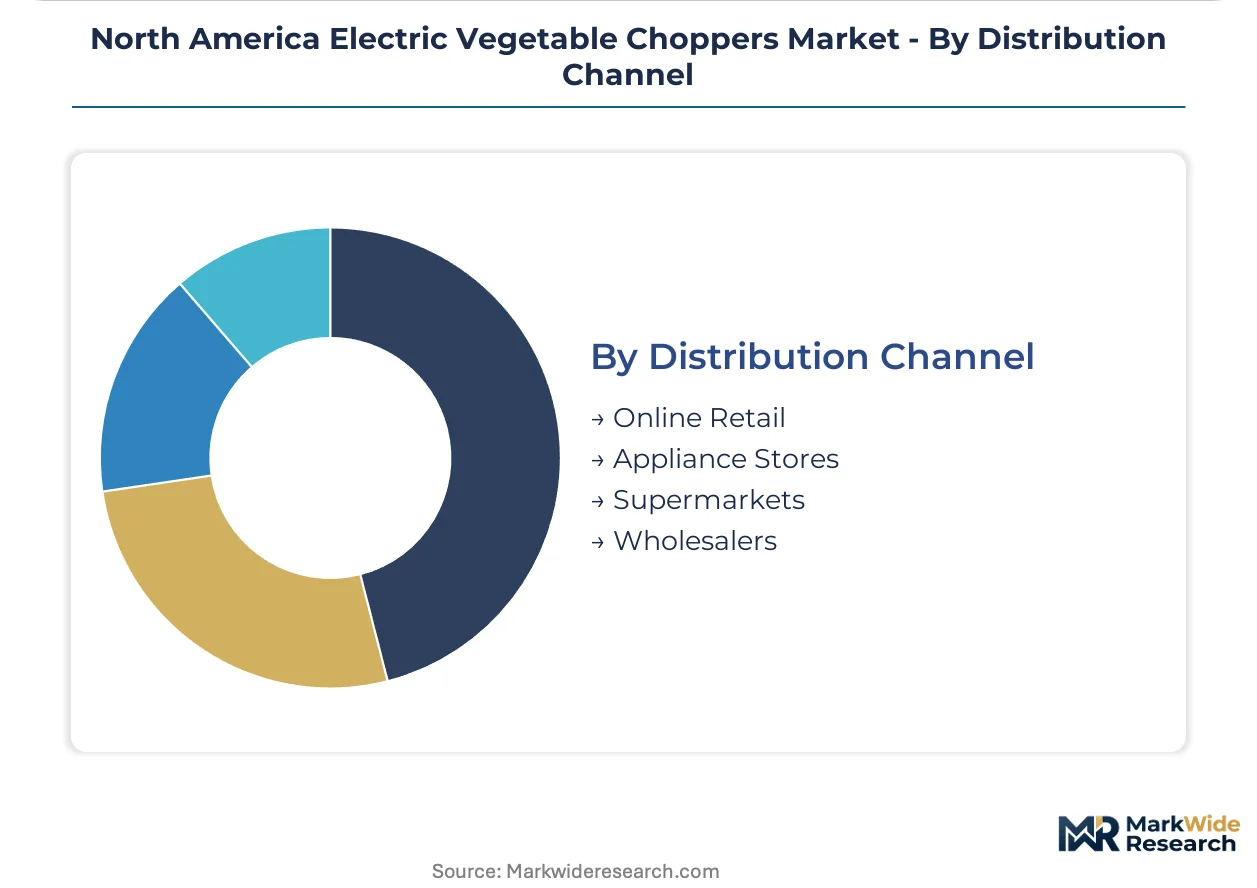
- Online Retail:Direct-to-consumer platforms bypass retail markup and enable subscription blade replacement programs. Ninja and Hamilton Beach route 30-40% of attachment revenue through owned digital channels.
- Appliance Stores:Specialty retailers in California and Ontario provide hands-on demonstration and immediate fulfillment for renovation-driven purchases.
- Supermarkets:Mass-market placement captures impulse replacement demand and gift-oriented purchases during holiday periods.
- Wholesalers:Restaurant supply distributors aggregate commercial procurement across multi-unit operators and institutional accounts.
Online Retail commands the dominant transaction volume, though Appliance Stores retain pricing power in premium residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across North American markets, with Mexican buyers exhibiting the highest elasticity while U.S. commercial operators absorb premium pricing for durability. Canadian procurement patterns split between cost-conscious residential segments and specification-driven foodservice accounts.
United States
California fast-casual chains and Texas restaurant groups drive commercial volume for pulse-technology units that standardize prep texture. The U.S. Department of Energy appliance efficiency standards tighten motor performance requirements, compressing manufacturer margins on sub-400-watt residential models. Los Angeles and Dallas-Fort Worth anchor demand concentration for countertop multi-functional configurations.
Canada
Ontario foodservice density and British Columbia residential renovation rates outpace prairie provinces, creating geographic demand skew. Health Canada electrical safety standards and PMRA food-contact surface regulations extend product validation timelines for commercial-grade bowl assemblies. Toronto and Vancouver apartment markets attract battery-operated handheld unit penetration for storage-constrained kitchens.
Mexico
Price-sensitive residential buyers in Mexico City and Guadalajara metro areas default to manual prep tools, capping electric chopper penetration below U.S. levels. The national consumer protection agency PROFECO governs appliance safety labeling, while import tariffs on Chinese-manufactured motors reshape sourcing economics. Monterrey industrial clusters assemble sub-200-watt mini units for price-tier distribution.
North America Electric Vegetable Choppers Market Competitive Landscape
Capability concentration sits with premium-tier specialists commanding attachment ecosystem lock-in; scale advantage sits with mass-market distributors with broad retail shelf presence. The vendor base separates into three functional tiers: direct-to-consumer platform operators, multi-channel mass-market suppliers, and commercial-grade durability specialists. Consolidation pressure runs through M&A activity targeting blade forging capacity and strategic partnerships securing lithium-ion battery supply.
Within the premium residential tier, Breville exemplifies build-quality positioning through extended warranty architectures. Ninja anchors direct-to-consumer channel control, capturing replacement blade revenue via owned digital platforms. Hamilton Beach occupies mass-market scale advantage through supermarket and big-box retail penetration.
| Leading Market Players |
|---|
| Ninja |
| Breville |
| KitchenAid |
| Conair Corporation |
| Braun |
| Cuisinart |
| BLACK+DECKER |
| The Vollrath Company |
| Hamilton Beach |
| Others |
Pricing and Supply Chain Analysis
Single-source blade forging dependency in Guangdong metalworking clusters determines both tiered pricing spreads and supply chain configuration across North American electric vegetable chopper markets. Tariff exposure on Chinese-manufactured components compresses margins on sub-400-watt residential units while forcing manufacturers toward premium positioning to absorb landed cost volatility.
Pricing Analysis
Aftermarket attachment revenue streams anchor lifetime value capture for electric vegetable chopper manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates Breville's warranty-backed positioning from Hamilton Beach's mass-market penetration and Ninja's direct-to-consumer blade subscription models. Price differentiation hinges on motor wattage certification and ENERGY STAR compliance tier, with California Title 20 mandates adding regulatory cost premiums. Pricing pressure stems from copper and rare-earth magnet commodity volatility, squeezing gross margins most acutely on handheld battery-operated segments. Residential buyers in secondary U.S. markets exhibit highest price sensitivity, while Texas and Ontario restaurant groups absorb premium positioning for pulse-technology durability claims.
Supply Chain Analysis
Neodymium rare-earth feedstock draws primarily from Chinese processing facilities, with secondary sourcing from Vietnamese and Australian mining operations. Stainless steel blade forgings rest on Guangdong metalworking clusters, while torque-calibrated motor assemblies source copper windings from Chilean and Peruvian extraction. Single-source vulnerability concentrates in Guangdong blade forging capacity, exposing North American assemblers to tariff disruption and logistics chokepoints at Long Beach and Vancouver ports. Distribution runs through wholesaler networks for commercial foodservice accounts, direct-to-consumer platforms for replacement attachments, and mass-market retail for residential impulse purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vegetable choppers face sustained substitution pressure from manual prep tools in price-sensitive residential segments, requiring incumbents to defend automation value through labor-cost arithmetic and texture consistency claims.
For Market Incumbents: Insulate core positioning by deepening backward integration into blade forging capacity or securing captive supply agreements with Guangdong metalworkers to neutralize tariff exposure. Prioritize California Title 20 pre-certification for motor architectures to pull forward replacement demand from adjacent states adopting efficiency frameworks. Defend against manual knife substitution by anchoring commercial value propositions in labor-hour reduction metrics visible to restaurant operators.
For New Entrants and Emerging Players: Build out battery-operated handheld penetration in Toronto and Vancouver apartment markets where outlet scarcity and counter space constraints coincide. Target catering operators with mobile power-independent units for off-premise event execution, leveraging lithium-ion supply chain partnerships to undercut established corded-equipment pricing. Establish direct-to-consumer attachment subscription programs to capture blade replacement revenue streams that incumbent retail channels leave exposed.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical integration plays into blade forging and motor component sourcing. Long-term viability over the next decade hinges on regulatory compliance capacity and aftermarket revenue capture architecture. Acquisition targets should demonstrate FDA Food Code material certification pipelines and established direct-to-consumer platform infrastructure. Watch for IRA electrification rebate expansion signals as inflection indicators for residential replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Blade Forging Backward Integration | Captive Guangdong metalworking capacity neutralizes tariff exposure on stainless steel components. |
| California Title 20 Pre-Certification | Early compliance pulls replacement demand from adjacent states adopting efficiency frameworks. |
| Direct-to-Consumer Attachment Platform | Owned digital channels bypass retail margin extraction on replacement blade revenue. |
| Battery-Operated Product Line Expansion | Lithium-ion handheld units penetrate Toronto and Vancouver storage-constrained apartment markets. |
| Commercial NSF Certification Investment | Validated sanitization protocols unlock institutional cafeteria procurement across Canadian healthcare. |
Research Methodology
The analysis maps countertop, multi-functional, handheld, and mini chopper configurations, each validated through commercial kitchen operators, residential renovation contractors, restaurant supply distributors, and appliance retail category managers. Primary interview data triangulates against customs import records, U.S. Department of Energy appliance efficiency filings, Health Canada electrical safety registrations, and FDA Food Code compliance documentation. Bottom-up unit shipment estimates from regional distributor channels converge with top-down spending analysis across residential renovation and commercial foodservice capital expenditure budgets.
Assumptions held fixed include prevailing tariff structures on Chinese-manufactured motors, Title 20 efficiency mandate adoption timelines, and IRA rebate qualification criteria across the projection horizon. The analytical framework models motor wattage tiers, end-user segmentation across restaurants and home kitchens, technology architectures from pulse control to battery operation, and distribution channel mix. CAGRs derive from regression analysis against commercial labor cost inflation trajectories and residential electrification policy intensity. Industry-specific forecast inputs include copper and rare-earth magnet price volatility indices and fast-casual chain capital expenditure disclosure patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated appliance conglomerates or lithium-ion battery specialists would shift outcomes. Specific risk factors include Guangdong supply disruption, California efficiency mandate acceleration, and manual prep tool price erosion in secondary markets. Cross-checking against U.S. Bureau of Labor Statistics foodservice employment cost indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Toast Maker Market
Kitchen Appliances
United Kingdom Kitchen Appliances Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
On-The-Go Pots Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Russia Household Electric Grill Market
Kitchen Appliances
Electric Countertop Griddles Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
Outdoor Kitchen Appliances Market