
 Luxury Car Rental Market | 2026-2036
Luxury Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Car Rental Market Intelligence
Corporate clientele is rotating toward experiential travel packages that bundle luxury vehicles with hospitality services, displacing traditional airport-centric rentals. Enterprise Holdings Inc. anchors North American corporate accounts through centralized fleet management systems. Sixt SE differentiates European operations with dedicated sports car divisions in Munich and Stuttgart. Turo Inc. leverages peer-to-peer infrastructure to access dispersed owner inventories without capital-heavy fleet ownership.
Luxury car rental denotes short-term access to premium vehicles priced above mass-market tiers, typically featuring leather interiors, advanced driver-assistance systems, and power outputs exceeding 300 horsepower for executive transport or leisure use. Sedan and SUV categories dominate fleet composition due to balanced passenger capacity and trunk volume for airport transfers. Business travelers generate the highest per-rental margins, while monthly and long-term lease structures capture extended-stay executives seeking predictable mobility costs. Online platforms and mobile apps now process the majority of bookings, though concierge services retain pricing power among celebrity and ultra-high-net-worth segments.
The EU Green Deal's fleet electrification timelines and the U.S. EPA's tailpipe emission standards reshape vehicle procurement decisions across major operators. FAA regulations governing airport ground transportation access determine rental counter placement and fleet turnover rates at hub locations. Stakeholders must monitor battery-electric vehicle residual values and charging infrastructure density before committing capital to next-generation luxury fleets.
Market Dynamics
Fleet electrification mandates from the EU Green Deal and California Air Resources Board are forcing operators to restructure procurement timelines and residual value models around battery-electric luxury vehicles.
Growth Catalysts
- EU Green Deal fleet mandates:Binding zero-emission targets for commercial fleets by 2035 accelerate capital redeployment into electric luxury inventories.
- Experiential hospitality bundling:Corporate event planners now package vehicles with concierge services, extending rental duration and margin capture.
- Dubai's tourism infrastructure density:Per-capita luxury rental volumes exceed Western European benchmarks due to low fuel costs and concentrated high-net-worth visitor flows.
Market Restraints
- Battery-electric residual value uncertainty:Depreciation curves for premium EVs remain unproven, constraining fleet financing options.
- Charging infrastructure gaps:Inadequate fast-charging density outside urban cores limits one-way rental flexibility and airport hub operations.
- FAA ground transportation access rules:Regulatory constraints on airport counter placement restrict fleet turnover velocity at high-volume locations.
Strategic Opportunities
- Peer-to-peer inventory aggregation:Asset-light platforms access dispersed owner vehicles without capital-intensive fleet ownership.
- Monthly executive mobility subscriptions:Extended-stay corporate users seek predictable cost structures replacing traditional lease arrangements.
- California ZEV incentive stacking:State rebates combined with federal IRA credits reduce net acquisition costs for battery-electric luxury models.
Industry Challenges
- EV technician certification pipelines:Maintenance networks lack sufficient high-voltage systems specialists for premium battery-electric fleets.
- Legacy reservation system integration:Real-time charge-state visibility requires middleware development across fragmented software stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Car Rental Market |
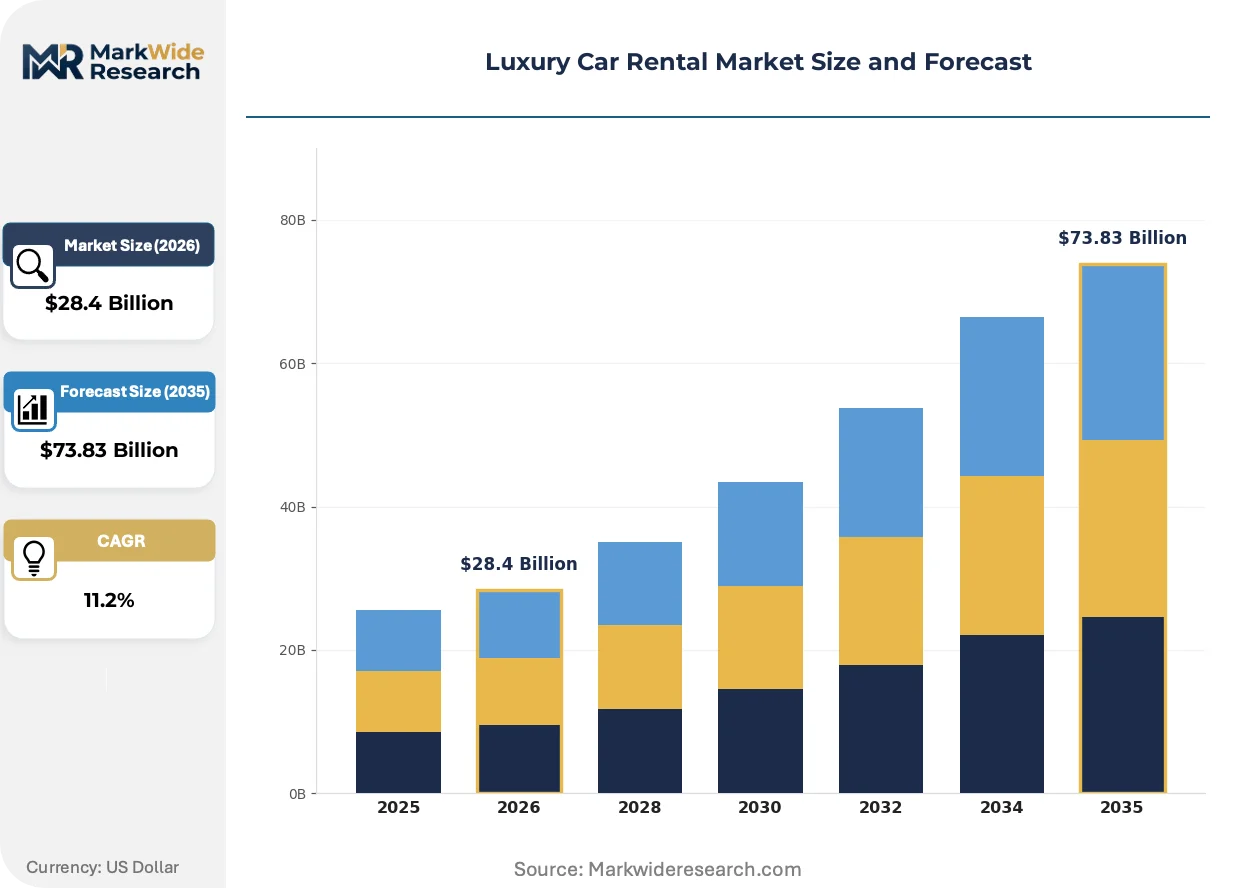
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $73.83 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Convertible, Coupe, Sports Car Rental Duration: Hourly, Daily, Weekly, Monthly, Long-Term Lease Customer Type: Business Travelers, Vacationers, Celebrities, Event Attendees, Corporate Clients Booking Channel: Online Platforms, Travel Agencies, Direct Reservations, Mobile Apps, Concierge Services |
| Companies Covered | The Hertz Corporation, Turo Inc., Enterprise Holdings Inc., Zoomcar Ltd., Getaround Inc., Sixt SE, Europcar Mobility Group, Movida, Avis Budget Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Car Rental Market Strategic Shifts & Innovations
Digital booking infrastructure and electrification requirements are compressing traditional operational models while opening asset-light pathways for new entrants.
Telematics-enabled predictive maintenance is bifurcating fleet management between premium operators with real-time diagnostics and legacy providers dependent on scheduled service intervals. High-net-worth leisure travelers increasingly select vehicles based on connected service reliability. This technology compression favors centralized fleet operators with proprietary data infrastructure over decentralized owner networks.
California Air Resources Board's Advanced Clean Cars II regulation mandates 100% zero-emission vehicle sales by 2035, forcing rental operators to accelerate procurement of battery-electric luxury models. Fleet managers now prioritize residual value insurance products to hedge against unproven secondary markets for premium EVs. Sports car divisions in Stuttgart and Munich face compressed planning horizons for internal combustion inventory.
Subscription-based mobility contracts are displacing traditional daily-rate structures among extended-stay executives seeking cost predictability. Corporate travel managers now consolidate vendor relationships around bundled hospitality-vehicle packages rather than airport-centric transactions. This procurement consolidation concentrates in the United Arab Emirates and California where extended-stay executive populations cluster.
Luxury Car Rental Market Segmentation
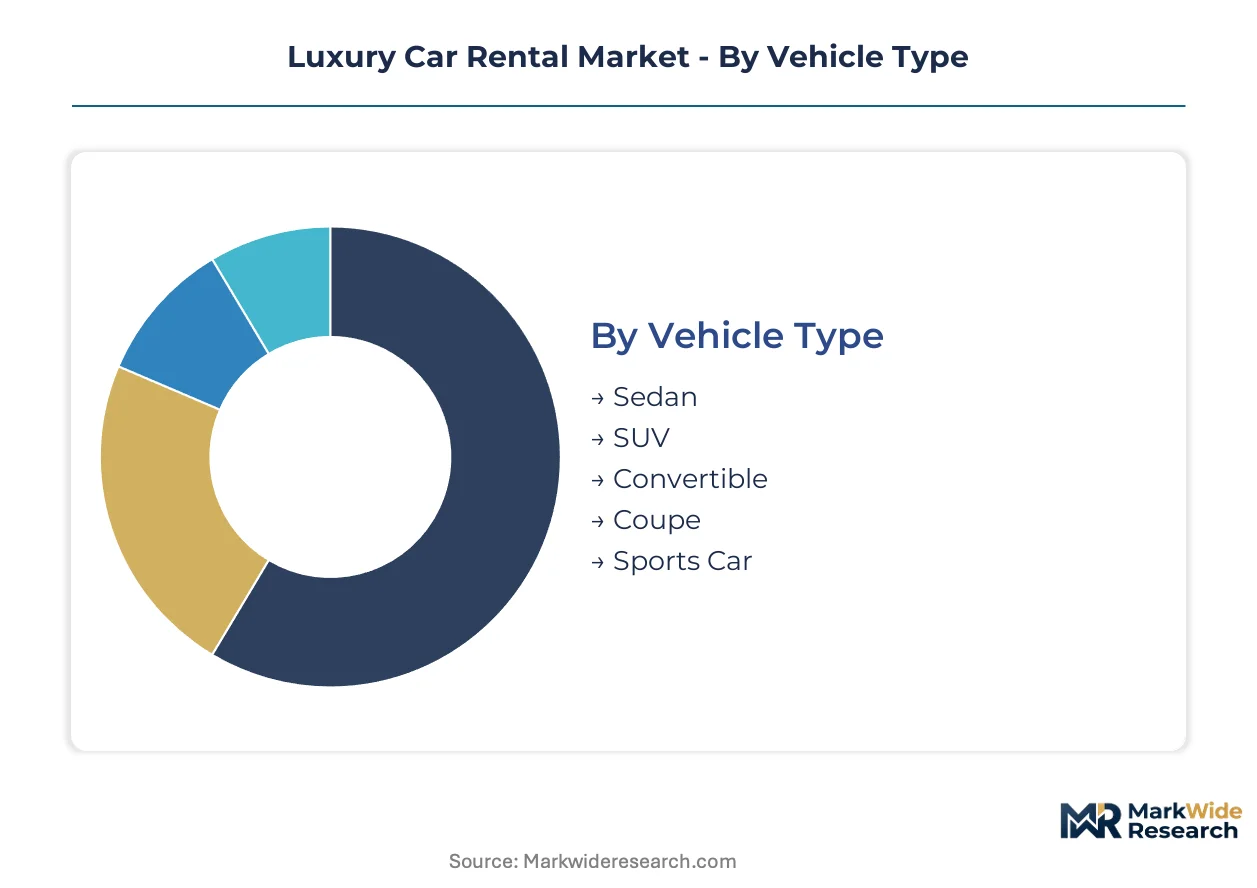
Fleet procurement strategies diverge sharply across vehicle configurations and customer profiles. Rental operators align depreciation schedules and insurance products with segment-specific utilization patterns and residual risk profiles.
Vehicle Type:
EU Green Deal zero-emission mandates and California Air Resources Board procurement timelines force differential electrification roadmaps across body styles.
- Sedan:Three-box configurations dominate corporate airport transfers with balanced rear-seat legroom and trunk capacity for executive luggage. Fleet managers in Dubai and Frankfurt prioritize electrified sedan variants for EU compliance and Middle Eastern fuel cost arbitrage.
- SUV:Elevated seating positions and all-wheel-drive architectures capture leisure demand in mountain and desert tourism corridors. Battery-electric SUV residual values remain unproven, constraining financing structures outside California's ZEV incentive zones.
- Convertible:Soft-top and retractable hardtop variants serve seasonal coastal markets with compressed rental windows.
- Coupe:Fixed-roof two-door configurations target weekend leisure segments with limited rear-seat utility.
- Sports Car:High-output internal combustion and performance EV platforms concentrate in Stuttgart and Munich specialty divisions.
Sedan handles the majority of throughput; Sports Car is climbing the fastest on share among experiential hospitality bundlers.
Rental Duration:
Revenue recognition and fleet utilization models shift dramatically across temporal structures, with subscription economics displacing transactional daily rates.
- Hourly:Micro-rental formats serve urban center shopping and dining circuits with severe vehicle turnover constraints.
- Daily:Standard 24-hour blocks remain the volume baseline for airport-centric transactions and insurance product attachment.
- Weekly:Seven-day structures capture extended leisure travel with modest per-day rate discounts versus daily stacking.
- Monthly:Thirty-day minimums with predictable cost structures displace traditional corporate leases among extended-stay executives in UAE and California technology corridors.
- Long-Term Lease:Multi-quarter arrangements with maintenance bundling serve rotational expatriate populations and project-based consulting engagements.
Daily retains volume dominance; Monthly is expanding most quickly as procurement managers consolidate vendor relationships.
Customer Type:
Margin capture and service intensity requirements stratify sharply across traveler motivations and booking authority structures.
- Business Travelers:Expense-account-funded airport transfers generate premium per-rental economics with predictable weekday demand patterns. Corporate travel policies increasingly mandate sustainability reporting, pushing procurement toward battery-electric fleet segments.
- Vacationers:Leisure-driven demand concentrates in seasonal peaks with higher price elasticity and ancillary service attachment rates.
- Celebrities:Privacy-screened vehicles and security-coordinated logistics command concierge-level service premiums.
- Event Attendees:Wedding, gala, and motorsport circuit demand clusters around specific calendar windows with surge pricing potential.
- Corporate Clients:Centralized procurement of vehicle-hospitality bundles displaces fragmented departmental booking across enterprise accounts.
Business Travelers anchor revenue stability; Corporate Clients are gaining share fastest through consolidated vendor contracts.
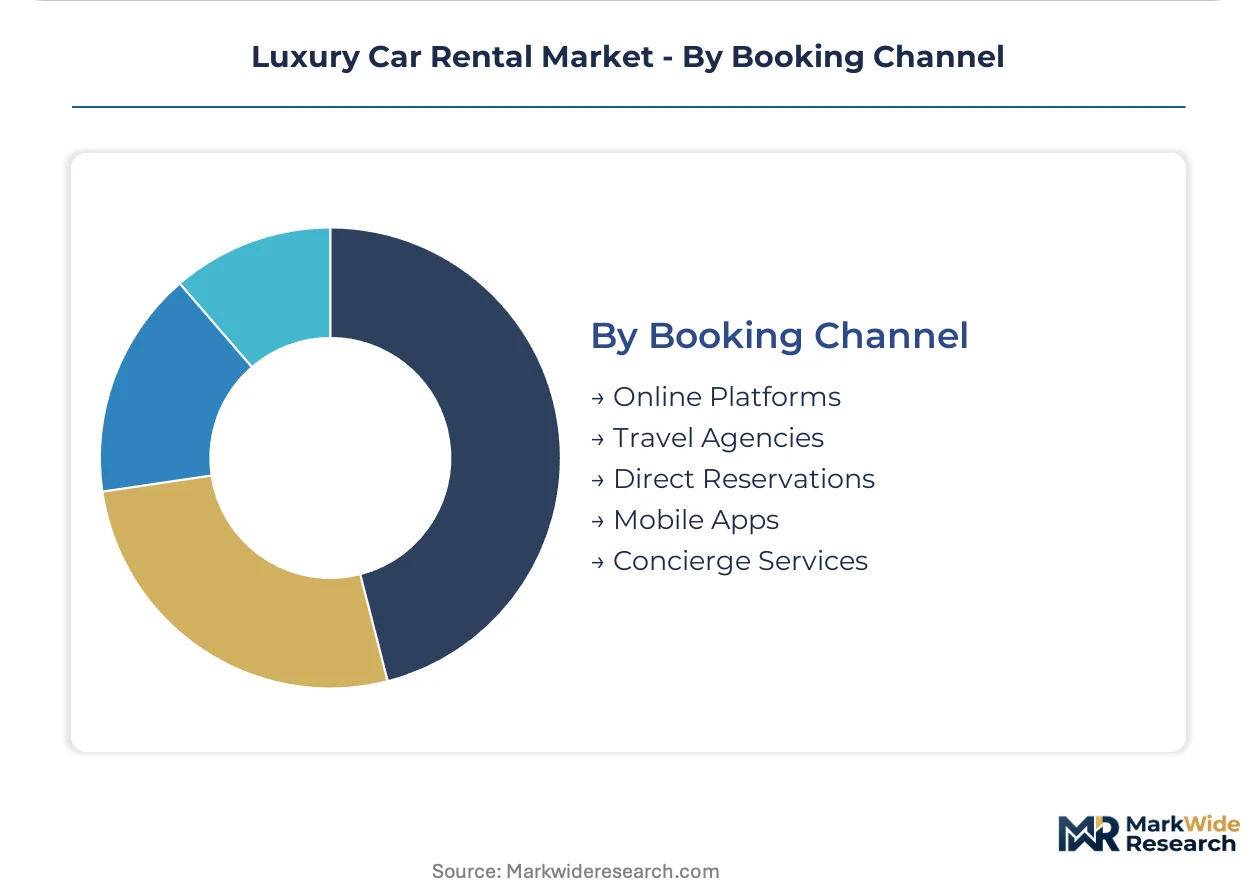
Booking Channel:
Customer acquisition economics and fleet visibility requirements determine platform investment priorities across direct and intermediated pathways.
- Online Platforms:Aggregator websites capture price-sensitive comparison shoppers with standardized vehicle class presentations and instant confirmation algorithms.
- Travel Agencies:Traditional intermediaries retain influence in corporate travel management and complex multi-leg itineraries.
- Direct Reservations:Operator-owned websites and call centers preserve margin through avoided intermediary commissions.
- Mobile Apps:Smartphone-native booking with GPS-enabled vehicle location and digital key integration serves on-demand urban demand.
- Concierge Services:White-glove human intermediaries retain pricing power for ultra-high-net-worth segments requiring discretion and customization.
Online Platforms process the majority of transaction volume; Mobile Apps show the steepest expansion trajectory among younger demographic cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate event planners and high-net-worth leisure travelers concentrate in specific metropolitan clusters where tourism infrastructure and regulatory incentives align. Fleet operators calibrate electrification roadmaps to local zero-emission mandates and charging density.
United States
Extended-stay executives in California technology corridors drive monthly subscription adoption. The EPA's tailpipe emission standards and California Air Resources Board's Advanced Clean Cars II regulation accelerate battery-electric procurement timelines. Los Angeles and San Francisco anchor West Coast fleet deployment with concentrated charging infrastructure.
Germany
Stuttgart and Munich specialty divisions serve experiential hospitality bundlers seeking performance vehicle access. The EU Green Deal's binding zero-emission fleet targets by 2035 force restructuring of residual value models. Bavaria's automotive engineering cluster supports high-voltage technician certification pipelines for premium EV maintenance.
United Arab Emirates
Dubai's tourism infrastructure sustains per-capita rental volumes above Western European benchmarks through low fuel costs and concentrated high-net-worth visitor flows. MOHAP oversees commercial vehicle licensing frameworks. The emirate's hospitality-vehicle package consolidation attracts corporate event procurement managers.
United Kingdom
London's corporate travel managers consolidate vendor relationships around bundled mobility services displacing airport-centric transactions. The country's national environmental regulator enforces commercial fleet emission reporting requirements. The Southeast England corridor connects executive transport demand with premium electrified sedan availability.
France
Île-de-France hosts centralized procurement negotiations for multinational corporate accounts seeking sustainability-aligned vehicle policies. The EU Green Deal mandates reshape Parisian operator fleet composition toward zero-emission luxury inventories. The region's concierge service density retains pricing power among ultra-high-net-worth segments.
Luxury Car Rental Market Key Industry Players
Player mix skews toward diversified mobility conglomerates with centralized fleet management capabilities and asset-light peer-to-peer platforms accessing dispersed owner inventories. Strategic archetypes include legacy airport-centric operators restructuring around subscription economics, technology-enabled aggregators bypassing capital-heavy ownership, and European specialty divisions concentrating sports car inventory in manufacturing-adjacent clusters. Competitive moves center on fleet electrification partnerships with OEMs and middleware development for real-time charge-state visibility.
Within the diversified conglomerate tier, Enterprise Holdings Inc. and Avis Budget Group Inc. occupy positions representing traditional fleet ownership scaled across corporate account management. Sixt SE anchors European specialty operations with dedicated performance vehicle divisions. Turo Inc. exemplifies the asset-light archetype leveraging peer-to-peer infrastructure without direct vehicle ownership.
| Leading Market Players |
|---|
| The Hertz Corporation |
| Turo Inc. |
| Enterprise Holdings Inc. |
| Zoomcar Ltd. |
| Getaround Inc. |
| Sixt SE |
| Europcar Mobility Group |
| Movida |
| Avis Budget Group Inc. |
| Others |
Cost & Logistics Intelligence
Fleet utilization rates above 75% at Dubai and Los Angeles hubs compress per-unit fixed costs and establish price floors that smaller operators cannot match without capital access. This scale concentration allows Enterprise Holdings and Sixt SE to absorb battery-electric residual value uncertainty through diversified depreciation schedules while regional independents face margin compression from unproven secondary markets.
Pricing Analysis
Cost-plus contracts with OEM procurement teams index fleet acquisition pricing to lithium carbonate and semiconductor spot markets, creating quarterly adjustment clauses that transfer commodity volatility to rental operators. Three-tier pricing structure across premium, standard, and economy levels segments airport transfers from experiential hospitality bundles and monthly executive subscriptions. Price differentiation hinges on concierge service attachment and charging infrastructure proximity. Cost compression in battery-electric tiers is intensifying because residual value insurance premiums now exceed internal combustion coverage by substantial margins. Vacationers exhibit highest price elasticity, while corporate procurement managers with sustainability mandates show lowest sensitivity.
Supply Chain Analysis
Inventory lead times for premium battery-electric vehicles from Germany, South Korea, and the United States now stretch 8-14 months versus 3-4 months for internal combustion equivalents, constraining fleet refresh velocity. Raw material dependencies center on lithium hydroxide, nickel sulfate, and automotive-grade semiconductors. Single-source vulnerability concentrates in South Korean battery cell supply and German luxury OEM allocation protocols. Distribution runs through airport hub counters, urban flagship locations, and peer-to-peer platform aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
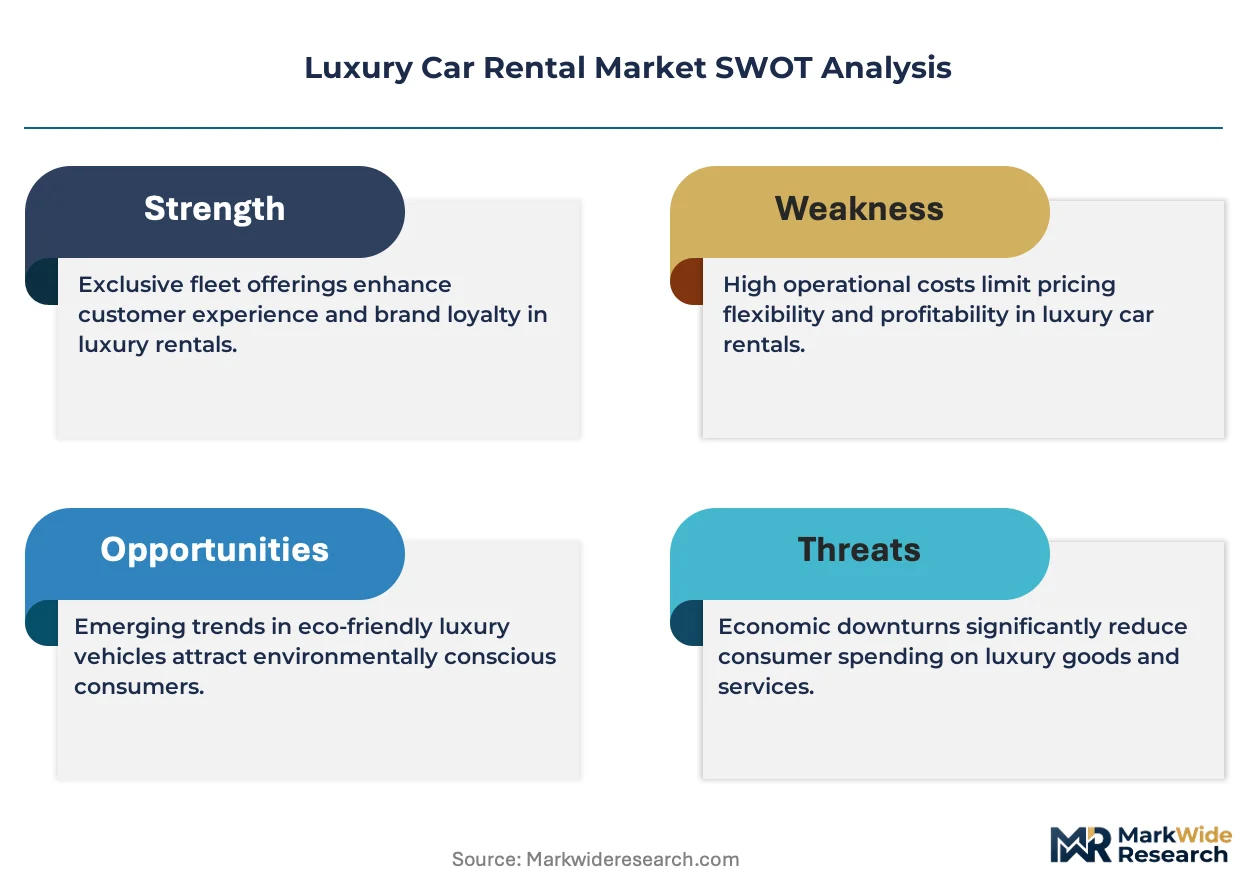
This market constitutes a defensive moat anchored in regulatory entrenchment: EU Green Deal and California Air Resources Board mandates create compliance barriers that favor scaled operators with electrification capital access over fragmented independents.
For Market Incumbents: Fortify residual value hedging through OEM partnership structures and captive insurance subsidiaries. Expand Munich and Stuttgart technician certification pipelines to address EV maintenance scarcity. Accelerate middleware development for real-time charge-state visibility across legacy reservation systems to neutralize Turo's platform-native advantage.
For New Entrants and Emerging Players: Anchor in monthly executive subscription white space across California technology corridors and UAE extended-stay clusters where procurement consolidation displaces fragmented departmental booking. Target asset-light peer-to-peer aggregation in secondary European cities with charging infrastructure gaps that deter fleet ownership. Pursue hospitality-vehicle bundling partnerships with luxury hotel groups as primary go-to-market channel.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with corporate subscription contracts and proprietary charging infrastructure networks. Five-to-ten-year viability favors scaled platforms with OEM electrification partnerships and centralized fleet management systems. Monitor battery-electric residual value insurance premium spreads as inflection indicator for capital redeployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | OEM allocation agreements with Mercedes-Benz and BMW secure battery-electric vehicle supply priority. |
| Charging Infrastructure Integration | Hub-based fast-charging deployment at Los Angeles and Dubai airports enables one-way rental flexibility. |
| Subscription Platform Launch | Monthly mobility contracts with predictable cost structures displace traditional corporate lease arrangements. |
| Residual Value Insurance Product | Hedging instruments against unproven battery-electric secondary markets reduce fleet financing constraints. |
| Concierge Service Expansion | White-glove human intermediaries retain pricing power among ultra-high-net-worth celebrity segments. |
Research Approach
Initial hypotheses were tested against primary input from fleet procurement directors, corporate travel managers, airport ground transportation regulators, and luxury hospitality concierges and refined through secondary validation against SEC 10-K filings, EU fleet emission compliance databases, vehicle registration statistics, and hospitality industry procurement surveys. Bottom-up triangulation across operator fleet composition data and top-down reconciliation against tourism arrival statistics anchored volume estimates.
Variance decomposition across vehicle type, rental duration, customer segment, and booking channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate aggregation weighted by base-year revenue contribution. Forecast inputs incorporated EU Green Deal compliance timelines, California ZEV incentive stacking mechanics, and battery-electric residual value trajectory assumptions.
Material uncertainties — regulatory acceleration or delay in fleet electrification mandates, lithium price volatility, and charging infrastructure buildout pace — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Car Vending Machine Market
Automotive Services
Europe Car Wash Market
Automotive Services
Global Cars-As-A-Service (CaaS) Market
Automotive Services
France Car Rental Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Cab Services Market
Automotive Services
Automotive Register Market
Automotive Services
North America MRO Distribution Market
Automotive Services
Qatar Car Rental Market
Automotive Services
Tow Truck Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
GCC Car Rental Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Driver's License Market