
 Closed Platform Screen Doors Market | 2026-2036
Closed Platform Screen Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Closed Platform Screen Doors Market Analytics
REACH compliance is rebalancing material sourcing costs for European suppliers of sealed door assemblies. Nabtesco Corporation leverages its precision motion-control heritage to dominate high-cycle platform door mechanisms in Japanese and Southeast Asian metros. Nanjing Kangni Mechanical & Electrical Co., Ltd. anchors its position through captive manufacturing of door drive units and control systems for China's state railway procurement. Wabtec Corporation (Faiveley Transport) extends its installed base advantage across legacy European networks where retrofit timelines stretch over multiple capital cycles.
Closed platform screen doors constitute sealed barrier systems installed at transit platform edges, typically comprising tempered glass panels mounted on aluminum frames with synchronized electromechanical drive units achieving opening cycles under three seconds. These systems eliminate passenger fall risk, reduce HVAC energy losses in climate-controlled stations, and enable automated train operation by ensuring platform-train gap safety. Automatic product types command the dominant revenue share due to integration demands with signaling and train control networks, while glass materials outpace metal alternatives where aesthetic and visibility specifications drive procurement. Railway stations and metro end-use segments concentrate the bulk of replacement demand as urban transit agencies upgrade aging first-generation installations.
China's NMPA and SAMR jointly enforce rail transit equipment certification under GB standards, while the EU's CE marking and MDR frameworks govern door-system safety components sold into European infrastructure projects. Japan's METI coordinates JIS standards with railway operators to ensure interoperability across heterogeneous platform configurations. Stakeholders must monitor divergence between national certification regimes as modular retrofit designs seek cross-border standardization.
Market Dynamics
Metro network expansion across Chinese tier-one cities is compressing procurement cycles and forcing suppliers to synchronize door-system deliveries with compressed construction timelines that now overlap multiple station phases simultaneously.
Growth Catalysts
- GB Standard Tightening:China's SAMR and NMPA enforcement of elevated rail transit equipment certification thresholds is mandating platform screen door replacements at legacy underground stations.
- Automated Train Operation:Integration with signaling networks is integrating platform-train gap safety systems as non-negotiable infrastructure for unmanned metro lines.
- HVAC Energy Recovery:Climate-controlled station operators are specifying sealed barrier systems to reduce cooling losses at underground platforms.
Market Restraints
- Aluminum Frame Input Volatility:Primary aluminum price swings transmitted through extrusion suppliers are compressing margin structures for door assembly manufacturers.
- Drive Unit Supply Concentration:Precision electromechanical actuator production clusters in Japan and Germany create single-source vulnerability for high-cycle mechanisms.
- Retrofit Site Access Constraints:Operating station platforms limit installation windows to overnight maintenance periods, extending project durations.
Strategic Opportunities
- India Metro Buildout:Underpenetrated urban rail networks in Mumbai, Bangalore, and Hyderabad are specifying platform screen doors for new-build stations without retrofit constraints.
- Glass-Metal Hybrid Materials:Tempered glass panel systems with aluminum subframes are capturing procurement preference where visibility and aesthetic specifications dominate.
- Modular Retrofit Designs:Standardized door modules seeking cross-border certification equivalence are reducing engineering duplication across national markets.
Industry Challenges
- Certification Timeline Compression:GB standards and CE marking divergence is forcing suppliers to maintain parallel testing protocols for multi-jurisdiction projects.
- Legacy Signaling Integration:First-generation platform door installations require custom interface engineering with heterogeneous train control networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Closed Platform Screen Doors Market |
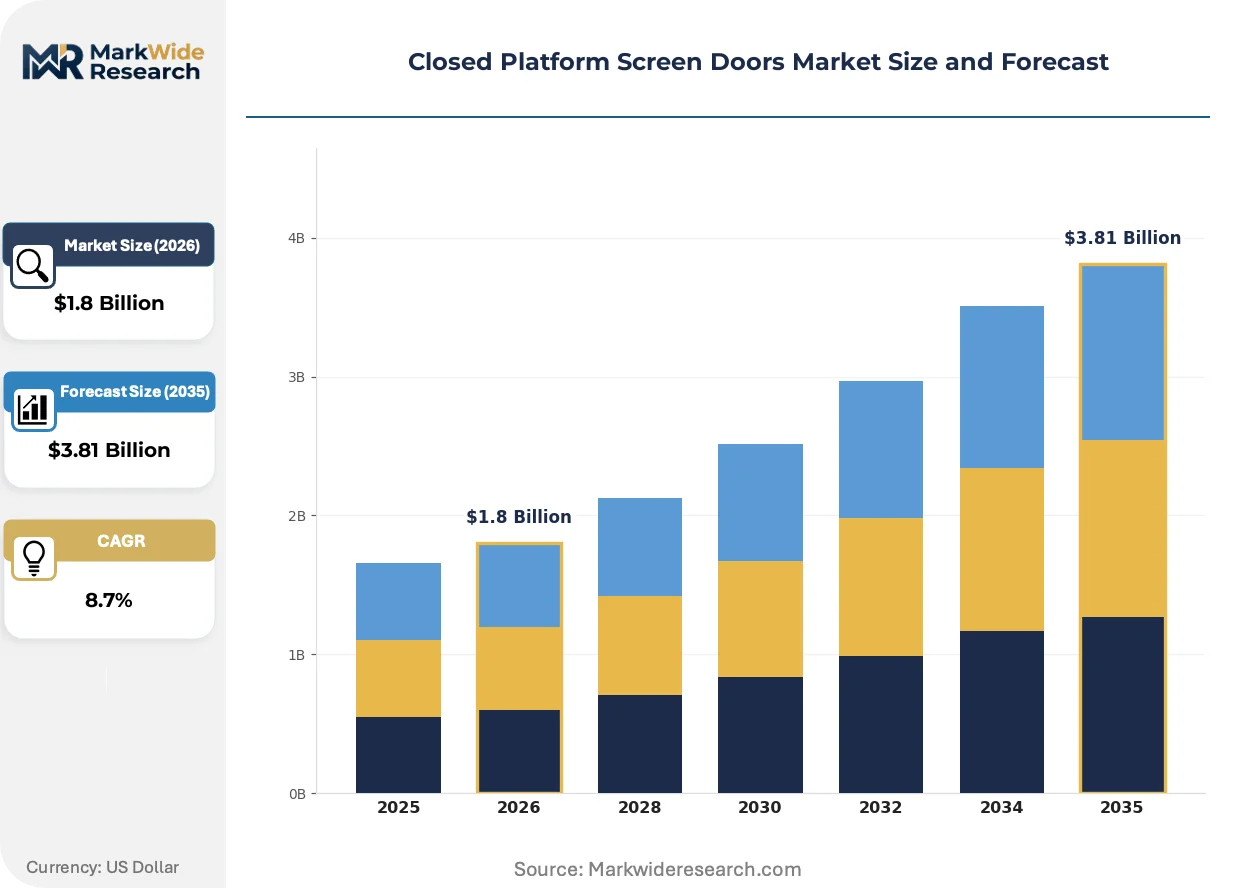
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Semi-Automatic, Modular Material: Metal, Glass, Acrylic, Polycarbonate Installation Type: Fixed, Movable, Retractable, Custom Fit End User: Railway Stations, Airports, Metros, Bus Terminals |
| Companies Covered | Nabtesco Corporation, Nanjing Kangni Mechanical & Electrical Co., Ltd., Wabtec Corporation (Faiveley Transport), Fangda Group Co., Ltd., Westinghouse Air Brake Technologies, Panasonic Corporation, Horton Automatics, KTK Group Co., Ltd., Stanley Access Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Closed Platform Screen Doors Market Evolving Landscape
Platform screen door technology is converging with broader rail automation architectures, compressing the boundary between mechanical barrier systems and digital train control networks. Three developments are reshaping competitive positioning.
Sensor fusion technology is integrating LiDAR and machine vision into door control units to detect platform-train gap obstructions in real time. Japanese and Southeast Asian metro operators are specifying these systems for high-frequency lines with sub-90-second headways. The technology is integrating safety-critical decision loops directly into door drive controllers, eliminating separate platform monitoring subsystems.
REACH compliance is rebalancing material sourcing for European sealed door assembly suppliers. ECHA restrictions on specific polymer formulations used in door seals and gaskets are forcing reformulation of weatherstripping compounds. German and French rail infrastructure projects are now specifying full material disclosure documentation alongside mechanical performance certificates.
After-sales service unbundling is disrupting traditional procurement models where door system suppliers bundled decade-long maintenance contracts. Chinese state railway procurement is now separating capital equipment purchase from operations and maintenance agreements, enabling third-party service providers to compete for retrofit and spare parts business. This pattern is most visible in Beijing and Shanghai metro network extensions where specialized maintenance contractors are displacing original equipment vendor service arms.
Closed Platform Screen Doors Market Segmentation
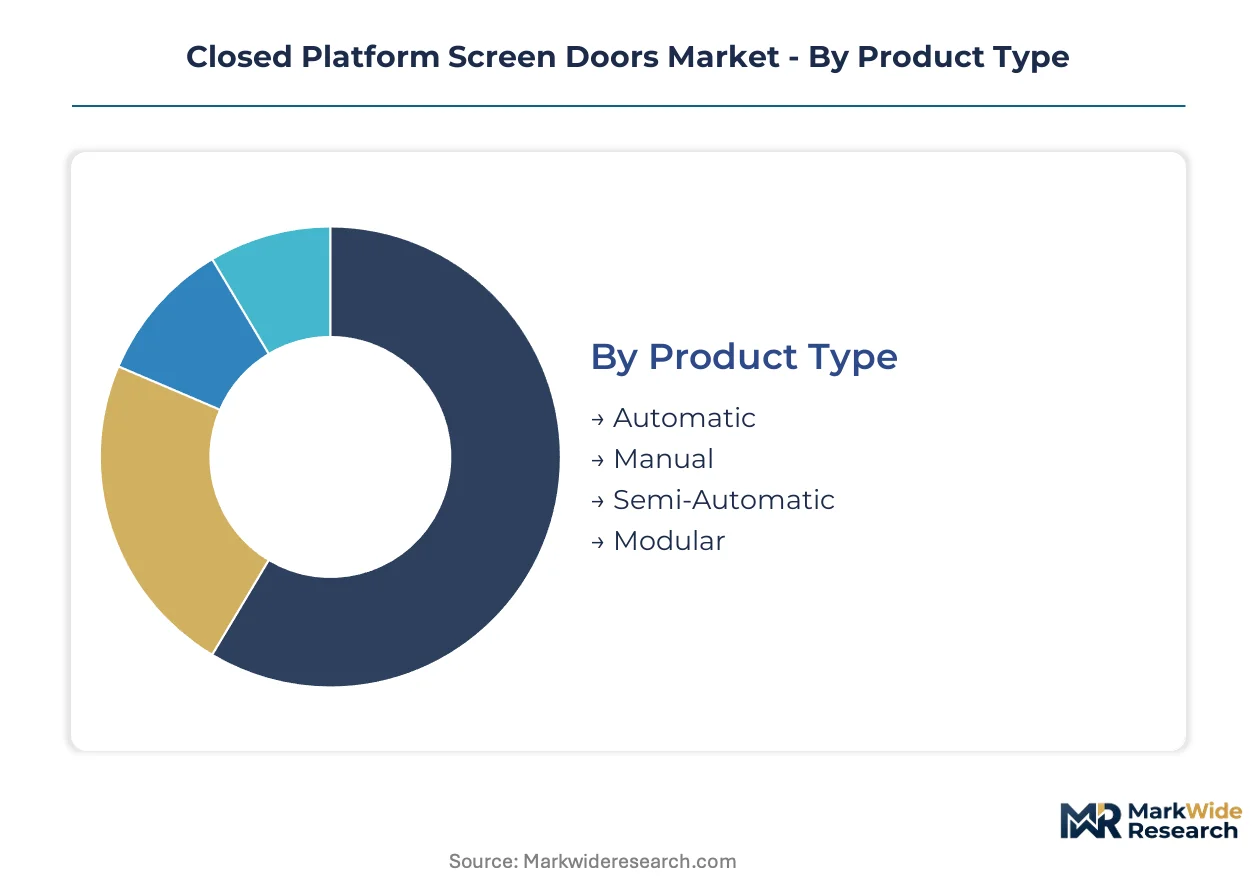
Segmentation in the closed platform screen doors market reveals how procurement specifications diverge across climate conditions, automation requirements, and retrofit constraints. Understanding these divisions exposes where suppliers must engineer flexibility into standardized platforms versus where captive designs dominate.
Product Type:
Customization demands peak where signaling integration complexity meets operational uptime requirements, forcing suppliers to balance modular architectures against integrated electromechanical systems.
- Automatic:Fully electromechanical systems synchronize with train control networks through programmable logic controllers, achieving sub-three-second open-close cycles. Demand concentrates at Chinese tier-one metro expansions where SAMR-mandated platform-train gap safety requirements intersect with automated train operation rollouts. These installations require continuous certification alignment with evolving GB standards.
- Manual:Operator-actuated barrier systems with mechanical release mechanisms serve legacy stations awaiting full automation retrofits. Procurement persists at Indian railway stations where capital constraints delay electromechanical upgrades, though operators face pressure from CDSCO-adjacent safety audits pushing toward semi-automatic transitions.
- Semi-Automatic:Hybrid configurations blending manual override with motorized assistance.
- Modular:Standardized door units designed for rapid field assembly and cross-border certification portability.
Leading the category by volume: Automatic. Growing fastest: Modular.
Material:
Cost tier stratification separates premium specifications demanding optical clarity from utilitarian installations prioritizing impact resistance and thermal stability.
- Glass:Tempered safety glass panels laminated with polyvinyl butyral interlayers deliver optical transmission exceeding 85% for platform visibility requirements. Chinese metro procurements in Beijing and Shanghai specify these systems where passenger surveillance and aesthetic integration with station architecture drive selection, despite weight penalties versus polymer alternatives.
- Metal:Aluminum extrusion frames with powder-coated steel infill panels dominate climate-extreme installations. Demand clusters at Middle Eastern airport terminals where MOHAP-adjacent fire safety regulations mandate non-combustible barrier materials, and where sand abrasion resistance outweighs visibility considerations.
- Acrylic:Cast polymethyl methacrylate panels offering intermediate weight and impact resistance.
- Polycarbonate:Extruded thermoplastic sheets with superior impact strength for high-vandalism environments.
Dominating procurement value: Glass. Expanding most quickly: Polycarbonate.
Installation Type:
Volume concentration tracks directly against retrofit site access constraints, with fixed systems capturing new-build efficiency while movable configurations command premium engineering margins.
- Fixed:Permanently anchored frame assemblies welded to platform structural elements. These systems capture procurement at Indian greenfield metro stations in Mumbai and Hyderabad where construction timelines permit integrated civil works, eliminating the mechanical complexity of later retrofit adaptation.
- Movable:Rail-mounted or pivoting barrier systems enabling platform reconfiguration. Japanese operators under METI-coordinated JIS standards specify these for multi-purpose platform edges accommodating both passenger services and maintenance vehicle access.
- Retractable:Folding or stacking panel systems for space-constrained platform geometries.
- Custom Fit:Site-engineered solutions for non-standard platform curves or heritage structure constraints.
Highest shipment volumes: Fixed. Steepest expansion trajectory: Custom Fit.
End User:
Customer type segmentation exposes diverging procurement authority structures, with state railway monopsonies contrasting against fragmented airport authority purchasing.
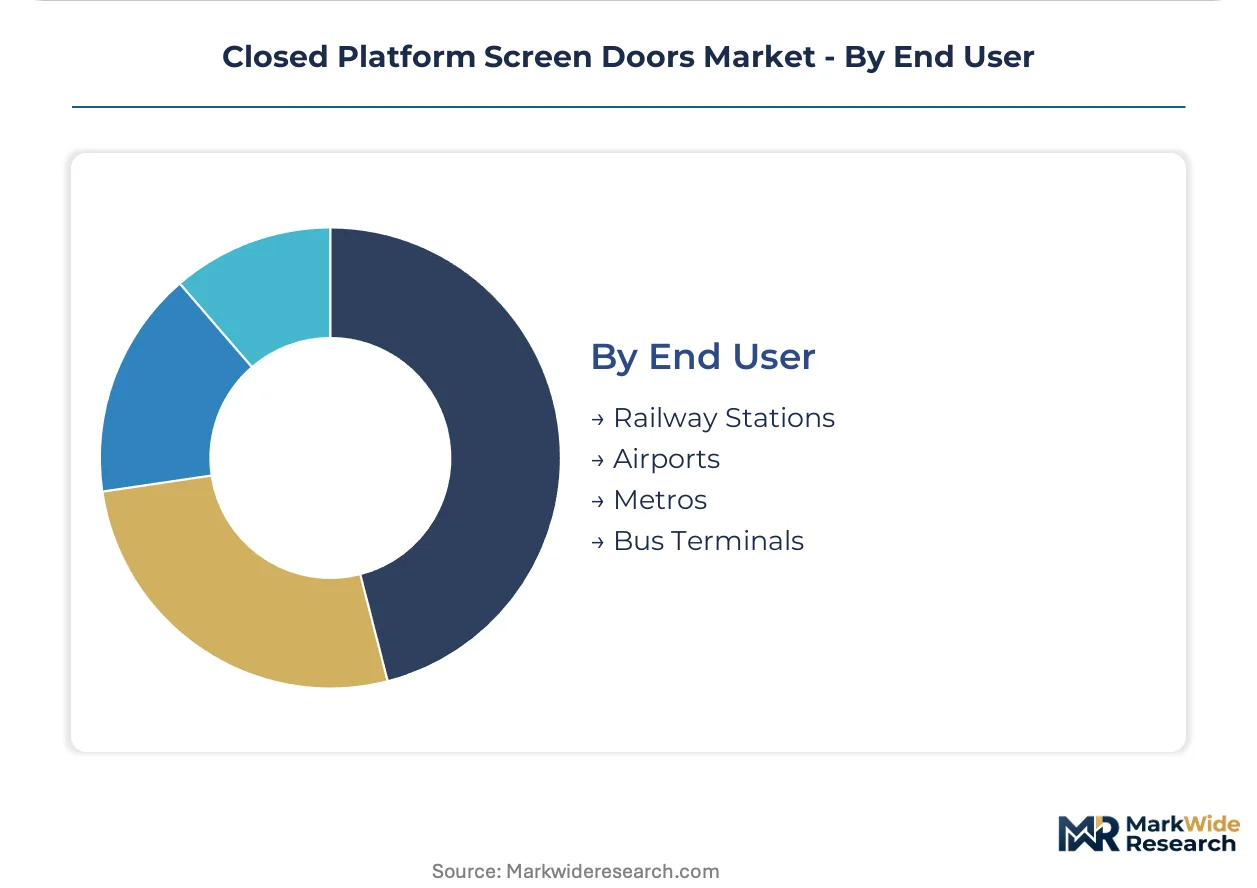
- Metros:Underground and elevated urban rail networks with high-frequency operations. China's state railway procurement concentrates demand here, with Beijing and Shanghai network extensions specifying platform screen doors as mandatory for climate-controlled stations under tightening GB energy efficiency mandates.
- Railway Stations:Intercity and regional rail terminals with lower frequency but higher passenger volume variance. Indian Railway specifications under BIS oversight are gradually mandating platform edge protection at major terminuses, though deployment lags metro adoption by multiple capital cycles.
- Airports:Automated people mover systems and terminal shuttle platforms.
- Bus Terminals:Bus rapid transit platforms with guided lane systems.
Commanding procurement spend: Metros. Gaining share fastest: Railway Stations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates over half of platform screen door procurement volume, driven by subway network extensions across Beijing, Shanghai, and Shenzhen. Metro operators in Japan and India are accelerating safety retrofits, while European networks face extended replacement cycles due to heterogeneous legacy infrastructure.
China
Beijing and Shanghai metro authorities are mandating platform screen door installations at all climate-controlled underground stations under tightening GB energy efficiency standards. SAMR and NMPA jointly enforce rail transit equipment certification thresholds that accelerate replacement of first-generation barrier systems. Door drive unit manufacturers cluster in Jiangsu and Guangdong provinces, supplying state railway procurement with synchronized electromechanical systems.
Japan
Tokyo Metro and Osaka Municipal Subway are specifying sensor-fusion door controllers for high-frequency lines with sub-90-second headways. METI coordinates JIS standards with railway operators to ensure interoperability across heterogeneous platform configurations. Precision motion-control specialists concentrate in the Kanto industrial corridor, dominating high-cycle mechanism production for domestic and Southeast Asian export markets.
India
Mumbai, Bangalore, and Hyderabad metro corporations are specifying platform screen doors for new-build stations without retrofit constraints. BIS oversight is gradually mandating platform edge protection at major railway terminuses, though deployment lags metro adoption. Domestic fabricators in Maharashtra and Karnataka are scaling assembly capacity to meet compressed construction timelines.
Germany
Berlin and Munich transport authorities are managing multi-decade retrofit programs across legacy U-Bahn networks with limited overnight installation windows. ECHA REACH restrictions on polymer formulations used in door seals are forcing reformulation of weatherstripping compounds for European sealed door assemblies. Industrial clusters in Bavaria and North Rhine-Westphalia supply precision aluminum extrusions and control systems.
United States
New York MTA and Washington Metro are evaluating platform barrier pilots amid ADA compliance pressures and passenger safety litigation. No federal mandate exists, leaving procurement decisions fragmented across municipal transit authorities. Domestic system integrators in the Northeast and California are partnering with Asian mechanism suppliers to bridge technology gaps.
Closed Platform Screen Doors Market Competitive Landscape
Japanese producers anchor one tier of precision electromechanical supply; Chinese fabricators hold volume manufacturing scale. The vendor base splits between consolidated motion-control specialists and fragmented regional door assembly contractors. Three archetypes dominate: integrated rail subsystem suppliers, captive manufacturers of drive units and control systems, and modular retrofit specialists. Geographic expansion and technology licensing represent the dominant competitive vectors as suppliers seek cross-border certification equivalence.
Within the integrated subsystem tier, Nabtesco Corporation and Wabtec Corporation exemplify precision heritage positioning. Among Chinese captive manufacturers, Nanjing Kangni Mechanical & Electrical Co., Ltd. occupies a position representing state railway procurement alignment. These three entities anchor distinct competitive vectors—Japanese precision export, North American installed base extension, and domestic Chinese vertical supply—without overlapping strategic territory.
| Leading Market Players |
|---|
| Nabtesco Corporation |
| Nanjing Kangni Mechanical & Electrical Co., Ltd. |
| Wabtec Corporation (Faiveley Transport) |
| Fangda Group Co., Ltd. |
| Westinghouse Air Brake Technologies |
| Panasonic Corporation |
| Horton Automatics |
| KTK Group Co., Ltd. |
| Stanley Access Technologies LLC |
| Others |
Value Network & Pricing Analysis
Compressed construction timelines at Chinese tier-one metro expansions are forcing door-system suppliers to absorb expedited logistics costs and maintain buffer inventory, which compresses margin structures and shifts pricing power toward state railway procurement authorities with consolidated purchasing volumes.
Pricing Analysis
Volume procurement by Chinese state railway authorities captures standard-tier equipment at compressed margins, while premium-tier sensor-fusion systems for Japanese high-frequency metros sustain elevated pricing through precision motion-control specialization. Price differentiation rests on certification grade alignment with GB standards versus JIS interoperability requirements, and on after-sales service bundling versus unbundled procurement models. Pricing pressure intensifies in the standard tier as domestic Chinese fabricators scale assembly capacity and compete on delivery speed. State railway procurement exhibits highest price sensitivity due to consolidated volumes and mandatory competitive bidding, while Japanese operators demonstrate lowest sensitivity where operational uptime requirements override capital cost considerations.
Supply Chain Analysis
Workforce availability for precision electromechanical assembly constrains capacity expansion in Japan's Kanto industrial corridor and Germany's Bavarian manufacturing clusters, anchoring high-cycle mechanism production in these geographies despite labor cost premiums. Geographic supply concentration centers on China for aluminum extrusions and drive unit final assembly, Japan for precision actuators, and Germany for control system engineering. Raw material dependencies draw from primary aluminum ingots, tempered glass panels, and polymer seal compounds subject to ECHA REACH restrictions. Single-source vulnerability persists for precision electromechanical actuators where Japanese and German producers dominate high-cycle specifications. Distribution runs through state railway procurement authorities in China, METI-coordinated operator consortia in Japan, and fragmented municipal transit authorities in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision electromechanical actuator manufacturing capacity represents the binding constraint propping pricing power for incumbent suppliers, as workforce limitations in Japan and Germany prevent rapid scaling of high-cycle mechanism output.
For Market Incumbents: Extend installed base advantages through captive control system upgrades that deepen integration with signaling networks, locking out modular retrofit competitors. Nabtesco Corporation and Wabtec Corporation should prioritize backward integration into sensor-fusion controller production to defend margin structures against unbundled maintenance contractors displacing original equipment vendor service arms in Chinese metro extensions. For New Entrants and Emerging Players: Specialized maintenance contractors represent the most accessible channel for penetrating the Chinese aftermarket, where state railway procurement separation of capital equipment from operations agreements creates white-space opportunity. Target India's greenfield metro buildout in Mumbai, Bangalore, and Hyderabad for new-build platform screen door specifications without retrofit site access constraints, leveraging partnerships with domestic fabricators in Maharashtra and Karnataka to meet compressed construction timelines. For Investors and Strategic Acquirers: The window for entry favors precision motion-control specialists with sensor-fusion capabilities and established JIS certification alignment, as automated train operation rollouts accelerate demand for integrated platform-train gap safety systems. Long-term viability over the next decade hinges on cross-border certification equivalence for modular designs. The signal to monitor is divergence between GB standards and CE marking timelines, which would force parallel testing investments and consolidate advantage among incumbent suppliers with established multi-jurisdiction compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor-Fusion Controllers | Captures value migration from mechanical barriers to digital train control networks at Japanese and Southeast Asian metros. |
| Modular Retrofit Certification Equivalence | Reduces engineering duplication across China's GB standards, Japan's JIS frameworks, and EU CE marking requirements. |
| Third-Party Maintenance Service Expansion | Exploits unbundled procurement patterns in Beijing and Shanghai metro network extensions displacing OEM service arms. |
| Greenfield Manufacturing Footprint in India | Positions suppliers to serve Mumbai, Bangalore, and Hyderabad metro buildouts without retrofit site access constraints. |
| REACH-Compliant Polymer Seal Reformulation | Secures access to German and French rail infrastructure projects under ECHA restrictions on door gasket compounds. |
Research Methodology
Independent corroboration across metro operator procurement directors, precision electromechanical engineering leads, and rail infrastructure project managers underwrites the qualitative findings on integration complexity and certification divergence. Primary interviews with state railway procurement officers in China, METI-coordinated operator technical staff in Japan, and BIS oversight personnel in India combined with secondary validation from customs trade data, railway equipment certification databases, and SEC filings from listed subsystem suppliers. Bottom-up demand modeling across automatic, manual, and modular product categories triangulates against top-down market sizing derived from metro network extension announcements and capital expenditure disclosures.
Rate-of-change decomposition across the projection horizon isolates volume growth from pricing dynamics and mix shifts toward sensor-fusion systems. Segmentation dimensions modeled include product type complexity, material specification tier, installation constraint category, and end-user procurement authority structure. CAGRs derive from installed base replacement cycles for first-generation barrier systems, new-build station specifications, and retrofit penetration rates. Industry-specific forecast inputs incorporate GB standards enforcement timelines, automated train operation rollout schedules, and REACH compliance transition deadlines for polymer seal formulations.
Caveats apply where aluminum price volatility, precision actuator supply disruptions, or certification timeline compression could materially shift the outlook for supplier margin structures and procurement cycle durations. Forecasts reflect assumptions on state railway procurement continuity, JIS-GB standards interoperability progress, and workforce availability in precision manufacturing clusters. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
Parking Space Management Market
Smart Transportation Solutions
Monorail System Market