
 Car Vending Machine Market | 2026-2036
Car Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Car Vending Machine Market Analysis
Multi-source component procurement is shifting toward vertically integrated supply chains as tower manufacturers seek captive production of elevator mechanisms and climate-control systems. Carvana anchors North American deployment density with its glass-enclosed automated retrieval towers. Vroom competes through a lighter capital model emphasizing software-driven logistics rather than fixed infrastructure. Autobahn Motors dominates Southeast Asian installations with compact-format units tailored to high-density urban parcels.
A car vending machine constitutes an automated vertical storage and retrieval structure housing multiple vehicles in stacked bays, using mechanical elevators and conveyor systems to deliver selected automobiles to ground-level bays within five to seven minutes. These structures integrate steel-framed towers, climate-controlled enclosures, and touchscreen customer interfaces to enable self-service vehicle collection without sales staff intervention. Full-size vending machines currently occupy the majority of installed base value due to their visibility and brand amplification for online retailers. Compact vending machines represent the fastest-growing product category as franchise operators and smaller dealerships seek lower-capital entry into automated retail. Automated dispensing systems command the technology margin pool because mechanical reliability directly determines customer satisfaction scores and repeat transaction rates.
The US Consumer Financial Protection Bureau oversees auto lending disclosures that affect how vending machine retailers structure payment workflows at touchscreen terminals. The National Highway Traffic Safety Administration maintains vehicle safety certification requirements that influence which automobiles qualify for unmanned delivery. Local zoning boards in Dallas, Austin, and Nashville have enacted specific height and setback ordinances that constrain tower placement in mixed-use districts. Stakeholders must monitor evolving municipal land-use codes and federal lending-rule harmonization as these dual regulatory tracks determine where capital deployment accelerates or stalls.
Market Dynamics
Automated vertical storage systems are compressing fulfillment timelines from days to minutes, forcing capital reallocation from dealership real estate toward steel-framed tower infrastructure and AI-driven inventory orchestration.
Growth Catalysts
- Consumer Financial Protection Bureau disclosure rules:Standardized auto lending workflows at touchscreen terminals reduce friction in unmanned vehicle collection, accelerating online retailer adoption across the United States.
- Digital-native buyer segments:Consumers bypassing traditional dealerships create pull-through demand for self-service vehicle retrieval without sales staff intervention.
- Climate-controlled enclosures:Mechanical reliability in extreme weather conditions expands addressable geographies previously unsuitable for outdoor vehicle storage.
Market Restraints
- Steel and aluminum input volatility:Tower manufacturers face margin pressure from fluctuating commodity prices for structural framing and elevator mechanisms.
- Municipal zoning fragmentation:Height and setback ordinances in Dallas, Austin, and Nashville constrain tower placement in mixed-use districts, creating site-by-site approval risk.
- Mechanical complexity threshold:Automated dispensing systems require specialized maintenance networks that remain thin outside major metropolitan clusters.
Strategic Opportunities
- Compact-format penetration:Franchise operators and smaller dealerships in high-density urban parcels present untapped demand for lower-capital automated retail entry points.
- AI-driven inventory management convergence:Machine learning for demand forecasting and mechanical retrieval optimization creates service-layer revenue beyond hardware sales.
- Local zoning code evolution:Municipal land-use liberalization for automated retail structures in transit-oriented districts enables new site categories.
Industry Challenges
- Mechatronics talent scarcity:Integration of elevator systems, conveyor mechanisms, and touchscreen interfaces demands cross-functional engineering expertise in short supply.
- NHTSA safety certification timelines:Vehicle qualification protocols for unmanned delivery extend product launch cycles and constrain model-year flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Vending Machine Market |
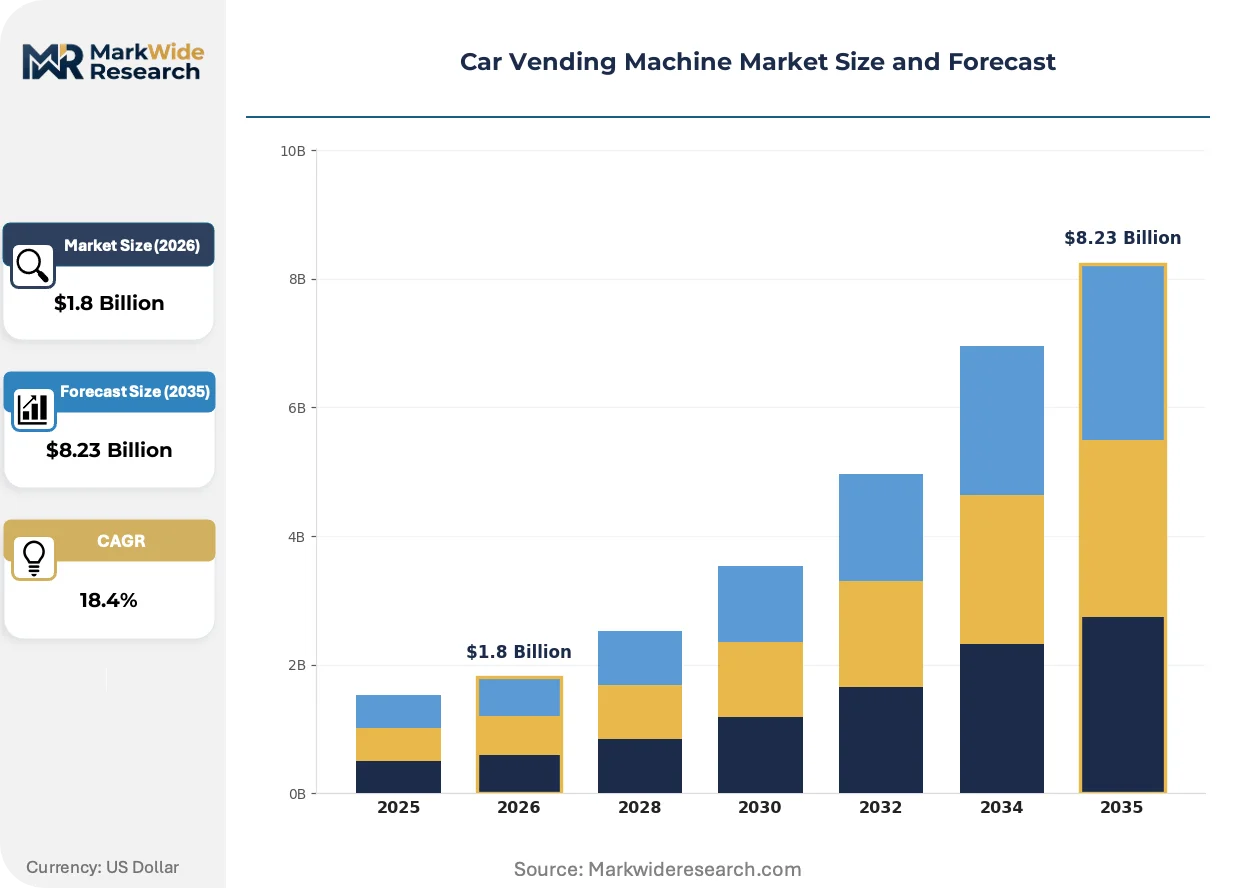
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Vending Machines, Full-Size Vending Machines, Hybrid Models, Mobile Vending Units End User: Retail Operators, Franchise Owners, Automotive Dealerships, Online Car Retailers Technology: Automated Dispensing Systems, Customer Interface Software, Inventory Management Tools, Payment Processing Solutions Installation Type: Indoor Installations, Outdoor Installations, Urban Locations, High Traffic Areas |
| Companies Covered | Carvana, Vroom, CarMax, Autobahn Motors, Nussbaum Technologies, Shift Technologies, Sonic Automotive, Cazoo, Ford & Alibaba Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Vending Machine Market Emerging Trajectories
Touchscreen customer interfaces and mechanical retrieval systems are merging into unified fulfillment platforms that compress transaction friction and reshape competitive differentiation beyond vehicle pricing alone.
Computer vision and predictive maintenance algorithms are unifying mechanical reliability with customer experience optimization. Online retailers deploy these systems to guarantee sub-seven-minute retrieval commitments. The technology is unifying hardware performance with brand trust metrics that drive repeat transaction rates.
EU machinery directives and emerging automated retail safety standards are tightening compliance requirements for vertical storage systems in European markets. Manufacturers must certify elevator mechanisms and climate enclosures to CE marking protocols before deployment. Compact-format vendors targeting European urban parcels are responding with modular designs that simplify field certification.
Self-service vehicle collection is displacing staffed handover ceremonies as the default fulfillment mode for digitally originated purchases. Younger buyer segments treat physical retrieval as a logistics step rather than a sales event. This behavioral pivot concentrates in United States metropolitan markets where Carvana-style tower visibility has normalized the automated experience.
Car Vending Machine Market Segmentation
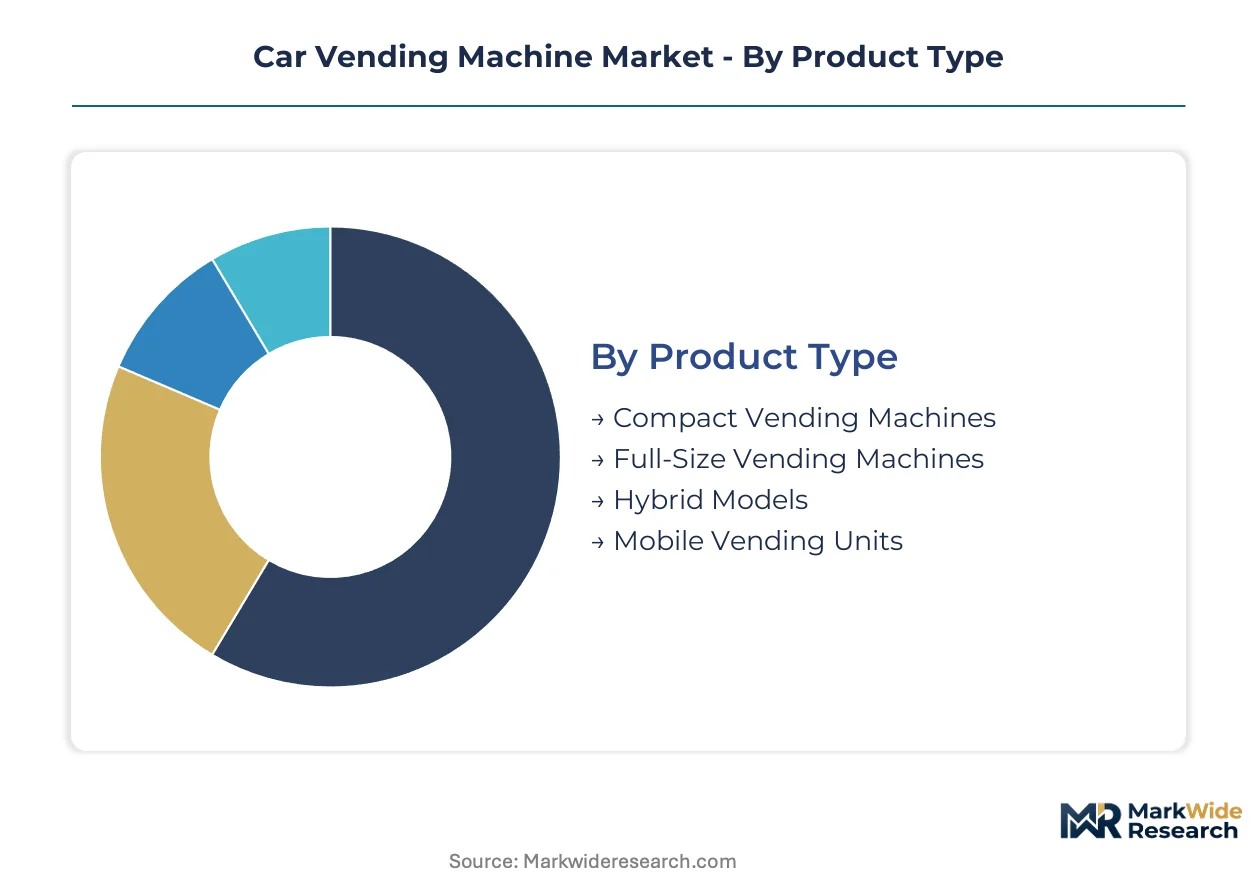
Segmentation in the car vending machine market reveals how capital deployment, buyer sophistication, and site constraints fragment demand across hardware formats and operational models. Understanding these divides helps vendors align product development with the divergent economics of online retailers versus traditional dealerships.
Product Type:
Capital intensity and site footprint separate buyers in this category, with tower height and bay capacity determining addressable customer pools.
- Full-Size Vending Machines:Steel-framed vertical towers with 20-30 vehicle bays dominate visible brand deployments. Online car retailers in the United States concentrate demand here, using glass-enclosed structures for marketing amplification alongside fulfillment.
- Compact Vending Machines:Reduced-height units with 8-15 bays target franchise operators and smaller dealerships in high-density urban parcels. Southeast Asian operators favor these formats where land scarcity and municipal height restrictions constrain tower placement.
- Hybrid Models:Configurable bay systems blend full-size capacity with compact footprints for mixed-use developments.
- Mobile Vending Units:Trailer-mounted retrieval systems serve temporary events and seasonal demand spikes without fixed infrastructure commitment.
Full-size installations lead volumes today; compact formats are expanding most quickly.
End User:
Digital maturity and financing infrastructure separate buyers, with online-native retailers demanding seamless unmanned workflows that legacy dealerships struggle to replicate.
- Online Car Retailers:Digital-first sellers require integrated touchscreen terminals and automated payment processing to complete transactions without staff intervention. These buyers anchor North American deployment density where regulatory clarity around consumer auto financing supports unmanned collection.
- Automotive Dealerships:Traditional sellers adopt vending infrastructure to reduce real estate costs and compress fulfillment timelines. Their installations concentrate in metropolitan clusters where mechanical maintenance networks remain accessible.
- Franchise Owners:Multi-unit operators seek standardized compact formats for rapid geographic replication.
- Retail Operators:Non-automotive retailers test vending concepts for brand differentiation in mixed-use commercial developments.
Online car retailers command the steepest expansion trajectory; automotive dealerships retain the largest installed base.
Technology:
Margin capture potential varies sharply across the technology stack, with hardware reliability commanding premium pricing against commoditized software layers.
- Automated Dispensing Systems:Mechanical elevators and conveyor mechanisms constitute the core IP differentiation. Manufacturers with captive production of these subsystems extract technology margin pools that software vendors cannot match.
- Inventory Management Tools:AI-driven demand forecasting and retrieval optimization create recurring service revenue beyond initial hardware sales.
- Customer Interface Software:Touchscreen terminals and mobile app integration enable self-service collection workflows.
- Payment Processing Solutions:Embedded lending disclosures and automated underwriting integrate with Consumer Financial Protection Bureau compliance requirements.
Automated dispensing systems generate the highest margin contribution; inventory management tools are climbing fastest as buyers prioritize AI-enabled orchestration.
Installation Type:
Climate exposure and zoning permissibility determine site economics, with outdoor deployments requiring hardened enclosures that indoor installations avoid.
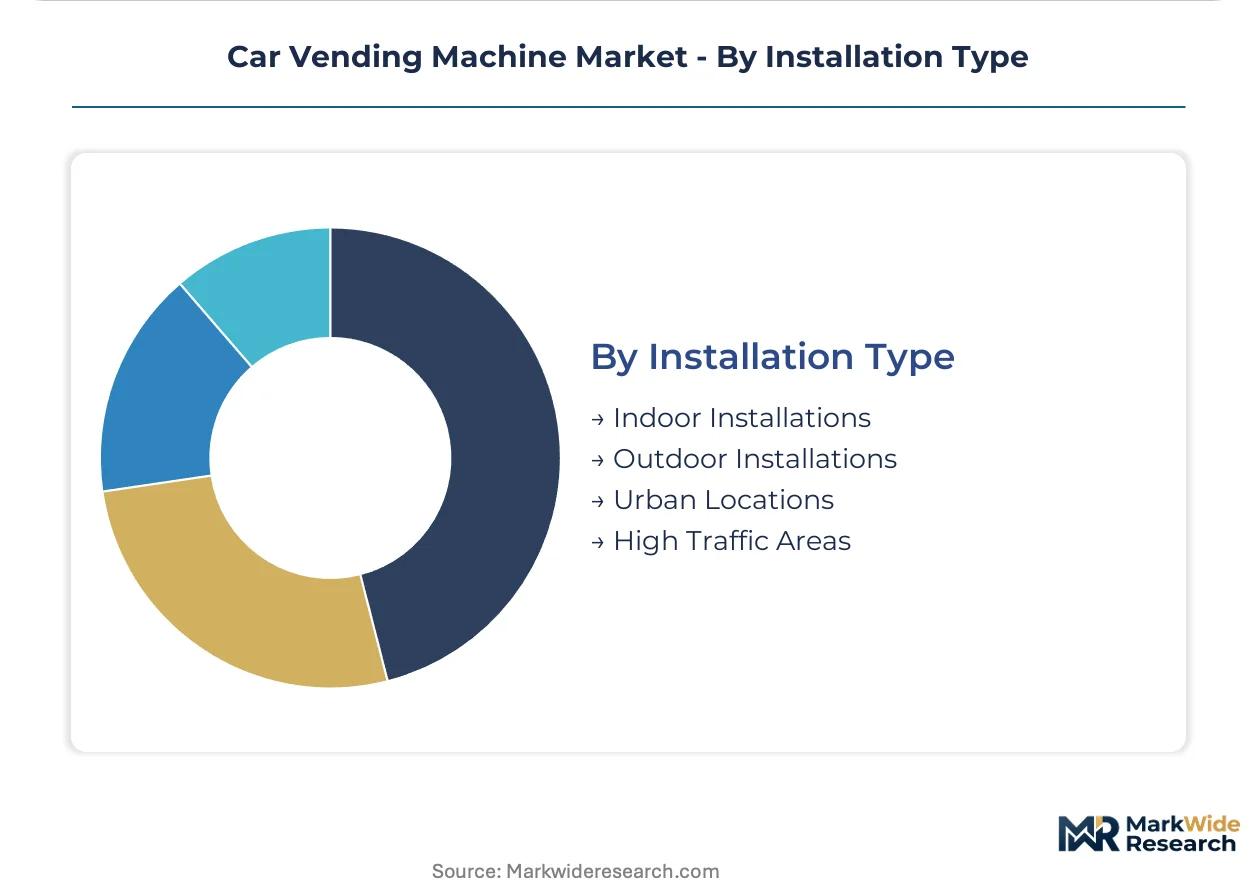
- Outdoor Installations:Climate-controlled steel towers with weatherproofing and HVAC systems expand addressable geographies previously unsuitable for vehicle storage. These structures face heightened municipal zoning scrutiny in mixed-use districts.
- Indoor Installations:Enclosed mall and dealership integrations reduce environmental hardening costs while limiting visibility-driven brand amplification.
- Urban Locations:High-density city parcels with transit proximity command premium placement economics.
- High Traffic Areas:Highway-adjacent and commercial corridor sites maximize consumer exposure for online retailer brand building.
Outdoor installations dominate new capital deployment; urban locations face the tightest site availability constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States metropolitan clusters dominate installed base density, with steel-framed tower deployments concentrated in Sun Belt cities where zoning permissibility and digital-native consumer penetration intersect most favorably.
United States
Carvana's glass-enclosed towers anchor deployment density in Dallas, Austin, and Nashville, where municipal height ordinances have stabilized around automated retail structures. The Consumer Financial Protection Bureau's standardized auto lending disclosure rules enable unmanned touchscreen payment workflows. Greater Phoenix and Atlanta metropolitan areas host the fastest tower installation velocity as online retailers compete for suburban visibility.
Germany
EU machinery directives and CE marking protocols for elevator mechanisms shape manufacturer compliance strategies for vertical storage systems. The KBA maintains vehicle safety certification requirements that influence which automobiles qualify for automated retrieval. Stuttgart and Munich industrial clusters concentrate engineering talent for mechatronics integration in compact-format units.
Singapore
Land scarcity and high-density urban parcels drive demand for reduced-height vending formats with 8-15 vehicle bays. The Land Transport Authority's parking structure regulations influence automated retail placement in transit-oriented developments. Autobahn Motors dominates installations in Marina Bay and Jurong Lake District with space-efficient configurations.
China
MIIT standards for automated mechanical systems and SAMR consumer protection rules frame equipment certification pathways. The dual carbon goals accelerate interest in climate-controlled enclosures that reduce energy intensity per vehicle stored. Shanghai and Shenzhen municipal governments pilot automated retail zoning in mixed-use commercial districts.
United Kingdom
Cazoo's tower deployments concentrate in Greater London and Birmingham where digital-first car buyers bypass traditional dealership networks. The Financial Conduct Authority oversees auto lending disclosure requirements at self-service terminals. Manchester and Leeds emerging clusters test compact-format installations for franchise operator adoption.
Car Vending Machine Market Vendor Landscape
Global majors compete with regional champions across tower manufacturing and online retail fulfillment, producing a tiered structure where capital intensity separates full-size infrastructure deployers from software-driven logistics operators. Three archetypes dominate: vertically integrated tower manufacturers with captive elevator production, asset-light online retailers outsourcing mechanical systems, and hybrid automotive-dealer networks retrofitting existing real estate. Competitive moves concentrate on strategic partnerships for site access and backward integration into climate-control subsystem production.
Within the online retailer archetype, Carvana and Vroom exemplify divergent capital strategies—Carvana through fixed tower infrastructure, Vroom through logistics software. Among automotive incumbents testing automated formats, CarMax occupies a position bridging traditional dealership networks with self-service retrieval experiments. Autobahn Motors anchors the Southeast Asian specialist tier with compact-format expertise. These three named entities represent the spectrum from heavy-infrastructure to asset-light positioning without exhausting the competitive set.
| Leading Market Players |
|---|
| Carvana |
| Vroom |
| CarMax |
| Autobahn Motors |
| Nussbaum Technologies |
| Shift Technologies |
| Sonic Automotive |
| Cazoo |
| Ford & Alibaba Group |
| Others |
Supply Flow & Price Mechanics
Steel and aluminum procurement preferences among tower manufacturers are compressing supplier margins and forcing backward integration into captive production of elevator mechanisms and climate-control subsystems.
Pricing Analysis
Input-cost pass-through from structural steel and aluminum framing dominates pricing dynamics for full-size vending machines. Three-tier pricing structure across premium, standard, and economy levels separates buyers by mechanical reliability specifications and after-sales service bundling. Pricing pressure stems from commodity volatility in structural metals, with online car retailers least price-sensitive due to brand amplification value from glass-enclosed towers. Franchise operators and smaller dealerships exhibit highest price sensitivity, driving compact-format demand.
Supply Chain Analysis
Freight costs for oversized steel tower components anchor supply chain economics in regional manufacturing footprints. Production concentrates in the United States, Germany, and China, with elevator mechanism fabrication drawing from specialized mechatronics clusters. Supply chain risk centers on single-source vulnerability for precision conveyor bearings and climate-control compressors. Distribution runs through manufacturer-direct installation teams rather than third-party logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car vending machine market compounds steadily as digital-native consumer penetration normalizes automated vehicle retrieval across metropolitan clusters.
For Market Incumbents: To counter mechanical complexity threshold constraints, tower manufacturers should deepen captive production of elevator mechanisms and climate-control systems. Certification investment in CE marking protocols and NHTSA safety workflows protects against regulatory fragmentation. Capacity addition in Stuttgart and Shanghai industrial clusters addresses mechatronics talent scarcity. For New Entrants and Emerging Players: Consumer Financial Protection Bureau disclosure standardization in the United States opens a window for software-driven logistics operators to bypass fixed infrastructure requirements. Compact-format penetration in high-density urban parcels presents the most penetrable entry point. Go-to-market positioning should emphasize AI-driven inventory management as a service-layer revenue anchor. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated tower manufacturers with in-house elevator production and established municipal zoning relationships. Long-term viability over the five-to-ten year window hinges on regulatory clarity expanding beyond current metropolitan clusters. Monitor local zoning code liberalization in transit-oriented districts as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elevator Mechanisms | Captive production of precision retrieval systems protects margin pools from commodity volatility. |
| AI-Driven Inventory Management Launch | Machine learning for demand forecasting creates recurring service revenue beyond hardware sales. |
| Compact-Format Geographic Expansion | Reduced-height units unlock high-density urban parcels constrained by municipal height ordinances. |
| CE Marking Certification Pathway | EU machinery directive compliance enables European market entry for vertical storage systems. |
| Municipal Zoning Partnership Program | Direct engagement with Dallas, Austin, and Nashville land-use boards accelerates site approvals. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tower manufacturing executives, online retailer operations directors, municipal zoning officials, and mechatronics engineering leads with secondary validation against SEC filings, customs trade data, and Consumer Financial Protection Bureau regulatory disclosures. Bottom-up installation tracking and top-down market sizing triangulated volume estimates.
Comparable-period anchoring linked projection assumptions to historical deployment velocity across the analysis window. Segmentation dimensions modeled include product type, end user archetype, technology stack, and installation environment. CAGRs derived from mechanical retrieval system adoption curves and digital-native buyer segment expansion patterns, with inputs from steel pricing indices and municipal zoning permissibility scoring.
Revisions become necessary when municipal land-use code shifts, commodity price spikes, or NHTSA safety certification timeline extensions materialize. Forecasts reflect documented assumptions about regulatory harmonization and consumer financing infrastructure development. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Parking Services Market
Automotive Services
Car Washing Service Market
Automotive Services
Automotive Retail Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
North America Car Wash Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Airbag Repair Service Market
Automotive Services
Singapore Car Rental Market
Automotive Services
GCC Car Rental Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
Global Cars-As-A-Service (CaaS) Market