
 Australia Fire Truck Market | 2026-2036
Australia Fire Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Fire Truck Market Insights
Leasing and asset-light fleet arrangements are reshaping how regional fire authorities acquire heavy apparatus, lowering capital barriers for smaller brigades. Rosenbauer Group leverages its European manufacturing scale to compete for Australian defense and civil defense contracts. WA Fire Appliances anchors its position through deep specialization in Western Australian terrain-specific configurations. Varley Group sustains domestic assembly capabilities that differentiate its offering for government tenders requiring local content.
Fire trucks are purpose-built emergency vehicles integrating water pumping systems, aerial ladders, and specialized rescue equipment mounted on heavy-duty chassis, designed to transport personnel and suppress fires in structural, wildland, or industrial environments. Urban fire trucks dominate current procurement volumes due to denser station networks and stricter response-time requirements in metropolitan zones. Wildland fire trucks represent the fastest-expanding product category as climate-intensified bushfire seasons extend operational demands across southeastern Australia. Government agencies command the largest end-user share, though industrial users in mining and energy corridors are emerging as a concentrated margin pool for customized off-road configurations.
Australian Design Rules administered by the Department of Infrastructure govern vehicle safety and emissions compliance for fire truck chassis operating on public roads. Standards Australia maintains AS 2419 and AS 2441 specifications for fire hydrant systems and pumping equipment that directly configure truck-mounted water delivery capabilities. The Building Codes Board coordinates with state fire services to align equipment standards with national construction code amendments. Stakeholders must monitor how evolving carbon-reduction mandates for government fleets reshape powertrain specifications and supplier qualification criteria.
Market Dynamics
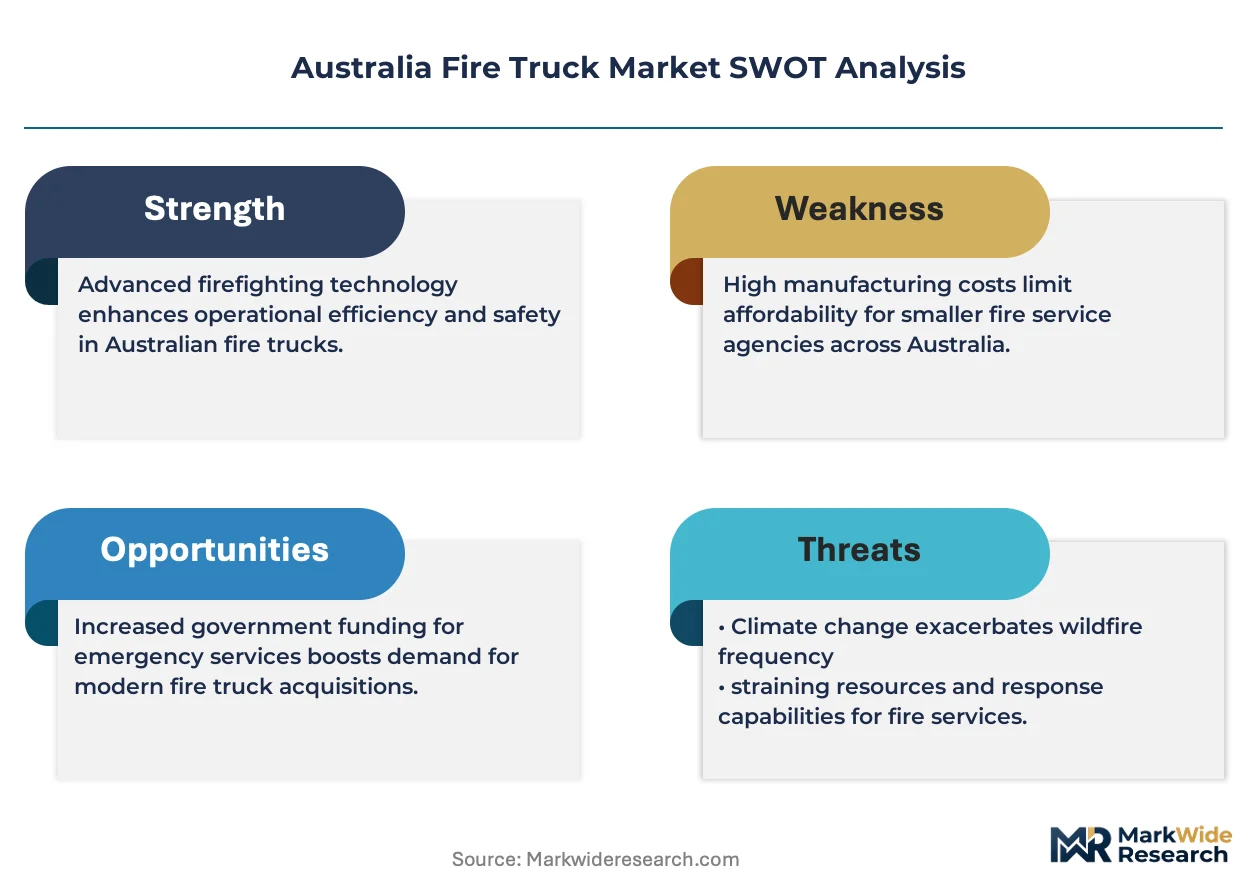
Climate-intensified bushfire seasons are compressing replacement cycles across Australian fire services while the Building Codes Board tightens equipment standards that force chassis and pumping system upgrades.
Growth Catalysts
- AS 2419 Pumping Specifications:Standards Australia's updated hydrant system requirements mandate higher flow-rate capabilities that drive apparatus replacement in New South Wales and Queensland brigades.
- Queensland Rural Fleet Expansion:State procurement budgets for regional fire services have widened to cover wildland-specific configurations as operational seasons lengthen.
- Hybrid Powertrain Trials:Government fleet carbon-reduction mandates are accelerating pilot programs for electric auxiliary systems in urban pumper configurations.
Market Restraints
- Specialized Chassis Concentration:Heavy-duty fire truck chassis supply concentrates among European and North American manufacturers, exposing Australian buyers to currency volatility and extended lead times.
- Aluminum and Composite Input Costs:Aerial ladder and body fabrication depends on aerospace-grade aluminum and engineered composites subject to energy-intensive production cost swings.
- ADR Emissions Compliance Friction:Australian Design Rules administered by the Department of Infrastructure impose testing timelines that delay new powertrain introductions by 12-18 months against comparable markets.
Strategic Opportunities
- Western Australian Mining Corridors:Industrial fire protection contracts in the Pilbara and Goldfields regions reward customized off-road configurations with multi-year service bundling.
- Leasing Model Penetration:Asset-light arrangements are opening municipal procurement to smaller regional brigades previously excluded by capital constraints.
- Telematics and Predictive Maintenance Convergence:Integration of chassis diagnostics with water delivery system monitoring creates recurring revenue streams through performance-based service contracts.
Industry Challenges
- Certified Technician Scarcity:Specialized training for integrated pumping and aerial systems outpaces vocational pipeline output in Tasmania and South Australia.
- Multi-Agency Specification Harmonization:Divergent equipment standards across state fire services force manufacturers to maintain parallel configuration lines, inflating engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Fire Truck Market |
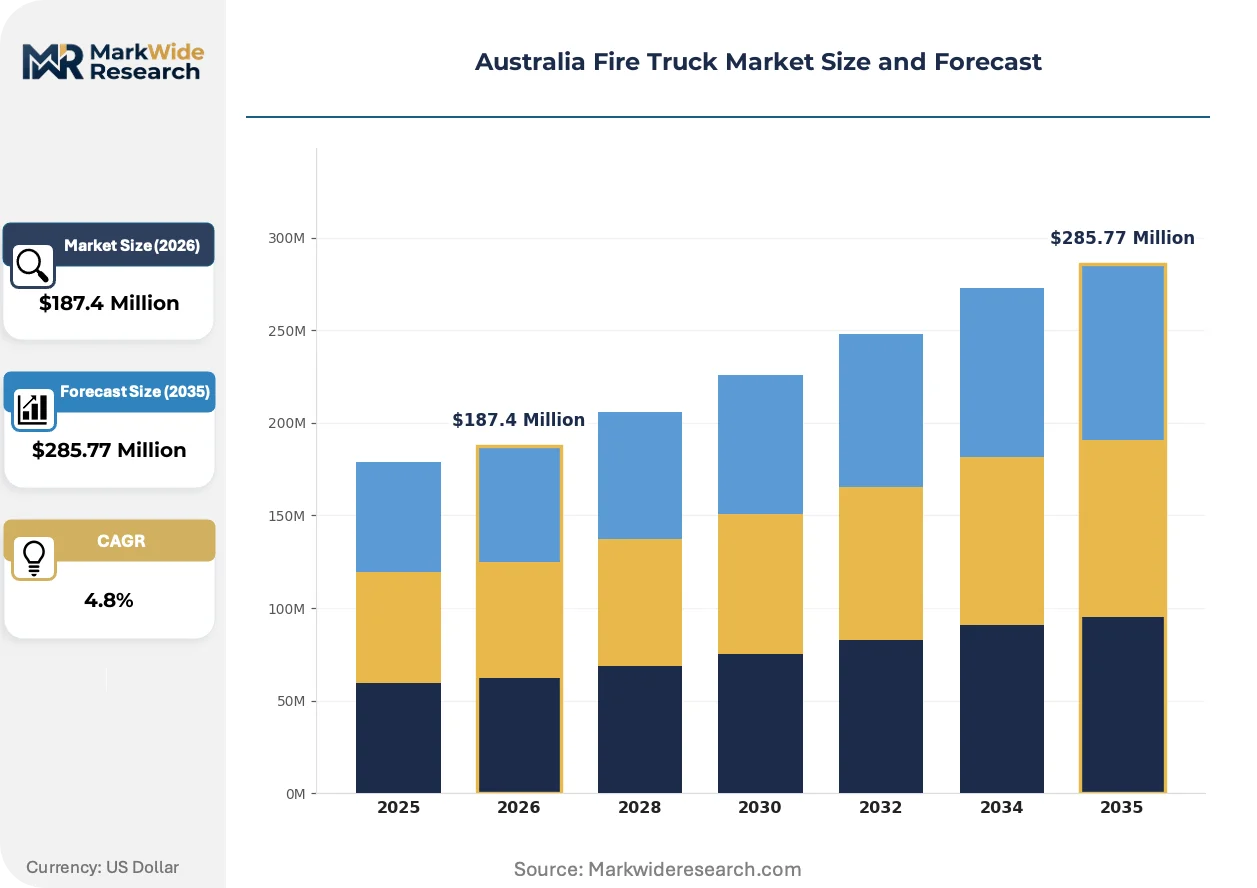
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urban Fire Trucks, Wildland Fire Trucks, Aerial Fire Trucks, Rescue Fire Trucks Application: Firefighting, Emergency Rescue, Disaster Response, Community Safety End User: Government Agencies, Private Sector, Non-Profit Organizations, Industrial Users Deployment: On-Road, Off-Road, Water-Based, Airborne |
| Companies Covered | Rosenbauer Group, WA Fire Appliances, Varley Group (SEM Fire and Rescue), Tatra Trucks, R.A. Bell and Co Pty Ltd, Liquid Sales (Qld) Pty Ltd, Fraser Engineering Limited, AB Volvo, Pearl Fire, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Fire Truck Market Trends and Innovations
Fire truck specification and acquisition patterns are pivoting toward modularity and service-based economics as climate pressures and fiscal constraints reshape how Australian emergency services deploy capital.
Compressed natural gas and hybrid electric auxiliary powertrains are migrating from municipal bus and refuse truck applications into fire apparatus demonstration fleets. Metropolitan brigades in Sydney and Melbourne are piloting these configurations for station-based pumping operations where range and refueling infrastructure constraints are manageable. The technology shift is enabling manufacturers to amortize powertrain development costs across municipal vehicle segments while compressing diesel-only platform lifecycles.
The Australian Building Codes Board coordinates with state fire services to align AS 2441 pumping equipment standards with national construction code amendments. This regulatory convergence is forcing apparatus manufacturers to certify new water delivery configurations against evolving structural fire suppression requirements. Urban pumper categories face the steepest compliance recertification burdens as response-time mandates tighten in denser metropolitan zones.
Regional fire authorities are consolidating procurement through cooperative purchasing agreements that aggregate demand across multiple brigades. This buyer concentration is displacing single-brigade tender processes and favoring suppliers with national service networks and standardized platform architectures. The pattern is most pronounced in Victoria where Country Fire Authority restructuring has centralized fleet planning decisions.
Australia Fire Truck Market Segmentation
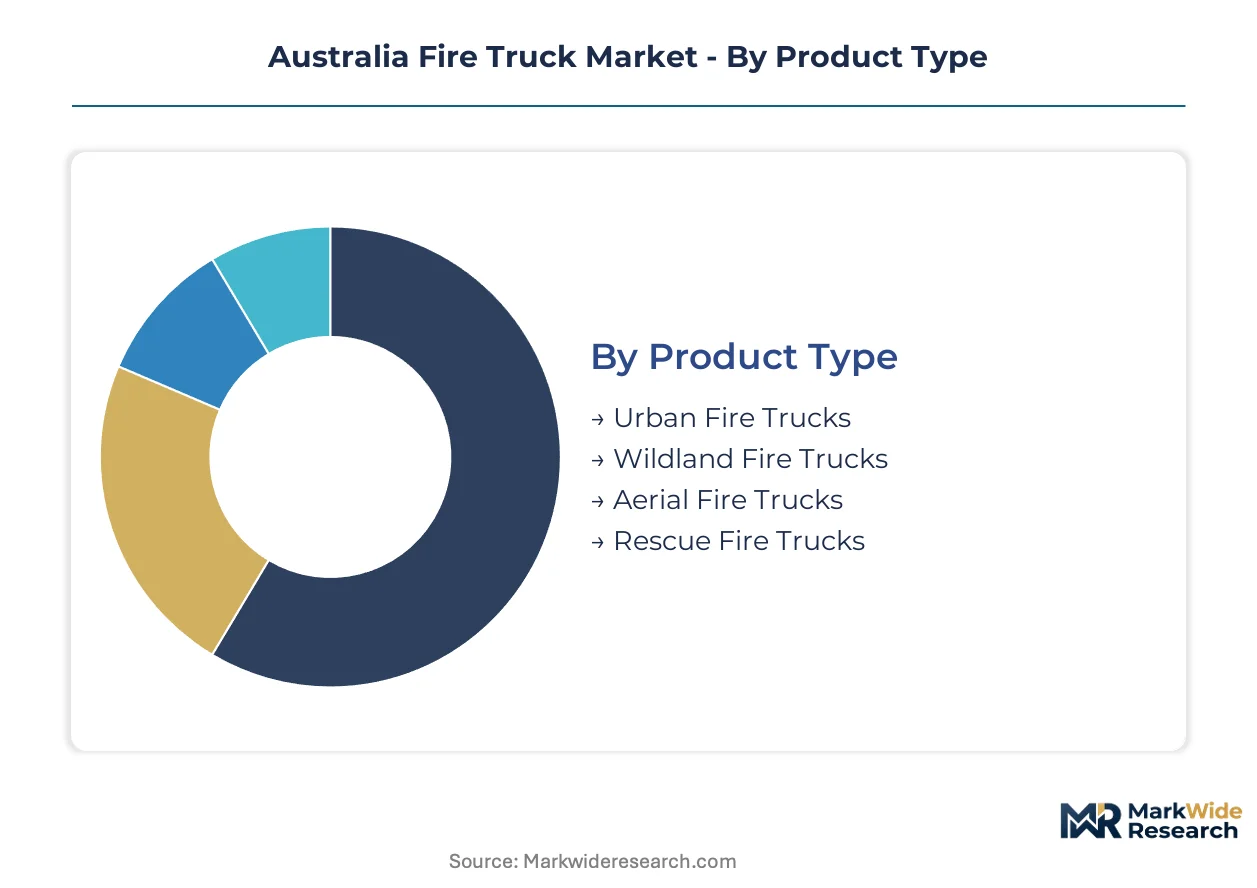
Australian fire truck procurement patterns fragment across operational terrain, regulatory jurisdiction, and capital deployment models. Equipment specifications diverge sharply between metropolitan response networks and remote bushfire suppression corridors, creating distinct aftermarket service ecosystems.
Product Type:
After-sales service intensity varies dramatically across chassis configurations, with aerial platforms requiring specialized technician certification and wildland units demanding terrain-specific parts logistics.
- Urban Fire Trucks:Pumpers and tankers built on heavy-duty road chassis integrate water delivery systems, foam proportioning equipment, and compressed air foam systems for structural suppression. New South Wales Fire and Rescue operates the densest metropolitan fleet, where response-time mandates under the Building Codes Board drive apparatus replacement cycles. Urban configurations command the highest service contract attachment rates due to continuous readiness requirements.
- Wildland Fire Trucks:Bushfire-specific designs feature high-clearance 4x4 or 6x6 chassis, protected pump housings, and extended water tanks for remote operation without hydrant access. Queensland Rural Fire Service and Victoria's Country Fire Authority are expanding procurement as fire seasons lengthen across southeastern Australia. These units require specialized field service networks due to operating distances from metropolitan maintenance depots.
- Aerial Fire Trucks:Turntable ladders and platform configurations incorporate hydraulic elevation systems and water towers for high-rise structural access.
- Rescue Fire Trucks:Multi-purpose units combine pumping capability with extrication equipment, hazardous materials containment, and technical rescue tooling.
Urban Fire Trucks holds the largest share; momentum sits with Wildland Fire Trucks.
Application:
Service bundling patterns track closely to incident frequency and equipment utilization rates across operational categories.
- Firefighting:Core structural and wildland suppression operations account for the highest apparatus utilization hours and corresponding maintenance density. Metropolitan brigades in Sydney and Melbourne run continuous-duty cycles that compress preventive maintenance intervals. State fire services consolidate fleet management to capture economies in parts procurement and technician deployment.
- Emergency Rescue:Road crash rescue, confined space entry, and trench collapse response require specialized stabilization and cutting equipment mounted on multi-role chassis. Demand concentrates along major transport corridors where state emergency services coordinate cross-jurisdictional response protocols. Equipment certification cycles are shorter due to safety-critical hydraulic and pneumatic systems.
- Disaster Response:Flood, storm, and earthquake operations deploy modular equipment packages on standard chassis platforms.
- Community Safety:Fire prevention education and building inspection programs utilize light-duty vehicles with minimal specialized equipment.
Firefighting dominates procurement volumes; Emergency Rescue is expanding most quickly due to multi-agency capability requirements.
End User:
Capital deployment models and procurement authority structures create distinct customer segments with diverging contract terms.
- Government Agencies:State fire services, rural fire brigades, and metropolitan departments operate under public procurement frameworks with mandatory local content preferences and multi-year fleet renewal schedules. New South Wales and Queensland maintain the largest centralized procurement budgets. These buyers negotiate performance-based service contracts with penalty clauses for apparatus availability.
- Industrial Users:Mining, energy, and petrochemical operators in Western Australia's Pilbara and Queensland's Bowen Basin procure customized off-road configurations with integrated foam systems and explosion protection. BHP and Rio Tinto operate captive fire services with dedicated maintenance infrastructure. Contract terms emphasize total cost of ownership and guaranteed response capability.
- Private Sector:Airport fire services, private hospital brigades, and facility management contractors procure to regulatory minimums with shorter asset holding periods.
- Non-Profit Organizations:Volunteer rural brigades rely on state government equipment grants and cooperative purchasing arrangements.
Government Agencies command the largest share; Industrial Users show the steepest expansion trajectory in customized off-road configurations.
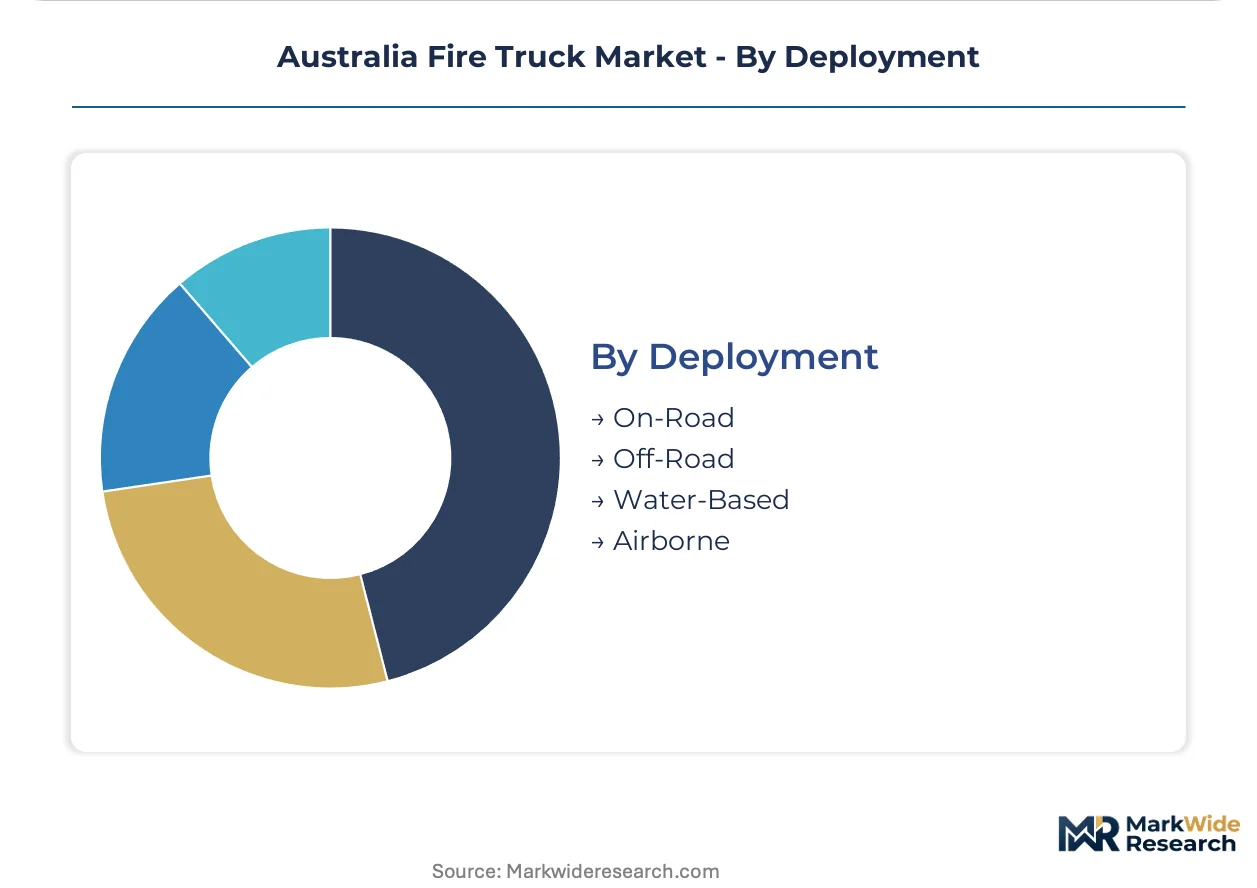
Deployment:
Operating environment dictates chassis specification, regulatory compliance pathway, and service network architecture.
- On-Road:Conventional highway-legal apparatus operating under Australian Design Rules administered by the Department of Infrastructure represents the standardized procurement baseline. Emissions compliance testing timelines delay new powertrain introductions by 12-18 months. Metropolitan brigades concentrate demand for these configurations.
- Off-Road:Mining site, forestry, and remote bushland operations require modified suspension, enhanced cooling, and protected underbody configurations not subject to full ADR certification. Western Australian suppliers anchor this segment through terrain-specific engineering relationships with resource operators.
- Water-Based:Fireboats and amphibious platforms serve harbor facilities and flood-prone regions with specialized marine certification requirements.
- Airborne:Aerial firefighting tankers and command aircraft operate under Civil Aviation Safety Authority regulations with minimal overlap with ground apparatus supply chains.
On-Road deployment holds the largest share; Off-Road configurations are gaining share fastest in resource corridor contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's fire truck market operates with limited import dependency, as European chassis manufacturers supply specialized platforms while domestic fabricators complete body and pumping system integration. State procurement frameworks favor local assembly, creating a regionally distributed supply base aligned with state fire service jurisdictions.
New South Wales
Fire and Rescue NSW maintains Australia's densest metropolitan fleet, where Building Codes Board response-time mandates compress replacement cycles for urban pumpers. The state's procurement budget expansion under the Emergency Services Levy funds cooperative purchasing agreements that aggregate demand across brigades. Sydney anchors the southeastern apparatus cluster, with regional depots in Newcastle and Wollongong extending service networks.
Victoria
Country Fire Authority restructuring has centralized fleet planning decisions, consolidating previously fragmented brigade tenders into state-level procurement. Climate-intensified fire seasons in the Grampians and East Gippsland drive wildland-specific configuration demand. Melbourne's manufacturing corridor hosts chassis modification facilities serving both metropolitan and regional deployments.
Queensland
Rural Fire Service fleet expansion programs target extended operational seasons across the Darling Downs and Southeast Queensland. State government budgets now cover wildland-specific apparatus previously funded through federal grants. Brisbane coordinates procurement for northern brigades, with Townsville and Cairns depots managing terrain-specific field service requirements.
Western Australia
Industrial fire protection contracts in the Pilbara and Goldfields regions reward customized off-road configurations with multi-year service bundling. WA Fire Appliances anchors the domestic supply base through terrain-specific engineering relationships with resource operators. Perth serves as the logistics hub for remote site apparatus deployment and specialized technician dispatch.
South Australia
Metropolitan Fire Service procurement concentrates on urban pumper replacement, while Country Fire Service brigades face certified technician scarcity for integrated aerial systems. Adelaide's maintenance infrastructure supports the Spencer Gulf industrial corridor, though parts logistics lag for remote Eyre Peninsula deployments. State procurement frameworks emphasize total cost of ownership metrics over upfront capital cost.
Australia Fire Truck Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: European chassis manufacturers supplying specialized platforms, domestic body fabricators completing apparatus integration, and regional service specialists maintaining field operations. Strategic archetypes include scale-driven European exporters, terrain-specialized domestic assemblers, and industrial-site service bundlers. Competitive positioning hinges on Australian Design Rules compliance timelines and state government local content preferences rather than pure manufacturing scale.
Among the named participants, Rosenbauer Group represents the European manufacturing scale archetype competing for defense and civil defense contracts, while WA Fire Appliances exemplifies the terrain-specialized domestic fabricator anchored in Western Australian resource corridors. Varley Group occupies a position within the local content tier, sustaining domestic assembly capabilities that differentiate its offering for government tenders requiring in-country fabrication. These three anchors illustrate how procurement fragmentation across state jurisdictions creates parallel competitive vectors rather than a unified national market structure.
| Leading Market Players |
|---|
| Rosenbauer Group |
| WA Fire Appliances |
| Varley Group (SEM Fire and Rescue) |
| Tatra Trucks |
| R.A. Bell and Co Pty Ltd |
| Liquid Sales (Qld) Pty Ltd |
| Fraser Engineering Limited |
| AB Volvo |
| Pearl Fire |
| Others |
Pricing and Supply Chain Analysis
Perth's industrial apparatus fabrication cluster concentrates specialized off-road chassis modification capacity, creating geographic pricing power for Western Australian mining corridor contracts that command premium service bundling terms unavailable to metropolitan procurement frameworks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for customized off-road configurations, while government agency procurement operates through competitive tender with performance-based service attachments. Price differentiation centers on certification grade under Australian Design Rules and after-sales service density, with aerial platforms commanding substantial premiums over standard pumpers. Cost compression in wildland configurations is intensifying because Queensland and Victoria rural brigades aggregate demand through cooperative purchasing agreements. State fire services exhibit lowest price sensitivity due to mandated fleet renewal schedules, whereas volunteer rural brigades face capital constraints that favor leasing arrangements.
Supply Chain Analysis
European export control frameworks on specialized hydraulic and aerial elevation technologies limit component flows to Australian fabricators, creating supply bottlenecks for advanced apparatus configurations. Manufacturing concentrates in Germany, Austria, and the Czech Republic for heavy-duty chassis and aerial ladder systems, while domestic body integration draws from aluminum and engineered composite suppliers in Victoria and New South Wales. Single-source vulnerability concentrates in aerospace-grade aluminum for aerial platforms, subject to energy-intensive production cost swings. Distribution runs through state fire service procurement frameworks with regional depot networks managing downstream service deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across state jurisdictions creates structural niche opportunities as climate-intensified bushfire seasons force divergent equipment specifications that favor specialized regional assemblers over standardized national platforms.
For Market Incumbents: Harden service network density in Queensland and Western Australia to preempt emerging competitors from capturing wildland and industrial maintenance contracts. Invest in Australian Design Rules pre-certification capabilities to compress 12-18 month powertrain introduction delays that threaten chassis supply relationships. Deepen backward integration into pumping system fabrication to defend margin position against European chassis manufacturers expanding downstream.
For New Entrants and Emerging Players: Pursue telematics-enabled predictive maintenance contracts as an entry wedge into government agency procurement frameworks previously closed to capital-constrained regional brigades. Target South Australia's Country Fire Service aerial systems segment, where certified technician scarcity creates service bundling opportunities for new entrants with specialized training capabilities. Lead with performance-based availability guarantees rather than upfront capital cost competition.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative purchasing agreements are concentrating buyer power and displacing single-brigade tenders that previously sustained fragmented local suppliers. Acquisition targets should exhibit terrain-specific engineering relationships with resource operators or established state-level service contracts with penalty-clause structures. Monitor hybrid powertrain pilot program outcomes in Sydney and Melbourne as the inflection signal for powertrain specification shifts that would reshape supplier qualification criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Certification Investment | Pre-positions suppliers for Australian Design Rules compliance ahead of government fleet carbon-reduction mandates. |
| Cooperative Purchasing Agreement Participation | Aggregates demand across Victoria's Country Fire Authority brigades, displacing fragmented single-brigade tenders. |
| Telematics Platform Integration | Creates recurring revenue streams through chassis diagnostics convergence with water delivery system monitoring. |
| Western Australian Service Network Expansion | Captures industrial fire protection contracts in Pilbara mining corridors requiring terrain-specific field service. |
| Backward Integration into Pumping Systems | Reduces exposure to AS 2419 specification changes that mandate flow-rate capability upgrades. |
Research Methodology
Cross-validation between fire service procurement officer interviews and Standards Australia technical documentation anchors the qualitative findings on specification evolution. Primary fieldwork engaged state fleet managers, chassis import specialists, aerial platform technicians, and regional brigade captains across New South Wales, Victoria, Queensland, and Western Australia. Secondary sources incorporated Australian Design Rules regulatory filings, state government budget appropriations, Building Codes Board amendment notices, and customs chassis import records. Bottom-up apparatus deployment counts triangulate against top-down state procurement budget allocations.
Calibration against historical fleet replacement cycles and announced cooperative purchasing agreements shapes the projection framework across the analysis window. Segmentation dimensions span product type, deployment environment, end-user capital structure, and state regulatory jurisdiction. CAGRs derive from weighted average replacement cycle compression rates and announced procurement budget trajectories. Industry-specific inputs include climate-adjusted fire season length projections and hybrid powertrain pilot program conversion assumptions.
Sensitivities concentrate around Australian Design Rules emissions compliance timeline shifts and state government local content preference enforcement. Forecasts reflect documented assumptions on chassis import lead times and cooperative purchasing agreement participation rates. Material shifts in Building Codes Board equipment standards or federal fleet carbon-reduction mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Car Vending Machine Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Auto Leasing Services Market
Automotive Services
Motorcycle Rental Market
Automotive Services
GCC Car Wash Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
US Quick Lube Equipment Market
Automotive Services
Automatic Tire Changer Market
Automotive Services
Automotive Retail Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
United States Automotive Service Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Automotive Register Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Sub Saharan Africa Automotive Market