
 Latin America Contract Logistics Market | 2026-2036
Latin America Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Contract Logistics Market Foresight
ISO 9001 certification is rotating as the baseline qualification for contract logistics providers bidding on multinational accounts in Latin America. DHL Supply Chain leverages its bonded warehouse network across Mexico and Brazil to sustain cross-border automotive flows. Kuehne + Nagel anchors pharmaceutical cold-chain operations with temperature-validated facilities in São Paulo and Buenos Aires. DB Schenker competes on project-cargo specialization for energy sector clients moving oversized equipment into Colombia and Peru.
Contract logistics encompasses the outsourcing of supply-chain execution functions—including inventory storage, order fulfillment, and distribution coordination—to third-party operators under multi-year service agreements, typically governed by KPI frameworks covering on-time delivery rates and inventory accuracy. Warehousing services and transportation management together constitute the core revenue architecture, with pharmaceutical and automotive verticals commanding premium service tiers due to compliance intensity and just-in-sequence delivery requirements. Road freight dominates delivery mode selection across the region, though air freight segments capture disproportionate margin pools from time-critical electronics and healthcare shipments.
ANTT in Brazil, SCT in Mexico, and Argentina's CNRT each enforce distinct operator licensing regimes that dictate fleet specifications, driver certification cycles, and cross-border documentation protocols. These frameworks elevate compliance costs for regional carriers while creating structural advantages for certified multinational providers with dedicated regulatory affairs capabilities. Stakeholders must monitor pending customs modernization initiatives and emerging carbon-reporting obligations that will reshape carrier qualification criteria and contract pricing structures.
Market Dynamics
Nearshoring relocations from Asia-Pacific into Mexico's manufacturing corridor are compressing lead-time requirements and forcing contract logistics providers to reconfigure warehouse networks for just-in-sequence automotive delivery.
Growth Catalysts
- ANTT regulatory modernization:Brazil's updated freight transport rules are mandating carrier recertification, which filters out informal operators and expands contract penetration among certified logistics providers serving formal enterprise accounts.
- Automotive vertical expansion:OEMs in Mexico and Brazil are outsourcing inbound logistics and sequencing centers to third-party operators as production complexity rises with electric vehicle platform introductions.
- Bonded warehouse infrastructure:Cross-border manufacturing clusters along the Mexico-US border are driving demand for customs-synchronized storage facilities that enable duty-deferred component flows.
Market Restraints
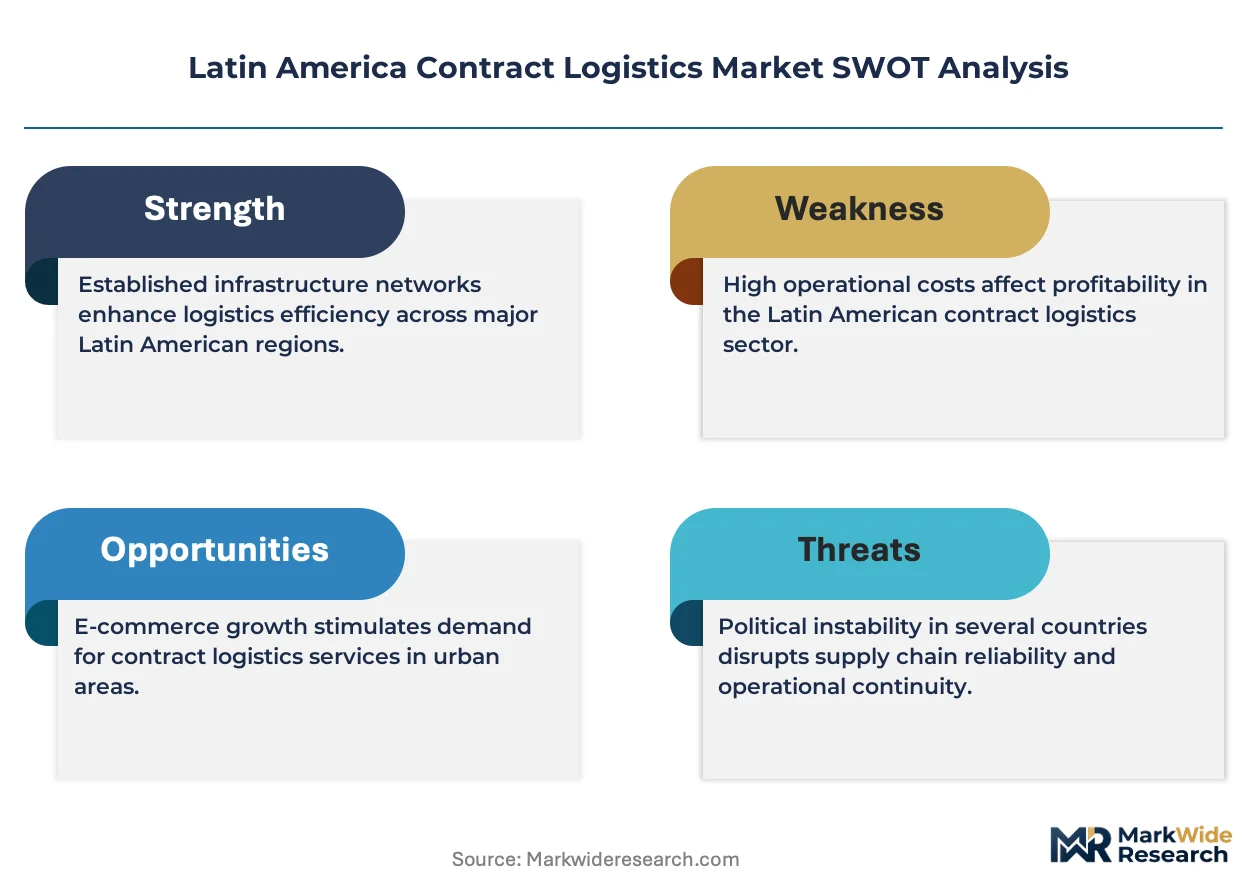
- Diesel price volatility:Road freight dominates Latin American contract logistics, and fuel represents 25-35% of variable costs for regional carriers, compressing margins when price spikes occur without contractual pass-through clauses.
- Fleet asset concentration:Brazil and Mexico together account for the majority of heavy-duty commercial vehicle registrations in the region, creating geographic supply risk when equipment shortages hit these markets simultaneously.
- Driver certification cycles:SCT-mandated refresher training and medical recertification in Mexico create operational friction, reducing effective driver availability during peak seasonal demand windows.
Strategic Opportunities
- Argentina pharmaceutical corridor:Buenos Aires and Rosario harbor underdeveloped cold-chain capacity relative to regional pharmaceutical production growth, creating first-mover advantage for temperature-validated facility investments.
- Colombia energy project logistics:Renewable energy installations in the Andes require specialized heavy-lift and oversized cargo handling that local carriers struggle to execute, opening niche for project-cargo specialists.
- ISO 14001 carbon reporting:Emerging corporate sustainability mandates across multinational accounts are creating preference premiums for providers with validated environmental management systems and emissions tracking capabilities.
Industry Challenges
- Warehouse management system integration:Mid-sized Latin American manufacturers operate legacy ERP platforms that resist API connectivity with modern WMS platforms, forcing expensive custom integration projects that delay contract launches.
- Certified forklift operator scarcity:Formal logistics qualifications remain underdeveloped in regional vocational training systems, creating recruitment bottlenecks for automated high-bay warehouse operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Contract Logistics Market |
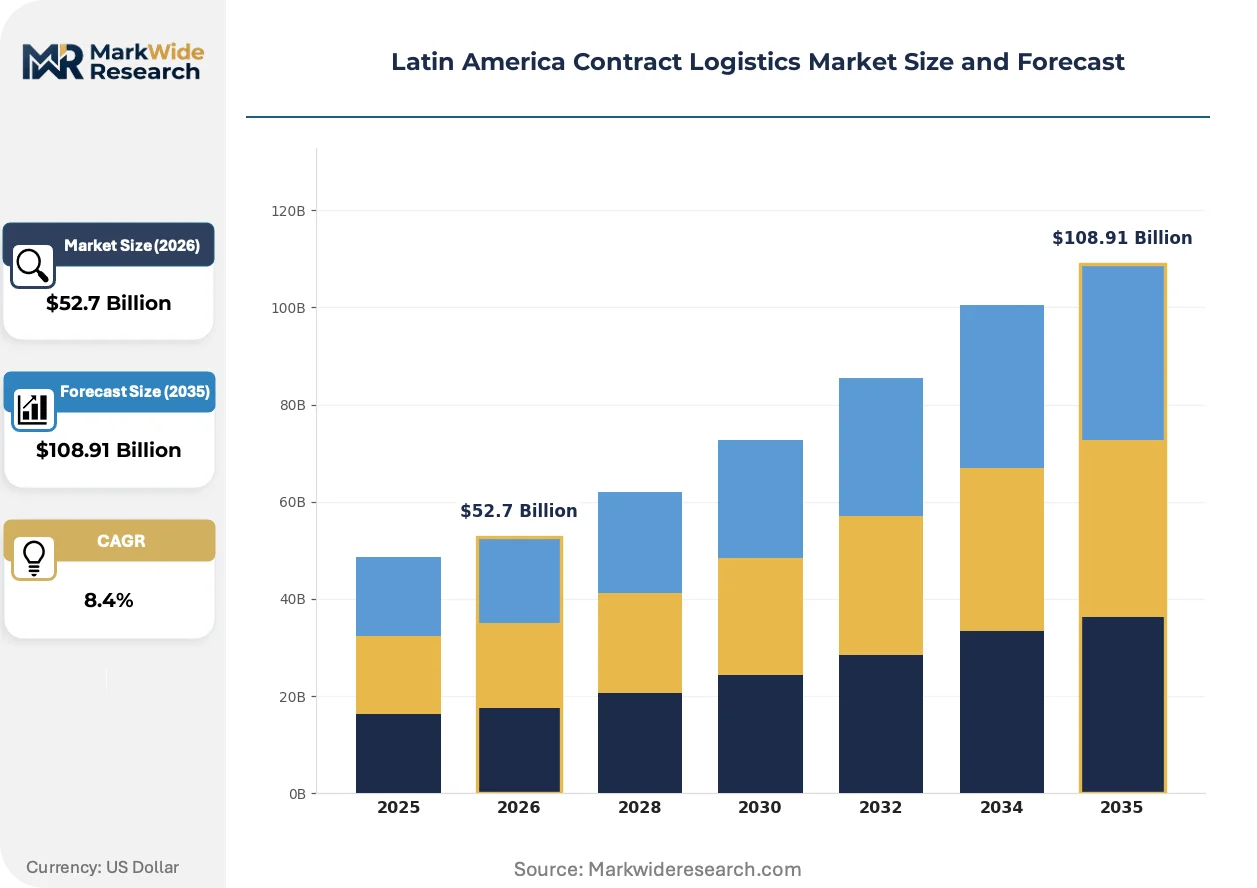
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation Management, Warehousing Services, Freight Forwarding, Distribution Management Industry Vertical: Retail, Automotive, Pharmaceuticals, Consumer Goods Delivery Mode: Road, Air, Sea, Rail Client Type: Large Enterprises, Small and Medium Enterprises, Startups, E-commerce |
| Companies Covered | DB Schenker, DHL Supply Chain, Kuehne + Nagel, UPS, GEODIS, CEVA Logistics, DSV, FedEx, C.H. Robinson, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Contract Logistics Market Shifts & Advancements
Digital freight matching and warehouse automation are converging to compress operational response times, while regulatory pressure on emissions and safety certification is elevating technology investment thresholds for market participation.
Autonomous mobile robots in warehouse operations are decomposing traditional labor-intensive picking and put-away workflows. Automotive and electronics manufacturers with high-SKU complexity are deploying AMR fleets at pilot scale in Mexico City and São Paulo distribution centers. This technology is decomposing the cost advantage of manual operations in high-turnover environments where wage inflation and retention challenges persist.
ANTT's updated freight transport regulations in Brazil are mandating electronic logging devices and stricter driver hour limits. Carrier compliance costs have risen substantially, prompting consolidation among smaller operators unable to absorb technology investments. The formal enterprise segment is responding by lengthening contract durations to lock in qualified capacity and secure rate stability.
Buyers are unbundling transportation management from warehousing in contract structures. Large retail and consumer goods accounts in Mexico are separating these functions to optimize each through specialized providers rather than single-source bundled arrangements. This pattern is most visible among multinational subsidiaries with global procurement mandates and centralized supplier performance scorecards.
Latin America Contract Logistics Market Segmentation
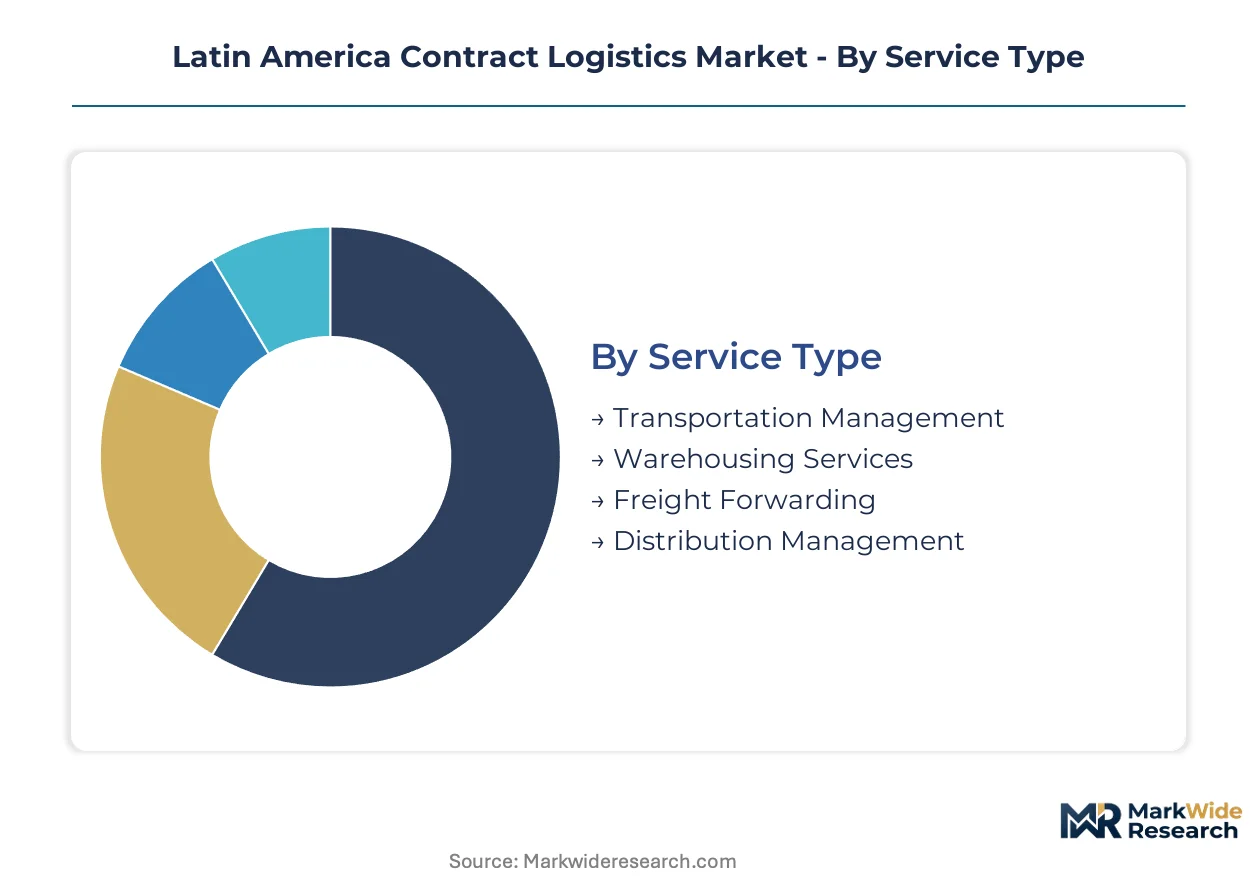
Segmentation in Latin American contract logistics reveals divergent margin structures and regulatory exposures across service types and client profiles. Understanding these divisions enables providers to allocate capital toward bonded warehousing in Mexico's manufacturing corridor and temperature-validated facilities serving Brazilian pharmaceutical production.
Service Type:
Domestic service lines concentrate in warehousing and road-based distribution, while freight forwarding and cross-border transportation management skew toward export-led manufacturing accounts in Mexico and Brazil.
- Transportation Management:Encompasses route optimization, carrier procurement, and freight audit under multi-year KPI frameworks. Demand concentrates among automotive OEMs in Mexico's Bajío region requiring just-in-sequence delivery synchronization with US assembly plants. ANTT electronic logging mandates in Brazil are filtering out informal carriers and consolidating contract awards among certified providers.
- Warehousing Services:Includes inventory storage, order fulfillment, and value-added processing in bonded and non-bonded facilities. Mexico's northern border corridor dominates investment flows as nearshoring relocations compress lead-time requirements for electronics and automotive component flows.
- Freight Forwarding:Coordinates multimodal international shipments with customs documentation and trade compliance management. Activity clusters around São Paulo and Buenos Aires as gateway ports for Asia-Pacific trade lanes.
- Distribution Management:Integrates last-mile delivery networks with retailer replenishment systems. Consumer goods accounts in Colombia and Chile are unbundling this function from warehousing to optimize through specialized providers.
Warehousing Services holds the largest share; momentum sits with Transportation Management as regulatory recertification reshapes carrier qualification.
Industry Vertical:
Vertical specialization determines compliance intensity and pricing power, with pharmaceutical and automotive commanding premium tiers against standardized retail and consumer goods handling.
- Automotive:Demands just-in-sequence delivery, sequencing centers, and cross-border component synchronization. OEMs in Mexico and Brazil are outsourcing inbound logistics as electric vehicle platform introductions multiply part-number complexity. SCT-mandated driver certification cycles create operational friction during peak demand windows.
- Pharmaceuticals:Requires temperature-validated cold-chain facilities with GDP compliance and serialization tracking. Buenos Aires and Rosario harbor underdeveloped capacity relative to regional production growth, creating first-mover advantage for certified investments.
- Retail:Encompasses store replenishment, e-commerce fulfillment, and returns processing. Large multinational subsidiaries are separating transportation from warehousing to optimize each through specialized providers.
- Consumer Goods:Involves high-volume, standardized handling with pressure on unit economics. Diesel price volatility compresses margins when contractual fuel pass-through clauses prove inadequate.
Retail holds the largest share; Pharmaceuticals is climbing the fastest on compliance-premium expansion.
Delivery Mode:
Modal selection reflects trade-off between cost efficiency and time sensitivity, with road freight dominating volume and air freight capturing disproportionate margin pools.
- Road:Accounts for the majority of ton-kilometers across Latin America with flexible routing and extensive network coverage. Fleet asset concentration in Brazil and Mexico creates geographic supply risk when equipment shortages hit simultaneously.
- Air:Serves time-critical electronics and healthcare shipments with premium pricing. Demand concentrates in São Paulo and Mexico City international airports for high-value, low-weight cargo.
- Sea:Handles bulk and containerized flows through Pacific and Atlantic gateway ports. Panama Canal congestion periodically disrupts schedules for Andean market access.
- Rail:Provides intermodal backbone for bulk commodities and select container corridors. Limited network coverage outside Brazil and Mexico constrains expansion.
Road holds the largest share; Air is gaining share fastest on healthcare and electronics time-sensitivity.
Client Type:
Enterprise scale determines contract structure complexity, with large multinationals driving integrated solutions and fragmented SME demand supporting specialized niche providers.
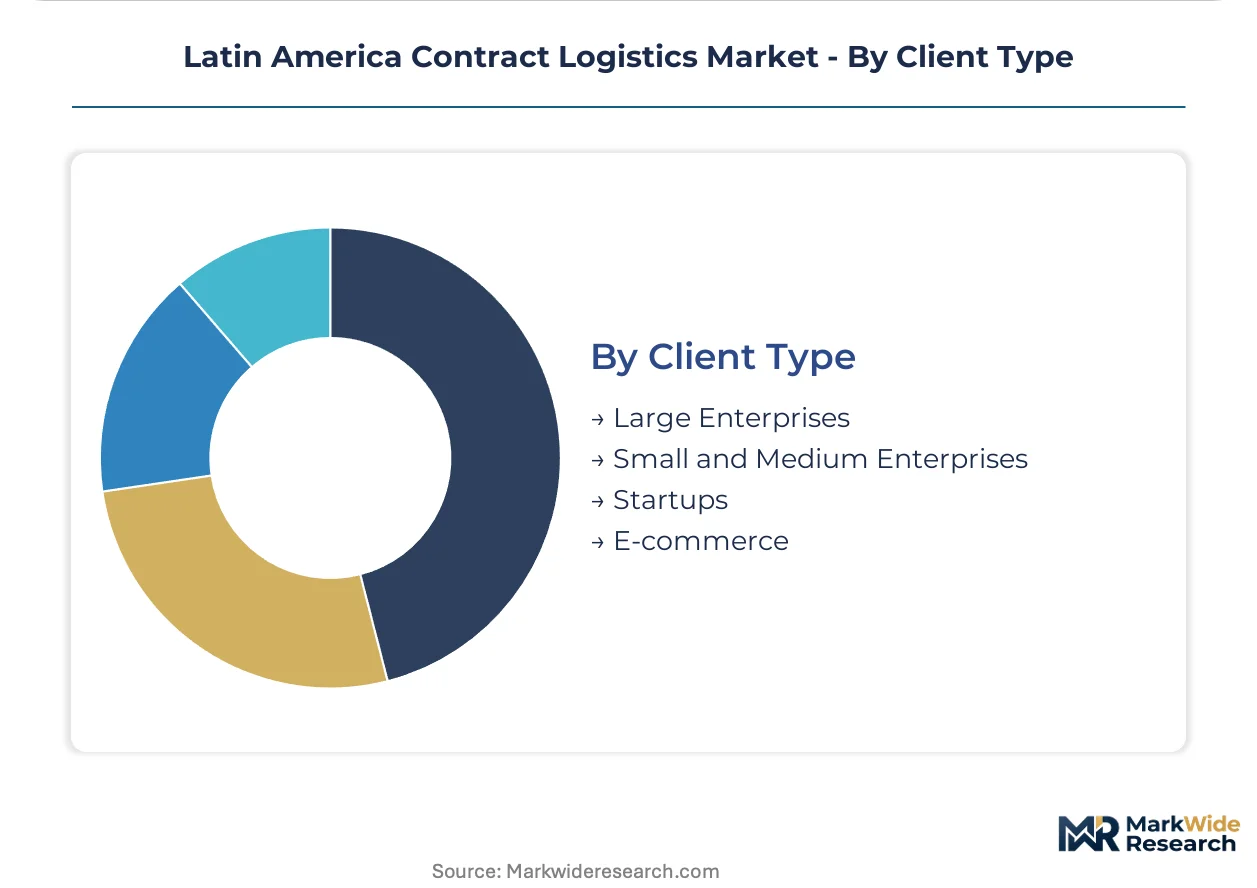
- Large Enterprises:Require multi-country network coverage with centralized procurement and performance scorecards. These accounts are lengthening contract durations to lock in qualified capacity and secure rate stability.
- Small and Medium Enterprises:Seek flexible, short-term arrangements without dedicated infrastructure commitments. ISO 9001 certification is rotating as baseline qualification even for mid-tier bids.
- Startups:Demand scalable, technology-enabled solutions without capital-intensive onboarding. Digital freight matching platforms are reducing entry barriers for this segment.
- E-commerce:Needs rapid fulfillment networks with returns processing and last-mile optimization. Mexico City and São Paulo distribution centers are deploying autonomous mobile robots at pilot scale to address wage inflation and retention challenges.
Large Enterprises holds the largest share; E-commerce shows the steepest expansion trajectory on fulfillment network investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nearshoring incentives from Mexico's federal government and Brazil's ANTT regulatory recertification mandates are redrawing logistics investment maps across Latin America, concentrating contract awards among certified multinational operators.
Mexico
Automotive OEMs expanding electric vehicle production in the Bajío region are compressing lead-time requirements for just-in-sequence component delivery. SCT-mandated driver certification cycles create operational friction during peak seasonal demand windows. The northern border corridor from Tijuana to Matamoros dominates bonded warehouse construction as duty-deferred manufacturing flows accelerate.
Brazil
Pharmaceutical production growth around São Paulo and Campinas is outpacing available cold-chain warehouse capacity. ANTT electronic logging device mandates and stricter driver hour limits are filtering out informal carriers from formal enterprise contracts. The Santos port complex anchors freight forwarding activity for Asia-Pacific trade lanes serving southeastern industrial zones.
Argentina
Underdeveloped temperature-validated storage relative to pharmaceutical output growth is creating facility investment opportunities in Buenos Aires and Rosario. The national transport regulator enforces distinct fleet specifications and cross-border documentation protocols that elevate compliance costs for regional carriers. The Rosario agro-industrial hub generates specialized bulk handling demand for export grain logistics.
Chile
Copper mining operations in the Atacama Desert require project-cargo specialists for oversized equipment movements from Pacific ports to high-altitude mine sites. The country's national mining regulator imposes strict carrier safety certification for hazardous material transport through mountain corridors. The Valparaíso-Santiago logistics axis handles the majority of containerized imports for Andean market distribution.
Colombia
Renewable energy installations in the Andes are driving demand for heavy-lift cargo handling that local carriers struggle to execute. The national transport ministry oversees operator licensing regimes dictating fleet modernization timelines for cross-border Andean routes. The Bogotá-Medellín manufacturing corridor is unbundling transportation management from warehousing to optimize each function through specialized providers.
Latin America Contract Logistics Market Competitive Landscape
Listed logistics conglomerates compete with private specialists across certification depth and bonded infrastructure scale. The market structure tilts toward consolidated multinational presence in premium automotive and pharmaceutical verticals, while fragmented regional carriers retain share in standardized consumer goods handling. Three archetypes dominate: integrated global networks with regulatory affairs capabilities, project-cargo specialists with heavy-lift assets, and digital freight platforms reducing SME entry barriers. Competitive moves center on bonded warehouse network expansion and strategic partnerships with automotive OEMs for sequencing center operations.
Within the integrated network tier, DHL Supply Chain and Kuehne + Nagel occupy positions defined by cross-border infrastructure density. DHL Supply Chain leverages bonded warehouse coverage across Mexico and Brazil to sustain automotive component flows. Kuehne + Nagel anchors pharmaceutical cold-chain operations with temperature-validated facilities in São Paulo and Buenos Aires. DB Schenker represents the project-cargo specialization archetype, competing on oversized equipment handling for energy sector clients moving into Andean markets.
| Leading Market Players |
|---|
| DB Schenker |
| DHL Supply Chain |
| Kuehne + Nagel |
| UPS |
| GEODIS |
| CEVA Logistics |
| DSV |
| FedEx |
| C.H. Robinson |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with fuel-adjustment clauses dominate Latin American contract logistics, locking in qualified carrier access for automotive OEMs while insulating buyers from diesel price spikes that compress margins for operators lacking pass-through mechanisms.
Pricing Analysis
Certification level creates the primary spread between premium and standard service tiers, with ISO 14001-validated environmental management systems commanding preference premiums from multinational accounts facing corporate sustainability mandates. Three-tier pricing structure across premium, standard, and economy levels reflects compliance intensity, with pharmaceutical and automotive verticals occupying the top tier due to GDP and just-in-sequence requirements. Cost compression in the consumer goods segment is intensifying because diesel represents 25-35% of variable costs for regional road carriers. SME accounts show highest price sensitivity, while large enterprises prioritize rate stability through extended contract durations.
Supply Chain Analysis
Just-in-sequence delivery preferences dominate automotive supply chains, forcing warehouse network reconfiguration to support compressed lead-time requirements as nearshoring accelerates. Supply concentrates in Mexico, Brazil, and Argentina, with fleet asset concentration in the first two creating geographic vulnerability during simultaneous equipment shortages. Raw material dependencies include diesel fuel, commercial vehicle chassis, and warehouse automation components sourced from Asia-Pacific manufacturing hubs. Single-source vulnerability runs through Brazil-Mexico heavy-duty vehicle registration dominance. Distribution runs through bonded facilities along Mexico's northern border corridor and São Paulo's pharmaceutical cold-chain cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American contract logistics functions as a service-attach opportunity where transportation management and value-added warehousing expand faster than pure storage, as buyers unbundle functions to optimize each through specialized providers.
For Market Incumbents: Compound bonded warehouse coverage in Mexico's manufacturing corridor to capture nearshoring-driven demand for duty-deferred component flows. Extend contract durations with automotive OEMs to lock in qualified capacity before ANTT recertification filters additional informal carriers. Defend against digital freight platforms by embedding proprietary WMS integration capabilities that resist API connectivity with legacy ERP systems at mid-sized manufacturers.
For New Entrants and Emerging Players: Temperature-validated cold-chain capacity gaps in Buenos Aires and Rosario offer white-space entry points for pharmaceutical-focused facility investments. Target Colombia's renewable energy project logistics niche where heavy-lift specialization requirements exceed local carrier capabilities. Pursue pilot AMR deployments in Mexico City and São Paulo distribution centers to establish technology differentiation before wage inflation erodes manual operation economics.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated network operators with regulatory affairs capabilities and cross-border infrastructure density. Long-term viability favors providers with dedicated compliance teams navigating ANTT, SCT, and CNRT licensing regimes. Acquisition targets should display certified cold-chain assets or bonded warehouse networks in nearshoring corridors. Watch diesel price volatility and customs modernization initiative timelines as inflection indicators for contract repricing cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Network Expansion | Enables duty-deferred component flows for Mexico-US automotive manufacturing clusters. |
| Temperature-Validated Facility Investment | Captures pharmaceutical cold-chain premiums in Buenos Aires and São Paulo production zones. |
| Regulatory Certification Acceleration | Secures ANTT and SCT compliance advantages as recertification mandates filter informal operators. |
| Autonomous Mobile Robot Deployment | Addresses wage inflation and retention challenges in high-SKU Mexico City distribution centers. |
| Transportation-Warehousing Unbundling | Optimizes each function through specialized providers as multinational procurement mandates evolve. |
Research Methodology
Cross-validation between primary field interviews and secondary trade data anchors the qualitative findings in this analysis. Conversations with logistics procurement managers at automotive OEMs, pharmaceutical supply chain directors, bonded warehouse operators, and ANTT regulatory compliance officers informed demand-side and supply-side dynamics. Secondary sources include customs modernization filings, ANTT regulatory updates, SCT operator licensing records, and trade flow databases from regional development banks. Bottom-up facility capacity assessments and top-down trade volume projections were triangulated to validate market sizing.
Sensitivity analysis across diesel price scenarios and nearshoring relocation pace brackets the forecast range. Segmentation dimensions modeled include service type, industry vertical, delivery mode, and client scale across the analysis window. CAGRs were derived from trend extrapolation of bonded warehouse construction permits, carrier recertification completion rates, and pharmaceutical production growth indices. Industry-specific inputs include SCT-mandated driver certification cycle impacts on effective capacity and AMR deployment timelines in high-turnover warehouse environments.
Underlying assumptions cover regulatory implementation consistency and nearshoring relocation continuity, with deviation risk concentrated in diesel price spike magnitude and customs modernization schedule delays. Forecasts reflect these conditions with explicit scenario boundaries. Revision becomes warranted when ANTT recertification completion rates or bonded warehouse utilization thresholds cross material inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Sri Lanka Freight and Logistics Market
Logistics and Shipping
Singapore Chemical Logistics Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
On-Demand Logistics Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Bangladesh Freight and Logistics Market