
 Qatar Car Rental Market | 2026-2036
Qatar Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Car Rental Market Insights
ISO 9001 certification is rotating as the baseline qualification for fleet operators seeking government and corporate contracts in Qatar. Europcar leverages its airport concession network to sustain high-visibility pickup locations at Hamad International. Al Muftah Rent A Car anchors its position through deep coverage of industrial zones in Ras Laffan and Mesaieed. Sixt differentiates via German-engineered fleet standards and premium service tiers targeting expatriate executives.
Car rental denotes the short-term commercial provision of motorized vehicles under contractual terms specifying duration, mileage limits, and insurance coverage, with fleets typically maintained through OEM-authorized service intervals and tire replacement cycles. The primary purpose centers on mobility substitution for travelers, temporary workforce transport, and corporate fleet flexibility without capital ownership. Corporate clients generate the most stable revenue pools through multi-year agreements with predictable utilization rates. Luxury vehicles command premium daily rates during peak event seasons including Formula 1 and international conferences. Short-term rentals dominate transaction volume at airport counters and hotel lobbies, while long-term contracts yield superior fleet utilization efficiency.
Qatar's Ministry of Transport (MOT) enforces commercial vehicle safety inspections and driver qualification standards that directly determine fleet eligibility for government tenders. The Qatar Central Bank's consumer finance regulations shape leasing structures and deposit requirements for individual renters. Qatar Tourism Authority accreditation programs influence which operators gain preferred placement at hospitality venues. Stakeholders must monitor MOT's proposed emissions standards for rental fleets and assess whether electric vehicle procurement timelines align with infrastructure rollout at charging stations across Doha and Lusail.
Market Dynamics
Corporate fleet outsourcing among Qatari logistics and construction firms is compressing ownership cycles and forcing rental operators to reconfigure utilization models around multi-year service agreements rather than transactional daily rentals.
Growth Catalysts
- ISO 9001 certification mandates:Government and corporate tenders now require baseline quality management credentials, filtering out uncertified operators from public sector contracts.
- Industrial zone concentration:Ras Laffan and Mesaieed petrochemical corridors generate sustained demand for heavy commercial vehicle leasing among energy sector contractors.
- Event-driven luxury demand:Formula 1 Qatar Grand Prix and international conference seasons create predictable spikes in premium vehicle utilization.
Market Restraints
- Commercial vehicle licensing friction:Qatar's Ministry of Transport tightened safety inspection protocols, extending fleet registration timelines and raising compliance costs for operators.
- Charging infrastructure lag:Electric vehicle procurement timelines misalign with sparse fast-charging coverage outside Doha and Lusail corridors.
- Imported fleet dependency:Vehicle supply concentrates through OEM-authorized distributors, limiting rental operators' bargaining leverage on procurement terms.
Strategic Opportunities
- Lusail City development zone:The smart city project creates captive demand for connected fleet services and automated rental kiosks at transit hubs.
- Long-term corporate leasing:Multi-year agreements with predictable utilization rates offer superior fleet efficiency compared to volatile short-term counters.
- Qatar Tourism Authority accreditation:Preferred placement programs at hospitality venues unlock exclusive distribution channels for inbound traveler segments.
Industry Challenges
- Technician certification gaps:Advanced diagnostics training for hybrid and electric powertrains lags behind fleet electrification commitments.
- Legacy reservation system integration:Real-time fleet visibility platforms struggle to synchronize with established corporate client procurement portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Car Rental Market |
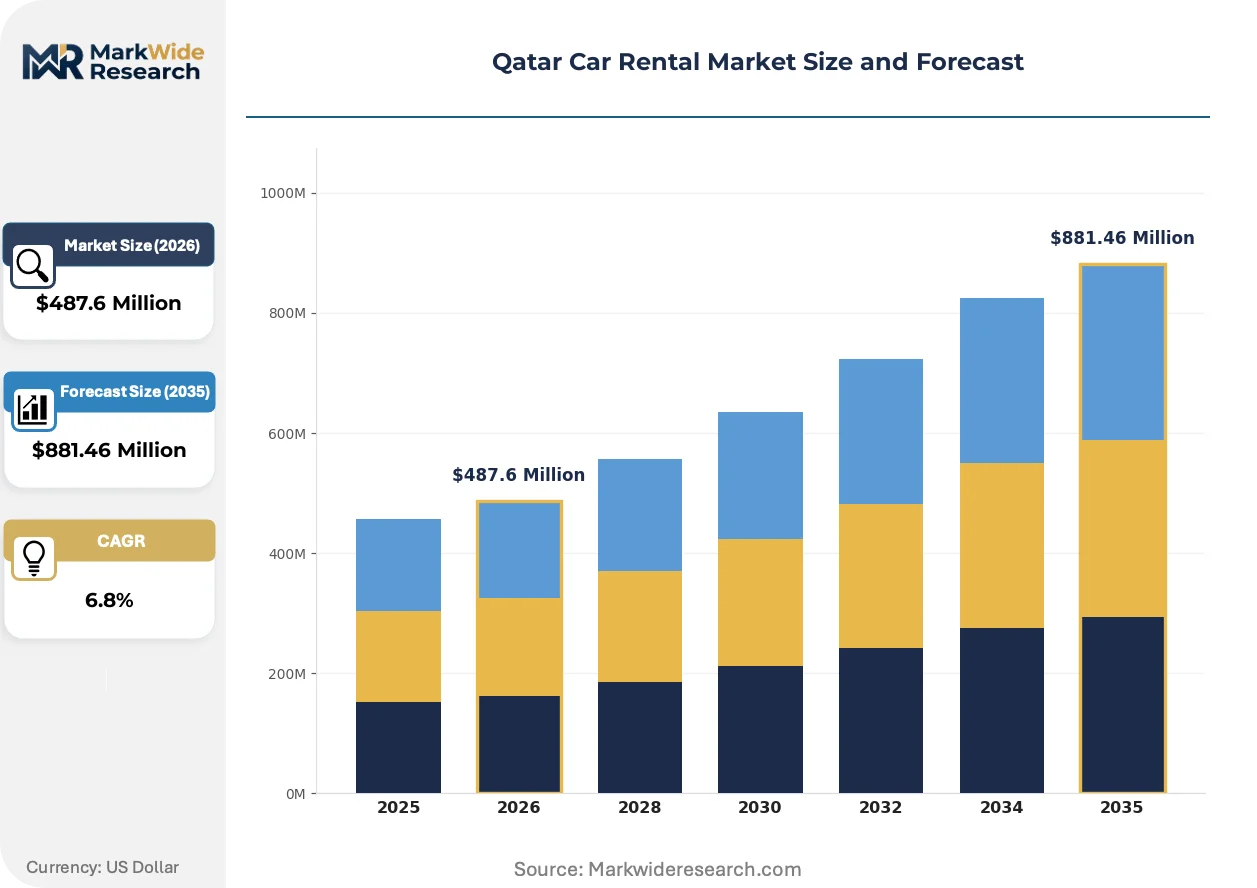
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Corporate Clients, Tourists, Local Residents, Government Agencies Vehicle Type: Economy Cars, SUVs, Luxury Vehicles, Vans Rental Duration: Short-Term, Long-Term, Weekly, Monthly Booking Channel: Online Platforms, Travel Agencies, Direct Rental, Mobile Apps |
| Companies Covered | Europcar, Sixt, Al Muftah Rent A Car, Al Mulla, Regency Fleets, Avis, Budget, Safety Rent a Car, Hertz, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Car Rental Market Trends and Innovations
Connected fleet telematics and automated rental interfaces are restructuring how operators manage utilization, pricing, and customer acquisition across Qatar's concentrated urban corridors and industrial zones.
Telematics-enabled fleet management is bifurcating operator capabilities between data-rich premium tiers and basic tracking systems. Corporate clients with multi-year contracts demand predictive maintenance dashboards and real-time utilization analytics. This technology compression is squeezing mid-tier operators unable to fund integrated platform investments.
Qatar's Ministry of Transport commercial vehicle regulations now mandate enhanced safety inspection frequencies and driver qualification documentation. The industrial consequence forces rental operators to reallocate administrative resources toward compliance documentation. Heavy commercial segments serving Ras Laffan and Mesaieed face the steepest adjustment costs.
Corporate procurement departments now consolidate vendor relationships through centralized fleet management platforms rather than decentralized branch-level contracting. Hotel and airport counter channels face margin compression as direct digital booking displaces intermediary placements. This pattern concentrates most visibly among expatriate executive segments in West Bay business districts.
Qatar Car Rental Market Segmentation
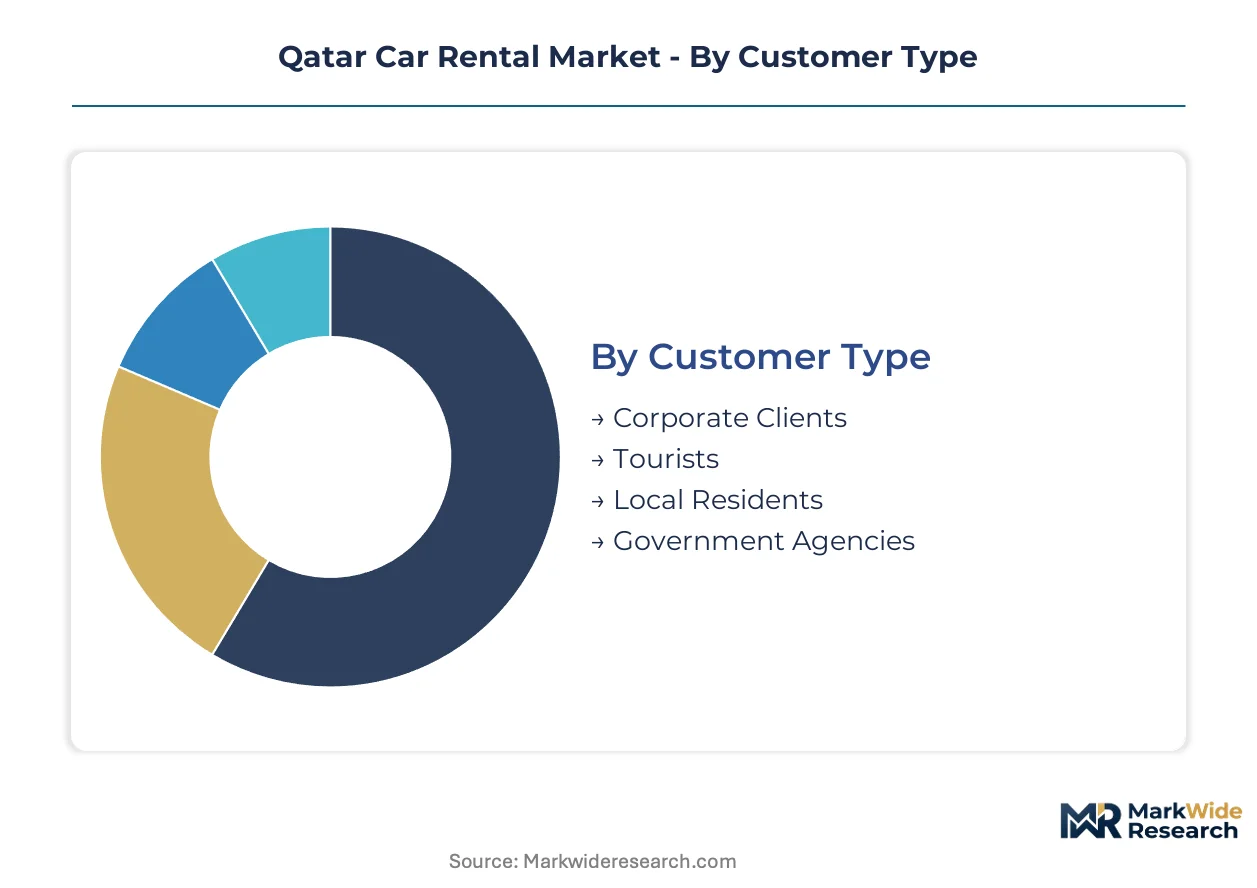
Segmentation in Qatar's car rental market reveals how distinct customer workflows and vehicle utilization patterns create specialized margin pools. Each dimension exposes where operators must align fleet composition, pricing architecture, and service delivery to capture value.
Customer Type:
Corporate clients command the deepest margin pools through multi-year fleet outsourcing agreements with predictable utilization rates.
- Corporate Clients:Multi-year fleet outsourcing agreements with Qatari logistics and construction firms generate stable revenue streams. Demand concentrates in Ras Laffan and Mesaieed industrial corridors where energy sector contractors require heavy commercial vehicle leasing under ISO 9001-mandated procurement.
- Tourists:Inbound travelers arriving through Hamad International Airport drive peak-season utilization spikes. This segment clusters around West Bay business districts and Lusail City development zones during Formula 1 Qatar Grand Prix and international conference seasons.
- Local Residents:Temporary mobility needs during vehicle maintenance periods or family events create intermittent demand patterns.
- Government Agencies:Public sector tenders require baseline quality management credentials that filter out uncertified operators from contract pools.
The dominant share belongs to Corporate Clients, while Tourists is closing the gap fastest.
Vehicle Type:
Luxury vehicles extract premium daily rates during event seasons, though SUVs sustain higher annual utilization across Qatar's dispersed urban geography.
- SUVs:Versatile chassis configurations accommodate both family transport and light commercial duties across Doha's expanding suburban corridors. Demand concentrates among expatriate executives in West Bay districts seeking elevated driving positions and cargo flexibility.
- Luxury Vehicles:German-engineered fleet standards command rate premiums during predictable peak seasons. This segment serves Formula 1 Qatar Grand Prix attendees and international conference delegates requiring chauffeur-ready specifications.
- Economy Cars:Compact sedans serve price-sensitive short-term rentals at airport counters and hotel lobbies.
- Vans:Multi-passenger configurations address workforce transport needs in industrial zones and construction sites.
SUVs holds the dominant position, with Luxury Vehicles expanding most quickly on event-driven pricing power.
Rental Duration:
Long-term contracts yield superior fleet utilization efficiency through predictable depreciation schedules and reduced transaction costs.
- Long-Term:Multi-year service agreements with corporate clients compress ownership cycles and force reconfigured utilization models. This segment generates the most stable revenue pools through centralized fleet management platforms rather than decentralized branch-level contracting.
- Monthly:Extended individual rentals align with temporary workforce assignments and project-based construction timelines.
- Short-Term:Daily and weekend rentals dominate transaction volume at airport terminals and hospitality venues.
- Weekly:Mid-duration bookings capture business travelers with compressed itineraries.
Long-Term captures the dominant share, while Monthly is climbing the fastest on project economy growth.
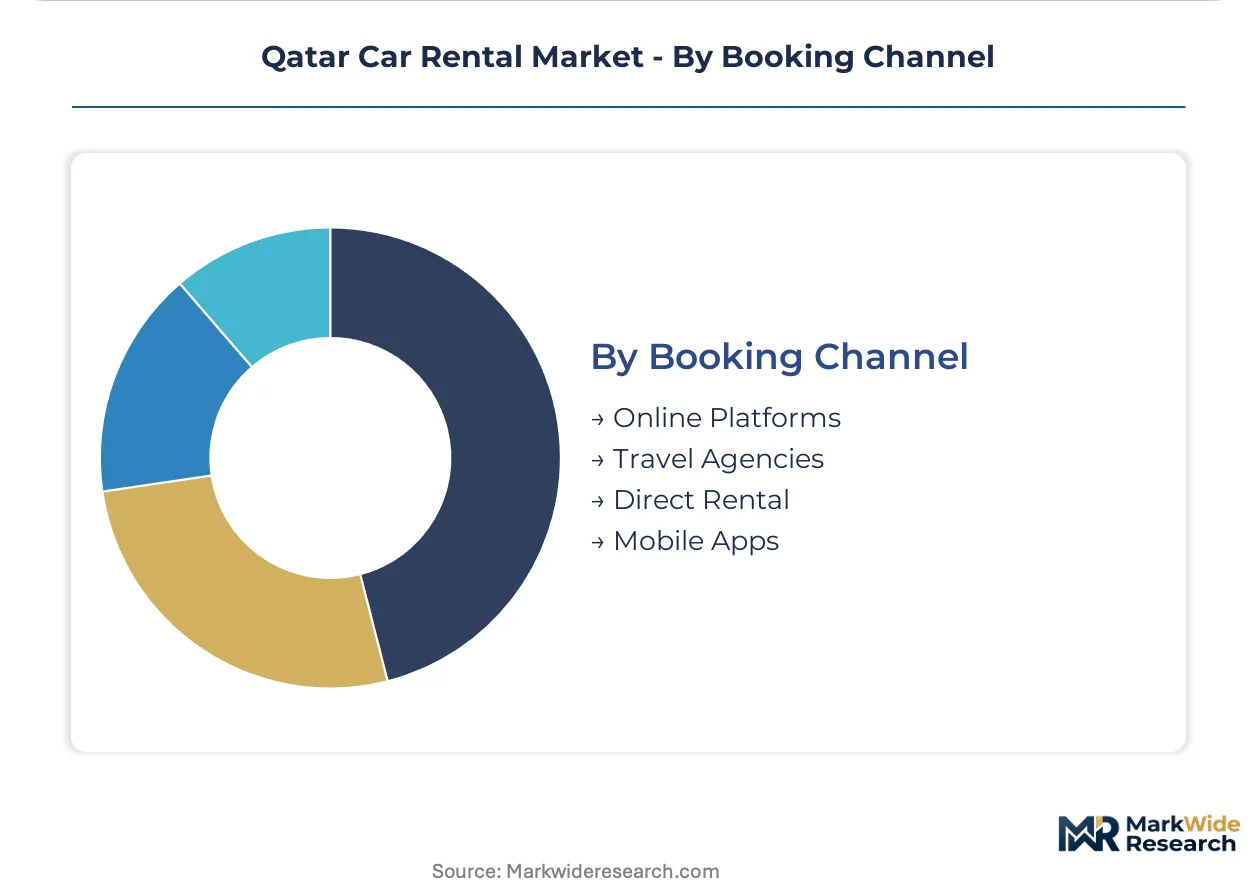
Booking Channel:
Digital platforms are displacing intermediary placements and compressing margins at traditional counter locations.
- Online Platforms:Direct digital booking displaces travel agency intermediaries among expatriate executive segments. Real-time fleet visibility platforms now synchronize with corporate client procurement portals for multi-year contract management.
- Mobile Apps:Automated rental interfaces enable connected fleet telematics integration for predictive maintenance dashboards.
- Direct Rental:Walk-in counters at airport terminals and West Bay business districts face margin compression from platform displacement.
- Travel Agencies:Traditional intermediary channels retain placement at hospitality venues through Qatar Tourism Authority accreditation programs.
Online Platforms commands the dominant share, with Mobile Apps gaining share fastest on telematics integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's Ministry of Transport commercial vehicle regulations and Qatar Tourism Authority accreditation programs are redistributing fleet operator presence across the emirate's economic corridors. The analysis examines demand concentration across five sub-regional markets where policy incentives and infrastructure investment reshape competitive positioning.
Doha Metropolitan Area
Hamad International Airport terminals and West Bay business districts generate concentrated short-term rental volume among inbound travelers and expatriate executives. Qatar Tourism Authority accreditation programs determine preferred placement at hospitality venues throughout the capital. West Bay's financial services cluster sustains premium vehicle demand through corporate procurement channels.
Lusail City
The smart city development project creates captive demand for connected fleet services and automated rental kiosks at transit hubs. Qatar's national infrastructure investment framework prioritizes sustainable mobility solutions within this planned urban zone. Real estate development timelines synchronize with multi-year corporate leasing agreements for construction workforce transport.
Ras Laffan Industrial City
Petrochemical corridor operations generate sustained demand for heavy commercial vehicle leasing among energy sector contractors. ISO 9001 certification mandates filter operator eligibility for government and corporate tenders in this zone. Logistics firms serving Ras Laffan's export facilities compress ownership cycles through fleet outsourcing arrangements.
Mesaieed Industrial Area
Energy and manufacturing operations sustain long-term commercial vehicle utilization with predictable depreciation schedules. Qatar's Ministry of Transport tightened safety inspection protocols extend fleet registration timelines for operators serving this southern industrial hub. Construction project timelines align with monthly and extended rental durations for temporary workforce assignments.
Al Wakrah and Southern Suburbs
Residential expansion and logistics warehousing create emerging demand for versatile SUV configurations and light commercial vehicles. Family transport needs and last-mile delivery operations intersect in this growth corridor south of Doha. Suburban development patterns favor flexible rental solutions over capital ownership for transient resident populations.
Qatar Car Rental Market Competitive Landscape
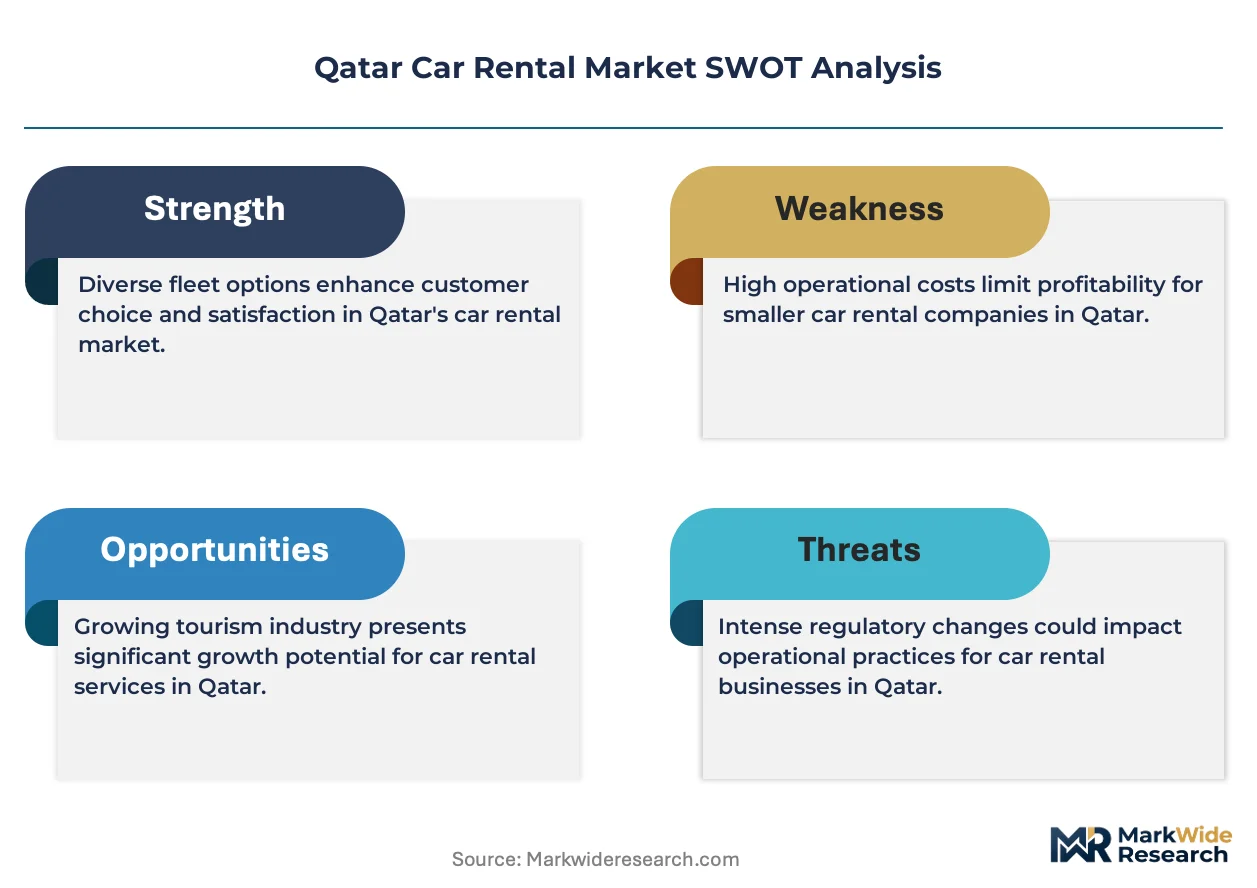
Player mix skews toward international franchise operators with airport concession networks and domestic specialists anchored in industrial zones. Market structure concentrates around three strategic tiers: global brands leveraging premium service standards, regional operators with deep local coverage, and specialized commercial vehicle providers. Dominant competitive moves include ISO 9001 certification acquisition for tender eligibility and telematics platform integration for corporate contract retention.
Among international franchise operators, Europcar and Sixt represent the premium-service archetype through high-visibility airport presence and German-engineered fleet positioning. Al Muftah Rent A Car occupies the domestic specialist tier with concentrated coverage of Ras Laffan and Mesaieed industrial corridors. These three exemplify how operator archetypes align with distinct demand vectors across Qatar's bifurcated market structure.
| Leading Market Players |
|---|
| Europcar |
| Sixt |
| Al Muftah Rent A Car |
| Al Mulla |
| Regency Fleets |
| Avis |
| Budget |
| Safety Rent a Car |
| Hertz |
| Others |
Pricing and Supply Chain Analysis
Fleet electrification commitments replacing internal combustion procurement are simultaneously redrawing supplier geography toward South Korean and Chinese battery OEMs and compressing margin structures as operators absorb upfront vehicle cost premiums without matching rate adjustments.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-accredited operators and uncertified competitors in Qatar's government tender market. Three-tier pricing structure across premium chauffeur services, standard corporate leasing, and economy airport rentals captures divergent buyer willingness-to-pay. Pricing pressure stems from centralized corporate procurement platforms squeezing intermediary margins at hotel and airport counters. Expatriate executives in West Bay districts show lowest price sensitivity, while price-sensitive tourists cluster around Hamad International's economy counters.
Supply Chain Analysis
Inventory lead times for German-engineered luxury vehicles stretch procurement cycles beyond twelve months, forcing operators to commit capital before demand materialization. Vehicle supply concentrates through Japan, Germany, and South Korea OEM-authorized distributors, limiting rental operator bargaining leverage. Fleet composition depends on semiconductor availability for telematics integration and advanced driver assistance systems. Single-source vulnerability runs through exclusive distributor relationships with Qatar's Ministry of Commerce-mandated import channels. Distribution runs through Doha port terminals and bonded warehousing facilities serving Ras Laffan and Mesaieed industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Qatari logistics and construction firms consolidating vendor relationships through centralized fleet management platforms, fragmenting branch-level pricing autonomy and compressing margins for counter-dependent operators.
For Market Incumbents: Consolidate telematics platform investments to retain corporate contract renewals as procurement departments mandate predictive maintenance dashboards and real-time utilization analytics. Deepen ISO 9001 certification maintenance to defend government tender eligibility against emerging competitors. Expand backward integration into captive maintenance facilities serving Ras Laffan and Mesaieed corridors to offset technician certification gaps threatening fleet electrification timelines.
For New Entrants and Emerging Players: Anchor in Lusail City's smart city development zone where automated rental kiosks and connected fleet services face limited incumbent saturation. Target Al Wakrah's southern suburban expansion corridor where residential growth and logistics warehousing create emerging SUV and light commercial demand without established operator coverage. Pursue Qatar Tourism Authority accreditation as the primary go-to-market pathway for preferred placement at hospitality venues.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with domestic specialists holding concentrated industrial zone coverage but lacking integrated telematics capabilities for corporate contract retention. Five-to-ten year viability hinges on electrification infrastructure alignment and MOT regulatory compliance cost absorption. Monitor Ministry of Transport emissions standard proposals as the critical inflection signal for fleet replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time fleet visibility satisfies corporate procurement mandates for predictive maintenance dashboards. |
| ISO 9001 Certification Investment | Quality management credentials unlock government and energy sector tender eligibility in Ras Laffan. |
| Lusail City Kiosk Deployment | Automated rental interfaces capture captive demand at transit hubs within Qatar's smart city flagship. |
| Electric Fleet Procurement | Zero-emission vehicle commitments align with MOT's proposed emissions standards and Lusail sustainability targets. |
| Industrial Zone Service Expansion | Deep coverage of Mesaieed and Ras Laffan corridors secures multi-year logistics and construction contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across Qatar's car rental ecosystem, incorporating fleet managers at logistics firms, procurement leads at construction contractors, operations directors at airport concession operators, and regulatory affairs contacts at the Ministry of Transport. Secondary validation drew from Qatar Central Bank consumer finance regulations, MOT commercial vehicle safety inspection protocols, Qatar Tourism Authority accreditation guidelines, and customs import data for vehicle distributor channels. Bottom-up fleet utilization models triangulated against top-down market value estimates across the analysis window.
Across the projection horizon, the analytical framework modeled customer type segmentation alongside vehicle class, rental duration tiers, and booking channel evolution. CAGRs were derived from regression analysis of historical fleet expansion rates against infrastructure investment timelines and regulatory compliance cost trajectories. Forecast inputs incorporated Lusail City development phase schedules, Formula 1 Qatar Grand Prix event calendars, and MOT inspection protocol amendment trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained infrastructure investment and stable regulatory enforcement; material deviation in electrification infrastructure rollout or MOT emissions standard timing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
North America MRO Distribution Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Motorsports Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Automotive Digital Services Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Electric Vehicle Repair Service Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Americas MAP Market
Automotive Services
US Quick Lube Equipment Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Automatic Tire Changer Market
Automotive Services
GCC Car Rental Market
Automotive Services
Automotive Homologation Services Market
Automotive Services
Tow Truck Market