
 LAMEA Vehicle Exhaust Hose Market | 2026-2036
LAMEA Vehicle Exhaust Hose Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Vehicle Exhaust Hose Market Analytics
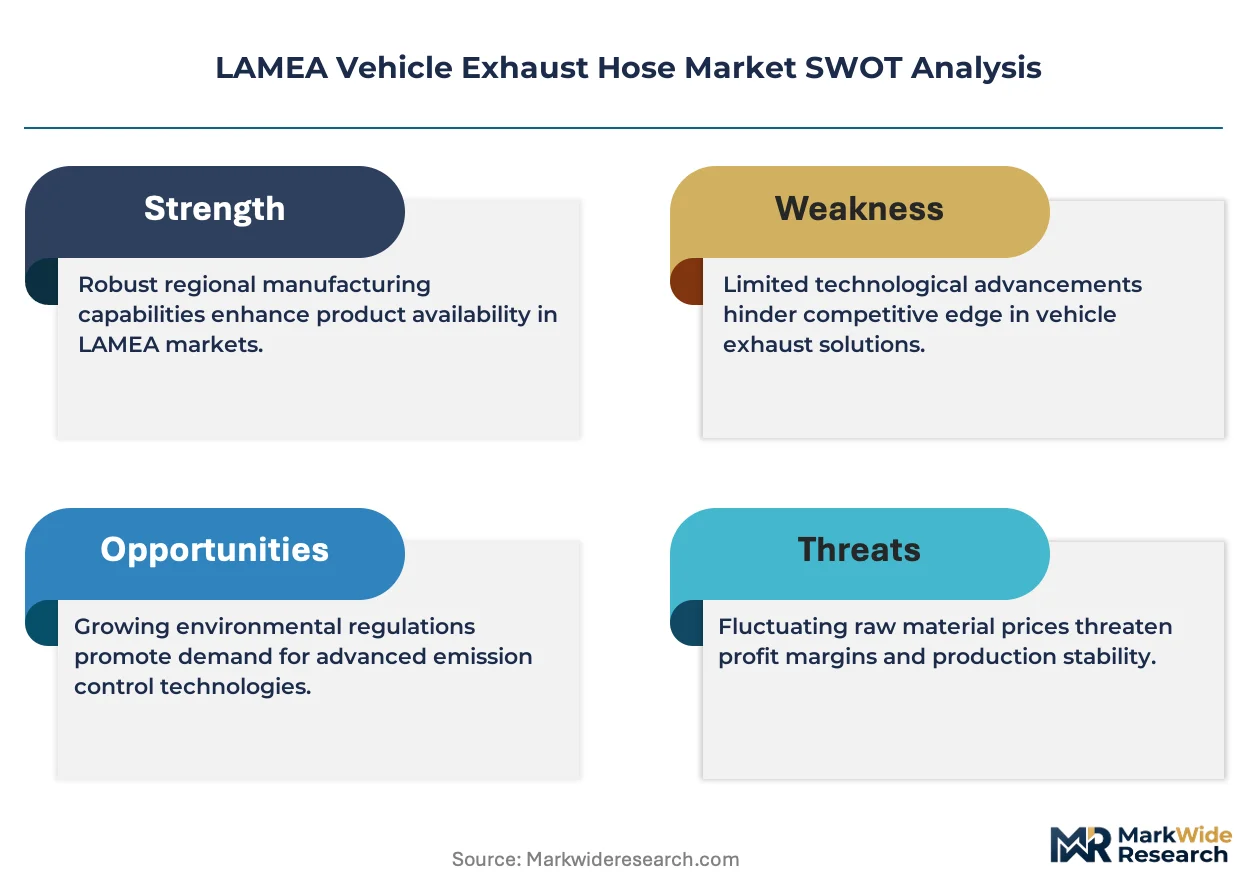
Skilled welder availability for stainless steel fabrication is bifurcating the competitive landscape across the LAMEA region. Nederman Holding AB leverages its captive fabrication capacity to sustain premium positioning in heavy-duty applications. Masterflex SE anchors its regional presence through localized rubber compounding expertise. Air Cleaning Specialists, Inc. competes on rapid-turn custom fabrication for mining fleet operators.
LAMEA vehicle exhaust hoses are flexible or rigid conduits manufactured from stainless steel, rubber, aluminum, or composite materials, designed to channel combustion gases from engine manifolds to after-treatment systems at operating temperatures typically exceeding 600°C. Their primary purpose is maintaining emission containment integrity while accommodating thermal expansion and vibration in commercial vehicle powertrains. Flexible hoses lead product type demand due to installation adaptability in retrofit environments, while composite materials represent the fastest-growing material segment as weight reduction pressures intensify in bus and heavy-duty truck applications. Aftermarket providers capture significant margin pools through emergency replacement cycles driven by PROCONVE enforcement timelines.
Brazil's PROCONVE standards, South Africa's National Regulator for Compulsory Specifications, and local content requirements under the Automotive Production and Development Programme shape product certification and import access across the region. These frameworks mandate specific temperature ratings and material traceability, effectively filtering non-compliant suppliers from OEM qualification lists. Stakeholders must monitor evolving emission testing protocols and localize supply chain nodes to maintain qualification status as enforcement mechanisms tighten.
Market Dynamics
PROCONVE enforcement timelines in Brazil are compressing replacement cycles and forcing aftermarket distributors to hold larger safety stocks of certified hoses, fundamentally restructuring inventory deployment across the LAMEA region.
Growth Catalysts
- Emission Standard Escalation:Brazil's PROCONVE P-8 and P-9 phases mandate higher-temperature containment systems, accelerating fleet-wide retrofit programs in São Paulo's urban bus corridors.
- Mining Fleet Density:South Africa's Platinum Belt transport operators run continuous-duty cycles that exhaust hose lifespans within 18-24 months, creating predictable replacement demand.
- Composite Material Adoption:Silicone-ceramic hybrid constructions reduce weight by 40% versus traditional stainless assemblies, penetrating heavy-duty truck OEM specifications in Chilean copper haul routes.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L sheet pricing fluctuates with nickel exchange rates, squeezing fabrication margins for regional hose assemblers without long-term mill contracts.
- Local Content Thresholds:South Africa's Automotive Production and Development Programme requires 60% domestic value-add, blocking import-dependent suppliers from OEM qualification lists.
- Technical Specification Divergence:Brazilian temperature rating protocols differ from SABS 1129 standards, forcing dual-SKU inventory burdens on distributors serving cross-border fleet operators.
Strategic Opportunities
- Underpenetrated Andean Corridor:Peruvian and Bolivian mining transport fleets operate with minimal emission containment infrastructure, presenting first-mover positioning for certified hose retrofit specialists.
- Smart Fleet Monitoring Convergence:Integration of pressure-drop sensors with exhaust hose assemblies enables predictive replacement scheduling, opening recurring revenue streams for telematics-enabled suppliers.
- PROCONVE Enforcement Services:Authorized testing station networks in Brazilian port cities require emergency hose replacement capabilities, creating channel partnership opportunities for rapid-response fabricators.
Industry Challenges
- Certified Welder Scarcity:TIG welding proficiency for 316L circumferential seams remains concentrated in São Paulo and Johannesburg industrial zones, constraining production scaling in secondary markets.
- Multi-Jurisdiction Traceability:Hose assemblies must carry material certificates acceptable to ANVISA, SABS, and Chile's SEC simultaneously, complicating documentation workflows for regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Vehicle Exhaust Hose Market |
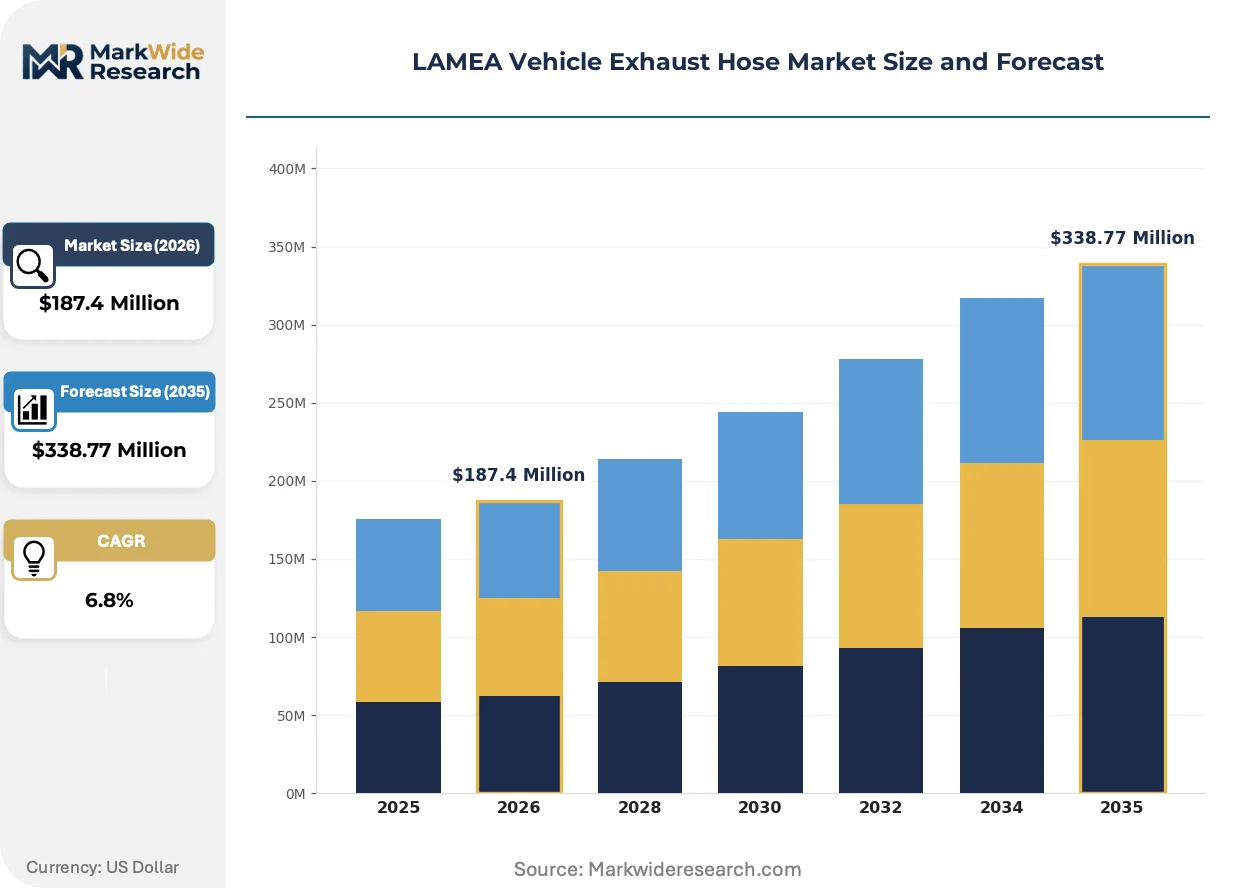
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Hoses, Rigid Hoses, Exhaust Pipes, Connector Pipes Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Buses Material: Stainless Steel, Rubber, Aluminum, Composite Materials End User: OEMs, Aftermarket Providers, Vehicle Manufacturers, Repair Shops |
| Companies Covered | Nederman Holding AB, Masterflex SE, Air Cleaning Specialists, Inc., Novaflex Group, Flexaust Inc., Eurovac, Precision Hose & Expansion Joints, BISCO Enterprise, Inc., Dayco LLC, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Vehicle Exhaust Hose Market Evolving Landscape
Material science advances and enforcement technology deployment are bifurcating the LAMEA exhaust hose landscape into premium certified and unbranded replacement tiers, with digital traceability emerging as the decisive competitive differentiator.
Silicone-ceramic composite laminates rated for continuous operation above 700°C are fragmenting the traditional stainless-steel dominance in heavy-duty applications. Chilean copper haulers and Brazilian sugarcane transport fleets are specifying these assemblies for weight-critical retrofit programs. The technology is fragmenting procurement patterns by enabling direct OEM bypass for mining operators with in-house engineering capabilities.
Brazil's PROCONVE P-8 enforcement protocols now require tamper-evident hose markings traceable to manufacturing batch records. This mandate is compressing the supplier base by disqualifying uncertified aftermarket sources from authorized service networks. Bus rapid transit operators in São Paulo and Rio de Janeiro are absorbing compliance costs through centralized fleet maintenance contracts.
Telematics-integrated procurement is consolidating buyer power among large fleet operators who demand real-time pressure-drop monitoring bundled with hose replacement services. Traditional parts distributors in South Africa's mining corridor are losing share to OEM-authorized service depots offering outcome-based maintenance agreements. This shift is most visible in the Platinum Belt, where Anglo American Platinum and Sibanye-Stillwater have consolidated supplier panels.
LAMEA Vehicle Exhaust Hose Market Segmentation
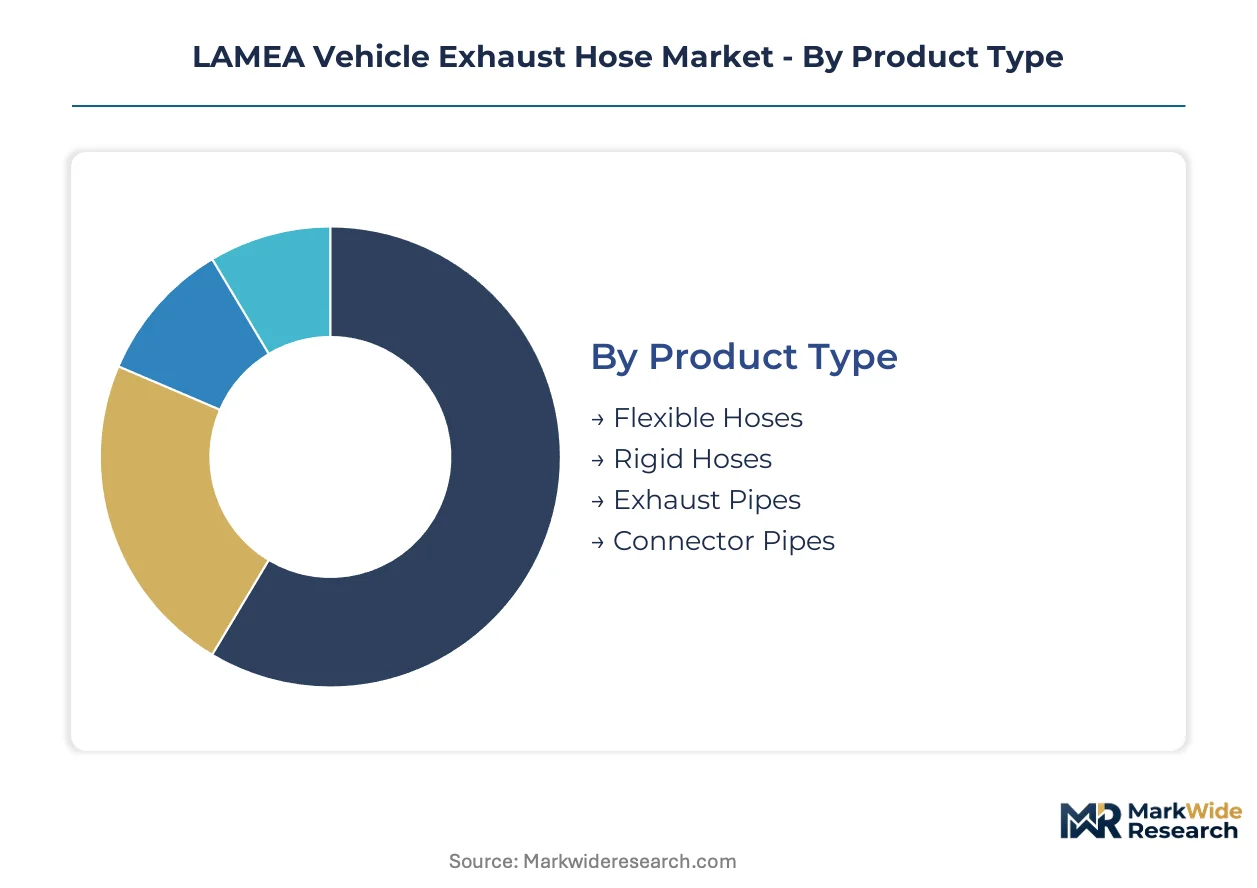
Segmentation in the LAMEA vehicle exhaust hose market reveals how procurement patterns split between retrofit flexibility demands and OEM specification rigidity. Understanding these divides exposes where margin pools concentrate and where certification barriers filter supplier participation.
Product Type:
Margin pools concentrate in flexible hose configurations where retrofit installation complexity commands premium pricing from fleet operators facing PROCONVE compliance deadlines.
- Flexible Hoses:Constructed from multi-ply stainless steel or silicone-ceramic laminates with corrugated geometries accommodating thermal expansion and vibration isolation. São Paulo's urban bus rapid transit operators specify these for retrofit programs where routing constraints prohibit rigid assemblies, absorbing compliance costs through centralized maintenance contracts.
- Rigid Hoses:Fabricated from seamless 316L tubing or cast aluminum with fixed geometries optimized for OEM production line fitment. South Africa's mining transport corridor favors these for original equipment specifications where weight reduction and predictable thermal performance justify higher unit costs.
- Exhaust Pipes:Straight or mandrel-bent tubing sections serving as primary gas conduits in heavy-duty powertrains.
- Connector Pipes:Transition fittings bridging dissimilar diameter or material interfaces in multi-stage exhaust systems.
The dominant share belongs to Flexible Hoses, while Composite Material variants within flexible configurations are climbing the fastest as weight reduction pressures intensify.
Application:
Volume concentration tracks commercial fleet density, with heavy-duty cycles generating predictable replacement demand that aftermarket distributors prioritize.
- Commercial Vehicles:Light and medium-duty trucks operating in Brazilian sugarcane transport and Chilean agricultural logistics. Fleet operators in these corridors run replacement cycles synchronized with PROCONVE enforcement timelines, creating margin concentration for certified suppliers.
- Heavy-Duty Trucks:Copper haulers on Chilean mountain routes and platinum belt transporters in South Africa. Continuous-duty cycles exhaust hose lifespans within 18-24 months, generating recurring revenue streams for service depots with rapid-response fabrication capabilities.
- Passenger Vehicles:Private automobiles with lower thermal loads and extended replacement intervals.
- Buses:Urban transit fleets subject to stringent idling emissions protocols in São Paulo and Rio de Janeiro.
Heavy-Duty Trucks capture the steepest margin expansion trajectory, while Commercial Vehicles maintain volume leadership across replacement cycles.
Material:
Cost tier differentiation separates premium certified assemblies from commodity replacement parts, with material traceability documentation determining OEM qualification access.
- Stainless Steel:Grade 316L and 321 alloys delivering continuous operation above 600°C with oxidation resistance. Nederman Holding AB leverages captive fabrication capacity for circumferential TIG welding of these assemblies, sustaining premium positioning where ANVISA and SABS traceability requirements filter uncertified competitors.
- Composite Materials:Silicone-ceramic hybrid laminates rated for 700°C+ operation with 40% weight reduction versus metal equivalents. Chilean copper haulers specify these for retrofit programs where payload optimization intersects with emission containment mandates.
- Rubber:EPDM and fluoropolymer compounds for lower-temperature flex sections and vibration dampening.
- Aluminum:Cast and extruded alloys for weight-critical applications with moderated thermal requirements.
Stainless Steel retains the largest installed base, though Composite Materials are expanding most quickly in heavy-duty retrofit specifications.
End User:
Customer type determines procurement leverage, with consolidated fleet operators extracting bundled service terms that fragment traditional parts distribution.
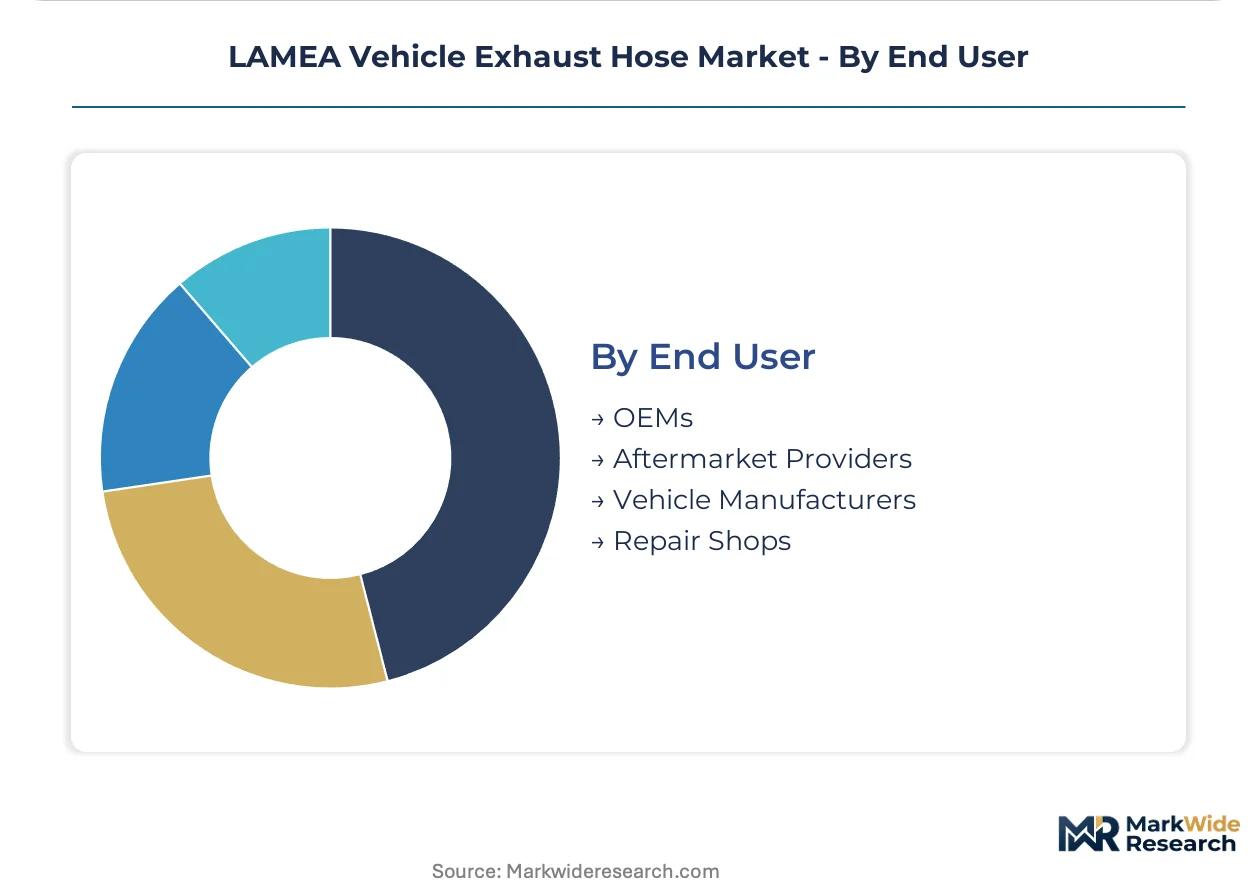
- Aftermarket Providers:Independent distributors and emergency replacement specialists serving mining fleets and port city testing stations. These stakeholders absorb inventory risk by holding safety stocks of dual-certified hoses acceptable to both ANVISA and SABS protocols.
- OEMs:Original equipment manufacturers integrating hoses into new vehicle assemblies. South Africa's Automotive Production and Development Programme mandates 60% domestic value-add, blocking import-dependent suppliers from qualification lists and concentrating procurement among localized fabricators.
- Vehicle Manufacturers:Assembly plants with captive specification control over tier-one supply agreements.
- Repair Shops:Authorized and independent service facilities executing warranty and post-warranty replacements.
Aftermarket Providers command the broadest geographic reach, while OEMs are consolidating supplier panels fastest through outcome-based maintenance agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands premium pricing power through PROCONVE enforcement density, while South African distributors absorb margin compression from local content mandates and nickel input volatility.
Brazil
São Paulo's urban bus rapid transit corridors drive retrofit demand as PROCONVE P-8 phases mandate higher-temperature containment systems. ANVISA traceability requirements filter uncertified suppliers from authorized service networks. Port city testing stations in Santos and Paranaguá require emergency replacement capabilities, restructuring inventory deployment across the national aftermarket.
South Africa
The Platinum Belt mining transport corridor generates predictable 18-24 month replacement cycles from continuous-duty haulers. The Automotive Production and Development Programme mandates 60% domestic value-add, blocking import-dependent suppliers from OEM qualification lists. Johannesburg industrial zones concentrate TIG welding capacity for 316L circumferential seams, constraining production scaling in secondary markets.
Chile
Copper haulers on Andean mountain routes specify silicone-ceramic hybrid constructions for weight-critical retrofit programs. The SEC certification framework diverges from Brazilian temperature rating protocols, forcing dual-SKU inventory burdens on cross-border distributors. Antofagasta and Calama mining clusters absorb compliance costs through centralized fleet maintenance contracts with OEM-authorized service depots.
Peru
Mining transport fleets in the Andean corridor operate with minimal emission containment infrastructure, presenting first-mover positioning for certified hose retrofit specialists. The national environmental regulator tightens enforcement timelines for heavy-duty vehicle emissions. Lima-based distributors hold safety stocks of dual-certified hoses acceptable to both ANVISA and SABS protocols for cross-border fleet operators.
Mexico
Nuevo León's heavy-duty truck assembly plants integrate localized supply chain nodes to maintain qualification status under tightening fitment specifications. The central bank's monetary policy influences stainless steel input pricing through exchange rate channels, squeezing fabrication margins for regional assemblers without long-term mill contracts. Monterrey industrial corridors anchor captive fabrication capacity for circumferential welding of premium assemblies.
LAMEA Vehicle Exhaust Hose Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the LAMEA vehicle exhaust hose market. Premium positioning concentrates among fabricators with captive TIG welding capacity and material traceability systems acceptable to ANVISA, SABS, and SEC simultaneously. Mid-tier regional assemblers compete on rapid-turn custom fabrication for mining fleet operators. Scale-driven specialists and rubber compounding experts occupy distinct competitive vectors, with consolidation pressure intensifying through telematics-integrated procurement and outcome-based maintenance agreements.
Among European-origin industrial filtration groups, Nederman Holding AB and Masterflex SE exemplify divergent strategic archetypes. Nederman represents premium-tier positioning through captive stainless steel fabrication capacity, while Masterflex anchors regional presence through localized rubber compounding expertise. Air Cleaning Specialists, Inc. occupies a position within the rapid-response fabrication tier, serving emergency replacement cycles for mining fleet operators and port city testing stations. These three players illustrate how certification density, material science capabilities, and geographic proximity to enforcement corridors determine competitive viability across the LAMEA region.
| Leading Market Players |
|---|
| Nederman Holding AB |
| Masterflex SE |
| Air Cleaning Specialists, Inc. |
| Novaflex Group |
| Flexaust Inc. |
| Eurovac |
| Precision Hose & Expansion Joints |
| BISCO Enterprise, Inc. |
| Dayco LLC |
| Others |
Value Network & Pricing Analysis
Ninety-day safety stock cycles for PROCONVE-certified assemblies concentrate procurement leverage among São Paulo-based distributors with captive fabrication capacity, compressing margins for import-dependent competitors while elevating price premiums for rapid-response availability. This inventory-service tradeoff shapes tiered pricing power across Brazilian port cities and South African mining corridors.
Pricing Analysis
Configured-to-order premium spreads of 35-50% above catalog pricing separate rapid-turn fabrication specialists from standard catalog distributors in Brazilian and South African markets. Three-tier pricing structure across certified-premium, qualified-standard, and unbranded-economy levels tracks ANVISA traceability documentation and TIG welding certification density. Cost compression in economy-tier stainless steel assemblies intensifies because nickel exchange volatility squeezes regional fabricators without long-term mill contracts. Fleet operators in São Paulo's bus rapid transit corridors exhibit lowest price sensitivity due to PROCONVE enforcement deadlines, while independent repair shops in secondary Brazilian states absorb highest sensitivity.
Supply Chain Analysis
Strategic stockpile preferences dominate Brazilian aftermarket distributors holding dual-certified inventory acceptable to ANVISA and SABS protocols, while just-in-time procurement characterizes OEM-authorized service depots in South Africa's Platinum Belt. Supply concentration rests on China for silicone-ceramic composite substrates, South Africa for localized 316L stainless fabrication, and Germany for precision corrugation equipment. Single-source vulnerability in TIG welding consumables sourced from Johannesburg industrial zones constrains production scaling. Distribution runs through authorized service networks in mining clusters and independent parts distributors in agricultural transport corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified welder scarcity for 316L circumferential seams fragments competitive viability, rewarding stakeholders who anchor production capacity in São Paulo and Johannesburg industrial zones while penalizing remote fabrication attempts.
For Market Incumbents: Fortify captive TIG welding capacity in São Paulo and Johannesburg to defend against emerging rapid-response fabricators targeting emergency replacement cycles. Deepen backward integration into silicone-ceramic composite substrate supply through long-term offtake agreements with Chinese suppliers. Certification investment in ANVISA-SABS dual-traceability systems remains essential for maintaining OEM-authorized service depot status. For New Entrants and Emerging Players: Anchor in Peruvian and Bolivian mining transport corridors where emission containment infrastructure remains minimal and first-mover certification advantages persist. Target Andean copper haulers with weight-critical retrofit specifications for silicone-ceramic hybrid constructions. Deploy telematics-integrated procurement partnerships as the primary go-to-market angle, bundling pressure-drop monitoring with scheduled replacement services. For Investors and Strategic Acquirers: Carve-out targets emerge from European industrial filtration groups divesting non-core LAMEA exhaust hose operations amid portfolio rationalization. Five-to-ten-year viability hinges on PROCONVE enforcement trajectory and composite material substitution rates. Monitor Anglo American Platinum and Sibanye-Stillwater supplier panel consolidation as the decisive inflection signal for aftermarket distributor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Captive TIG Welding Capacity Expansion | São Paulo and Johannesburg fabrication nodes capture premium pricing from PROCONVE enforcement timelines. |
| Silicone-Ceramic Composite Backward Integration | Upstream control over Chinese substrate supply secures margin protection against nickel volatility. |
| Telematics-Integrated Service Partnerships | Pressure-drop sensor bundling opens recurring revenue streams with Anglo American Platinum fleet contracts. |
| Dual-Certification Documentation Investment | ANVISA-SABS traceability compliance filters uncertified competitors from authorized service networks. |
| Andean Corridor First-Mover Positioning | Peruvian mining fleet retrofits offer uncaptured demand before environmental regulator enforcement tightens. |
Research Methodology
Operator-level perspectives from fleet maintenance directors, aftermarket procurement managers, OEM platform engineers, and certified welding supervisors anchored the qualitative base for this analysis. Primary interviews with Brazilian bus rapid transit operators and South African mining transport coordinators combined with secondary validation from ANVISA regulatory filings, SABS standards documentation, and Chile SEC certification frameworks. Customs records for 316L stainless steel sheet imports, vehicle production databases for heavy-duty truck assembly, and mining fleet operator maintenance logs provided demand-side triangulation. Bottom-up unit economics for hose replacement cycles and top-down market sizing from commercial vehicle registration data converged through iterative reconciliation.
Sensitivity analysis tested forecast robustness across nickel price volatility bands, PROCONVE enforcement acceleration scenarios, and composite material substitution rates over the projection horizon. Segmentation dimensions modeled include product type flexibility, application duty cycle intensity, material thermal rating tier, and end-user procurement consolidation level. CAGRs derived from fitted growth curves applied to replacement cycle frequencies and fleet expansion trajectories. Industry-specific inputs incorporated TIG welding capacity utilization rates in Johannesburg industrial zones and silicone-ceramic laminate adoption curves in Chilean copper haul routes.
Decision-makers should treat outputs as directional under stable nickel exchange rates and PROCONVE enforcement adherence to announced timelines; material deviation would warrant model refresh. Forecasts reflect assumptions regarding certified welder availability constraints and composite material qualification progress. Revision becomes warranted when Anglo American Platinum or Sibanye-Stillwater supplier panel consolidation crosses threshold levels that eliminate independent distributor participation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Chassis Leveling Valves Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Forklift Seats Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
US Group 2 Powered Mobility Devices Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Global Automotive Battery Sensor Market
Vehicle Components
Sideloaders Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Electric Forklifts Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
Truck Suspension System Market