
 Automotive Register Market | 2026-2036
Automotive Register Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Register Market Outlook
Subscription-based compliance monitoring is recalibrating what automotive register platforms monetize, shifting revenue from one-time record queries to recurring vehicle-lifecycle data streams. Texas Instruments Incorporated leverages embedded secure-element hardware to anchor authentication layers for these platforms. Infineon Technologies specializes in automotive-grade microcontroller architectures that sustain encrypted data pipelines between registers and OEM backends. Robert Bosch competes through integrated telematics-to-register service bundles that dominate European fleet deployments.
An automotive register is a centralized or distributed data system that records vehicle identity, ownership, operational history, and regulatory compliance status, typically interfacing with government databases and OEM telematics gateways through encrypted APIs with sub-second query response requirements. Its primary purpose is to enable lawful vehicle transfer, insurance underwriting, and emissions accountability across jurisdictions. Digital Platforms and API-enabled Integration Levels capture the deepest margin pools, as OEMs and fleet operators demand real-time bi-directional data exchange rather than static record retrieval. Subscription Services within the service-type dimension are expanding fastest, driven by recurring compliance-check mandates and predictive maintenance integrations.
The EU Green Deal and GDPR shape data sovereignty and cross-border vehicle record portability across Europe, while REACH and CE marking requirements influence the hardware components embedded in connected register terminals. The EPA and NHTSA in the United States enforce emissions and safety recall linkage to state-level registration databases, creating divergent compliance architectures. Stakeholders must monitor which regulatory framework prevails in their target geography before committing to platform architecture decisions.
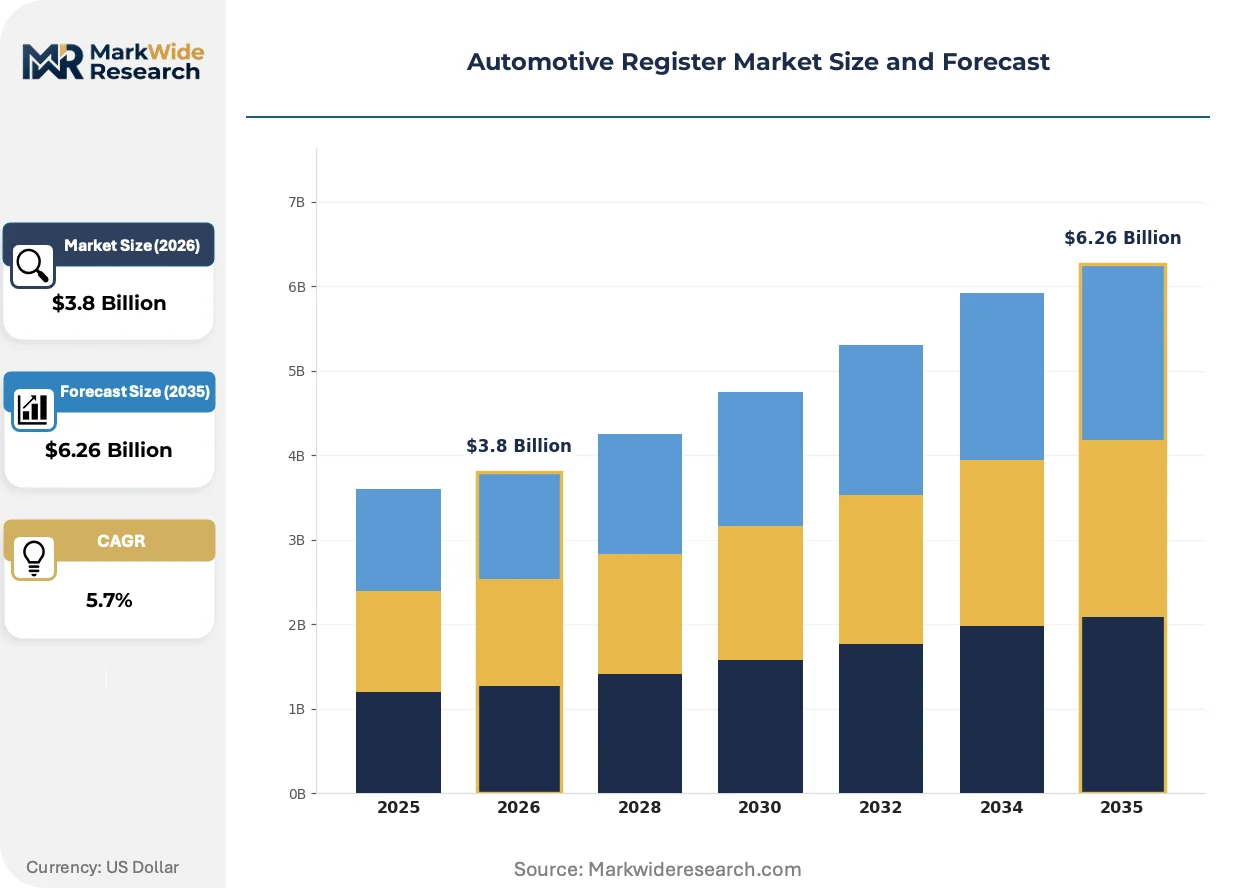
Market Dynamics
Subscription monetization is electrifying automotive register economics, compressing one-time query revenue into recurring vehicle-lifecycle data streams while EU Green Deal mandates force platform modernization investments.
Growth Catalysts
- EU Green Deal:Digital vehicle passport requirements accelerate platform upgrades across European fleet operators, creating mandatory replacement cycles for legacy systems.
- Fleet Telematics Convergence:Connected vehicle data infrastructure enables real-time compliance monitoring, embedding register platforms into operational workflows rather than administrative afterthoughts.
- Germany:OEM-dealer integration mandates establish the continent's most advanced data exchange standards, pulling neighboring markets toward compatible architectures.
Market Restraints
- Secure-Element Hardware Costs:Embedded authentication chips from semiconductor suppliers impose fixed cost floors that resist volume scaling.
- GDPR Data Sovereignty:Cross-border vehicle record portability requirements fragment cloud infrastructure strategies and multiply compliance overhead.
- Legacy System Entrenchment:Decades of paper-based registration records in Eastern European markets create digitization backlogs that delay platform standardization.
Strategic Opportunities
- Predictive Maintenance Integration:Bi-directional data exchange between registers and OEM backends opens service revenue streams beyond compliance.
- Poland and Czech Republic:Underpenetrated fleet markets present first-mover advantages for subscription-based vehicle history platforms.
- API-First Distribution:Insurance underwriters and logistics platforms are emerging as direct procurement channels, bypassing traditional dealer intermediaries.
Industry Challenges
- Embedded Systems Talent Scarcity:Automotive-grade microcontroller programming expertise concentrates at Infineon and Robert Bosch, constraining vendor diversification.
- Multi-Jurisdiction Certification:REACH, CE marking, and EPA requirements demand parallel compliance tracks that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Register Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Platforms, Mobile Applications, Web Portals, Subscription Services Customer Type: Consumers, Dealerships, Repair Shops, Fleet Operators Service Type: Registration Services, Compliance Checks, History Reports, Data Analytics Integration Level: Basic, Advanced, API-enabled, Custom Solutions |
| Companies Covered | Texas Instruments Incorporated, Nexperia, STMicroelectronics, Infineon Technologies, Robert Bosch, ON Semiconductor, Denso, ZF Friedrichshafen, Hyundai Mobis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Register Market Strategic Shifts
Real-time data exchange architectures are displacing static record retrieval as the core value proposition, while regulatory mandates force interoperability investments across previously siloed national systems.
Blockchain-anchored vehicle identity verification is electrifying ownership transfer processes, creating immutable provenance chains that compress title clearance from weeks to hours. German fleet operators are piloting these systems most aggressively, responding to KBA pressure for fraud-resistant documentation. The structural consequence is collapsing intermediary layers between registers, insurers, and financiers.
REACH and RoHS requirements are reshaping hardware component sourcing for connected register terminals, restricting substance use in embedded secure elements. Terminal manufacturers must requalify supply chains under ECHA oversight, extending procurement cycles. Automotive-grade microcontroller vendors are responding with pre-certified component portfolios that accelerate OEM integration timelines.
Usage-based insurance procurement is fragmenting traditional distribution, with commercial fleets demanding direct API access to vehicle history data rather than broker-mediated reports. This disintermediation is most visible in the Netherlands and Belgium, where dense logistics corridors compress risk-assessment windows. Register platforms are responding with tiered data licensing that separates compliance-grade from commercial-grade record packages.
Automotive Register Market Segmentation
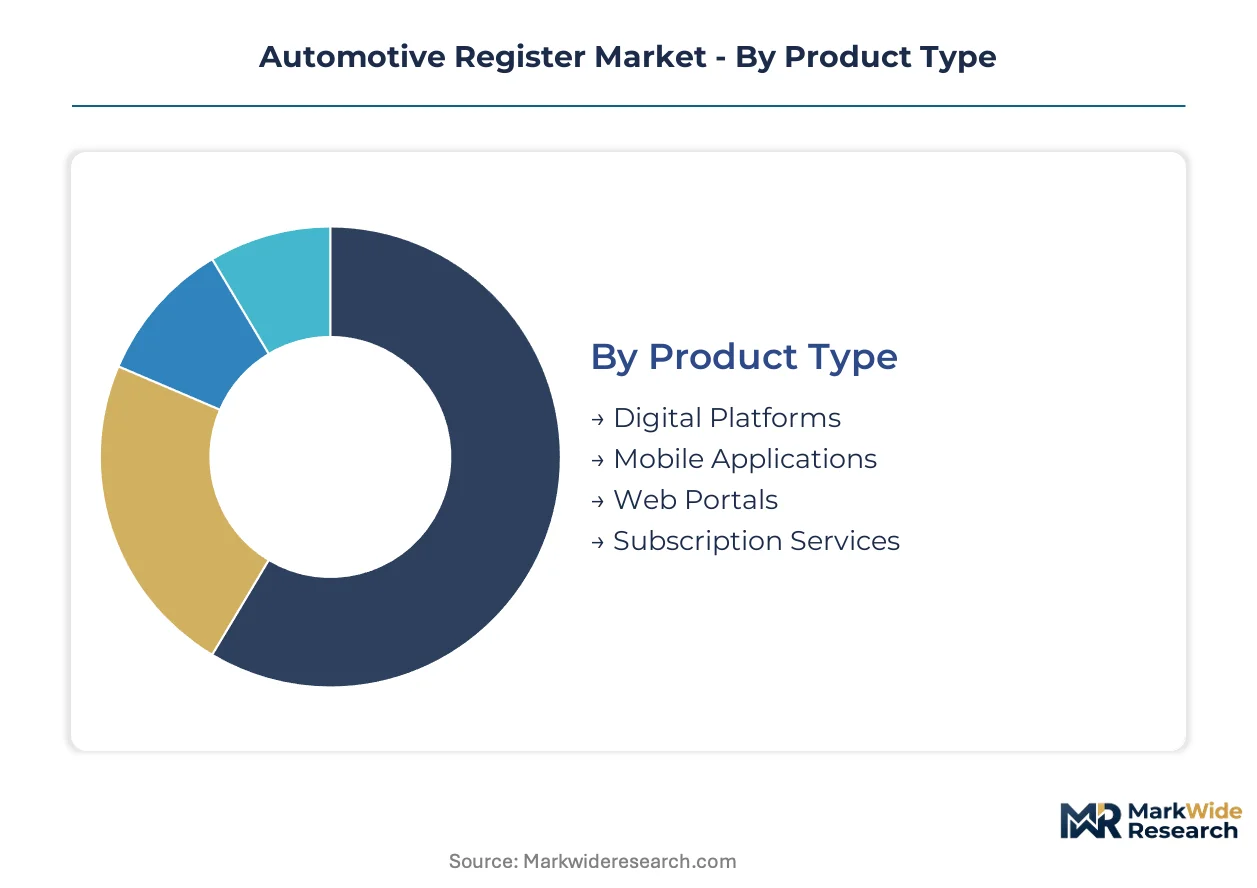
Automotive register platforms monetize through distinct technical architectures and service delivery models. Segmentation reveals where subscription economics displace transactional revenue and which integration depths command premium positioning.
Product Type:
Buyers differentiate by deployment complexity and recurring revenue potential rather than upfront licensing.
- Digital Platforms:Cloud-native architectures with real-time bi-directional data exchange between registers and OEM backends. Fleet operators in Germany concentrate demand here, driven by KBA mandates for digital vehicle passport compliance and encrypted API throughput requirements.
- Subscription Services:Recurring vehicle-lifecycle data streams that compress one-time query revenue into predictable monthly fees. GDPR data sovereignty requirements fragment cloud infrastructure strategies, yet margins deepen through predictive maintenance integrations.
- Mobile Applications:Consumer-facing interfaces with embedded secure-element authentication for ownership transfer verification.
- Web Portals:Browser-based access points for static record retrieval and administrative compliance submissions.
Volume sits with Digital Platforms; growth tilts toward Subscription Services.
Customer Type:
Procurement authority shifts from individual vehicle owners to institutional buyers with fleet-scale data requirements.
- Fleet Operators:Multi-vehicle enterprises demanding real-time compliance monitoring across jurisdictions. EU Green Deal mandates accelerate platform modernization investments, embedding registers into operational workflows rather than administrative afterthoughts.
- Dealerships:OEM-affiliated networks requiring seamless vehicle history integration for trade-in valuation and warranty validation.
- Repair Shops:Service centers accessing compliance status and recall notifications through API-enabled integration layers.
- Consumers:Individual buyers purchasing one-time history reports for used vehicle transactions.
Revenue concentrates with Fleet Operators; margin expansion favors Dealerships through OEM integration mandates.
Service Type:
Value capture depends on data velocity—static reports commoditize while real-time analytics command premium tiers.
- Data Analytics:Predictive algorithms processing telematics feeds for maintenance forecasting and residual value modeling. Insurance underwriters in the Netherlands and Belgium procure direct API access, bypassing broker intermediaries entirely.
- Compliance Checks:Automated verification against REACH, CE marking, and emissions standards. EPA and NHTSA linkages to state registration databases create divergent architecture requirements across markets.
- History Reports:Consolidated ownership and accident documentation for secondary market transactions.
- Registration Services:Title issuance and ownership transfer processing through government database interfaces.
Transaction volume flows through Compliance Checks; value creation accelerates fastest in Data Analytics.
Integration Level:
Technical sophistication determines pricing power—surface-level connectivity underperforms against embedded system architectures.
- API-enabled:Real-time bi-directional data pipelines sustaining sub-second query response requirements. Automotive-grade microcontroller programming expertise concentrates at specialized semiconductor vendors, constraining vendor diversification.
- Custom Solutions:Bespoke implementations for OEM-dealer integration mandates with proprietary encryption layers.
- Advanced:Pre-configured middleware with standardized telematics gateway compatibility.
- Basic:Manual data entry portals with batch processing limitations and minimal automation.
Deployment scale favors API-enabled architectures; pricing premiums attach to Custom Solutions serving German OEM integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of automotive register hardware concentrates in Germany and the United States, while fleet operator demand spreads across Western Europe and North America. Consumption patterns diverge as regulatory mandates drive platform modernization in some markets while legacy system entrenchment delays adoption elsewhere.
Germany
KBA digital vehicle passport requirements and OEM-dealer integration mandates accelerate platform upgrades across fleet operators. The EU Green Deal forces encrypted API throughput investments for real-time compliance monitoring. Stuttgart and Munich anchor the continent's densest concentration of connected vehicle data infrastructure development.
United States
EPA emissions linkages to state registration databases and NHTSA safety recall integration drive divergent compliance architectures across jurisdictions. Fleet telematics convergence embeds register platforms into operational workflows rather than administrative afterthoughts. Michigan and California host the most advanced OEM-backend integration clusters.
Netherlands
Usage-based insurance procurement fragments traditional distribution as commercial fleets demand direct API access to vehicle history data. GDPR data sovereignty requirements fragment cloud infrastructure strategies despite deepening margins through predictive maintenance integrations. The Rotterdam-Antwerp logistics corridor compresses risk-assessment windows for register platforms.
Poland
Underpenetrated fleet markets present first-mover advantages for subscription-based vehicle history platforms entering from Western European neighbors. REACH and RoHS requirements reshape hardware component sourcing for connected register terminals. Warsaw and Krakow emerge as digitization hubs addressing decades of paper-based registration backlogs.
China
MIIT connected vehicle standards and dual carbon goals accelerate domestic platform modernization investments. Automotive-grade microcontroller programming expertise concentrates at specialized semiconductor vendors, constraining vendor diversification. Shanghai and Shenzhen lead development of encrypted data pipelines between registers and OEM backends.
Automotive Register Market Competitive Environment
Capital-heavy semiconductor foundries compete with asset-light systems integrators for margin capture in automotive register value chains. The vendor base organizes around three strategic archetypes: secure-element hardware suppliers anchoring authentication layers, microcontroller specialists sustaining encrypted data pipelines, and integrated telematics-to-register service providers bundling fleet deployments. Consolidation pressures concentrate among semiconductor vendors while systems integration remains fragmented across regional specialists. Dominant competitive moves include strategic partnerships bridging hardware-to-software gaps and portfolio diversification into predictive maintenance adjacencies.
Within the secure-element tier, Texas Instruments Incorporated and Infineon Technologies occupy anchor positions representing divergent approaches to embedded authentication hardware. Robert Bosch exemplifies the integrated systems archetype through bundled telematics-to-register offerings. STMicroelectronics and ON Semiconductor sit within the microcontroller specialization cluster serving encrypted pipeline requirements. Nexperia represents European-based component sourcing strategies responding to REACH and RoHS terminal manufacturing constraints. Denso, ZF Friedrichshafen, and Hyundai Mobis reflect geographic diversification across Japanese, German, and Korean industrial bases respectively.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Nexperia |
| STMicroelectronics |
| Infineon Technologies |
| Robert Bosch |
| ON Semiconductor |
| Denso |
| ZF Friedrichshafen |
| Hyundai Mobis |
| Others |
Value Chain & Pricing Dynamics
Automotive-grade microcontroller programming expertise concentrates in Stuttgart and Munich, where labor-cost differentials between German engineering clusters and Eastern European assembly nodes widen pricing-tier spreads across API-enabled and basic integration levels.
Pricing Analysis
Margin tightening in custom solutions reflects Infineon and Robert Bosch's concentration of embedded systems talent. Three-tier pricing structure across premium, standard, and economy levels separates API-enabled architectures with sub-second response guarantees from batch-processing web portals. Certification-grade compliance checks command premiums over commercial-grade record packages. Fleet operators in Germany show least price sensitivity due to KBA mandate deadlines, while Eastern European repair shops resist subscription migration from one-time query models.
Supply Chain Analysis
Workforce availability for secure-element hardware design concentrates in Germany, the United States, and China, constraining vendor diversification beyond Texas Instruments and STMicroelectronics. Automotive register production draws from semiconductor foundries in Taiwan and South Korea for microcontroller fabrication, with terminal assembly tethered to REACH-compliant component sourcing under ECHA oversight. Single-source vulnerability in automotive-grade secure-element chips fragments cloud infrastructure strategies. Distribution runs through OEM-dealer integration mandates and direct API licensing to insurance underwriters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive register markets operate under supply-constrained conditions where embedded systems talent scarcity props pricing power for incumbent semiconductor vendors.
For Market Incumbents: Anticipate margin compression from API-first distribution channels disintermediating traditional dealer networks. Defensive consolidation through backward integration into predictive maintenance software stacks counters asset-light systems integrators. Capacity addition in Polish digitization hubs addresses Eastern European backlog demand before first-mover entrants establish subscription platforms. For New Entrants and Emerging Players: Commercial fleets in the Netherlands and Belgium present underserved buyer archetypes demanding direct API access for usage-based insurance procurement. White-space concentration sits with underpenetrated Polish and Czech Republic fleet markets where paper-based registration backlogs delay incumbent platform standardization. Go-to-market execution through logistics corridor partnerships bypasses legacy dealer channel entrenchment. For Investors and Strategic Acquirers: Re-rating potential sits with integrated telematics-to-register service providers given EU Green Deal acceleration of digital vehicle passport mandates. Long-term viability favors vendors bundling encrypted data pipelines with OEM-backend integration capabilities. Acquisition target archetypes include regional systems integrators with KBA-compliant certification pathways. Watch for inflection signals in German fleet operator pilot programs for blockchain-anchored vehicle identity verification.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Direct data licensing to insurance underwriters in the Netherlands compresses broker-mediated distribution layers. |
| Predictive Maintenance Integration | Bi-directional OEM backend data exchange deepens subscription margins beyond compliance-check commoditization. |
| Blockchain Identity Verification | German KBA pilot programs for fraud-resistant documentation collapse title clearance timelines from weeks to hours. |
| Eastern European Market Entry | Polish and Czech fleet digitization backlogs create first-mover subscription platform advantages. |
| REACH-Compliant Hardware Sourcing | ECHA oversight of secure-element substance restrictions extends procurement cycles for terminal manufacturers. |
Study Parameters
Document review covered vehicle production databases, IHS Markit registration data, EU regulatory filings, and semiconductor vendor disclosures, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations directors, and automotive aftermarket distributors. Secondary validation drew from KBA technical standards, EPA emissions linkage documentation, and GDPR cross-border portability guidance. Bottom-up segment sizing triangulated against top-down macroeconomic anchors across the analysis window.
Historical volume trajectories cross-referenced against expert panel inputs on EU Green Deal implementation timelines and fleet telematics convergence rates. Segmentation dimensions modeled include integration level, service type, customer archetype, and regional regulatory cluster. CAGRs derived from slope-intercept analysis of subscription monetization curves and compliance mandate acceleration patterns. Industry-specific inputs encompassed encrypted API throughput requirements and embedded secure-element cost floors.
Revisions become necessary when GDPR data sovereignty rulings fragment cloud infrastructure strategies, REACH substance restrictions reshape hardware sourcing, or legacy system entrenchment in Eastern European markets delays platform standardization beyond projected timelines. Forecasts reflect documented assumptions on OEM-dealer integration mandate compliance schedules and semiconductor foundry capacity allocation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Global Cars-As-A-Service (CaaS) Market
Automotive Services
Global Street Sweeper Market
Automotive Services
Brushless Car Wash Machine Market
Automotive Services
Driver's License Market
Automotive Services
Tow Truck Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
US Car Wash Services Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
US Quick Lube Equipment Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
Car Washing Service Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Luxury Car Rental Market