
 North America MRO Distribution Market | 2026-2036
North America MRO Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
North America MRO Distribution Market Intelligence
Mid-sized independent manufacturers is unwinding the historical dominance of large OEM captive buyers in MRO procurement. W.W. Grainger leverages its branch network density to serve this shifting base with same-day fulfillment. MRC Global anchors its position through deep inventory of pipe, valve, and fitting categories for energy sector accounts. Fastenal Company differentiates by embedding vending machines directly on factory floors, capturing recurring spend from decentralized maintenance budgets.
North America MRO distribution encompasses the procurement, warehousing, and logistics of replacement parts, consumables, and equipment used to maintain operational continuity of industrial assets, typically involving SKUs ranging from standard fasteners to application-specific electrical components with same-day or scheduled delivery parameters. The product type dimension shows electrical supplies commanding premium margin pools due to code-compliance complexity and contractor dependency, while safety equipment experiences accelerated specification turnover as ANSI standards evolve. End user segmentation reveals aerospace and automotive buyers consolidating vendor lists under long-term managed inventory agreements, shifting margin capture toward service-type value adds rather than pure product resale.
OSHA workplace safety mandates, EPA hazardous material handling requirements, and FAA repair station documentation standards for aerospace buyers collectively elevate compliance documentation burdens that favor distributors with certified quality systems and traceable supply chains. NHTSA guidelines for automotive supplier facilities further tighten specification adherence, pushing smaller distributors toward partnership or exit. Stakeholders must monitor how Buy American provisions and potential tariff adjustments reshape sourcing economics for imported electrical and fastener categories.
Market Dynamics
Mid-sized independent manufacturers are consolidating vendor relationships away from large OEM captive buyers, compressing the addressable base for traditional distribution while elevating service-level expectations around same-day fulfillment and technical support.
Growth Catalysts
- Predictive maintenance programs:Manufacturing plants across the Midwest and Southeast are expanding sensor-based asset monitoring, creating recurring demand for diagnostic equipment and replacement components.
- OSHA workplace safety mandates:Tightening compliance requirements for industrial buyers elevate specification standards for personal protective equipment and safety systems, favoring certified distributors.
- Petrochemical cluster concentration:Texas, Ohio, and Michigan drive bulk purchasing volumes through dense automotive and energy sector maintenance operations.
Market Restraints
- Steel and copper price volatility:Raw material input swings compress margin pools for electrical supplies and fastener categories with long inventory cycles.
- Buy American sourcing requirements:Domestic content mandates for federal procurement limit import flexibility for electrical and fastener SKUs, raising landed costs.
- Skilled technician shortage:Retiring maintenance workforces in automotive and aerospace facilities delay repair timelines and dampen parts consumption velocity.
Strategic Opportunities
- Mexico nearshoring expansion:Automotive and electronics manufacturers relocating production to Baja California and Querétaro create greenfield MRO infrastructure demand.
- Vending machine channel penetration:Point-of-use inventory systems embedded directly on factory floors capture decentralized maintenance budgets before they aggregate.
- IRA clean energy incentives:Tax credits for domestic manufacturing facility upgrades accelerate capital equipment replacement cycles and associated consumables demand.
Industry Challenges
- Traceability system integration:FAA repair station documentation standards for aerospace buyers require ERP upgrades that strain mid-sized distributor IT budgets.
- Multi-site inventory harmonization:Buyers consolidating vendor lists under managed inventory agreements demand real-time visibility across fragmented supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America MRO Distribution Market |
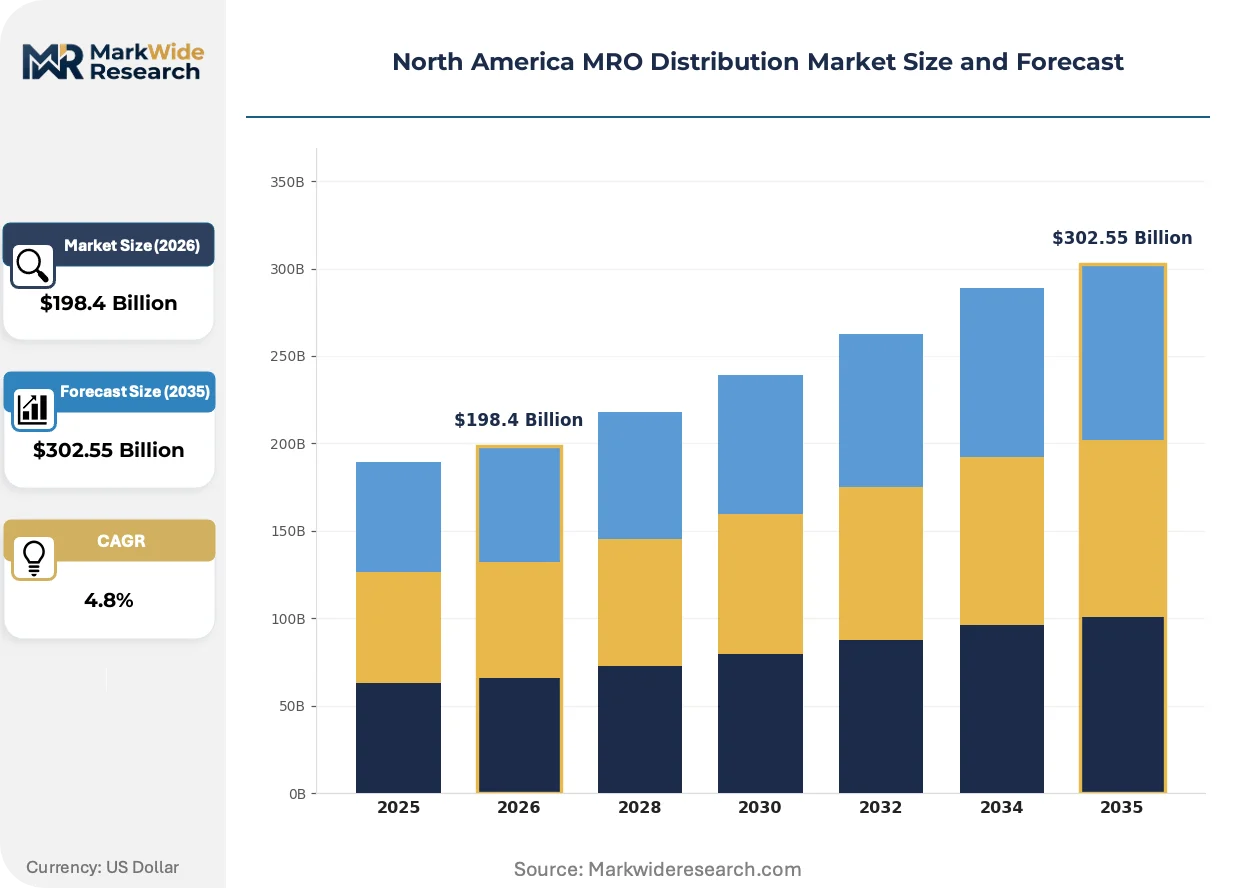
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $302.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tools, Fasteners, Safety Equipment, Electrical Supplies End User: Manufacturing, Aerospace, Automotive, Construction Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers Service Type: Inventory Management, Delivery Services, Technical Support, Repair Services |
| Companies Covered | Rexel (North America), MRC Global, Wesco International, Fastenal Company, DXP Enterprises, Sonepar (North America), ADI Global Distribution, MSC Industrial Direct, W.W. Grainger, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America MRO Distribution Market Strategic Shifts & Innovations
Digital inventory management and embedded fulfillment systems are compressing traditional branch-based distribution models. Three developments warrant particular attention.
Industrial IoT sensor networks are miniaturizing condition monitoring hardware for deployment on legacy equipment without retrofit downtime. Automotive and petrochemical facilities in Michigan and Texas are adopting these systems at accelerating rates. The technology is miniaturizing the addressable market for preventive maintenance schedules while expanding the installed base for predictive analytics subscriptions.
EPA hazardous waste disposal rules are tightening cradle-to-grave documentation requirements for chemical consumables and contaminated PPE. Industrial buyers now face audit exposure for improper chain-of-custody records. Electrical supplies and solvent-based maintenance products face the steepest compliance burden, pushing smaller distributors toward certified quality system investments or partnership exits.
Maintenance budget decentralization is fragmenting purchasing authority from centralized procurement offices to individual plant managers and line supervisors. Vendor-managed inventory agreements and consignment stocking arrangements are displacing traditional purchase-order workflows in automotive and aerospace facilities. This pattern concentrates in Ohio and Southeast manufacturing corridors where multi-site operators seek to reduce administrative overhead.
North America MRO Distribution Market Segmentation
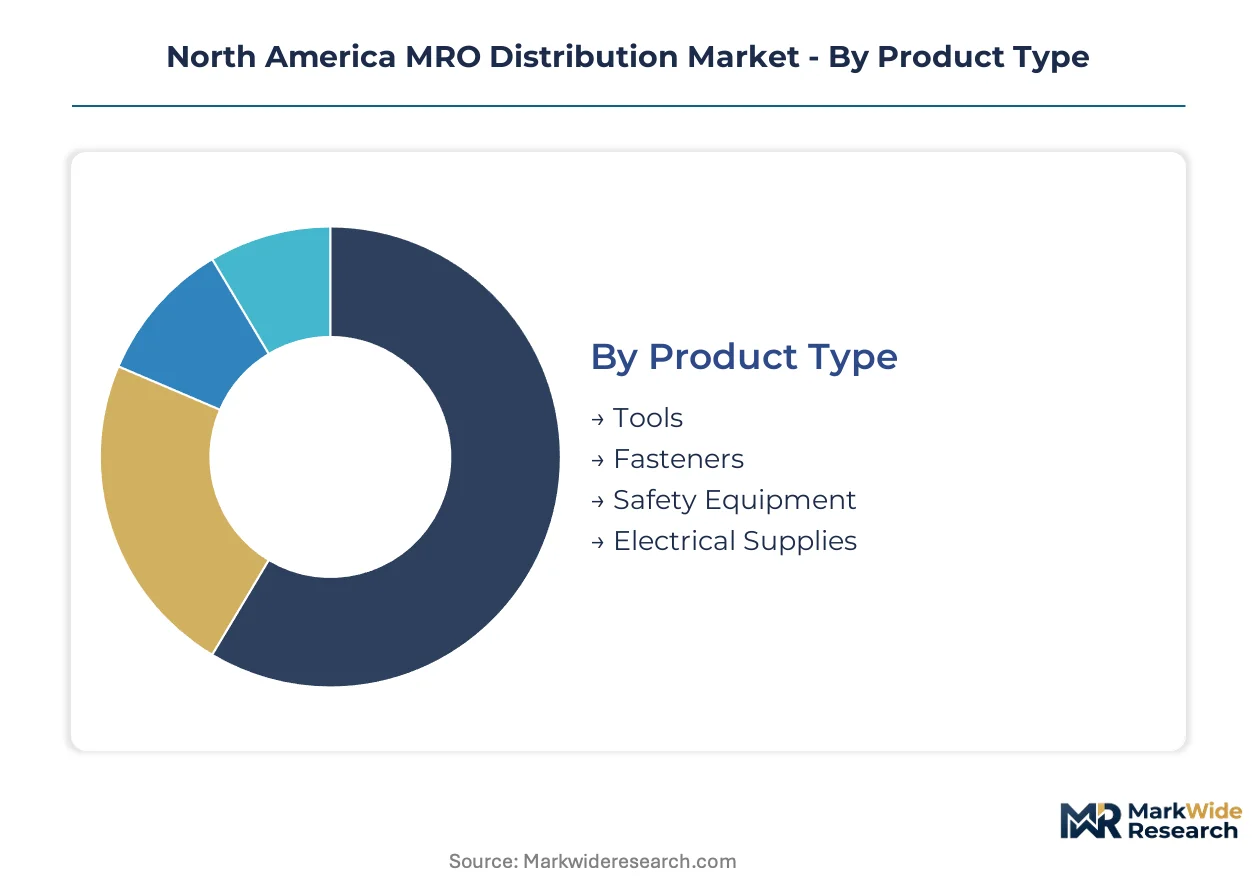
MRO procurement patterns diverge sharply across product categories and buyer profiles. Electrical supplies and safety equipment command premium positioning through regulatory complexity, while channel selection increasingly separates transactional from relationship-driven accounts.
Product Type:
Margin pools concentrate in categories where code compliance and specification expertise create defensible positioning against commodity competition.
- Electrical Supplies:Circuit breakers, conduit systems, and industrial wiring carry NEC code-compliance burdens that favor distributors with certified technical staff. Demand clusters in Texas petrochemical corridors and Michigan automotive plants where 24-hour emergency replacement cycles are standard.
- Safety Equipment:ANSI-rated PPE, fall protection, and respiratory systems face accelerated specification turnover as OSHA updates exposure limits. Automotive facilities in Ohio and Southeast assembly plants drive volume through mandated refresh cycles.
- Fasteners:Standard and application-specific threaded hardware serves high-velocity replacement needs across discrete manufacturing.
- Tools:Hand tools, power equipment, and precision measurement instruments support both preventive and corrective maintenance workflows.
Electrical supplies hold installed capacity. Safety equipment is rotating up the share rankings.
End User:
Application requirements dictate service-level expectations and contract structures across buyer verticals.
- Manufacturing:Discrete and process manufacturers maintain the broadest SKU diversity with highest order frequency. Midwest metalworking and Southeast food processing facilities consolidate vendor lists under multi-year managed inventory agreements.
- Automotive:Tier suppliers and final assembly plants impose traceability mandates that strain distributor quality systems. Michigan and Ohio OEM networks drive specification-heavy procurement with zero-defect delivery requirements.
- Aerospace:FAA repair station documentation standards require lot-level traceability for fasteners and electrical components.
- Construction:Project-based demand concentrates in commercial and infrastructure buildouts with seasonal volume spikes.
Manufacturing anchors volume throughput. Automotive is climbing the fastest on technical service intensity.
Distribution Channel:
Channel economics separate inventory-carrying intermediaries from platform-based and direct models.
- Distributors:Branch networks with local inventory and counter service dominate same-day fulfillment for unplanned maintenance. Texas and Ohio markets show highest branch density concentration.
- Online Retail:Digital platforms capture planned, low-urgency procurement with transparent pricing and consolidated shipping.
- Direct Sales:Manufacturer-direct relationships serve large accounts with dedicated contract terms and custom stocking.
- Wholesalers:Bulk aggregation models supply smaller distributors and independent repair shops with extended payment terms.
Distributors maintain field presence. Online retail is gaining share fastest on procurement decentralization.
Service Type:
Value capture is migrating from product resale toward embedded service capabilities that reduce buyer administrative burden.
- Inventory Management:Vendor-managed stocking and consignment arrangements transfer carrying cost risk from buyer to distributor. Aerospace and automotive facilities in Ohio and Michigan lead adoption of real-time consumption tracking.
- Technical Support:On-site specification assistance and code interpretation services defend margin in electrical and safety categories.
- Delivery Services:Scheduled and emergency logistics tiers segment customers by downtime cost sensitivity.
- Repair Services:Tool refurbishment and equipment calibration extend distributor relationships beyond initial sale.
Inventory management holds contract value. Technical support is expanding most quickly on compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial MRO procurement concentrates in manufacturing corridors where petrochemical, automotive, and aerospace clusters generate dense maintenance demand. The EPA and OSHA compliance frameworks create uneven distributor penetration across sub-regional markets. Three countries anchor North American throughput with distinct regulatory and industrial profiles.
United States
Texas petrochemical corridors and Michigan automotive plants drive bulk electrical and fastener consumption through 24-hour emergency replacement cycles. OSHA workplace safety mandates and EPA hazardous waste disposal rules tighten documentation requirements for industrial buyers. Ohio and Southeast manufacturing facilities consolidate vendor lists under managed inventory agreements to reduce administrative overhead.
Canada
Ontario automotive assembly and Alberta energy extraction operations sustain steady demand for safety equipment and pipe-valve-fitting categories. Health Canada and provincial occupational health regulators enforce PPE specification standards that favor certified distributors with traceable supply chains. British Columbia mining and Pacific Northwest cross-border manufacturing clusters generate specialized tool and consumables procurement.
Mexico
Baja California and Querétaro automotive nearshoring expansion creates greenfield MRO infrastructure demand for tier suppliers relocating from US Midwest facilities. Mexican federal labor law and PROFEPA environmental enforcement elevate compliance documentation burdens for cross-border distributors. Northern border states and Mexico City metro manufacturing zones concentrate procurement authority among large multinational accounts with centralized purchasing.
North America MRO Distribution Market Key Industry Players
Concentration sits with diversified industrial distributors operating dense branch networks and captive supply relationships with energy and manufacturing accounts. The vendor base separates into three functional tiers: national full-line distributors with same-day fulfillment capabilities, specialty category players anchoring specific product verticals, and regional independents serving localized repair shops. Strategic moves center on vending machine channel penetration for point-of-use inventory capture and vendor-managed inventory agreements that transfer carrying cost risk.
Within the national distributor tier, W.W. Grainger and Fastenal Company exemplify divergent fulfillment architectures. Grainger leverages branch network density for emergency replacement cycles in Texas and Ohio manufacturing corridors. Fastenal embeds vending machines directly on factory floors to capture decentralized maintenance budgets. MRC Global occupies a position as energy sector specialist with deep pipe-valve-fitting inventory for petrochemical accounts.
| Leading Market Players |
|---|
| Rexel (North America) |
| MRC Global |
| Wesco International |
| Fastenal Company |
| DXP Enterprises |
| Sonepar (North America) |
| ADI Global Distribution |
| MSC Industrial Direct |
| W.W. Grainger |
| Others |
Cost & Logistics Intelligence
Scale economies in branch network density shape both supply concentration and price floors across the North America MRO Distribution Market. Dense inventory positioning in Texas and Ohio manufacturing corridors allows large distributors to absorb carrying costs that compress margins for regional independents serving lower-volume accounts.
Pricing Analysis
Volume-discount tiering structures separate national account pricing from spot-buy premiums and consignment arrangements. Three-tier pricing stratifies across premium certified-grade electrical supplies, standard industrial fasteners, and economy maintenance consumables. Price differentiation hinges on ANSI certification level and same-day delivery radius. Cost compression in economy-tier consumables is intensifying because steel and copper volatility erodes inventory turns. Small independent repair shops exhibit highest price sensitivity, while aerospace facilities with FAA traceability mandates accept premium positioning.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive and aerospace facilities seeking to minimize working capital, while strategic stockpiling persists in petrochemical corridors where unplanned downtime costs dwarf carrying expenses. Geographic supply concentration draws from China for standard fasteners, Mexico for nearshored electrical assemblies, and domestic mills for steel conduit and copper wiring. Raw material dependencies rest on steel coil, copper cathode, and engineered plastics. Single-source vulnerability concentrates in specialized electrical components with UL certification requirements. Distribution runs through branch-based intermediaries with local counter service and vending machine point-of-use systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping the North America MRO Distribution Market as vendor-managed inventory agreements and embedded vending systems transform transactional procurement into recurring-revenue ecosystems. Interoperability between distributor ERP systems and buyer asset management platforms is becoming the decisive competitive moat.
For Market Incumbents: Secure branch network density in Michigan and Ohio automotive corridors against encroachment from digital-native distributors. Defend same-day fulfillment capabilities through strategic inventory positioning near Tier 1 supplier clusters. Vertical integration into certified electrical testing services counters margin erosion from commodity fastener categories.
For New Entrants and Emerging Players: OSHA compliance certification fast-tracks open pathways into safety equipment procurement at mid-sized manufacturers unwinding from large OEM captive programs. White-space targets concentrate in Mexico nearshoring zones where greenfield facilities lack established MRO relationships. Embedded vending machine partnerships with plant engineering teams bypass entrenched procurement gatekeepers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among distributors with vendor-managed inventory penetration above thirty percent of account portfolios. Long-term viability favors specialists with traceable supply chains serving aerospace and automotive verticals. Acquisition targets should demonstrate ERP integration capabilities with buyer predictive maintenance platforms. The signal to watch is consolidation velocity among mid-sized independents facing FAA documentation standard upgrades.
| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Use Vending Expansion | Captures decentralized maintenance budgets before aggregation into centralized procurement. |
| Vendor-Managed Inventory Agreements | Transfers carrying cost risk from automotive buyers to distributors with real-time consumption tracking. |
| Certified Quality System Investment | Meets FAA repair station documentation standards for aerospace fastener and electrical component traceability. |
| Mexico Nearshoring Infrastructure Buildout | Serves tier suppliers relocating from US Midwest to Baja California and Querétaro corridors. |
| Predictive Maintenance Platform Integration | Aligns distributor ERP systems with buyer Industrial IoT sensor networks for automated replenishment. |
Research Approach
Findings reconcile primary fieldwork against secondary review of distributor financial disclosures, EPA enforcement records, and OSHA compliance databases. Interviews with maintenance directors at automotive assembly plants, procurement leads at petrochemical facilities, branch operations managers, and aftermarket service heads informed demand-side validation. Secondary sources include customs trade data, SEC 10-K filings, and industry association procurement surveys. Bottom-up SKU-level demand modeling triangulates against top-down regional manufacturing output indices.
Segmentation dimensions modeled span product type, end-user vertical, distribution channel, and service type across the projection horizon. The analytical framework incorporates electrical supplies, safety equipment, fasteners, and tools with manufacturing, automotive, aerospace, and construction buyer segments. CAGRs derive from regression analysis against industrial production indices and capital expenditure cycles. Forecast inputs include sensor-based predictive maintenance adoption rates and IRA clean energy facility upgrade tax credit utilization.
Decision-makers should treat outputs as directional under assumptions of steady OSHA and EPA regulatory enforcement; material deviation would warrant model refresh. Forecasts embed assumptions regarding steel and copper price stability and continued automotive nearshoring momentum. Practitioners should keep alternative scenarios live as Buy American sourcing requirements and tariff adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
France Car Rental Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Driverless Sweeper Market
Automotive Services
Electric Vehicle Repair Service Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Airbag Repair Service Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
Automotive Register Market
Automotive Services
Driver's License Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
GCC Car Rental Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Car Wash System Market
Automotive Services
Car Wash Services Market