
 Tow Truck Market | 2026-2036
Tow Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Tow Truck Market Analysis
Certified heavy-duty diesel technician availability is collapsing across North American fleet maintenance networks, constraining fleet expansion timelines for operators serving interstate corridors. Miller Industries leverages in-house boom fabrication to sustain its position in rotator manufacturing for extreme recovery applications. FleetNet America competes through proprietary dispatch software that anchors its contracted maintenance network across southeastern states. Kelly Mobile Services specializes in urban light-duty response, occupying dense metropolitan zones where parking enforcement generates recurring call volume.
A tow truck is a motorized recovery vehicle engineered with hydraulic boom, wheel-lift, or flatbed mechanisms rated by gross vehicle weight capacity, designed to transport disabled, impounded, or collision-damaged vehicles from roadways to repair facilities or impound lots. Light-duty units dominate unit sales volume due to proliferation in urban roadside assistance contracts, while heavy-duty configurations command concentrated margin pools tied to commercial trucking recovery and industrial accident response. Emergency towing services generate the most predictable revenue streams through municipal and insurance contracts, whereas vehicle transport segments face margin pressure from digital broker platforms that disintermediate traditional dispatch relationships.
NHTSA Federal Motor Vehicle Safety Standards govern towing equipment lighting and conspicuity requirements, while EPA Tier 4 emissions regulations shape powertrain procurement decisions for fleet renewal cycles. OSHA workplace safety directives affect operator training protocols and hydraulic system maintenance schedules, particularly for heavy-duty recovery scenarios involving overturned commercial vehicles. Stakeholders must monitor electrification readiness across charging infrastructure corridors, as battery-electric tow truck deployments will require redefined payload calculations and range specifications for viable fleet economics.
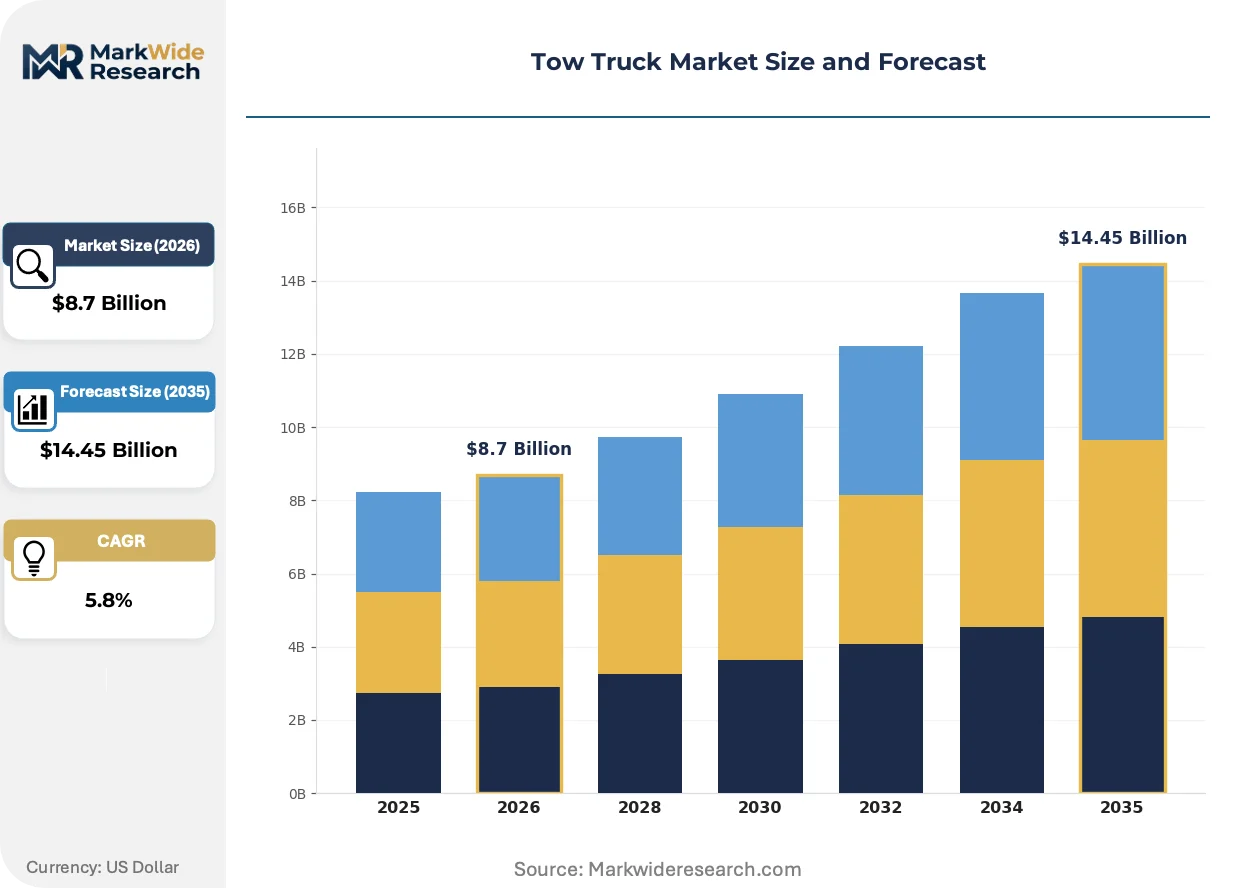
Market Dynamics
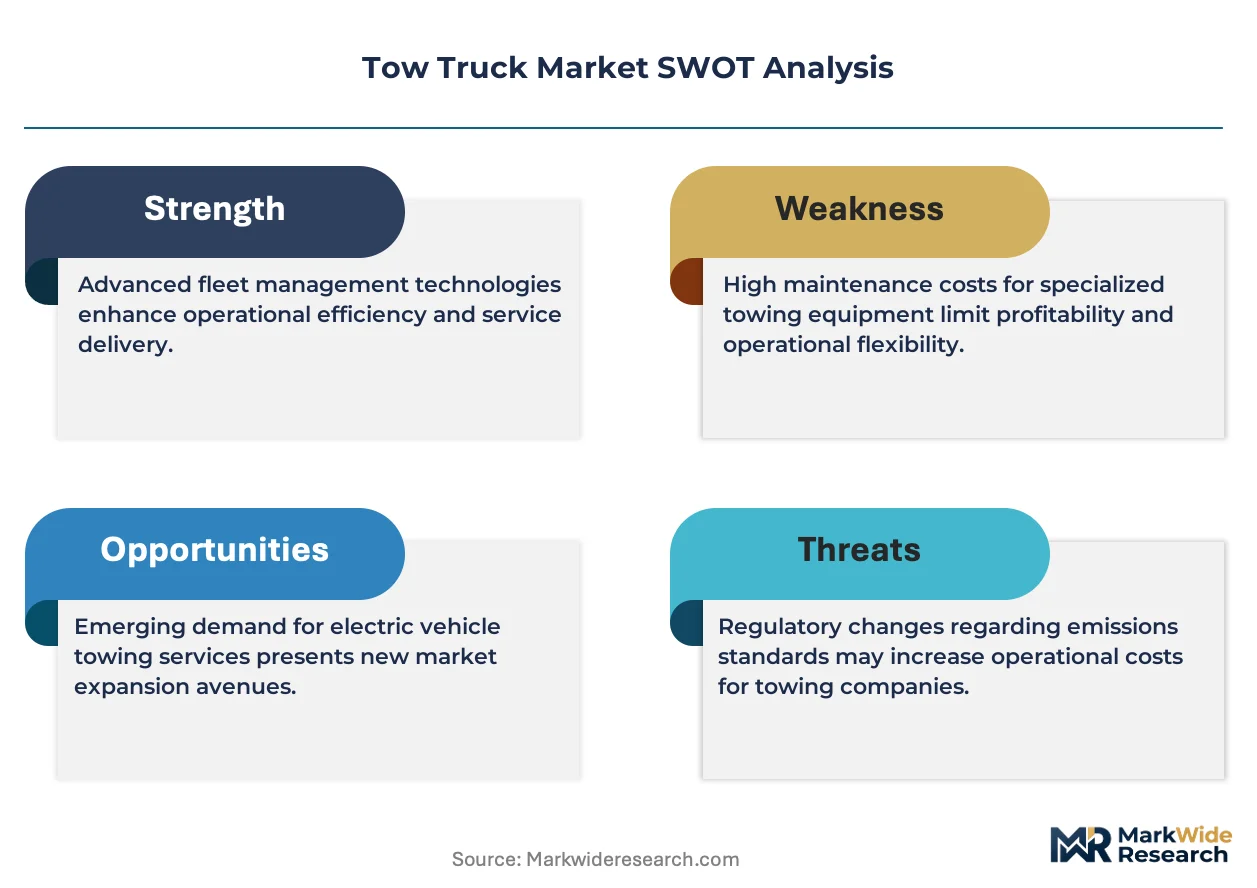
Fleet electrification mandates and EPA Tier 4 emissions compliance are forcing capital-intensive powertrain transitions across municipal and commercial towing operators, compressing replacement cycles and redrawing competitive positioning around charging infrastructure access.
Growth Catalysts
- Urban traffic management contracts:Municipal fleet operators in Sun Belt metropolitan corridors are expanding contracted towing services to manage congestion and incident response, creating predictable revenue streams for operators with dispatch software integration.
- Insurance carrier roadside assistance networks:Property and casualty insurers are consolidating preferred provider networks for policyholder roadside assistance, concentrating volume with operators capable of sub-30-minute response time guarantees.
- Heavy-duty recovery specialization:Commercial trucking density along interstate freight corridors sustains demand for rotator-equipped units rated above 50-ton capacity, anchoring margin pools in extreme recovery applications.
Market Restraints
- Diesel technician scarcity:Certified heavy-duty diesel technician availability is collapsing across North American fleet maintenance networks, constraining fleet expansion timelines for operators serving interstate corridors.
- Steel and hydraulic component volatility:Boom fabrication and winch system input costs fluctuate with commodity pricing, pressuring gross margins for manufacturers without captive supply of fabricated assemblies.
- Battery-electric payload penalties:Current battery-electric chassis configurations reduce effective towing capacity by 15-20% versus comparable diesel platforms, limiting viable deployment to light-duty urban routes.
Strategic Opportunities
- Charging corridor infrastructure:Interstate charging network buildout along I-10, I-35, and I-95 corridors creates positioning windows for operators to establish electrified heavy-duty recovery capabilities ahead of fleet turnover.
- Telematics-integrated dispatch platforms:Real-time vehicle location and diagnostic data streams enable predictive dispatch models that compress response times and improve asset utilization rates.
- OSHA heavy-lift certification programs:Specialized operator training for overturned commercial vehicle recovery commands premium pricing and creates defensible contracting positions with industrial clients.
Industry Challenges
- Hydraulic system maintenance specialization:Boom and wheel-lift mechanism overhaul requires tooling and expertise distinct from standard automotive repair, creating technician recruitment friction for expanding operators.
- NHTSA lighting compliance timelines:Conspicuity and illumination standard updates require retrofit or replacement of existing fleet units, compressing cash flow for smaller operators with aged equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tow Truck Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Vehicles, Commercial Trucks, Motorcycles, Vans Service Type: Emergency Towing, Non-Emergency Towing, Recovery Services, Vehicle Transport Capacity: Light-Duty, Medium-Duty, Heavy-Duty, Super-Duty End User: Roadside Assistance Companies, Fleet Operators, Repair Shops, Private Individuals |
| Companies Covered | Mercer Transportation, Kelly Mobile Services, Miller Industries, Bear Flag Towing, Platinum Transportation Solutions, FleetNet America, Bokum Logistics, Express Towing Extreme Towing, Anaheim Fullerton Towing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tow Truck Market Emerging Trajectories
Digital broker platforms are disintermediating traditional dispatch relationships in vehicle transport segments while electrification and automation reshape equipment specifications and operator skill requirements.
Modular boom architectures are decomposing the traditional integrated chassis-manufacturer relationship. Fleet operators in Texas and Florida are specifying boom assemblies separately from chassis platforms, enabling mixed-vendor configurations that optimize payload ratings against route requirements. This decomposition is compressing margins for full-system manufacturers while expanding addressable market for specialized fabricators.
EPA Tier 4 Final emissions regulations are accelerating diesel aftertreatment complexity. Fleet procurement committees now weight total cost of ownership over acquisition price, extending replacement cycles for pre-2021 equipment and concentrating new-unit demand with financing-capable dealers. Heavy-duty configurations face the steepest compliance cost escalation, favoring operators with scale to amortize aftertreatment maintenance infrastructure.
Insurance carriers are unbundling roadside assistance from core auto policies. Progressive and State Farm policyholders increasingly select towing coverage à la carte, fragmenting demand across digital-native dispatch platforms that compete on price transparency rather than relationship depth. This shift is most visible in California and Arizona, where smartphone-native driver populations exhibit low brand loyalty to traditional motor club memberships.
Tow Truck Market Segmentation
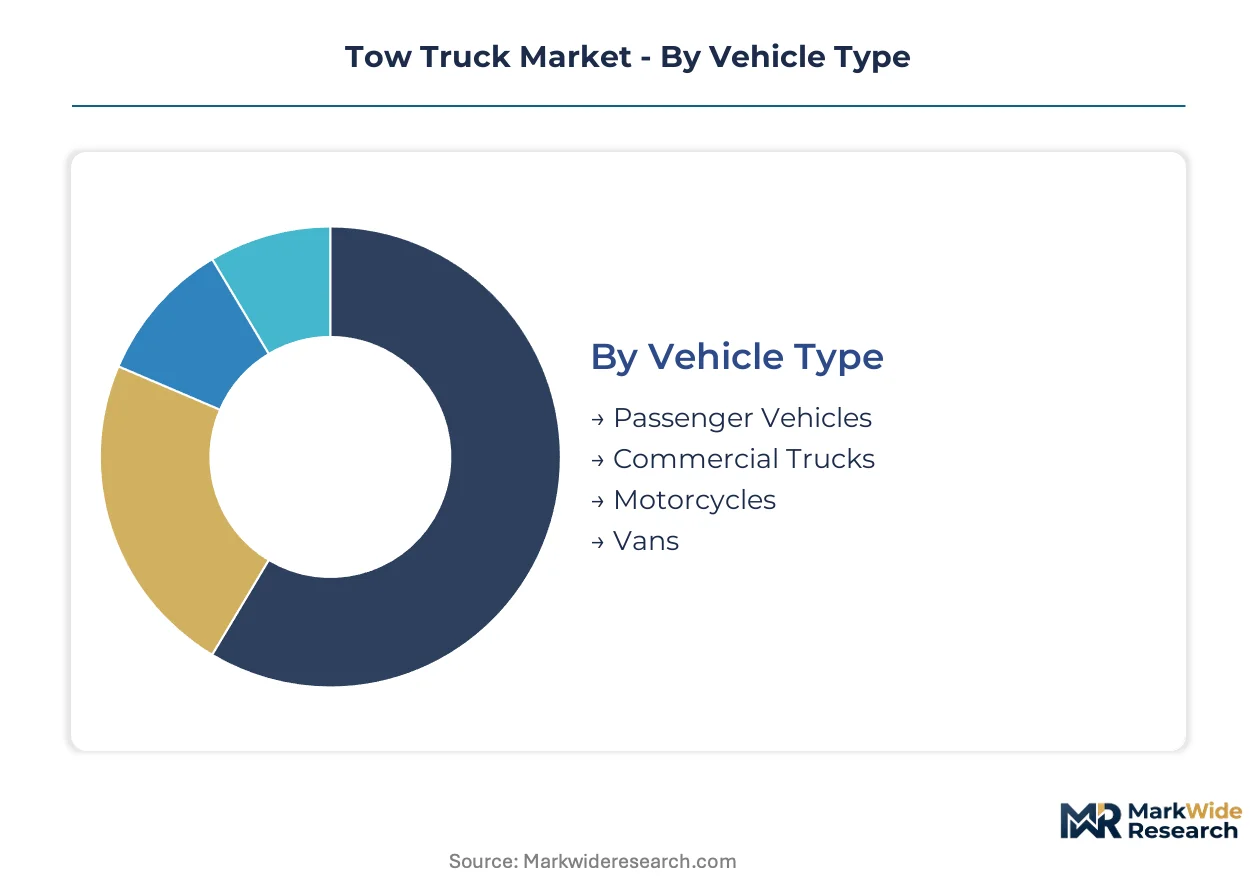
Tow truck market segmentation reveals distinct equipment specifications, service economics, and customer procurement patterns that shape manufacturer product development and operator fleet composition. Understanding these dimensional splits enables stakeholders to align capacity investments with revenue concentration points across emergency response, commercial recovery, and logistics transport verticals.
Vehicle Type:
Channel flow varies sharply by vehicle category, with passenger vehicle incidents driving volume through insurance-preferred networks while commercial truck recoveries route through specialized heavy-duty operators with direct fleet contracts.
- Passenger Vehicles:Sedans, SUVs, and light trucks constitute the highest incident frequency segment, with demand concentrating in Sun Belt metropolitan corridors where parking enforcement and collision response generate recurring call volume through municipal and insurance contracts.
- Commercial Trucks:Class 8 tractors and box trucks require rotator-equipped recovery units rated above 25-ton capacity, with demand anchoring along I-10, I-35, and I-95 freight corridors where density sustains premium pricing for extreme recovery applications.
- Motorcycles:Two-wheeled transport demands specialized flatbed or cradle configurations to prevent drivetrain damage, with call volume clustering in urban zones and recreational riding corridors.
- Vans:Commercial and passenger van configurations occupy a mid-weight recovery niche, frequently handled by light-duty wheel-lift units in urban roadside assistance networks.
Passenger vehicles dominate installed base. Commercial trucks represent where expansion concentrates for margin-focused operators.
Service Type:
Cost tier differentiation separates emergency response premiums from commoditized transport segments, with contract structure and response time guarantees determining profitability rather than equipment specification alone.
- Emergency Towing:Police-initiated and accident-scene clearance commands immediate dispatch priority, with municipal contracts in Texas and Florida metropolitan areas providing predictable revenue streams for operators with sub-30-minute response capabilities.
- Non-Emergency Towing:Mechanical failure and flat tire assistance carries lower per-incident revenue but higher volume throughput, with insurance carrier roadside assistance networks consolidating preferred providers around digital dispatch integration.
- Recovery Services:Overturned commercial vehicles and off-road extrication demands specialized operator certification and hydraulic boom capacity, with OSHA heavy-lift training creating defensible contracting positions with industrial clients.
- Vehicle Transport:Dealer transfers and relocation logistics face margin compression from digital broker platforms that disintermediate traditional dispatch relationships, particularly visible in California and Arizona markets.
Emergency towing anchors contracted revenue stability. Recovery services deliver the steepest expansion trajectory for specialized operators.
Capacity:
Application requirements dictate chassis specification, with urban route constraints and interstate corridor demands creating divergent fleet composition strategies across operator scale tiers.
- Light-Duty:Units rated below 10,000 lbs GVWR handle standard passenger vehicle recovery, proliferating in dense metropolitan zones where parking enforcement and roadside assistance contracts sustain high unit deployment.
- Medium-Duty:10,000-26,000 lbs capacity bridges passenger and commercial applications, with demand concentrating among independent operators serving mixed suburban and exurban territories.
- Heavy-Duty:Configurations above 26,000 lbs GVWR with integrated boom fabrication address commercial trucking recovery, with Miller Industries and specialized fabricators competing for rotator manufacturing in extreme recovery segments.
- Super-Duty:50-ton plus capacity units serve industrial accident response and multi-vehicle pile-up scenarios, with procurement limited to operators with scale to amortize specialized maintenance infrastructure.
Light-duty units saturate urban markets. Heavy-duty configurations concentrate margin expansion for corridor-serving fleets.
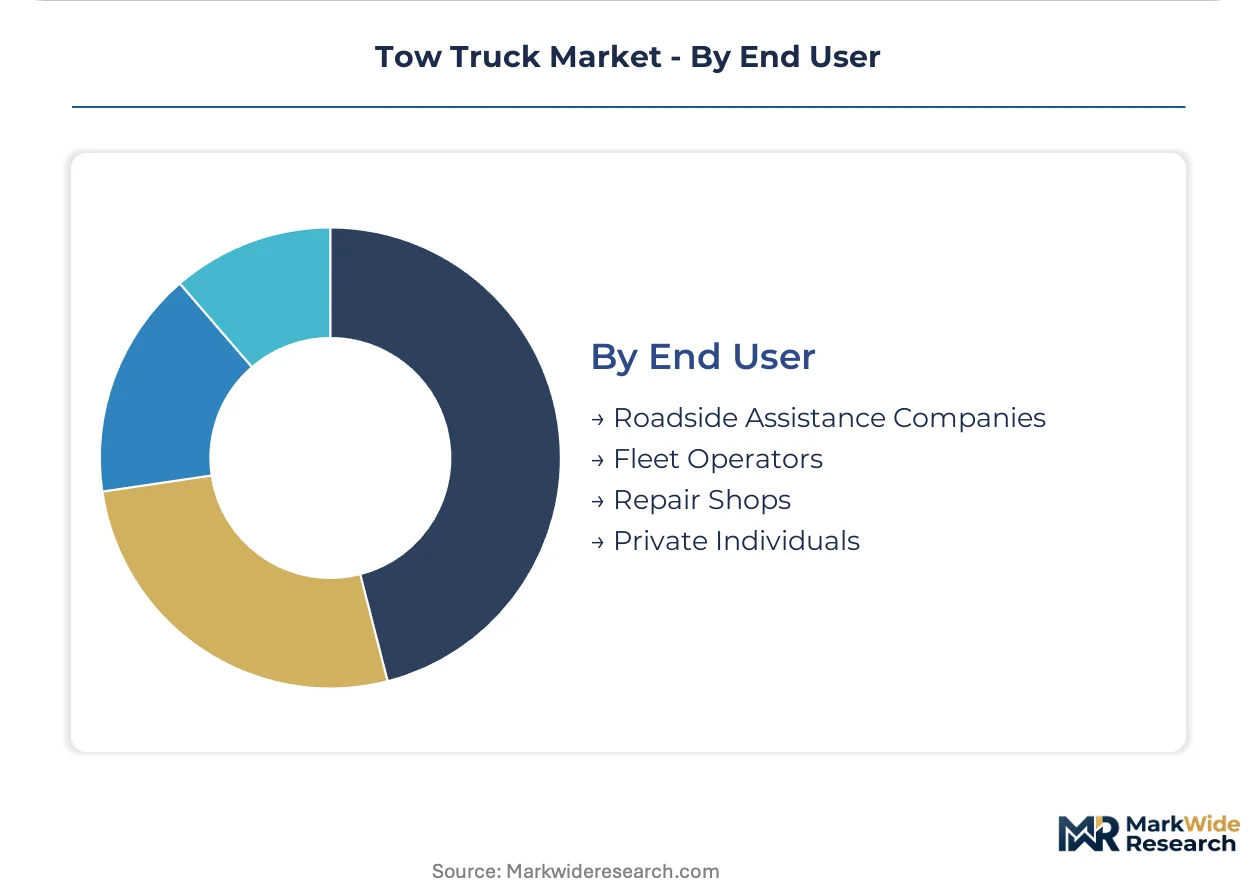
End User:
Customer type determines procurement patterns, with institutional buyers prioritizing dispatch software integration and total cost of ownership while individual consumers respond to price transparency and smartphone accessibility.
- Roadside Assistance Companies:Motor clubs and insurance-affiliated networks consolidate volume with operators capable of telematics integration and guaranteed response windows, with FleetNet America competing through proprietary dispatch platforms across southeastern states.
- Fleet Operators:Municipal and commercial fleet managers specify equipment for in-house recovery capability, with EPA Tier 4 compliance and electrification readiness increasingly weighted in procurement committees.
- Repair Shops:Body shops and mechanical garages maintain limited towing capacity for customer vehicle intake, typically sourcing light-duty wheel-lift units through equipment financing programs.
- Private Individuals:Consumer-direct demand fragments across digital-native dispatch platforms, with smartphone-native driver populations in Sun Belt states exhibiting low brand loyalty to traditional motor club memberships.
Roadside assistance companies dominate contracted volume. Fleet operators represent the fastest-climbing customer segment as municipal outsourcing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates heavy-duty recovery demand along interstate freight corridors, whereas European markets prioritize compact urban configurations for dense historic centers and narrow road networks.
United States
Sun Belt metropolitan corridors from Houston to Phoenix sustain the highest emergency call volumes through municipal traffic management contracts and insurance-preferred provider networks. EPA Tier 4 Final emissions regulations accelerate fleet turnover timelines for diesel-powered heavy-duty units. The I-35 corridor through Texas anchors rotator-equipped recovery demand for commercial trucking incidents.
Germany
Autobahn freight density and strict vehicle inspection protocols generate consistent demand for technical recovery services and accident-scene clearance. KBA type-approval requirements govern towing equipment mounting and lighting configurations. The Rhine-Ruhr industrial cluster concentrates specialized operators serving commercial fleet maintenance networks.
China
Highway expansion in western provinces and electric vehicle penetration reshape service requirements for battery-electric disabled vehicle transport. MIIT vehicle classification standards influence chassis specification for domestic manufacturers. The Yangtze River Delta manufacturing belt drives demand for integrated logistics recovery solutions.
Japan
Compact urban geometry and parking enforcement density favor light-duty wheel-lift configurations with tight turning radius specifications. METI energy efficiency guidelines affect powertrain selection for municipal fleet procurement. The Kanto region around Tokyo concentrates the highest service call frequency per lane-kilometer.
Canada
Trans-Canada Highway commercial trucking volumes and severe winter weather conditions sustain demand for heavy-duty recovery and extreme cold-start capabilities. Transport Canada CMVSS lighting regulations align with NHTSA conspicuity standards for cross-border fleet compatibility. The Alberta oil sands corridor anchors specialized industrial recovery equipment deployment.
Tow Truck Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-system manufacturers competing against regional fabricators and software-anchored service networks. The competitive landscape stratifies across three archetypes: chassis-integrated original equipment manufacturers, specialized boom fabricators supplying mixed-vendor configurations, and dispatch-platform operators consolidating contracted service networks. Dominant competitive moves include backward integration into hydraulic component supply and geographic expansion through municipal contract aggregation in high-traffic corridors.
Among North American operators, Miller Industries occupies a position within the integrated manufacturing tier, while FleetNet America exemplifies the platform-anchored service network archetype. Kelly Mobile Services represents the metropolitan specialization vector, with density-focused deployment in urban zones generating recurring call volume through parking enforcement relationships.
| Leading Market Players |
|---|
| Mercer Transportation |
| Kelly Mobile Services |
| Miller Industries |
| Bear Flag Towing |
| Platinum Transportation Solutions |
| FleetNet America |
| Bokum Logistics |
| Express Towing Extreme Towing |
| Anaheim Fullerton Towing |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final emissions certification gates both chassis qualification and price differentiation in heavy-duty tow truck procurement, separating municipal fleet operators with financing scale from independent contractors facing compressed replacement cycles. Municipal buyers absorb compliance premiums through extended amortization schedules, while smaller operators defer fleet turnover and concentrate in used-equipment arbitrage.
Pricing Analysis
Long-term municipal contracts anchor pricing stability for fleet-scale operators, while spot-market incident response fragments revenue across digital dispatch platforms. Three-tier pricing structure across premium rotator-equipped units, standard heavy-duty configurations, and economy light-duty wheel-lifts reflects certification grade and after-sales service bundling. Cost compression in light-duty segments intensifies because insurance carriers consolidate preferred provider networks around response-time guarantees. Private individuals exhibit highest price sensitivity, whereas industrial clients with OSHA heavy-lift requirements accept premium positioning.
Supply Chain Analysis
United States and Germany anchor integrated chassis-boom fabrication for heavy-duty recovery equipment, while China supplies hydraulic component castings and steel assemblies. Boom fabrication draws from specialized steel grades and precision hydraulic cylinder manufacturing concentrated in Midwestern industrial corridors. Single-source vulnerability in certified diesel aftertreatment systems creates procurement friction for fleet renewal timelines. Distribution runs through manufacturer-authorized dealers with captive financing arms, particularly for municipal procurement committees requiring bonded contract performance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across service tiers creates entry windows for specialized operators, as electrification mandates and technician scarcity simultaneously disrupt incumbent cost structures and open niche contracting positions.
For Market Incumbents: Compound fleet scale advantages through backward integration into hydraulic maintenance infrastructure, addressing the certified technician collapse that constrains competitor expansion. Acquire regional operators along I-35 and I-10 corridors to consolidate municipal contract portfolios before electrification turnover accelerates. Anchor defensive positioning against digital broker disintermediation by embedding proprietary dispatch software into insurance carrier preferred provider agreements. For New Entrants and Emerging Players: Battery-electric charging corridor gaps along interstate freight routes present immediate white-space opportunity, as incumbent operators defer heavy-duty electrification investments pending payload penalty resolution. Target municipal outsourcing expansion in Sun Belt metropolitan zones where traffic management contracts concentrate predictable revenue streams. Deploy telematics-integrated dispatch platforms as primary go-to-market wedge, compressing response-time guarantees below incumbent benchmarks. For Investors and Strategic Acquirers: EPA Tier 4 Final compliance deadlines reshape the acquisition landscape toward operators with pre-2021 equipment amortization runway and technician training infrastructure already deployed. Long-term viability centers on electrification-ready fleet positioning and software-anchored service network density. Target acquisition archetype: mid-scale regional operators with contracted municipal revenue and maintenance capabilities transferable to battery-electric platforms. Monitor NHTSA lighting standard update timelines as inflection signal for forced fleet turnover velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Positions operators for battery-electric heavy-duty deployment along I-10 and I-95 corridors ahead of fleet mandates. |
| Technician Certification Program | OSHA heavy-lift training creates defensible contracting moats with industrial clients facing liability exposure. |
| Dispatch Platform Integration | Telematics-embedded response guarantees secure preferred provider status with Progressive and State Farm networks. |
| Municipal Contract Aggregation | Consolidated procurement across Texas and Florida metropolitan zones generates predictable revenue amortization. |
| Hydraulic Component Backward Integration | In-house boom fabrication insulates margins from steel commodity volatility and supply lead-time compression. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of NHTSA safety filings, EPA emissions compliance databases, and municipal procurement records, integrating perspectives from fleet maintenance directors, municipal traffic management officers, heavy-duty equipment dealers, and hydraulic component procurement leads. Bottom-up unit deployment estimates triangulate against top-down fleet turnover projections derived from chassis registration data and replacement cycle assumptions.
Segmentation dimensions modeled span vehicle type, service category, capacity tier, and end-user archetype across the projection horizon, with growth trajectories derived from contracted municipal spending patterns and insurance network consolidation trends. Forecast inputs incorporate EPA regulatory phase-in schedules, diesel technician graduation rates from vocational programs, and charging infrastructure buildout commitments along designated freight corridors.
Forecasts assume regulatory continuity in EPA Tier 4 Final and NHTSA lighting standard regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Car Wash Services Market
Automotive Services
Car Vending Machine Market
Automotive Services
Automotive Homologation Services Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Car Wash Franchise Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Global Street Sweeper Market
Automotive Services
Automotive MRO Market
Automotive Services
Automotive Repair and Service Market
Automotive Services
France Car Rental Market
Automotive Services
Car Wash System Market
Automotive Services
Vehicles for Disabled Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
GCC Car Wash Market
Automotive Services
Cab Services Market