
 United States Automotive Dealership Market | 2026-2036
United States Automotive Dealership Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive Dealership Market Analytics
NADA certification requirements is bifurcating the competitive landscape between capital-heavy franchise operators and agile independent networks. AutoNation leverages its coast-to-coast footprint to sustain service revenue density. Lithia Motors anchors its growth in secondary and tertiary markets where brand representation remains thin. Penske Automotive Group competes through premium brand concentration and integrated transportation services.
The United States automotive dealership constitutes a licensed retail and service intermediary between vehicle manufacturers and end consumers, operating through physical showrooms, service bays, and digital transaction platforms that handle inventory financing, warranty administration, and aftermarket parts distribution. Franchise dealerships dominate transaction volume and manufacturer incentive capture, while certified pre-owned operations concentrate margin in vehicle remarketing. Electric vehicle specialization within the vehicle type segment is expanding fastest as OEM allocation shifts and technician retraining demands intensify.
The FTC's revised Vehicle Shopping Rule and state-level dealer franchise laws enforced by attorneys general in California, Texas, and Florida govern advertising transparency and factory-direct sales prohibitions. EPA tailpipe standards and NHTSA Corporate Average Fuel Economy mandates filter through to dealership lot composition and incentive structures. Stakeholders must monitor how right-to-repair legislation and evolving OEM agency models redistribute control over pricing, inventory, and customer data across the retail channel.
Market Dynamics
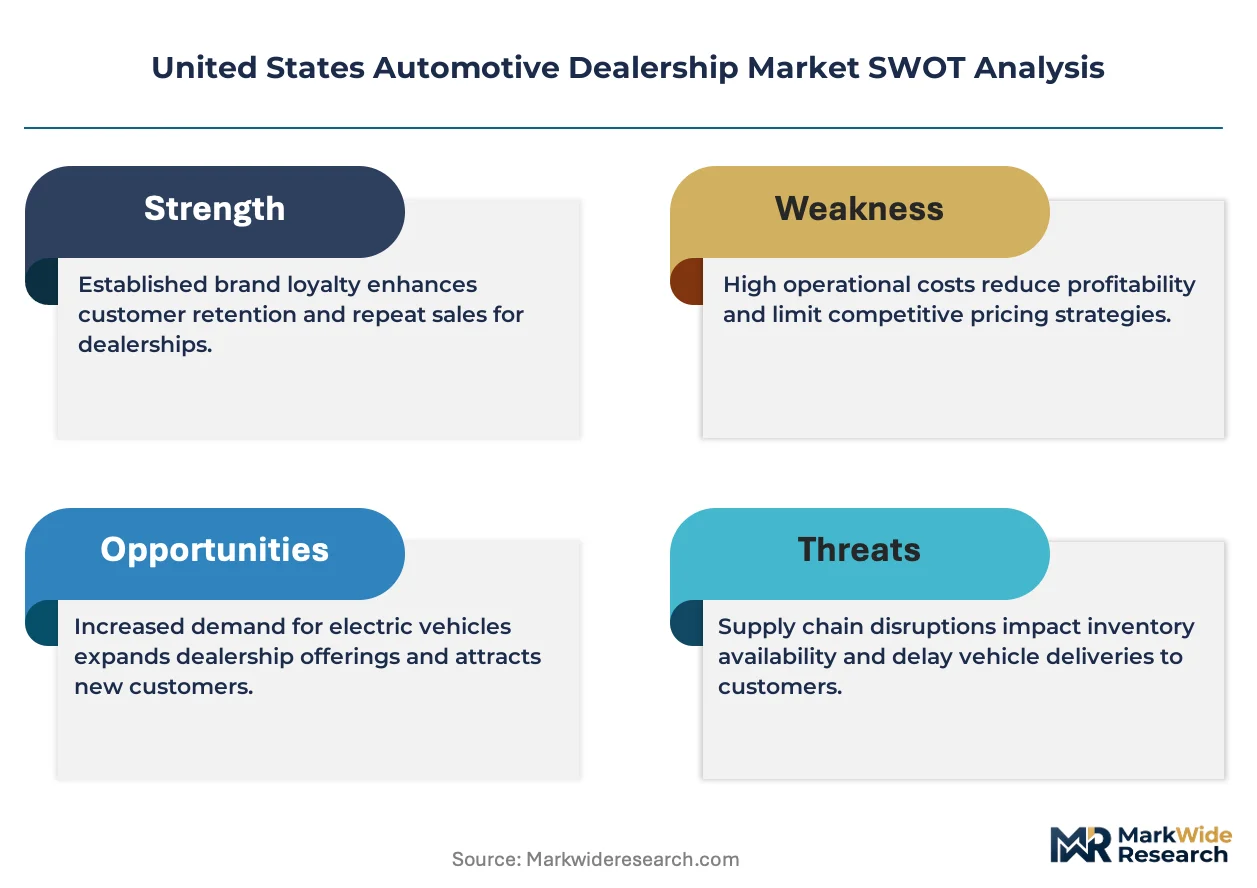
Electric vehicle allocation mandates from Detroit manufacturers are compressing traditional franchise economics while forcing capital redeployment into charging infrastructure and technician certification pipelines.
Growth Catalysts
- EPA tailpipe standards:Stringent emissions thresholds are accelerating OEM electrification roadmaps and expanding certified EV service bay requirements across franchise networks.
- Fleet electrification:Commercial operators in energy logistics and last-mile delivery are consolidating procurement through dealership fleet departments for volume pricing and maintenance bundling.
- Texas population migration:Inbound residential growth in Houston and Dallas-Fort Worth corridors is sustaining above-average new vehicle registration rates and service retention.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing and cell manufacturing capacity remains concentrated in Asian supplier networks, exposing margin pressure from input cost volatility.
- NHTSA fuel economy mandates:Compliance costs for CAFE credit deficits are compressing manufacturer incentive budgets available for dealer floorplan support.
- Direct-to-consumer sales prohibition variance:State-level franchise law fragmentation creates operational complexity for multi-state operators navigating Texas, California, and Florida attorney general enforcement.
Strategic Opportunities
- Secondary market penetration:Rural counties in Montana, Idaho, and Wyoming remain underrepresented by premium brand service infrastructure, creating whitespace for satellite facility deployment.
- Right-to-repair legislation:Pending state bills in Massachusetts and Colorado would mandate diagnostic tool access, opening independent service revenue streams previously captured by franchised bays.
- Agency model convergence:Fixed-price transaction structures and OEM-controlled inventory positioning would reduce working capital intensity for retail operators while shifting margin to digital customer acquisition.
Industry Challenges
- High-voltage technician certification:ASE and manufacturer-specific EV safety credentials require 18-24 month training pipelines, creating workforce bottlenecks as service demand accelerates.
- Legacy DMS integration:Dealer management system migration to cloud-native platforms faces resistance from fixed operations managers dependent on decades-old workflow modules.
- Real estate repositioning:Footprint reduction from shrinking inventory lots conflicts with manufacturer facility image requirements and service bay expansion needs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive Dealership Market |
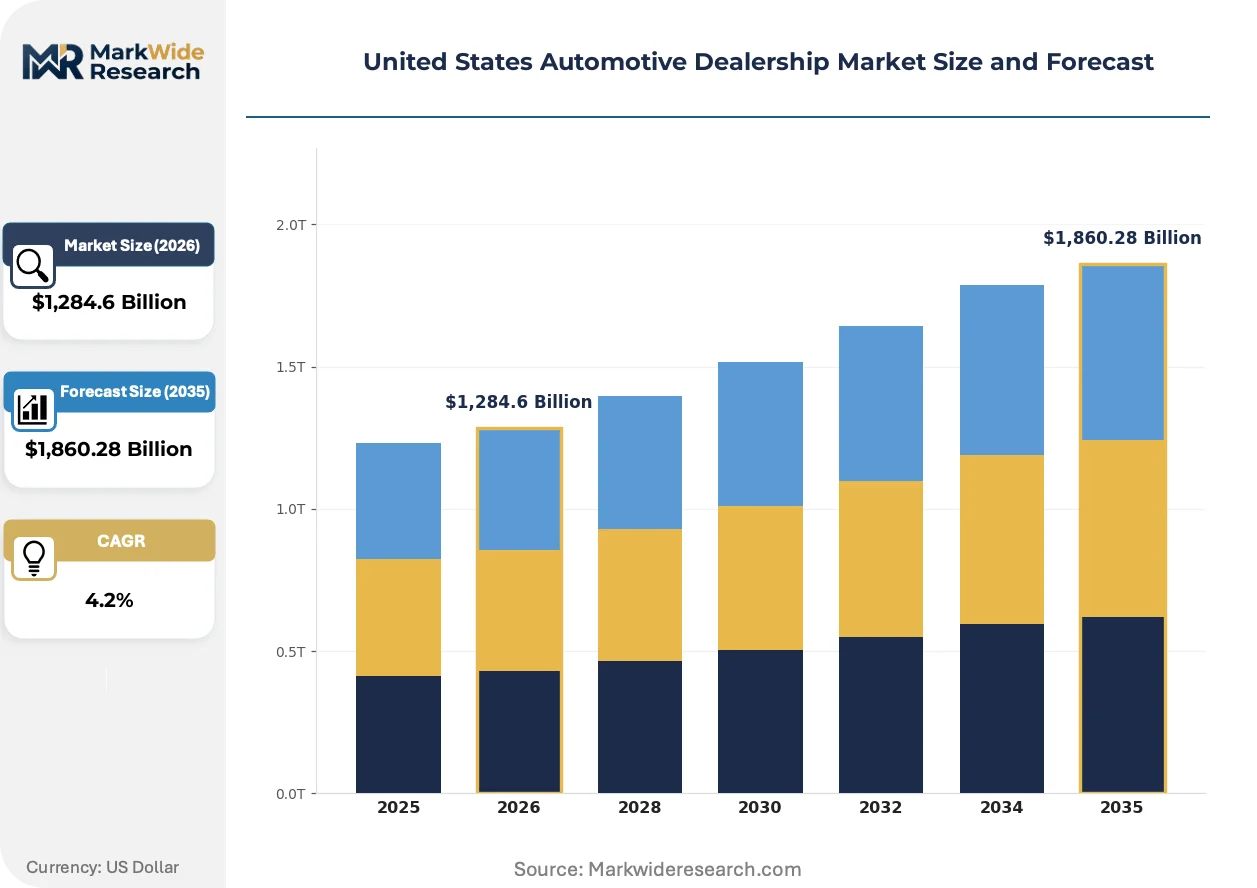
| Market Size in 2026 | $1,284.6 Billion |
| Market Size in 2035 | $1,860.28 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Dealership Type: Franchise, Independent, Certified Pre-Owned, Luxury Sales Channel: Online Sales, In-Person Sales, Auction, Wholesale Customer Type: Private Buyers, Commercial Fleets, Rental Services, Government Vehicle Type: New Vehicles, Used Vehicles, Electric Vehicles, Hybrid Vehicles |
| Companies Covered | Asbury Automotive Group, Sonic Automotive, Lithia Motors, Victory Automotive Group, Group 1 Automotive, AutoNation, Hudson Automotive Group, Ken Ganley Automotive Group, Penske Automotive Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive Dealership Market Evolving Landscape
Digital retailing infrastructure is compressing the traditional showroom-to-delivery timeline while redistributing customer data ownership between dealers and their manufacturer partners.
Over-the-air software update capability is displacing routine service appointments as the primary dealer-customer touchpoint. Fleet operators and luxury buyers now expect remote diagnostic access and predictive maintenance scheduling without physical bay visits. This compression threatens traditional service revenue density that has subsidized new vehicle transaction thinness for decades.
The FTC's revised Vehicle Shopping Rule mandates all-in pricing disclosure in digital advertising, eliminating the documentation fee obfuscation that previously anchored negotiation leverage. Dealerships in California and Texas are restructuring compensation plans away from back-end gross toward volume-based manufacturer stair-step incentives. Smaller independent operators lacking compliance infrastructure face heightened attorney general scrutiny.
Subscription-based vehicle access is fragmenting traditional ownership patterns among urban millennials and corporate mobility managers. Flex-drive programs through dealership digital platforms are replacing 36-month retail leases in coastal metropolitan markets. Florida and Arizona retirement communities show strongest resistance, maintaining conventional purchase preferences despite national behavioral shifts.
United States Automotive Dealership Market Segmentation
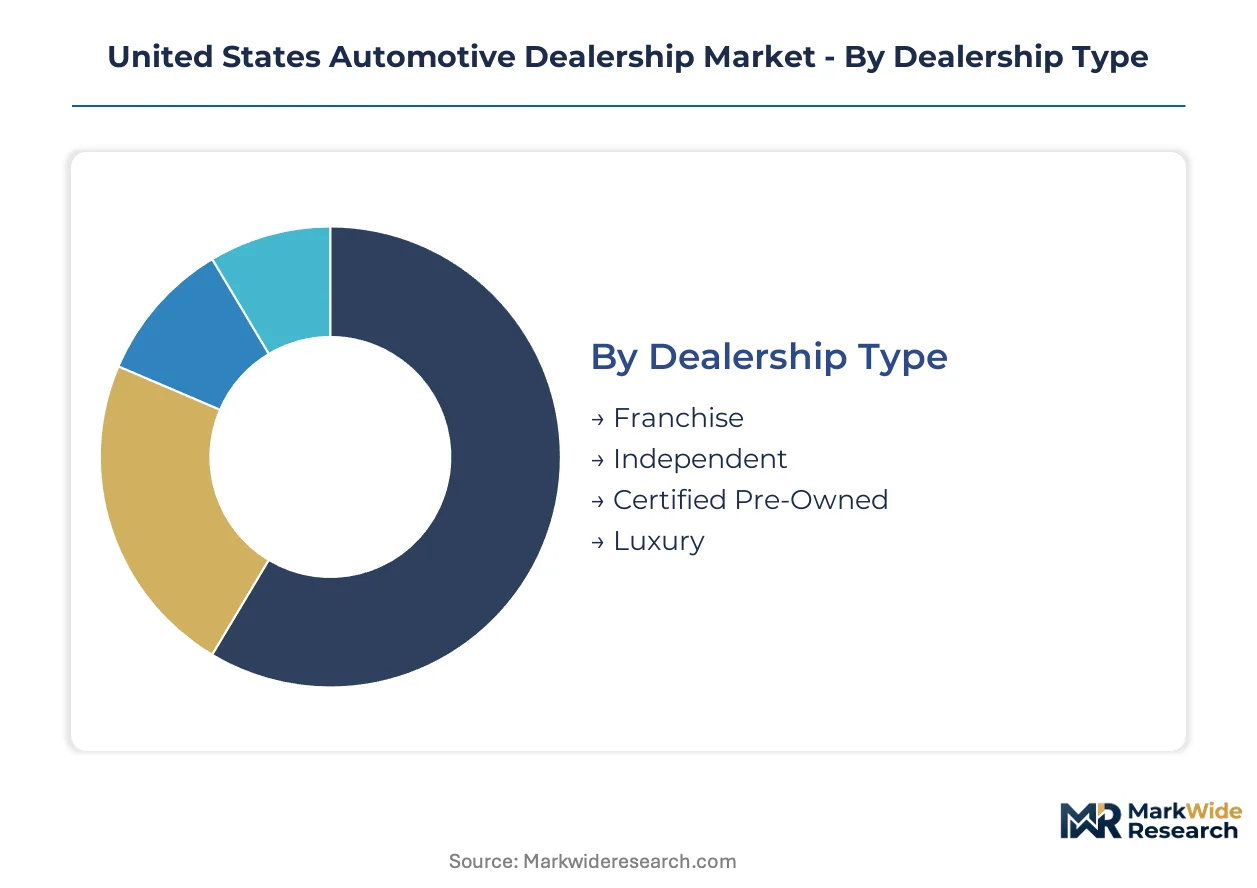
Dealership segmentation determines capital allocation, facility requirements, and manufacturer incentive eligibility. Channel mix varies sharply across customer types and vehicle technologies, forcing operators to balance physical footprint against digital transaction infrastructure.
Dealership Type:
Franchise networks capture manufacturer allocation and warranty revenue, while independents and certified pre-owned operators concentrate margin in vehicle remarketing and service arbitrage.
- Franchise:Licensed operators holding OEM sales and service agreements with exclusive territory rights. New vehicle allocation from Detroit manufacturers flows through these channels, with EPA tailpipe compliance mandates compressing traditional floorplan economics. Texas and Florida host the densest franchise concentration due to population migration and fleet turnover.
- Independent:Unaffiliated retailers sourcing inventory through auction, trade-in, and wholesale channels. These operators exploit pricing flexibility and lower overhead in secondary markets where brand representation remains thin. FTC advertising disclosure rules create compliance asymmetry against capital-heavy franchise competitors.
- Certified Pre-Owned:Factory-backed used vehicle programs with extended warranty coverage and inspection protocols. Manufacturer stair-step incentives increasingly favor CPO volume over new vehicle throughput.
- Luxury:Premium brand specialists concentrating in coastal metropolitan markets and affluent retirement corridors. Subscription-based vehicle access programs are fragmenting traditional ownership patterns among urban millennials in these channels.
Franchise operations dominate transaction volume and incentive capture. Certified Pre-Owned is where expansion concentrates as OEM remarketing pipelines mature.
Sales Channel:
Cost tier stratification separates high-touch physical retail from low-margin digital and bulk transaction formats.
- Online Sales:Digital retailing infrastructure compressing showroom-to-delivery timelines while redistributing customer data ownership. The FTC's revised Vehicle Shopping Rule mandates all-in pricing disclosure, eliminating documentation fee leverage previously embedded in negotiation workflows. Fixed-price transaction structures are gaining traction in agency model pilots.
- In-Person Sales:Traditional showroom operations with test drive, negotiation, and F&I product presentation. These channels retain dominance in Florida and Arizona retirement communities where conventional purchase preferences persist despite national behavioral shifts.
- Auction:Wholesale vehicle redistribution platforms serving independent dealers and remarketing specialists. Physical auction volume faces displacement from digital wholesale platforms reducing transport and recon costs.
- Wholesale:Direct fleet and commercial volume transactions bypassing retail markup. Fleet operators in energy logistics and last-mile delivery consolidate procurement through these channels for volume pricing and maintenance bundling.
In-Person Sales anchors revenue density through F&I penetration. Online Sales is climbing the fastest as OEM agency models reduce working capital intensity for retail operators.
Customer Type:
Application-based segmentation separates individual mobility from commercial asset deployment and public procurement.
- Private Buyers:Individual consumers purchasing for personal transportation needs. These customers increasingly expect remote diagnostic access and predictive maintenance scheduling without physical bay visits, compressing traditional service revenue density.
- Commercial Fleets:Business operators managing vehicle assets for logistics, delivery, and field service applications. Electrification mandates from EPA and NHTSA are accelerating procurement consolidation through dealership fleet departments.
- Rental Services:Short-term mobility providers cycling inventory through rapid turnover models. These customers prioritize acquisition cost and residual value predictability over service bundling.
- Government:Federal, state, and municipal procurement programs with standardized specifications and compliance requirements. NHTSA fuel economy mandates filter through to lot composition and incentive structures affecting these buyers.
Private Buyers represent the largest addressable population. Commercial Fleets is gaining share fastest as electrification roadmaps accelerate replacement cycles.
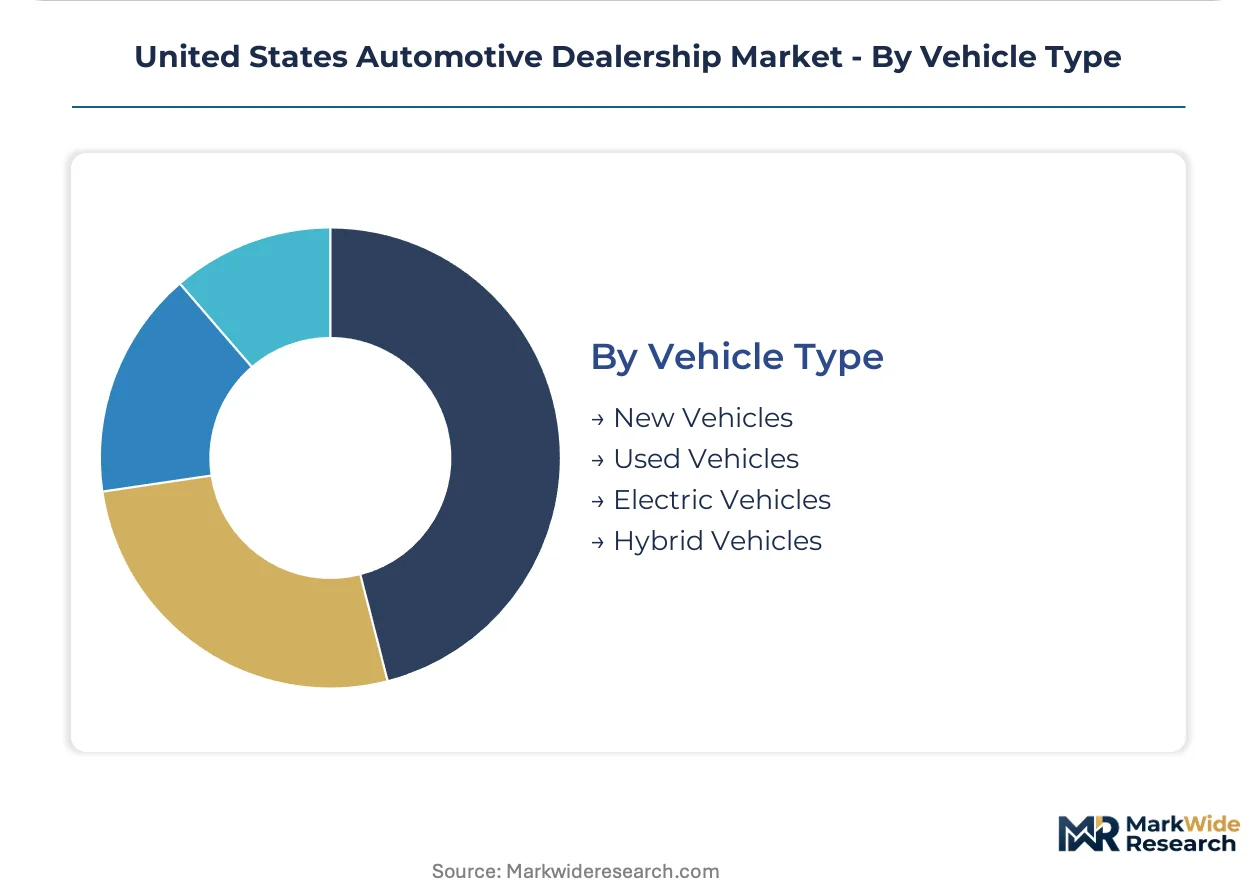
Vehicle Type:
Technology maturity and regulatory pressure create divergent margin profiles across powertrain categories.
- New Vehicles:Factory-fresh inventory subject to manufacturer allocation and image program requirements. EPA tailpipe standards and NHTSA CAFE mandates are reshaping procurement patterns and incentive structures.
- Used Vehicles:Prior-ownership inventory remarketed through retail or wholesale channels. These units concentrate margin in markets where new vehicle affordability constraints push buyers downstream.
- Electric Vehicles:Battery-electric powertrains requiring specialized charging infrastructure and high-voltage technician certification. ASE and manufacturer-specific EV safety credentials demand 18-24 month training pipelines, creating workforce bottlenecks as service demand accelerates.
- Hybrid Vehicles:Dual-powertrain systems bridging internal combustion and electrification technologies. These units serve transition markets where charging infrastructure remains underdeveloped.
New Vehicles dominate manufacturer incentive flows. Electric Vehicles is where capital redeployment concentrates as OEM allocation shifts and technician retraining demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 35 corridor anchors Texas dealership throughput, connecting Dallas-Fort Worth logistics nodes to Houston energy-sector fleet operators. This infrastructure backbone sustains above-average vehicle registration velocity and service bay utilization across the state's franchise networks.
Texas
Houston energy logistics and Dallas-Fort Worth last-mile delivery fleets are consolidating procurement through dealership fleet departments. The Texas attorney general enforces franchise law prohibitions on factory-direct sales, protecting dealer territory rights. The I-35 corridor sustains the densest concentration of premium brand representation outside coastal metros.
California
Los Angeles and San Francisco Bay Area metros drive electric vehicle allocation demand from Detroit manufacturers. The California attorney general enforces advertising transparency rules under state consumer protection statutes. Southern California retirement corridors maintain conventional purchase preferences despite subscription-model growth elsewhere.
Florida
Miami and Tampa retirement communities sustain above-average service retention rates for internal combustion vehicles. The Florida attorney general coordinates with NHTSA on fuel economy mandate compliance documentation. The I-4 corridor between Orlando and Tampa hosts expanding certified pre-owned operations targeting snowbird remarketing.
Michigan
Detroit manufacturer headquarters proximity compresses floorplan economics through allocation mandate pressure. The Michigan attorney general maintains strict dealer franchise law enforcement against agency model experiments. The Ann Arbor-Detroit corridor concentrates technician training infrastructure for high-voltage certification pipelines.
Arizona
Phoenix and Tucson retirement communities resist subscription-based vehicle access models despite national behavioral shifts. The Arizona attorney general monitors right-to-repair legislation impacts on independent service revenue. The I-10 corridor sustains wholesale auction volume serving southwestern independent dealer networks.
United States Automotive Dealership Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. Franchise networks concentrate transaction volume and manufacturer incentive capture, while independent operators exploit pricing flexibility in secondary markets. Three archetypes dominate: coast-to-coast consolidators, secondary-market penetration specialists, and premium-brand concentration players. Competitive moves center on facility image program compliance and fleet department capacity expansion.
Within the consolidator tier, AutoNation and Lithia Motors occupy positions reflecting divergent geographic strategies. AutoNation exemplifies coast-to-coast footprint density sustaining service revenue concentration. Lithia Motors anchors secondary and tertiary market penetration where brand representation remains thin. Penske Automotive Group sits within the premium-brand specialization archetype, competing through integrated transportation services beyond traditional retail.
| Leading Market Players |
|---|
| Asbury Automotive Group |
| Sonic Automotive |
| Lithia Motors |
| Victory Automotive Group |
| Group 1 Automotive |
| AutoNation |
| Hudson Automotive Group |
| Ken Ganley Automotive Group |
| Penske Automotive Group |
| Others |
Value Network & Pricing Analysis
Sixty-day floorplan carrying costs concentrate pricing power among multi-state franchise operators with captive finance relationships, compressing margin recovery for independents lacking manufacturer incentive stair-step access. This inventory velocity differential separates capital-heavy networks from agile competitors in secondary markets.
Pricing Analysis
Volume-discount tiering structures separate manufacturer stair-step incentives from retail transaction gross. Pricing stratifies across premium brand representation, certified pre-owned warranty backing, and independent auction-sourced inventory. Cost compression in new vehicle transactions is intensifying because EPA compliance mandates redirect OEM incentive budgets toward electrification roadmaps. Fleet operators demonstrate lowest price sensitivity through maintenance bundling, while private retail buyers in secondary markets exhibit highest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate franchise networks under manufacturer allocation discipline, while strategic stockpiling persists among independent operators exploiting auction price volatility. Vehicle sourcing draws from Detroit assembly plants, Mexican maquiladora cross-border production, and Asian battery-electric component import channels. Cathode material processing and cell manufacturing capacity rests on concentrated Asian supplier networks. Single-source vulnerability in lithium-ion supply exposes margin pressure from input cost volatility. Distribution runs through manufacturer-controlled rail and truck networks to regional processing centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA tailpipe standards and NHTSA fuel economy mandates constitute a regulatory inflection forcing capital redeployment across the retail channel, positioning electrification infrastructure as the decisive capability differentiator.
For Market Incumbents: Consolidate service bay capacity through high-voltage technician certification pipelines and charging infrastructure deployment. Defensive positioning requires backward integration into fleet maintenance contracts before independent networks capture commercial electrification volume. Threat substitution from agency model pilots demands channel control reinforcement through digital customer data ownership.
For New Entrants and Emerging Players: Anchor in rural counties across Montana, Idaho, and Wyoming where premium brand service infrastructure remains underrepresented. The most penetrable whitespace targets satellite facility deployment adjacent to energy-sector logistics corridors. A fleet-focused go-to-market angle bypasses capital-intensive showroom requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from private dealership groups lacking compliance infrastructure for FTC advertising disclosure mandates. Long-term viability favors operators with demonstrated EV service throughput and manufacturer stair-step incentive capture. The signal to watch is right-to-repair legislation passage in Massachusetts and Colorado as independent service revenue inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Technician Certification Pipeline | ASE and manufacturer-specific EV credentials address 18-24 month workforce bottlenecks. |
| Fleet Electrification Infrastructure Partnership | Charging bay deployment captures commercial procurement consolidation through volume pricing. |
| Digital Retailing Platform Integration | FTC all-in pricing compliance eliminates documentation fee leverage in negotiation workflows. |
| Secondary Market Satellite Facility Expansion | Rural county penetration exploits thin brand representation in Montana and Wyoming corridors. |
| Right-to-Repair Diagnostic Tool Investment | Independent service revenue streams open under pending Massachusetts and Colorado legislation. |
Research Methodology
Cross-validation between NHTSA fuel economy compliance filings and state attorney general enforcement records anchors the qualitative findings. Primary interviews with dealership operations directors, OEM platform allocation managers, fleet procurement leads, and aftermarket distributor executives combine with secondary validation from EPA tailpipe standard publications, FTC Vehicle Shopping Rule documentation, and vehicle registration databases. Bottom-up triangulation across franchise network capacity and top-down macroeconomic indicators establish segment-level estimates.
Sensitivity analysis around electrification adoption curves and lithium-ion supply cost trajectories informs projection robustness. The analytical framework models segmentation across propulsion architecture, dealership type, customer application, and regional regulatory cluster throughout the forecast period. CAGRs derive from manufacturer allocation mandate timelines and fleet replacement cycle analysis. Industry-specific inputs include high-voltage technician certification pipeline completion rates and charging infrastructure deployment density.
Decision-makers should treat outputs as directional under continued EPA tailpipe standard enforcement and NHTSA CAFE mandate trajectory; material deviation would warrant model refresh. Forecasts reflect assumptions around manufacturer incentive budget stability and franchise law prohibition durability. Revision becomes warranted when lithium-ion supply concentration or right-to-repair legislative passage crosses threshold impacts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
United States Automotive Service Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Qatar Car Rental Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Online Car-Hailing Service Market
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Car Wash System Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Mobility Scooters Market
Automotive Services
US Quick Lube Equipment Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
Brushless Car Wash Machine Market
Automotive Services
Automatic Tire Changer Market