
 Global Automotive Engineering Services Outsourcing Market | 2026-2036
Global Automotive Engineering Services Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Engineering Services Outsourcing Market Foresight
Electric vehicle startups is reorganizing procurement patterns across the Global Automotive Engineering Services Outsourcing Market, pulling work away from traditional internal R&D departments. Capgemini Engineering leverages its embedded systems expertise to anchor long-term contracts with software-defined vehicle programs. AVL List GmbH sustains dominance in powertrain simulation through deep testing infrastructure across European and Asian facilities. Bertrandt AG competes on body-in-white engineering specialization, occupying a narrow but defensible niche in structural design.
Automotive engineering services outsourcing covers the contracted provision of technical design, simulation, prototyping, and validation activities performed by third-party specialists on behalf of vehicle manufacturers and suppliers. These services integrate CAD/CAM modeling, CAE analysis, and embedded software development to compress development cycles and transfer fixed R&D costs to variable expenditure. Simulation services leads the service type dimension due to the capital intensity of physical testing infrastructure, while software development within the technology segment captures the fastest expansion as vehicles become compute platforms on wheels. Client type concentration tilts toward OEMs, though tier-1 suppliers are deepening outsourcing relationships to preserve margin on commoditized hardware.
The EU Green Deal and associated F-Gas Regulation shape powertrain engineering priorities by accelerating zero-emission platform development across European automotive value chains. The EPA and NHTSA in the United States enforce parallel emissions and safety standards that elevate testing and validation outsourcing volumes as compliance complexity outstrips captive capabilities. Stakeholders must monitor how regulatory divergence between jurisdictions fragments engineering standards and multiplies the cost of unified platform development.
Market Dynamics
Software-defined vehicle architectures are forcing engineering service providers to restructure delivery models around continuous integration pipelines rather than discrete program phases. This compression of development cycles eliminates traditional handoff points between design and validation, embedding outsourcing partners deeper into OEM operational workflows.
Growth Catalysts
- EU Green Deal compliance mandates:F-Gas Regulation and associated emissions frameworks compel powertrain electrification programs that exceed captive engineering capacity at European OEMs.
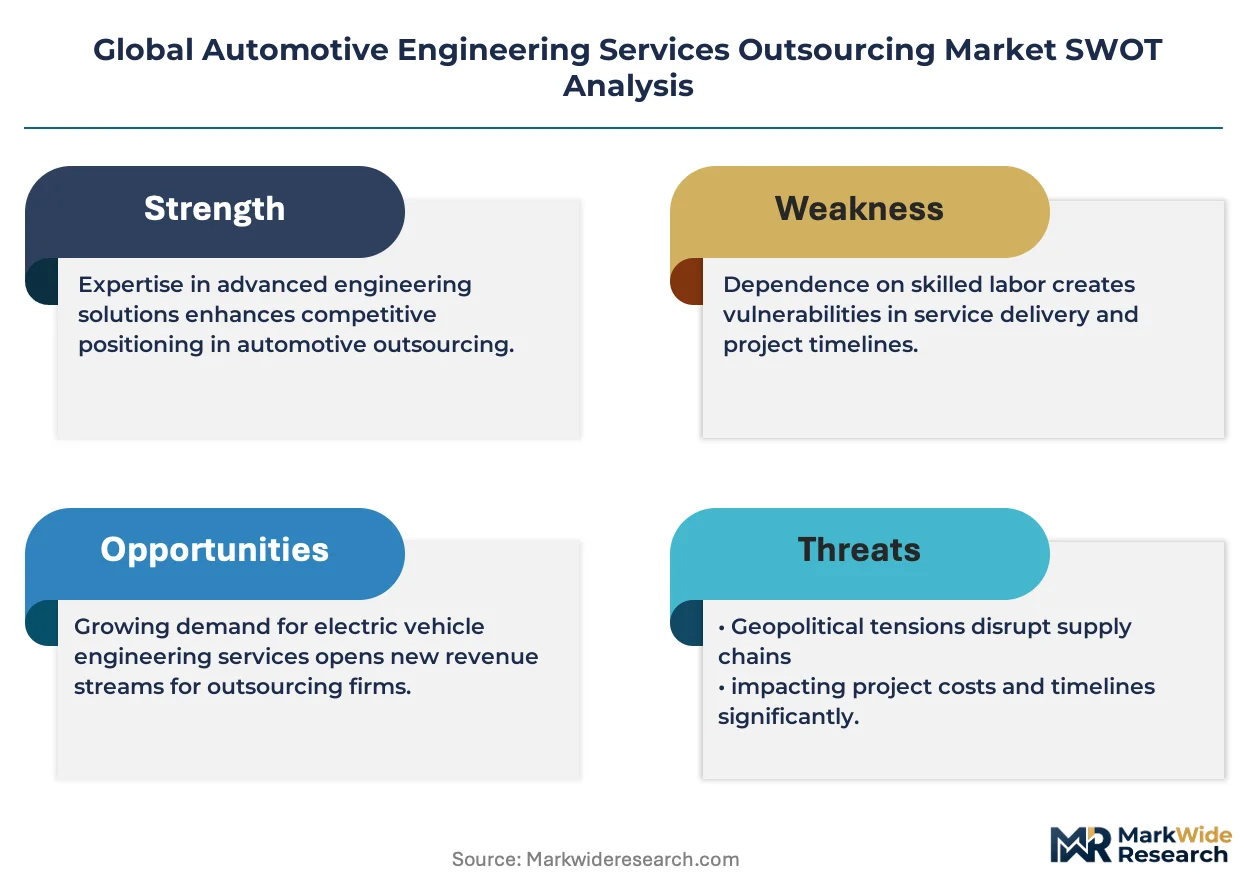
- Functional safety engineering:ISO 26262 certification requirements for autonomous systems generate sustained demand for independent validation services across sensor fusion and control domains.
- India PLI scheme for automotive:Domestic manufacturing incentives attract global OEMs establishing local engineering centers, creating regional outsourcing demand for localization and homologation support.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fabrication dominance creates input volatility that disrupts embedded systems development timelines and prototyping schedules.
- Engineering talent scarcity:Embedded software and systems architecture expertise concentrates in Germany, the United States, and Japan, constraining provider expansion in emerging markets.
- Regulatory fragmentation:Divergent NHTSA and EU AI Act requirements for autonomous vehicle validation multiply compliance costs for unified platform development.
Strategic Opportunities
- Brazil ANVISA medical-vehicle convergence:Mobile health and diagnostic vehicle platforms create cross-sector engineering demand combining automotive chassis with healthcare equipment integration.
- Digital twin adoption:Physics-based simulation convergence with real-time data streaming enables predictive validation services that compress physical testing requirements.
- US Inflation Reduction Act incentives:Domestic battery and EV manufacturing subsidies attract engineering investment toward North American facility design and process optimization.
Industry Challenges
- Systems integration complexity:Legacy CAN bus architectures interfacing with zonal E/E platforms create validation gaps that prolong program timelines and escalate rework costs.
- Cybersecurity certification backlog:UN R155 and ISO/SAE 21434 compliance timelines strain provider capacity as threat analysis and penetration testing requirements expand across vehicle domains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Engineering Services Outsourcing Market |
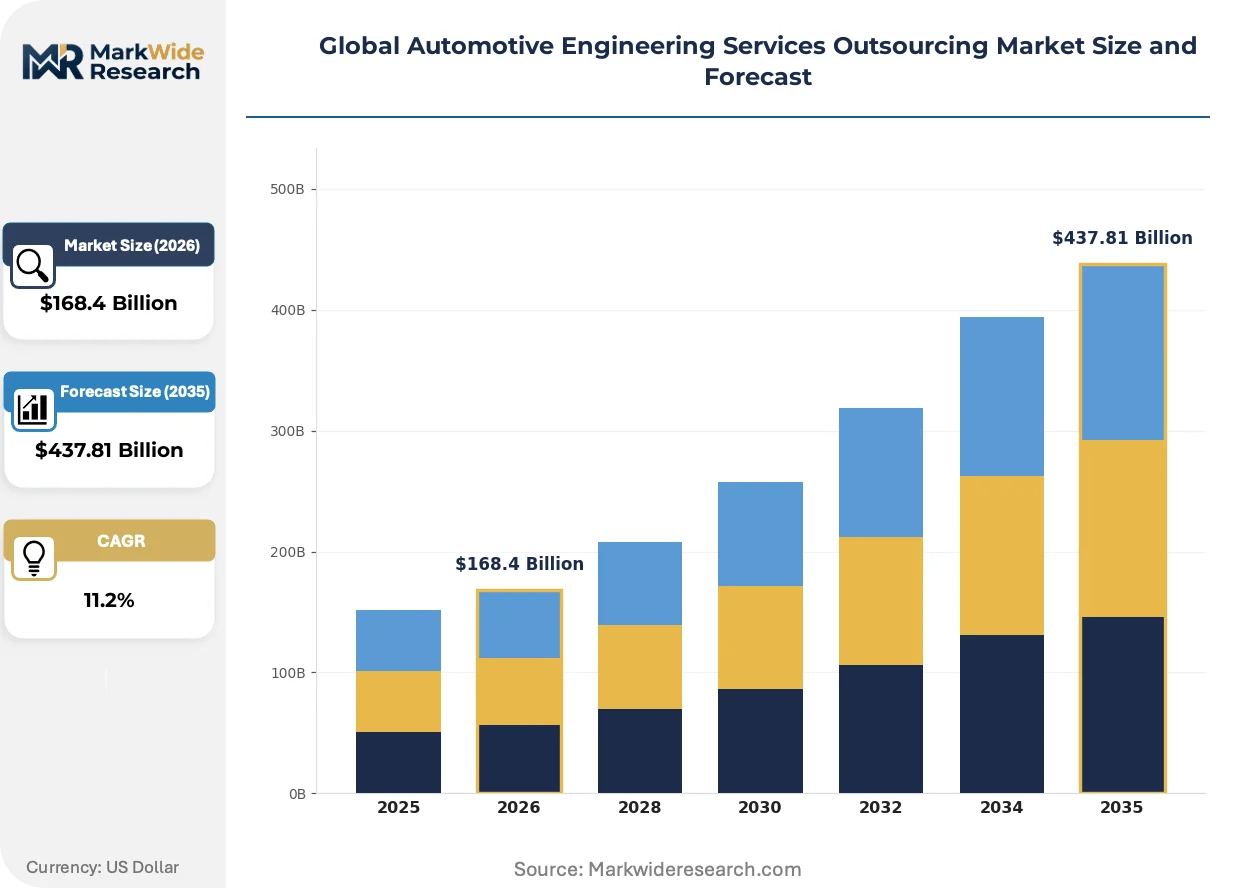
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $437.81 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design Engineering, Simulation Services, Prototyping, Testing & Validation, Product Lifecycle Management, Documentation Technology: CAD/CAM, CAE, Vehicle Dynamics, Embedded Systems, Software Development, Control Systems Client Type: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assembly Plants, Engineering Consultants, Research Institutes Application: Powertrain, Chassis & Suspension, Body & Exterior, Infotainment, Safety Systems, Connectivity Solutions |
| Companies Covered | Capgemini Engineering, AVL List GmbH, Bertrandt AG, HCL Technologies, IAV GmbH, Tech Mahindra, Wipro, L&T Technology Services, EDAG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Engineering Services Outsourcing Market Shifts & Advancements
Artificial intelligence is penetrating engineering workflows at the point of highest friction: requirements translation and test case generation. This insertion is compressing specification-to-simulation cycles and forcing providers to retrain technical staff around machine-augmented design methodologies.
Generative design algorithms are fragmenting traditional topology optimization workflows across body structure and thermal management applications. Tier-1 suppliers in Germany and Japan are deploying these tools for battery enclosure development, collapsing iteration cycles from weeks to days. The structural consequence is fragmenting the competitive advantage of established simulation specialists who previously dominated physics-based optimization.
The EU AI Act's risk classification framework for autonomous systems is mandating traceability and human oversight protocols that reshape validation documentation requirements. Engineering service providers must now embed algorithmic auditing capabilities alongside traditional functional safety processes. European OEMs are responding by consolidating validation contracts with partners possessing dual ISO 26262 and AI governance competencies.
Fixed-fee program structures are yielding to consumption-based engagement models where engineering hours scale with sprint velocity rather than predetermined milestones. This shift disrupts traditional account planning at German and Japanese OEMs, replacing annual budget commitments with dynamic resource allocation. The United States market exhibits the fastest adoption of this model among EV startups seeking to preserve cash runway during platform development.
Global Automotive Engineering Services Outsourcing Market Segmentation
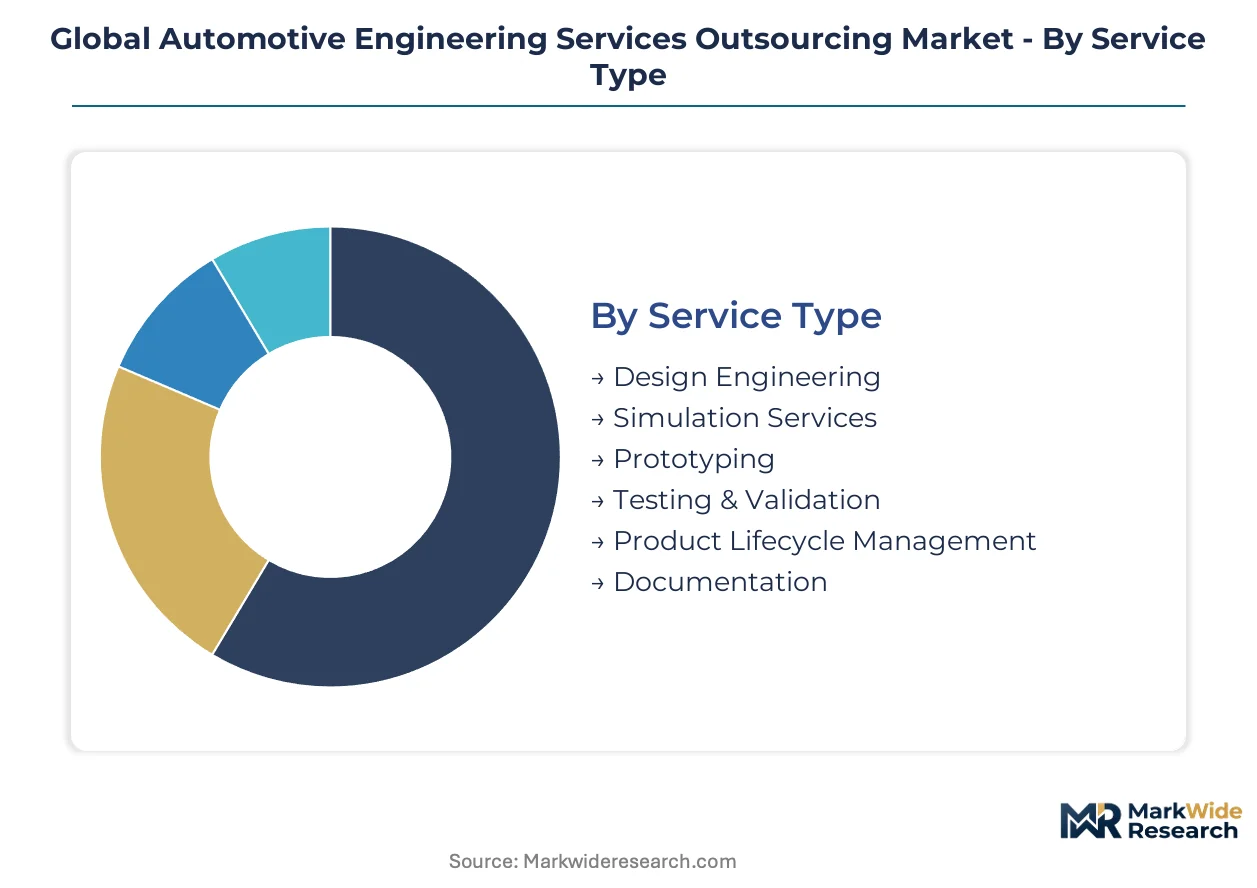
Engineering service providers structure offerings around distinct capability bundles that match client risk tolerance and technical maturity. Segmentation clarity determines contract pricing, talent allocation, and regulatory compliance pathways across the automotive value chain.
Service Type:
Regulatory differentiation between EU Green Deal mandates and NHTSA safety protocols fragments service demand across validation intensity levels.
- Simulation Services:Physics-based modeling environments replicate crash dynamics, thermal behavior, and aerodynamic performance without physical prototypes. German OEMs concentrate procurement here to satisfy KBA type-approval requirements while compressing development cycles. Capital intensity of HPC clusters and wind tunnel correlation creates high barriers that favor established European providers.
- Testing & Validation:Physical verification protocols span EMC chambers, durability tracks, and climatic exposure facilities. Demand clusters in Michigan and Stuttgart where OEMs maintain proximity to regulatory submission offices. ISO 26262 functional safety certification requirements extend program timelines and elevate independent third-party demand.
- Design Engineering:CAD-based geometry development and packaging optimization for body structures and thermal systems.
- Prototyping:Rapid manufacturing of concept vehicles, mule chassis, and pre-series components using additive and subtractive methods.
- Product Lifecycle Management:Configuration management, change control, and requirements traceability across distributed engineering teams.
- Documentation:Technical writing for homologation submissions, service manuals, and regulatory filing packages.
Established volume favors Simulation Services; emerging adoption favors Testing & Validation.
Technology:
Application criticality separates technologies commanding premium pricing from those facing commoditization pressure.
- Software Development:Operating system porting, middleware integration, and application layer coding for software-defined vehicle architectures. EV startups in California and Texas drive fastest expansion as they outsource entire digital cockpit and ADAS stacks to preserve cash runway. UN R155 cybersecurity mandates embed compliance checkpoints throughout development workflows.
- Embedded Systems:ECU hardware-software co-design for powertrain control, battery management, and chassis domain controllers. Japanese and German OEMs maintain captive competence here, limiting outsourcing to surge capacity during platform launches. Functional safety requirements under ISO 26262 constrain supplier qualification to pre-certified partners.
- CAD/CAM:Geometric modeling, surface development, and manufacturing process planning for stamped and cast components.
- CAE:Finite element analysis, computational fluid dynamics, and multi-body simulation for structural and thermal performance prediction.
- Vehicle Dynamics:Ride, handling, and steering calibration through simulation and physical prototype testing.
- Control Systems:Algorithm development for closed-loop control of motors, brakes, and suspension actuators.
Software Development climbs the fastest; Embedded Systems retains the deepest margin pool.
Client Type:
Procurement sophistication varies sharply between integrated manufacturers and specialized component suppliers.
- OEMs:Full-vehicle manufacturers outsourcing discrete work packages while retaining systems integration authority. European and North American volume producers dominate contract value, with electrification programs exceeding captive engineering capacity. EU AI Act traceability requirements for autonomous systems favor long-term partnerships over transactional sourcing.
- Tier-1 Suppliers:Component and subsystem manufacturers seeking engineering support to preserve margin on commoditized hardware. Bosch, Continental, and Denso extend outsourcing relationships into software-defined domains where internal competence gaps have emerged.
- Aftermarket Providers:Conversion specialists and performance tuners requiring homologation support for modified vehicles.
- Vehicle Assembly Plants:Contract manufacturers and joint venture facilities needing localization engineering for regional market entry.
- Engineering Consultants:Specialist boutiques subcontracting overflow work or accessing specialized simulation infrastructure.
- Research Institutes:Academic and government laboratories pursuing pre-competitive technology development with industry co-funding.
OEMs anchor current revenue concentration; Tier-1 Suppliers represent the steepest expansion trajectory.
Application:
Electrification intensity and software content determine outsourcing penetration by vehicle domain.
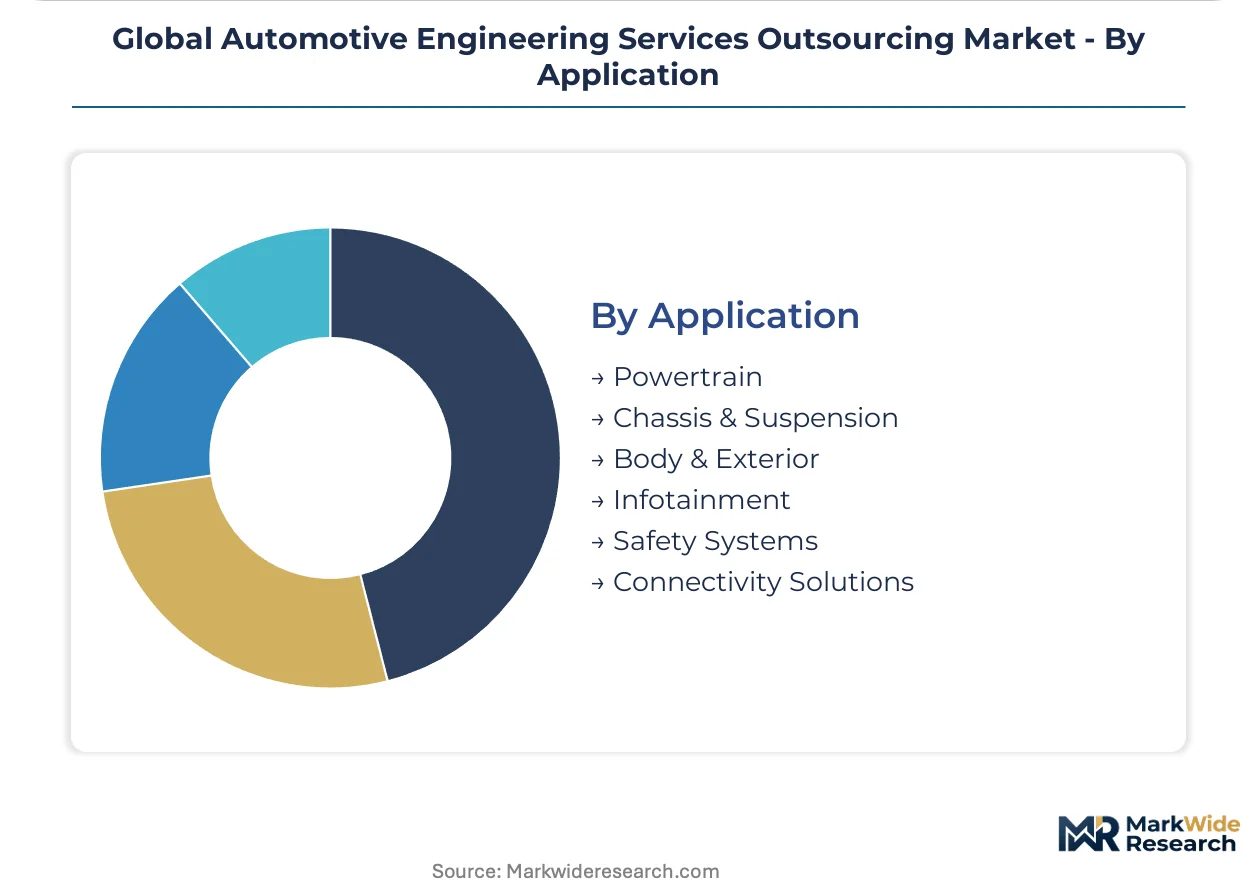
- Powertrain:Engine, transmission, and electric drive unit development spanning thermal management, NVH optimization, and efficiency calibration. EU F-Gas Regulation and EPA emissions standards compel zero-emission platform investment that exceeds European OEM captive capacity. Battery electric architectures eliminate legacy mechanical complexity while introducing thermal runaway prevention and cell balancing challenges.
- Connectivity Solutions:V2X communication modules, telematics platforms, and over-the-air update infrastructure. Chinese OEMs lead deployment volume, with MIIT certification requirements driving localization engineering demand. Cybersecurity validation under UN R155 and ISO/SAE 21434 extends development timelines beyond traditional hardware programs.
- Chassis & Suspension:Structural design, kinematics optimization, and ride control system integration.
- Body & Exterior:Structural crashworthiness, aerodynamic efficiency, and manufacturing process design.
- Infotainment:Display integration, audio systems, and human-machine interface development.
- Safety Systems:Airbag deployment, restraint system optimization, and structural crash energy management.
Powertrain commands the largest contract value; Connectivity Solutions gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German automotive clusters to Asian component suppliers, anchoring Europe's densest engineering services corridor. This maritime infrastructure underwrites just-in-time delivery of prototype parts and simulation data exchanges across the North Sea-Baltic rim.
United States
EV startups in Austin and the Bay Area outsource entire digital cockpit stacks to preserve cash runway during platform development. The Inflation Reduction Act's domestic battery manufacturing subsidies attract engineering investment toward Michigan and Tennessee facility design. Detroit maintains proximity to NHTSA submission offices, concentrating testing and validation procurement.
Germany
Stuttgart and Munich OEMs exceed captive engineering capacity for zero-emission platform development under EU Green Deal mandates. The KBA type-approval process drives simulation services procurement to satisfy regulatory submission requirements. Wolfsburg and Ingolstadt anchor powertrain electrification programs that pull work from traditional internal R&D departments.
China
MIIT certification requirements for V2X modules drive localization engineering demand in Shanghai and Shenzhen. The Yangtze River Delta hosts the fastest expansion of software-defined vehicle architectures among domestic OEMs. CATL's battery ecosystem in Ningbo creates adjacent outsourcing demand for thermal management and cell balancing engineering.
India
The PLI scheme for automotive manufacturing attracts global OEMs establishing local engineering centers in Pune and Chennai. Domestic capacity for homologation support and localization engineering expands around Bangalore's embedded software talent pool. Tata Motors and Mahindra deepen outsourcing relationships to preserve margin on commoditized hardware programs.
Japan
METI's carbon neutrality roadmap accelerates powertrain electrification investment beyond Toyota and Honda captive capabilities. Nagoya's Chubu region maintains embedded systems competence for ECU hardware-software co-design, limiting outsourcing to surge capacity. Yokohama and Tokyo house tier-1 suppliers extending engineering relationships into software-defined domains.
Global Automotive Engineering Services Outsourcing Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory certification depth, creating a tiered structure where scale advantages clash with niche expertise. The vendor base clusters around three strategic archetypes: diversified IT conglomerates with automotive verticals, pure-play engineering specialists with testing infrastructure, and tier-1 supplier spin-offs preserving captive relationships. Dominant competitive moves include portfolio diversification into software-defined vehicle domains and geographic expansion through nearshore delivery centers in Eastern Europe and Mexico.
Within the pure-play engineering tier, AVL List GmbH and Bertrandt AG exemplify contrasting specialization strategies—Graz-based powertrain simulation dominance versus German body-in-white structural design focus. Capgemini Engineering occupies a position bridging IT services depth with embedded systems credibility, anchoring long-term contracts through software-defined vehicle program integration. These three entities represent the spectrum from infrastructure-heavy testing specialists to digitally-native platform integrators.
| Leading Market Players |
|---|
| Capgemini Engineering |
| AVL List GmbH |
| Bertrandt AG |
| HCL Technologies |
| IAV GmbH |
| Tech Mahindra |
| Wipro |
| L&T Technology Services |
| EDAG Group |
| Others |
Supply & Pricing Matrix
HPC cluster utilization rates at German simulation centers establish minimum viable scale thresholds that filter out sub-scale competitors and compress price floors for physics-based modeling services. EU Green Deal compliance mandates intensify demand for KBA-certified validation, embedding certification premiums into contract structures while semiconductor supply volatility forces buyers toward longer-term capacity commitments.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations, with OEMs securing preferential rates for multi-year software-defined vehicle programs while tier-1 suppliers face standard-rate exposure on surge capacity. Price differentiation rests on ISO 26262 certification grade and geographic delivery cost, with German-proximate engineering centers commanding premiums over Eastern European alternatives. Cost compression in embedded software development is intensifying because EV startups prioritize cash preservation over capability depth. Tier-1 suppliers exhibit highest price sensitivity due to margin pressure on commoditized hardware, while premium OEMs prioritize certification breadth over unit cost.
Supply Chain Analysis
Prototype component inventory lead times stretch across Taiwan, South Korea, and Germany as semiconductor fabrication concentration creates input volatility for ECU development schedules. Raw material dependencies center on advanced silicon wafers, rare earth magnets for motor assemblies, and lithium-ion cell chemistry variations. Single-source vulnerability in Taiwan semiconductor fabrication poses structural risk to embedded systems prototyping timelines. Distribution runs through tier-1 supplier engineering centers in Stuttgart, Detroit, and Nagoya, with just-in-time data exchanges replacing physical component flows for simulation-heavy programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architectures represent a high-growth disruption, with continuous integration pipelines compressing traditional program phases and embedding outsourcing partners deeper into OEM operational workflows than prior regulatory cycles permitted.
For Market Incumbents: Shield core powertrain simulation franchises by embedding ISO 26262 and AI governance competencies ahead of EU AI Act enforcement, while securing captive capacity in Eastern European delivery centers to defend margin position against cost-optimized entrants. Threat concentration sits with digitally-native platform integrators acquiring embedded systems credibility through vertical hiring.
For New Entrants and Emerging Players: Certification fast-tracks through dual ISO 26262 and UN R155 accreditation open white-space in cybersecurity validation, where provider capacity constraints outstrip demand expansion. Target tier-1 supplier software-defined domain gaps in Japan and Germany, where captive competence erosion exceeds outsourcing willingness. Go-to-market leverage rests on consumption-based engagement models that displace fixed-fee structures at EV startups.
For Investors and Strategic Acquirers: Pure-play engineering specialists with testing infrastructure and regional regulatory relationships represent acquisition target archetypes, as diversified IT conglomerates seek automotive vertical credibility. Long-term viability hinges on software-defined vehicle program integration depth rather than discrete service bundling. Signal to watch: consolidation of validation contracts with dual functional safety and AI governance competencies at European OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Continuous integration pipelines embed outsourcing partners into OEM operational workflows permanently. |
| Battery Supply Agreement | CATL ecosystem proximity in Ningbo creates adjacent thermal management engineering demand. |
| Geographic Manufacturing Footprint | Michigan and Tennessee facility design attracts engineering investment under IRA domestic subsidies. |
| Platform Standardization | Zonal E/E architectures reduce legacy CAN bus validation gaps that prolong program timelines. |
| Charging Infrastructure Partnership | V2X module localization requirements under MIIT certification drive Shanghai engineering center expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and dealership operations heads. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings, and customs/trade records. Bottom-up segment sizing triangulated against top-down market boundary checks.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from trend extrapolation anchored in named regulatory inflection points and technology adoption curves. Industry-specific inputs included EU Green Deal implementation timelines and MIIT certification requirement phases.
The analysis sits within stated boundaries; outcomes outside sustained electrification investment levels or semiconductor supply normalization would require recalibration. Forecasts reflect documented assumptions around regulatory enforcement intensity and platform standardization velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Authorized Car Service Center Market
Automotive Services
North America Car Wash Market
Automotive Services
Automotive Repair and Service Market
Automotive Services
GCC Car Rental Market
Automotive Services
France Car Rental Market
Automotive Services
United States Automotive Service Market
Automotive Services
Americas MAP Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Automotive Digital Services Market
Automotive Services
Onboard Maintenance Systems Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Online Car-Hailing Service Market
Automotive Services
Qatar Car Rental Market
Automotive Services
Motorsports Market
Automotive Services
Malaysia Car Wash Service Market