
 India Electric Vehicle Financing Market | 2026-2036
India Electric Vehicle Financing Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Vehicle Financing Market Foresight
Aftermarket battery residual-value assessment is tilting from informal dealer estimates toward structured third-party certification. State Bank of India leverages its rural branch density to originate two-wheeler EV loans in tier-3 towns. ICICI Bank anchors its position through digital underwriting APIs integrated with OEM sales platforms. Mahindra & Mahindra Financial Services specializes in captive financing for commercial three-wheeler fleets tied to its vehicle manufacturing arm.
India electric vehicle financing encompasses credit instruments, lease structures, and subscription contracts collateralized by battery-electric or hybrid-electric mobility assets, where loan-to-value ratios typically range from 75% to 85% depending on vehicle segment and borrower credit tier. Its primary purpose channels institutional liquidity into EV acquisition while managing residual-value risk across battery degradation curves. Two-wheeler and three-wheeler product categories dominate disbursement volumes due to lower ticket sizes and faster payback periods for gig-economy riders. Non-banking financial companies compete aggressively on approval speed, often disbursing within 48 hours against banks' longer documentation cycles.
RBI's priority-sector lending mandate for EV assets, SEBI's green bond framework, and state-level EV policies in Maharashtra and Karnataka collectively shape capital availability and interest-rate subsidies for borrowers. BIS certification requirements for charging infrastructure interoperability indirectly influence fleet-operator financing decisions by de-risking asset utilization rates. Stakeholders must monitor how battery-swapping standardization and dynamic electricity tariffs reshape residual-value models and refinancing structures.
Market Dynamics
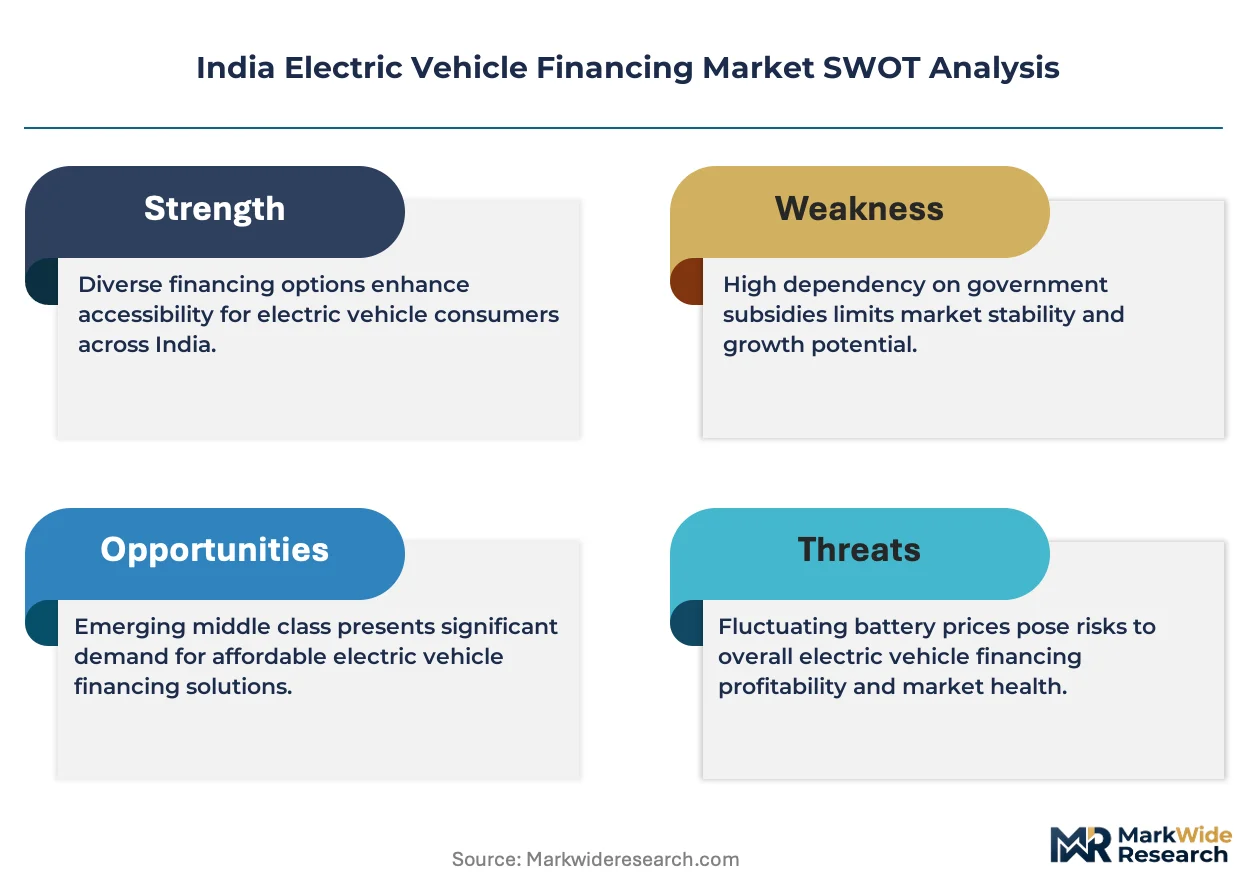
Priority-sector lending mandates from RBI are compressing cost-of-capital spreads between conventional auto loans and EV-backed instruments, forcing lenders to rebuild underwriting models around battery degradation curves rather than engine-hour depreciation tables.
Growth Catalysts
- FAME-II subsidy stack:Central purchase incentives combine with state-level exemptions on road tax and registration fees, reducing effective acquisition cost for fleet operators in Maharashtra and Karnataka.
- Last-mile logistics electrification:E-commerce fulfillment networks are mandating zero-emission last-mile fleets, creating captive demand for three-wheeler financing with fast payback periods.
- Battery-swapping infrastructure:Standardized interoperable swapping stations are de-risking residual-value uncertainty, enabling lease structures with lower monthly obligations.
Market Restraints
- Lithium-ion import dependency:Cell and pack supply concentrates in China, exposing financiers to currency volatility and supply disruption risk in collateral valuation.
- Charging interoperability gaps:BIS certification timelines for connector standards create asset-stranding risk for fleet operators deploying before protocol finalization.
- Secondary market illiquidity:Absence of organized resale channels for used EVs compresses recovery rates on defaulted loans compared to internal combustion assets.
Strategic Opportunities
- Tier-3 town penetration:Rural branch networks can originate two-wheeler EV credit in Uttar Pradesh and Bihar where two-wheeler density exceeds four-wheeler ownership.
- SEBI green bond framework:Issuance of asset-backed securities against EV loan pools accesses institutional ESG capital at spreads below bank wholesale funding.
- Telematics-embedded underwriting:Real-time battery state-of-health data from OEM-connected platforms enables dynamic LTV adjustments and usage-based pricing.
Industry Challenges
- Residual-value modeling talent scarcity:Credit teams lack actuarial expertise in lithium-ion degradation curves, forcing reliance on vendor-supplied projections.
- Multi-registrar lien perfection:Uniform Commercial Code-equivalent filings across state RTOs create documentation friction for national fleet financiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Vehicle Financing Market |
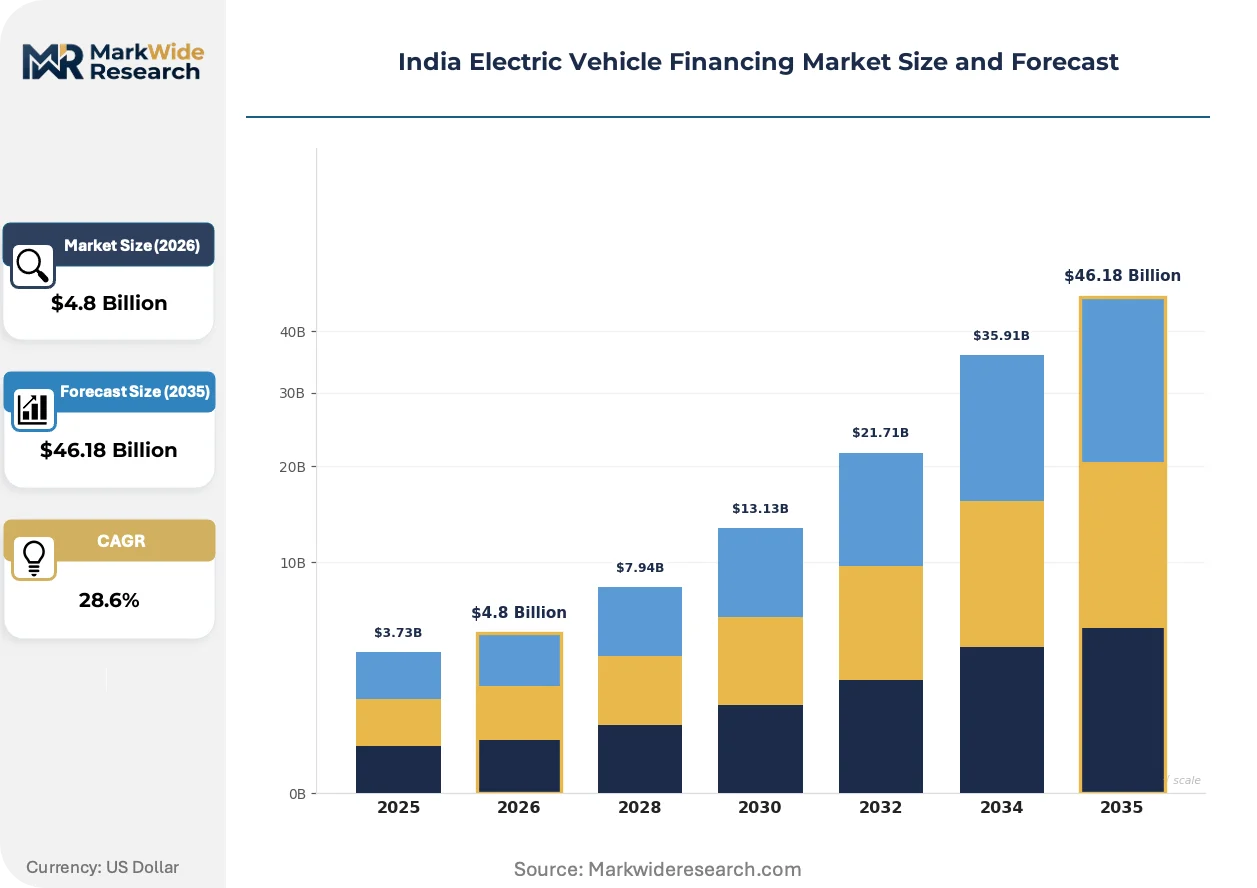
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Wheelers, Three-Wheelers, Passenger Vehicles, Commercial Vehicles Service Type: Leasing, Loan, Subscription, Deferred Payment Financing Source: Banks, Non-Banking Financial Companies, Credit Unions, Peer-to-Peer Lending Customer Type: Individuals, Fleet Operators, Corporates, Government |
| Companies Covered | State Bank of India, ICICI Bank, Mahindra & Mahindra Financial Services, Shriram Transport Finance Company, Tata Capital Limited, HDFC Bank, Cholamandalam Investment and Finance Company, Revfin, Ecofy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Vehicle Financing Market Shifts & Advancements
Financing structures are migrating from simple term loans toward asset-light subscription and lease products where battery ownership separates from vehicle shell ownership, fragmenting collateral management across multiple counterparty types.
Telematics-integrated underwriting is collapsing the information asymmetry between lender and borrower. Real-time state-of-charge, cycle count, and thermal event data streams from OEM cloud platforms enable dynamic interest rate adjustments tied to actual battery health rather than chronological age. Fleet operators in Bengaluru and Hyderabad are piloting usage-indexed repayment schedules where monthly obligations fluctuate with kilometers logged.
RBI's priority-sector lending classification for EV assets is compressing risk-weighted capital requirements for scheduled commercial banks. The regulatory change permits lower provisioning against EV loan portfolios compared to conventional auto finance, redirecting bank treasury allocation toward electric two-wheeler and three-wheeler segments. Regional rural banks with granular branch presence are originating paperless applications through Aadhaar-linked e-KYC workflows.
Subscription-based mobility procurement is displacing outright purchase among gig-economy delivery riders in Mumbai and Delhi NCR. Platform-integrated financing bundles vehicle, battery, maintenance, and insurance into per-day or per-delivery charges, eliminating down-payment barriers. NBFCs are embedding themselves into OEM sales platforms through API-based instant approval systems that disburse within hours against traditional bank documentation cycles lasting days.
India Electric Vehicle Financing Market Segmentation
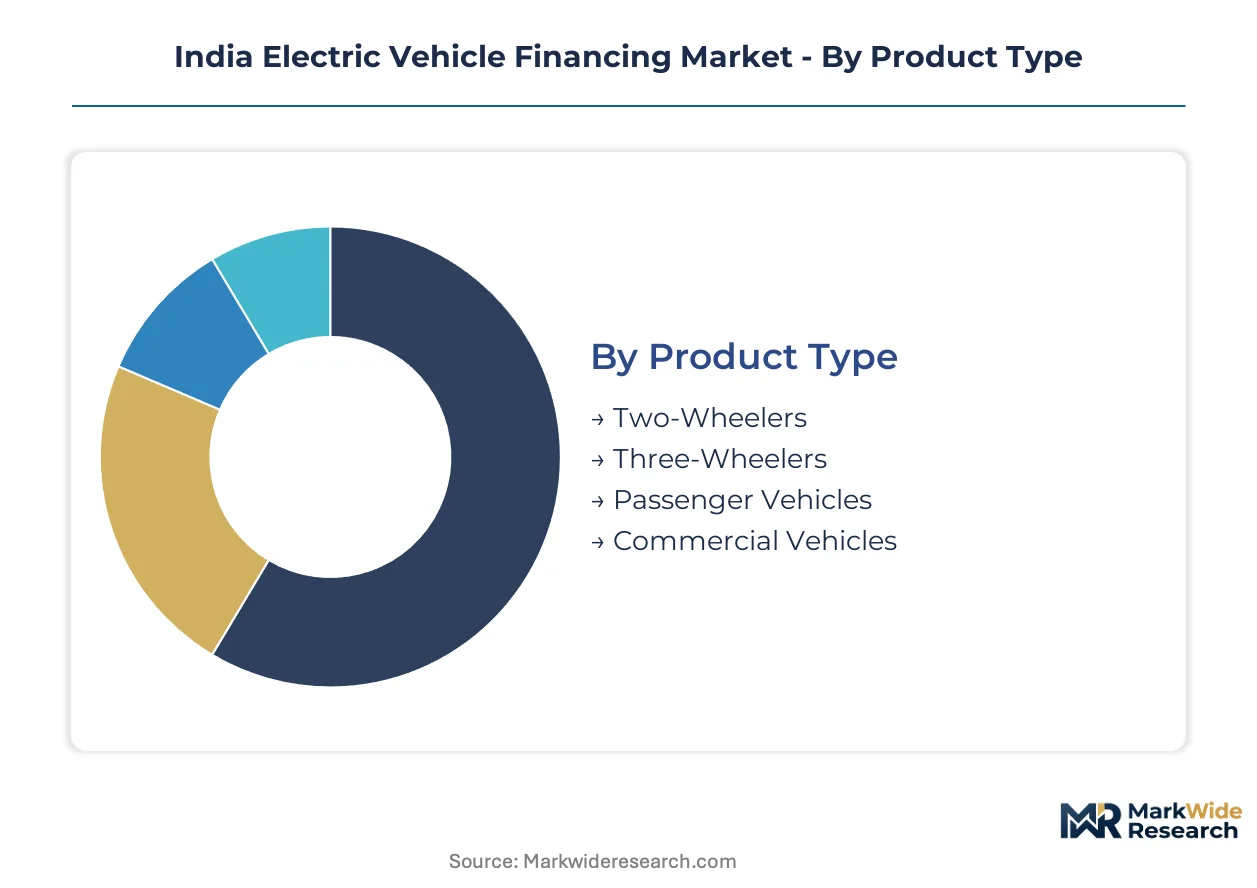
Financing structures in India's EV market fragment sharply by asset durability and payback velocity. Product type determines collateral depreciation curves, while customer segmentation dictates risk-weighted capital allocation across rural branch networks and digital underwriting platforms.
Product Type:
Two-wheelers turn over fastest with 18-24 month replacement cycles, while commercial vehicles stretch across 5-7 year tenures requiring residual-value guarantees.
- Two-Wheelers:Battery-electric scooters and motorcycles with 2-3 kWh packs dominate disbursement volumes through sub-₹1.5 lakh ticket sizes. Gig-economy delivery riders in Bengaluru and Hyderabad cluster here, drawn by 48-hour NBFC approvals and FAME-II subsidy stacks that compress effective acquisition cost below internal combustion equivalents.
- Three-Wheelers:Commercial passenger and cargo variants with swappable battery configurations anchor last-mile logistics financing. E-commerce fulfillment mandates from Flipkart and Amazon force fleet electrification in Maharashtra and Karnataka, where state road-tax exemptions compound central incentives.
- Passenger Vehicles:Four-wheeler private transport carries longer documentation cycles and stricter CIBIL thresholds, concentrating among salaried borrowers in Delhi NCR and Mumbai.
- Commercial Vehicles:Electric buses and light trucks require structured lease-back arrangements with municipal corporations or state transport undertakings, tying repayment to kilometer-based revenue shares.
Two-wheelers anchor the volume base while three-wheelers gain share at the steepest rate.
Service Type:
Cost tier stratification separates capital-heavy ownership from operational expenditure models preferred by cash-constrained fleet operators.
- Leasing:Full-service contracts bundle vehicle shell, battery, maintenance, and insurance into fixed monthly obligations. Battery-swapping standardization by BIS enables residual-value certainty that supports 3-4 year lease terms for three-wheeler fleets in Chennai and Pune.
- Loan:Traditional term financing with 75-85% LTV ratios dominates individual borrower uptake, though documentation friction pushes approval timelines toward 5-7 days at scheduled commercial banks.
- Subscription:Per-day or per-delivery charging models eliminate down-payment barriers for gig workers, with platform-embedded NBFCs disbursing through API integrations at OEM dealerships.
- Deferred Payment:Balloon structures with low initial EMIs and residual-value buyout options target corporate fleet managers seeking balance-sheet optimization.
Loan products still dominate absolute rupee volumes, though subscription structures are climbing fastest among delivery-platform contractors.
Financing Source:
Application concentration varies by approval velocity, with rural penetration favoring branch density over digital sophistication.
- Banks:Scheduled commercial lenders leverage RBI priority-sector lending mandates to compress risk-weighted capital requirements. State Bank of India's rural network originates two-wheeler paper in Uttar Pradesh and Bihar through Aadhaar-linked e-KYC.
- Non-Banking Financial Companies:Agile underwriting with 24-48 hour turnaround captures gig-economy borrowers excluded by traditional credit scoring. ICICI Bank's digital APIs and specialized EV NBFCs embed at OEM point-of-sale terminals.
- Credit Unions:Cooperative structures in Kerala and Tamil Nadu mobilize member deposits for community-based EV two-wheeler pools with peer-guarantee mechanisms.
- Peer-to-Peer Lending:Platform-mediated retail capital channels into individual borrower pools, though regulatory ambiguity under RBI's P2P master directions constrains scale.
Banks control the deepest capital pools while NBFCs capture the steepest expansion trajectory in gig-economy segments.
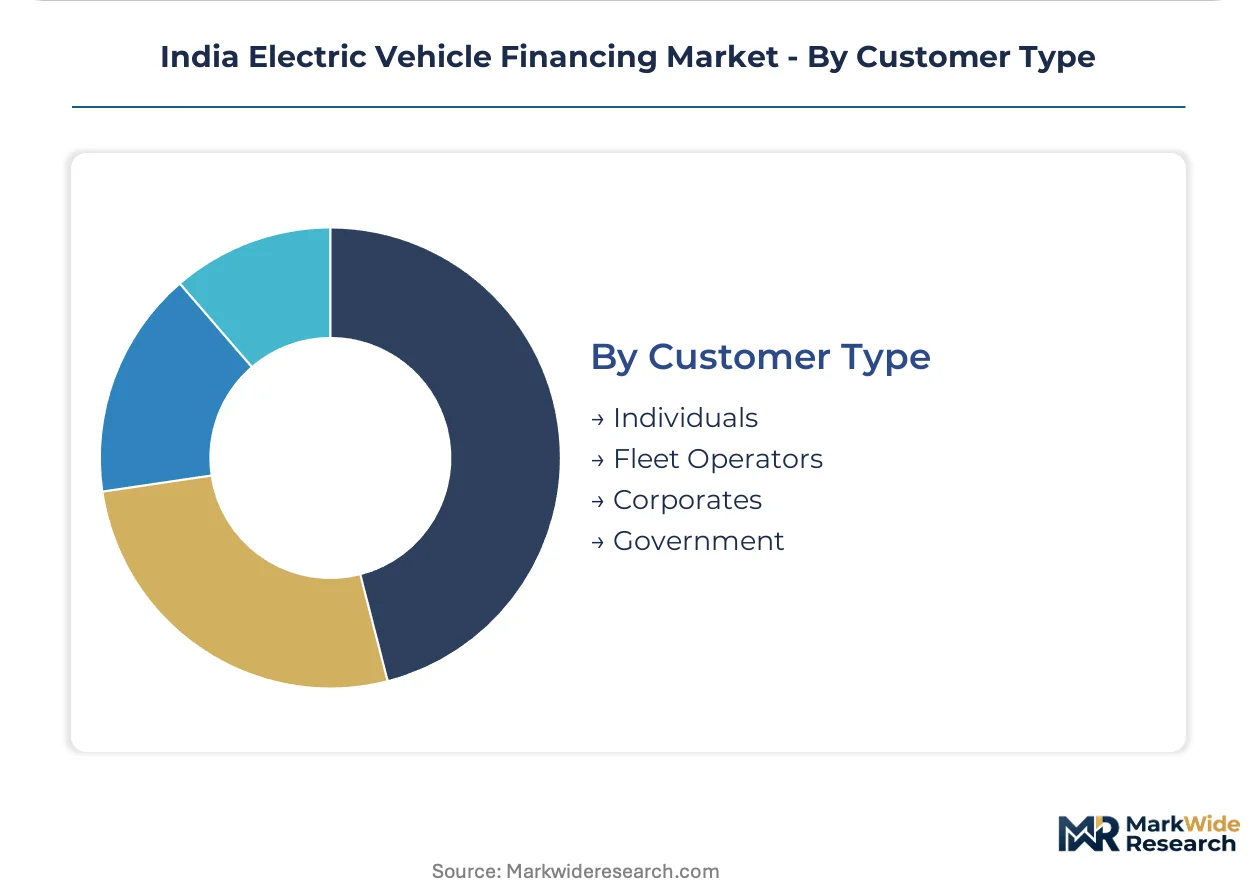
Customer Type:
Volume concentration tilts toward institutional procurement as fleet operators aggregate demand across standardized vehicle configurations.
- Individuals:Salaried and self-employed borrowers with CIBIL scores above 700 access priority-sector lending rates. Two-wheeler density in tier-3 towns drives origination through regional rural banks.
- Fleet Operators:Aggregated demand from logistics and ride-hailing platforms commands bulk pricing and standardized service contracts. Mahindra & Mahindra Financial Services structures captive financing for commercial three-wheeler deployments tied to manufacturing volume commitments.
- Corporates:ESG-mandated vehicle procurement programs at IT and consulting firms drive passenger EV leasing through SEBI green bond-funded structures.
- Government:State transport undertakings and municipal corporations issue tender-backed payment guarantees for electric bus fleets, though fiscal stress in Punjab and Rajasthan delays disbursement timelines.
Fleet operators anchor institutional capital deployment while individual borrowers sustain the broadest geographic origination footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for EV financing varies sharply across Indian states, with price-sensitive borrowers in Uttar Pradesh and Bihar driving two-wheeler origination through rural branch networks, while fleet operators in Maharashtra and Karnataka absorb premium lease structures with lower rate sensitivity.
Maharashtra
Mumbai-based fleet operators command bulk pricing for three-wheeler deployments tied to e-commerce fulfillment mandates. The state road-tax exemption stacks with FAME-II subsidies, compressing effective acquisition cost by nearly one-third. Pune and Nashik industrial corridors anchor captive financing arrangements for last-mile logistics operators.
Karnataka
Bengaluru's ride-hailing density generates subscription-model uptake among gig-economy delivery riders seeking zero down-payment structures. The state's EV policy mandates 100 percent road-tax exemption through 2027. Hosur and Tumkur manufacturing clusters feed vehicle supply into adjacent Tamil Nadu financing networks.
Gujarat
Surat and Ahmedabad textile belt fleet operators prioritize commercial three-wheeler procurement with battery-swapping configurations. Gujarat's industrial incentive schemes attract NBFC back-office operations for digital underwriting scale. The Gandhinagar policy corridor coordinates central-state subsidy alignment.
Tamil Nadu
Chennai's automotive supplier ecosystem enables residual-value guarantees for passenger EV leases. State transport undertakings issue tender-backed payment commitments for electric bus fleets. Coimbatore and Madurai tier-3 markets drive two-wheeler origination through cooperative credit structures.
Delhi-NCR
Corporate ESG procurement programs in Gurugram and Noida anchor passenger EV leasing through SEBI green bond-funded structures. The Delhi government's odd-even enforcement and congestion pricing accelerate fleet electrification timelines. Faridabad logistics parks generate institutional demand for light commercial vehicle financing.
India Electric Vehicle Financing Market Competitive Landscape
Scheduled commercial banks and non-banking financial companies split the market along velocity-versus-scale lines. Public sector lenders leverage branch density for rural origination, while NBFCs capture urban gig-economy segments through API-embedded approval systems. Three archetypes dominate: balance-sheet-heavy banks with priority-sector mandates, agile digital NBFCs with OEM platform integration, and captive financiers tied to vehicle manufacturing arms. Competitive intensity centers on approval speed compression and battery residual-value guarantee structures.
Within the public sector tier, State Bank of India anchors rural penetration through Aadhaar-linked e-KYC workflows. ICICI Bank and Mahindra & Mahindra Financial Services occupy distinct positioning vectors—ICICI through digital underwriting APIs integrated at point-of-sale terminals, Mahindra & Mahindra Financial through captive three-wheeler fleet structures tied to manufacturing volume commitments. These three entities exemplify the strategic segmentation between branch-scale origination, platform-embedded velocity, and vertical integration models.
| Leading Market Players |
|---|
| State Bank of India |
| ICICI Bank |
| Mahindra & Mahindra Financial Services |
| Shriram Transport Finance Company |
| Tata Capital Limited |
| HDFC Bank |
| Cholamandalam Investment and Finance Company |
| Revfin |
| Ecofy |
| Others |
Supply & Pricing Matrix
Hosur and Tumkur battery pack assembly clusters feed downstream financing spreads through capacity absorption rates that compress or expand lender margin buffers. RBI priority-sector lending mandates transmit into borrower-facing rates while lithium-ion import costs transmit upstream from Ningbo and Shenzhen port congestion.
Pricing Analysis
After-sales battery residual-value guarantees drive lifetime value capture across lease structures. Three-tier pricing stratifies across premium OEM-integrated financing, standard bank term loans, and economy NBFC subscription products. Pricing pressure stems from 48-hour approval velocity competition among non-bank lenders. Gig-economy delivery riders exhibit highest price sensitivity while municipal fleet managers absorb premium lease rates for residual-value certainty.
Supply Chain Analysis
Supplier-financing facilities from cell manufacturers extend payment terms to domestic pack assemblers. China, South Korea, and Japan anchor cathode active material and separator supply. Lithium carbonate and nickel sulfate feedstock dependencies concentrate pricing volatility risk. Tariff exposure on cell imports from China creates margin compression for unhedged financiers. Distribution runs through OEM-embedded NBFC APIs and rural bank branch networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across vehicle segments, financing structures, and geographic penetration creates multiple niche entry points. Subscription-model displacement of term loans among gig-economy riders exemplifies demand-side shift opening white-space.
For Market Incumbents: Pre-empt fintech platform integration by embedding underwriting APIs at OEM point-of-sale terminals before specialized EV NBFCs consolidate dealer relationships. Build captive battery residual-value assessment capabilities to reduce vendor-projection dependency. Vertical integration into telematics data partnerships with Mahindra and Tata Motors strengthens collateral monitoring. For New Entrants and Emerging Players: Tier-3 towns in Uttar Pradesh and Bihar with two-wheeler density exceeding four-wheeler ownership represent the most penetrable entry point for rural branch-light digital origination. Battery-swapping standardization by BIS enables lease-structure innovation with lower monthly obligations. Partner with regional rural banks for Aadhaar-linked e-KYC distribution rather than building de novo branch networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because RBI priority-sector lending mandates compress risk-weighted capital requirements for EV portfolios versus conventional auto finance. Acquisition targets should display OEM-embedded API infrastructure and granular battery health data access. Monitor FAME-III subsidy announcement timing as inflection indicator for fleet-operator procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Embedded Underwriting Platform | Real-time battery state-of-health data from OEM cloud platforms enables dynamic LTV adjustments. |
| Battery Residual-Value Guarantee Structure | Third-party certification by BIS-accredited agencies de-risks lease-end obligations for fleet operators. |
| Priority-Sector Lending Portfolio Buildout | RBI-mandated lower risk weights redirect bank treasury allocation toward electric two-wheeler segments. |
| OEM-Integrated API Distribution | Instant approval systems at dealership terminals collapse NBFC 48-hour advantage to near-zero. |
| Green Bond Securitization Program | SEBI framework access channels institutional ESG capital at spreads below bank wholesale funding. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers at Flipkart and Amazon, NBFC underwriting heads, RBI regulatory affairs officers, and SEBI green bond issuers. Secondary validation drew from RBI circulars on priority-sector lending, SEBI green bond framework disclosures, BIS certification timelines for charging infrastructure, and state EV policy documents from Maharashtra and Karnataka. Bottom-up loan disbursement estimates triangulated against top-down priority-sector lending targets.
Calibration anchored volume projections to observed FAME-II subsidy uptake rates and state-level road-tax exemption utilization across the analysis window. Segmentation dimensions modeled include vehicle class, financing structure type, customer archetype, and geographic state cluster. CAGRs derived from compounding annual disbursement growth assumptions tied to fleet electrification mandates and gig-economy rider expansion. Battery degradation curve assumptions and residual-value recovery rates informed lease-structure penetration forecasts.
Practitioners should monitor subsidy scheme renewal timing, BIS charging standard finalization, and lithium price volatility for early signals of forecast deviation. Assumptions reflect current regulatory stance and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
EV Thermal Management System Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
Light Electric Vehicle Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
India Electric Vehicle Market