
 Global Cars-As-A-Service (CaaS) Market | 2026-2036
Global Cars-As-A-Service (CaaS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cars-As-A-Service (CaaS) Market Intelligence
The unbundling of traditional vehicle ownership costs into flexible subscription tiers is shifting consumer and corporate procurement preferences. Legacy rental giants like Hertz Global Holdings leverage their extensive fleet and physical locations to offer short-term subscription services. In contrast, automakers such as BMW Group and Volkswagen AG differentiate through premium brand experiences and direct-from-manufacturer vehicle access. Enterprise Holdings also competes by focusing on the corporate fleet management segment with comprehensive service packages.
Cars-as-a-Service provides users with access to vehicles on a temporary basis, typically through a subscription or per-use model, without the burdens of ownership. These services rely on digital platforms that manage booking, payment, and vehicle access, often using telematics to monitor vehicle health and location data. While ride-hailing and car leasing constitute mature service types, car subscription models represent the fastest-growing segment. Corporate end-users increasingly prefer these subscription models for their predictable costs and fleet flexibility over traditional purchasing.
The General Data Protection Regulation (GDPR) in Europe governs the handling of customer and vehicle telematics data by CaaS providers. Simultaneously, vehicle safety mandates from the US National Highway Traffic Safety Administration (NHTSA) and emissions policies in China influence the types of vehicles deployed in service fleets. Stakeholder success depends on aligning service models with this evolving landscape of data privacy, vehicle safety, and environmental compliance.
Market Dynamics
The structural shift from asset ownership to usage-based access models is the central force defining the Cars-as-a-Service market. This change is propelled by corporate demand for operational flexibility and cost predictability, enabled by digital platforms integrating telematics and fleet management tools.
Growth Catalysts
- Integrated Telematics Platforms:The incorporation of advanced telematics allows for real-time vehicle tracking, predictive maintenance alerts, and driver behavior monitoring, which optimizes fleet efficiency and reduces operational costs for corporate clients.
- Urban Corporate Demand:Strong demand from corporations in dense metropolitan areas, particularly in the United States and Germany, for flexible mobility solutions to supplement or replace traditional company car fleets drives market expansion.
- Environmental Regulations:Emissions policies, such as China's stringent vehicle standards, encourage fleet turnover to newer, compliant models, a process simplified and made less capital-intensive through CaaS subscription models.
Market Restraints
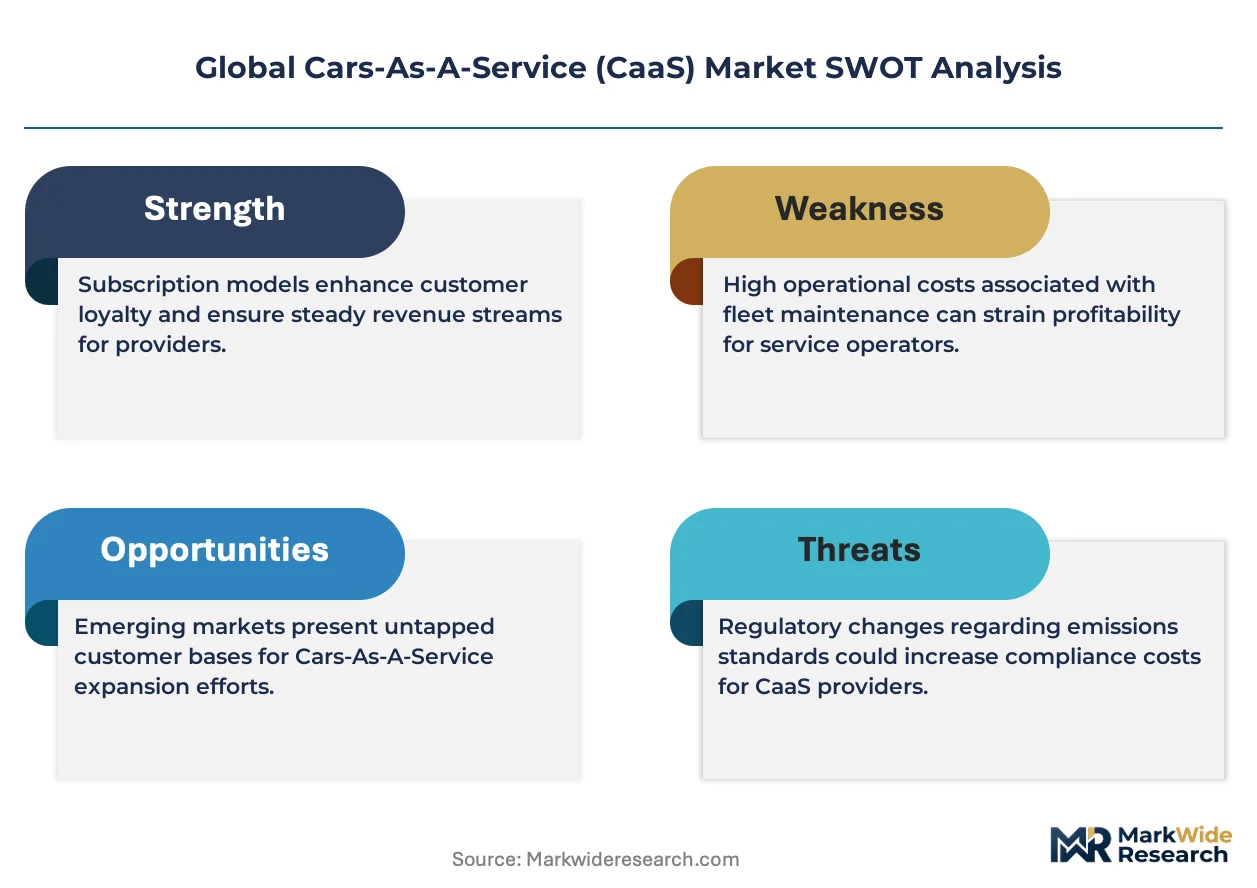
- High Capital Expenditure:The business model requires significant upfront investment in acquiring a large and diverse vehicle fleet, in addition to the capital needed for developing and maintaining the underlying technology platform.
- Data Privacy Compliance:Navigating complex data privacy regulations, notably Europe's GDPR, creates significant compliance burdens and operational costs related to the handling of sensitive customer and vehicle telematics data.
- Competition from Legacy Models:The market faces strong competition from well-established traditional car leasing and daily rental services, which represent familiar and deeply entrenched alternatives for both corporate and individual users.
Strategic Opportunities
- Service Bundling:Providers can create value by bundling vehicle access with ancillary mobility services, such as reserved parking, electric vehicle charging subscriptions, and integrated public transport passes, creating a seamless urban mobility solution.
- Expansion into Secondary Markets:Significant opportunity exists in expanding from primary metropolitan hubs into secondary cities and large suburban zones where car dependency remains high but flexible ownership alternatives are scarce.
- AI-Powered Personalization:The convergence of telematics data with artificial intelligence can enable dynamic pricing, personalized vehicle recommendations, and customized insurance offerings, enhancing user experience and provider profitability.
Industry Challenges
- Logistical Complexity:Managing the end-to-end logistics of vehicle cleaning, maintenance, refueling or recharging, and strategic repositioning to meet demand fluctuations presents a significant and constant operational hurdle.
- Residual Value Risk:CaaS providers bear the full financial risk of accelerated vehicle depreciation, which is exacerbated by rapid technological advancements and shifting consumer preferences for the latest models and features.
- Enterprise System Integration:A primary challenge for serving corporate clients involves the complex technical integration of the CaaS platform with a customer’s existing enterprise resource planning and expense management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cars-As-A-Service (CaaS) Market |
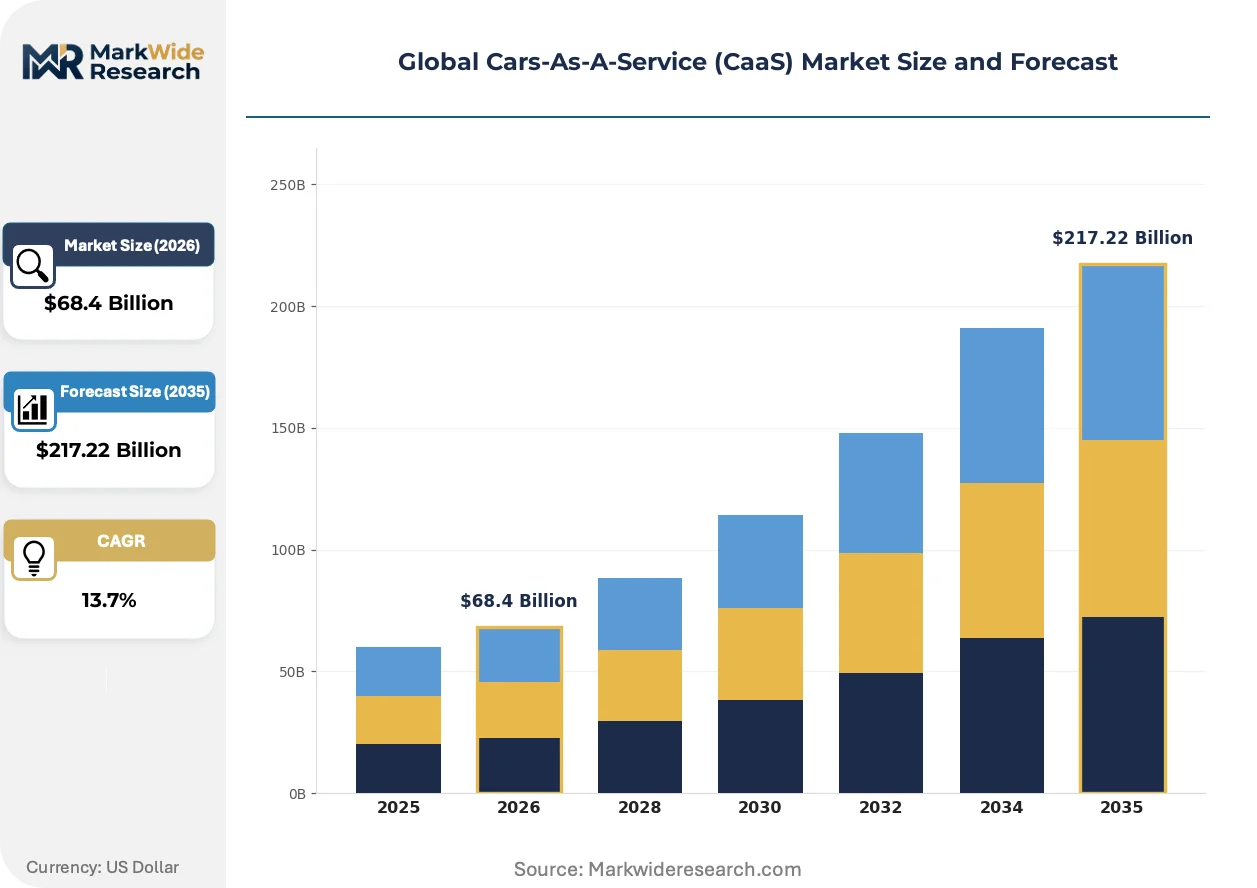
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $217.22 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Car Leasing, Car Subscription, Fleet Management End User: Individuals, Corporates, Government Agencies, Small Businesses Vehicle Type: Electric Vehicles, Sedans, SUVs, Luxury Cars Technology: Mobile Apps, Telematics, AI-based Routing, Blockchain |
| Companies Covered | Hertz Global Holdings, Sixt SE, Avis Budget Group, Enterprise Holdings, LeasePlan/Ayvens, BMW Group, Daimler AG, Volkswagen AG, Zoomcar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cars-As-A-Service (CaaS) Market Strategic Shifts & Innovations
The evolution of CaaS is defined by a push towards hyper-personalization and operational automation. Service differentiation is increasingly based on the sophistication of the underlying data analytics engine, which transforms raw vehicle and usage data into actionable intelligence for both the provider and the end-user.
AI-Enhanced Fleet Operations
Advanced telematics systems generate vast streams of data on vehicle health and usage. Corporate fleet managers are the primary adopters of these systems, seeking to optimize asset utilization and driver safety. Proactive, data-driven fleet management, which predicts maintenance needs and identifies cost-saving opportunities, is overtaking reactive, schedule-based operational models.
Data Governance and Regulatory Scrutiny
Europe's General Data Protection Regulation (GDPR) sets a high bar for the collection and processing of personal data from drivers. This regulation forces CaaS platforms to implement robust data security measures and transparent consent protocols for handling location and behavior information. Providers operating in the EU are most affected, redesigning user interfaces and backend systems to ensure compliance.
Shift to Flexible Procurement Models
A clear preference for flexible, usage-based subscription contracts is displacing traditional multi-year leasing agreements within corporate procurement. This behavioral change disrupts established fleet management channels, favoring digital-native platforms that offer on-demand scalability and simplified billing. The trend is most visible among technology and professional services firms in major economic centers in the United States and Germany.
Global Cars-As-A-Service (CaaS) Market Segmentation
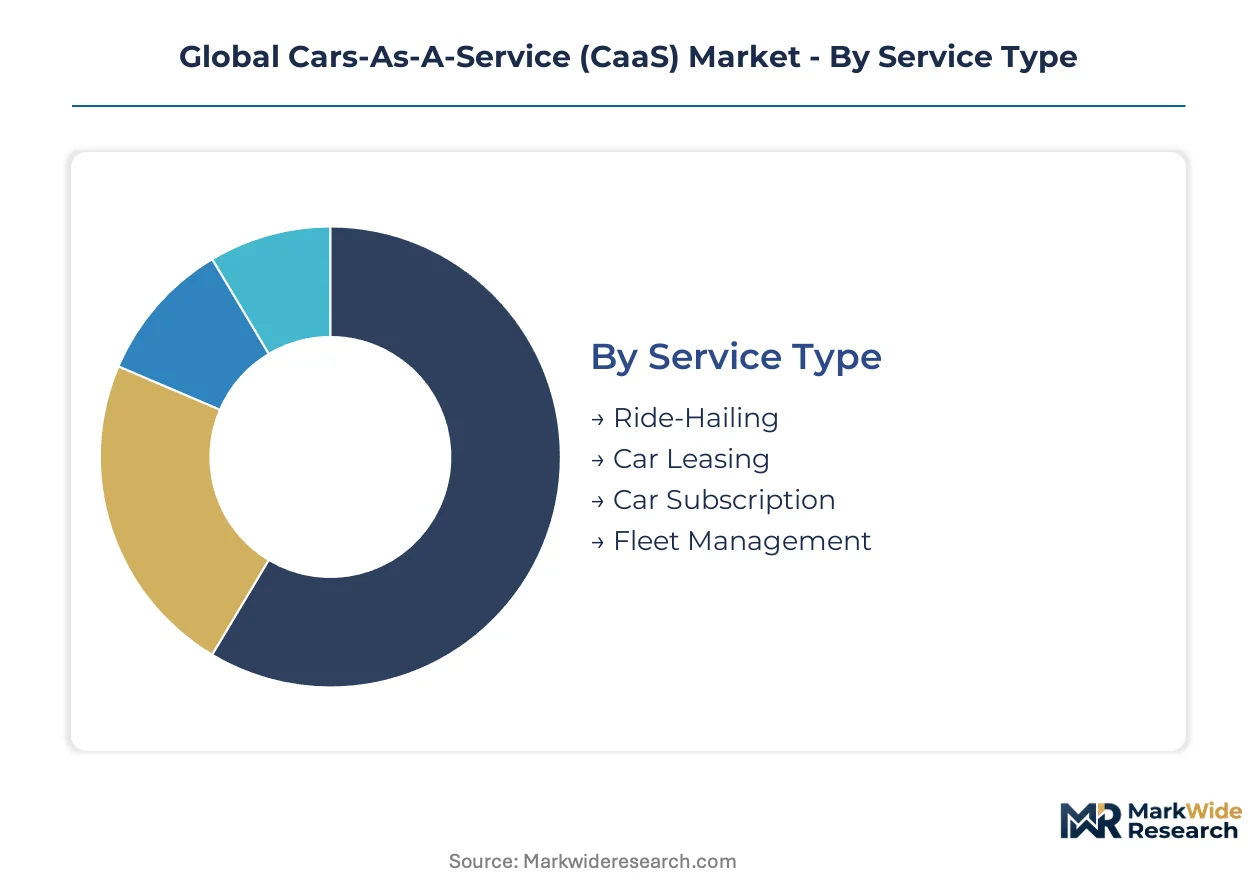
The Cars-as-a-Service market categorizes offerings based on distinct service models, user demographics, vehicle specifications, and enabling technologies. Understanding these segments is crucial for providers to tailor solutions and for corporate clients to optimize their mobility procurement strategies.
Service Type:
Supply concentration within the Cars-as-a-Service market dictates the range of mobility solutions available to end-users.
- Car Subscription:This model provides users with vehicle access on a temporary basis, typically through a flexible subscription, without the burdens of ownership. Demand is concentrating among corporate end-users in major economic centers like the United States and Germany, driven by predictable costs and fleet flexibility.
- Fleet Management:These comprehensive service packages manage corporate vehicle fleets, integrating advanced telematics for vehicle tracking and maintenance scheduling. Corporate clients seeking operational efficiency and reduced costs are the primary adopters for integrated CaaS platforms.
- Ride-Hailing:This service connects passengers with drivers through digital platforms for on-demand transportation.
- Car Leasing:Traditional vehicle leasing offers long-term access to a vehicle for a fixed monthly payment.
Car Leasing absorbs the bulk of installed capacity; Car Subscription is expanding most quickly.
End User:
Customer type segmentation reveals distinct preferences and operational requirements across different user groups.
- Corporates:These entities represent the primary source of demand for integrated CaaS platforms, seeking flexible mobility solutions for employees and operational fleets. Their procurement preferences are shifting from asset ownership to usage-based access models due to cost predictability.
- Individuals:Personal users access vehicles on a temporary basis for private use, often through subscription or per-use models to avoid ownership burdens. This segment is influenced by the unbundling of traditional vehicle ownership costs into flexible tiers.
- Government Agencies:Public sector organizations utilize CaaS for specific fleet needs, often driven by efficiency mandates and budget constraints.
- Small Businesses:Smaller enterprises adopt CaaS to manage mobility costs and access vehicles without significant capital expenditure.
Corporate end-users drive significant volume; Government Agencies are demonstrating accelerating demand.
Vehicle Type:
Vehicle type distribution reflects varying demand volumes for specific car categories within CaaS fleets.
- Electric Vehicles:These vehicles are integrated into CaaS fleets to meet environmental regulations and corporate sustainability goals. Emissions policies in regions like China encourage fleet turnover to newer, compliant models.
- SUVs:Sport Utility Vehicles offer versatility and passenger capacity, making them popular choices for various CaaS applications, including corporate shuttles and family subscriptions. Their demand remains strong across diverse metropolitan areas.
- Sedans:Traditional sedans provide efficient and comfortable transport options, forming a core component of many CaaS offerings.
- Luxury Cars:Premium vehicles cater to high-end subscription services and executive transport needs, differentiating provider offerings.
Sedans continue to maintain a substantial share; Electric Vehicles are gaining traction rapidly.
Technology:
Technology maturity levels influence the operational sophistication and competitive differentiation of CaaS platforms.
- Telematics:Advanced telematics systems enable real-time vehicle tracking, predictive maintenance alerts, and driver behavior monitoring for optimized fleet efficiency. These platforms are crucial for data collection and operational insights.
- AI-based Routing:Artificial intelligence algorithms optimize vehicle deployment, repositioning, and route planning to meet dynamic demand fluctuations. This technology enhances operational efficiency and user experience in dense urban environments.
- Mobile Apps:These applications serve as the primary interface for users to book, manage, and access CaaS vehicles.
- Blockchain:Distributed ledger technology offers potential for secure transaction processing and transparent data sharing within CaaS ecosystems.
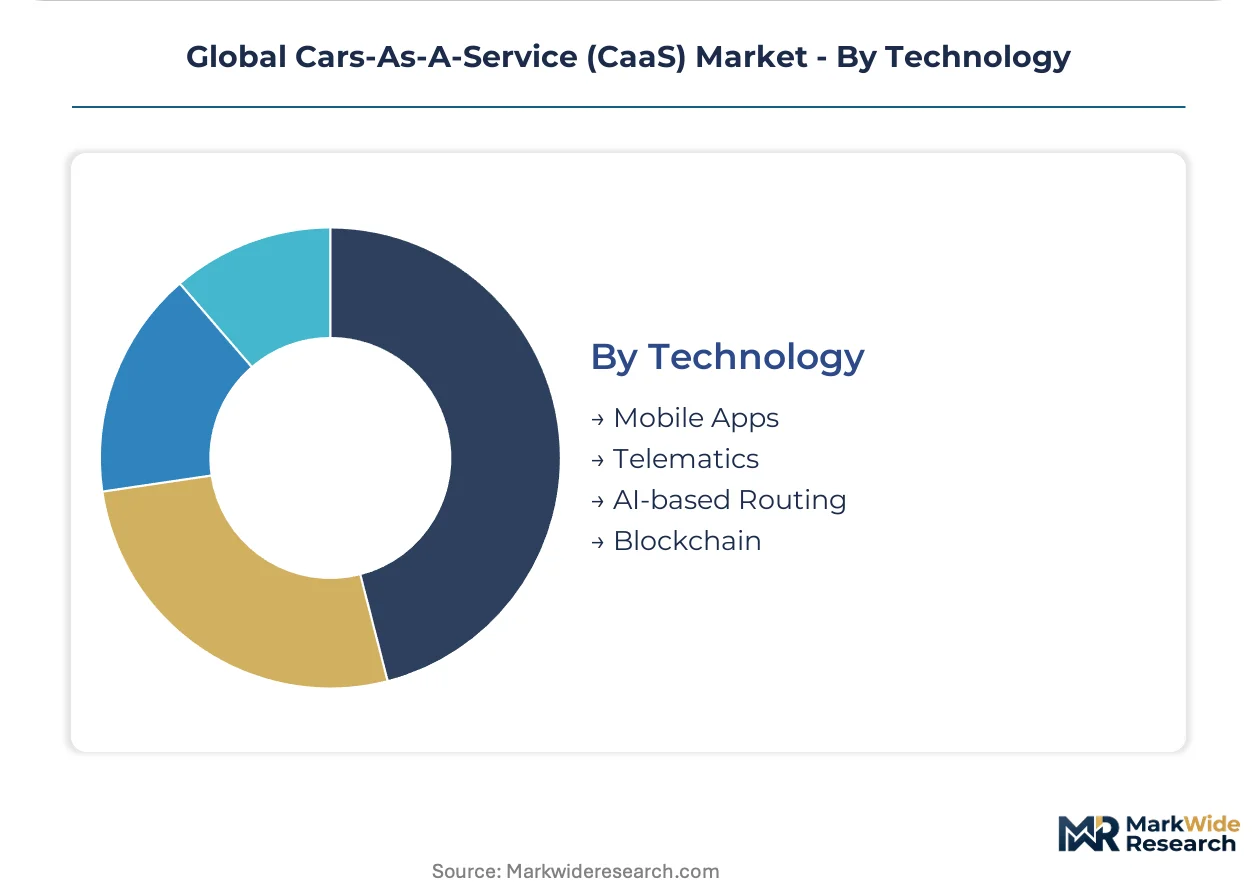
Mobile Apps form the foundational layer for most services; AI-based Routing offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration within major economic hubs like the Silicon Valley in the United States and the Rhine-Ruhr region in Germany drives significant demand for Cars-as-a-Service platforms. These areas benefit from robust corporate activity and a high density of technology and professional services firms. Such localized demand centers foster innovation and scalability for mobility solutions.
United States
United States corporations prioritize flexible mobility solutions for employee fleets, driving CaaS platform adoption. The US National Highway Traffic Safety Administration (NHTSA) influences vehicle types deployed through safety mandates. In the bustling Silicon Valley, technology firms increasingly integrate CaaS for their extensive employee transportation needs.
Germany
German businesses seek cost-predictable and flexible fleet options, particularly in metropolitan areas. Europe's General Data Protection Regulation (GDPR) imposes strict data privacy requirements on CaaS providers in Germany. The automotive heartland around Munich sees manufacturers and service providers piloting next-generation CaaS models.
China
China's aggressive emissions policies accelerate fleet turnover, favoring CaaS models for compliance. The country's dual carbon goals promote electric vehicle integration within CaaS offerings. In Shanghai's dynamic financial district, corporations utilize CaaS platforms to achieve their sustainability objectives.
United Kingdom
United Kingdom businesses increasingly demand operational flexibility and predictable costs for their vehicle fleets. UK data protection regulations, aligned with GDPR principles, mandate robust handling of telematics data by CaaS platforms. London's expansive financial services sector actively adopts CaaS for efficient and scalable employee mobility.
Japan
Japanese corporate clients prioritize efficient fleet management and digital integration for urban operations. Japan's Ministry of Economy, Trade and Industry (METI) supports the development of advanced mobility services. Tokyo's bustling technology and business hubs see CaaS platforms optimizing corporate travel and last-mile delivery services.
Global Cars-As-A-Service (CaaS) Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for market share in the Cars-as-a-Service market. The landscape features a tiered structure, with legacy automotive manufacturers and rental giants alongside digital-native mobility startups. Strategic archetypes include asset-heavy fleet operators, technology-driven platform providers, and brand-focused premium service offerings. Dominant competitive moves involve portfolio diversification into ancillary services and strategic partnerships to expand geographic reach.
Companies like Hertz Global Holdings represent established legacy rental providers, leveraging extensive physical networks and fleet assets for short-term subscriptions. These players often integrate their existing infrastructure to offer new CaaS models. Automakers such as BMW Group differentiate through premium brand experiences and direct-from-manufacturer vehicle access, emphasizing vehicle quality and advanced features. Digital-native platforms like Zoomcar exemplify the pure-play specialists, focusing on flexible subscription models and technology-driven user experiences. These diverse players collectively shape the market's evolving service delivery models and competitive dynamics.
| Leading Market Players |
|---|
| Hertz Global Holdings |
| Sixt SE |
| Avis Budget Group |
| Enterprise Holdings |
| LeasePlan/Ayvens |
| BMW Group |
| Daimler AG |
| Volkswagen AG |
| Zoomcar |
| Others |
Cost & Logistics Intelligence
Private equity-backed mobility specialists and established automotive OEMs shape supply behavior and pricing discipline within the CaaS market. These entities influence fleet acquisition strategies and the structuring of subscription models.
Pricing Analysis
Margin tightening across car subscription services reflects intense competition from traditional leasing and daily rental alternatives. The dominant pricing structure is a subscription-based model, offering predictable costs to users. Price differentiation stems from premium brand experiences and comprehensive service bundling, including maintenance. Corporate clients demonstrate lower price sensitivity due to their focus on predictable operating costs and fleet flexibility, while individual users remain highly price-sensitive.
Supply Chain Analysis
Direct-to-corporate channels dominate the distribution of CaaS solutions for fleet management. Geographic supply concentration for vehicle fleets centers on Germany, the United States, and China, reflecting major automotive manufacturing hubs and significant corporate demand. The supply chain draws from a diverse pool of vehicles, telematics hardware, and sophisticated software platforms. Residual value risk, driven by rapid technological advancements and shifting preferences for newer models, represents a significant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CaaS market represents a technology-transition phase, with digital platforms replacing legacy vehicle ownership models for flexible access.
For Market Incumbents:Deploy digital integration to enhance existing fleet management and subscription offerings. Legacy rental giants like Hertz Global Holdings should leverage their physical assets by integrating advanced telematics for predictive maintenance. This move addresses the threat from technology-driven pure-play specialists, reinforcing operational efficiency and customer retention.
For New Entrants and Emerging Players:Small businesses in secondary cities represent an underserved buyer archetype with high potential. Target these regions and specialized vehicle types, such as electric vans for local deliveries, where traditional CaaS penetration is low. A go-to-market angle focusing on AI-powered personalization and flexible, short-term contracts can attract these clients.
For Investors and Strategic Acquirers:Distressed-cycle entries favor technology-driven platform providers in Europe, particularly those with robust data governance frameworks. The long-term viability of CaaS hinges on the structural shift from asset ownership to usage-based access over the next five to ten years. Investors should monitor regulatory clarity on data privacy, like GDPR enforcement, as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Service Bundling | Integrates vehicle access with ancillary mobility services, enhancing user convenience and provider revenue streams. |
| Invest in AI-Powered Personalization | Enables dynamic pricing and customized offerings, improving user experience and operational efficiency for providers. |
| Target Secondary Metropolitan Markets | Captures untapped demand in areas with high car dependency but limited flexible mobility options. |
| Deepen Telematics Integration | Optimizes fleet utilization and maintenance scheduling, reducing operational costs for corporate clients. |
| Align with Emissions Policies | Ensures fleet compliance and meets corporate sustainability goals, particularly in regions like China and Europe. |
Research Approach
SEC 10-K filings, NHTSA reports, and automotive industry association data formed the secondary backbone of this analysis. This was complemented by primary interviews with fleet managers, CaaS platform executives, automotive OEM strategists, and mobility solution providers. The approach ensured robust data validation through bottom-up and top-down triangulation.
Bottom-up market sizing models were employed to estimate market volumes and values across the analysis window. The analytical framework incorporated segmentation dimensions including service type, end-user, vehicle type, technology, and regional adoption rates. Compound annual growth rates were derived from historical data extrapolation and projected market dynamics, utilizing inputs such as urbanization rates and corporate mobility budgets.
Revisions become necessary when significant regulatory shifts or unforeseen macroeconomic volatility materialize. Forecasts reflect assumptions regarding technological advancements and stable market conditions. Practitioners should monitor data privacy regulations and global economic indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Airbag Repair Service Market
Automotive Services
US Car Wash Services Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Automotive Homologation Services Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Driverless Sweeper Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
Car Rental Business Market
Automotive Services
Automotive Garage Equipment Market
Automotive Services
Mobile Car Wash Service Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Motorsports Market
Automotive Services
Car Washing Service Market