
 LTE Base Station System Market | 2026-2036
LTE Base Station System Market Size, Share, and Industry Trends Forecast 2026-2036
LTE Base Station System Market Intelligence
The 3GPP Release cycle, which dictates backward compatibility and feature interoperability, is unwinding the tight coupling between hardware and software vendors. Ericsson leverages its extensive patent portfolio in MIMO technology to maintain a strong position with major mobile network operators. Nokia Corporation differentiates through its focus on private enterprise networks and industrial IoT solutions. Huawei Technologies Co. competes on manufacturing scale and rapid deployment capabilities in markets across Asia and Africa.
An LTE base station system comprises the hardware and software infrastructure, including the Evolved Node B (eNB), that provides wireless communication between user equipment and the mobile network's core. It manages radio resources, handles mobility functions, and utilizes technologies like FDD-LTE or TD-LTE for data transmission. While macro base stations constitute the largest product segment by installed base, pico and femto base stations are seeing faster deployment for urban densification. Within applications, public safety networks and industrial IoT represent high-value opportunities.
Spectrum allocation policies from national regulators like the US FCC and India's TRAI directly influence deployment timelines and technology choices. Concurrently, standards from the ITU and 3GPP define the technical specifications for interoperability and performance. The EU's directives on cybersecurity for critical infrastructure also shape product development. Vendor selection will increasingly hinge on navigating these fragmented regulatory landscapes while adapting to the disaggregation of hardware and software supply chains.
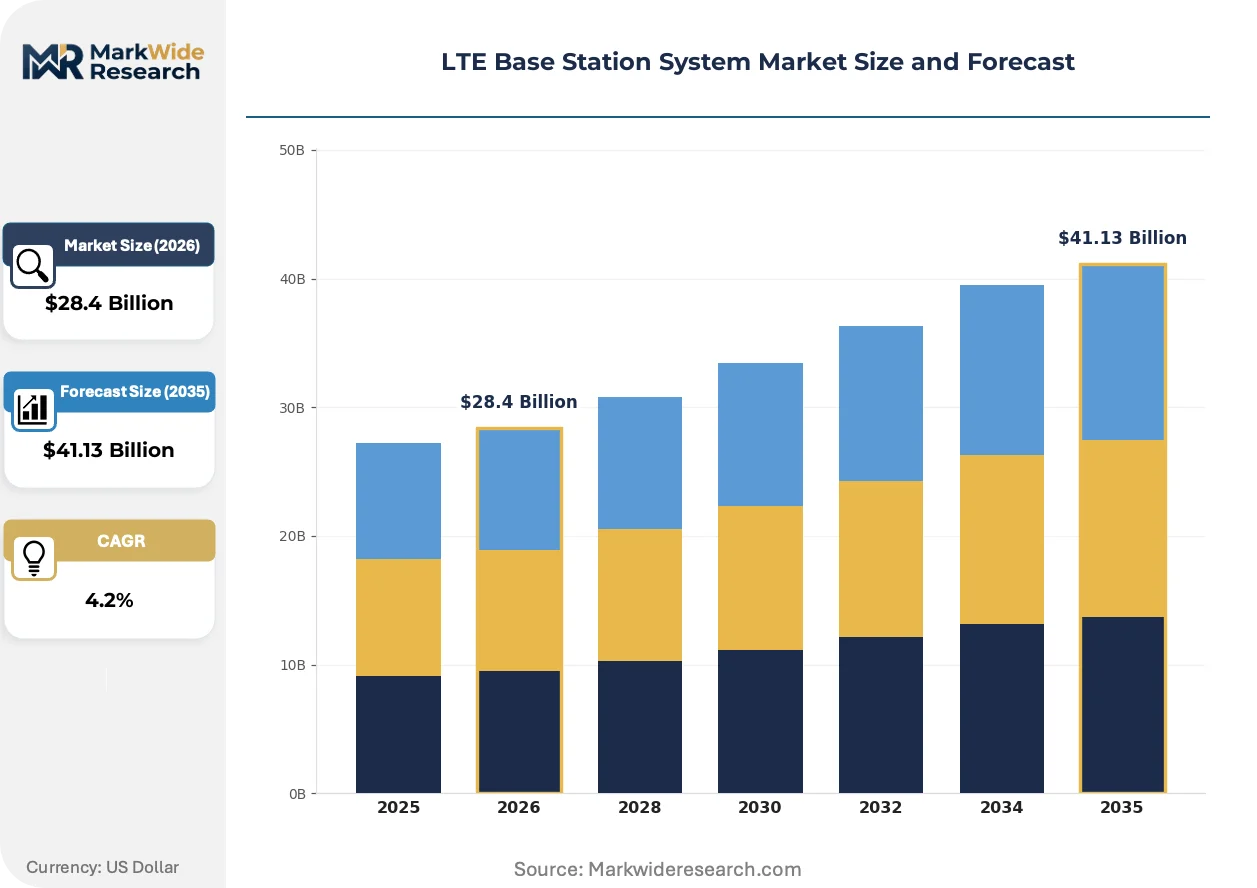
Market Dynamics
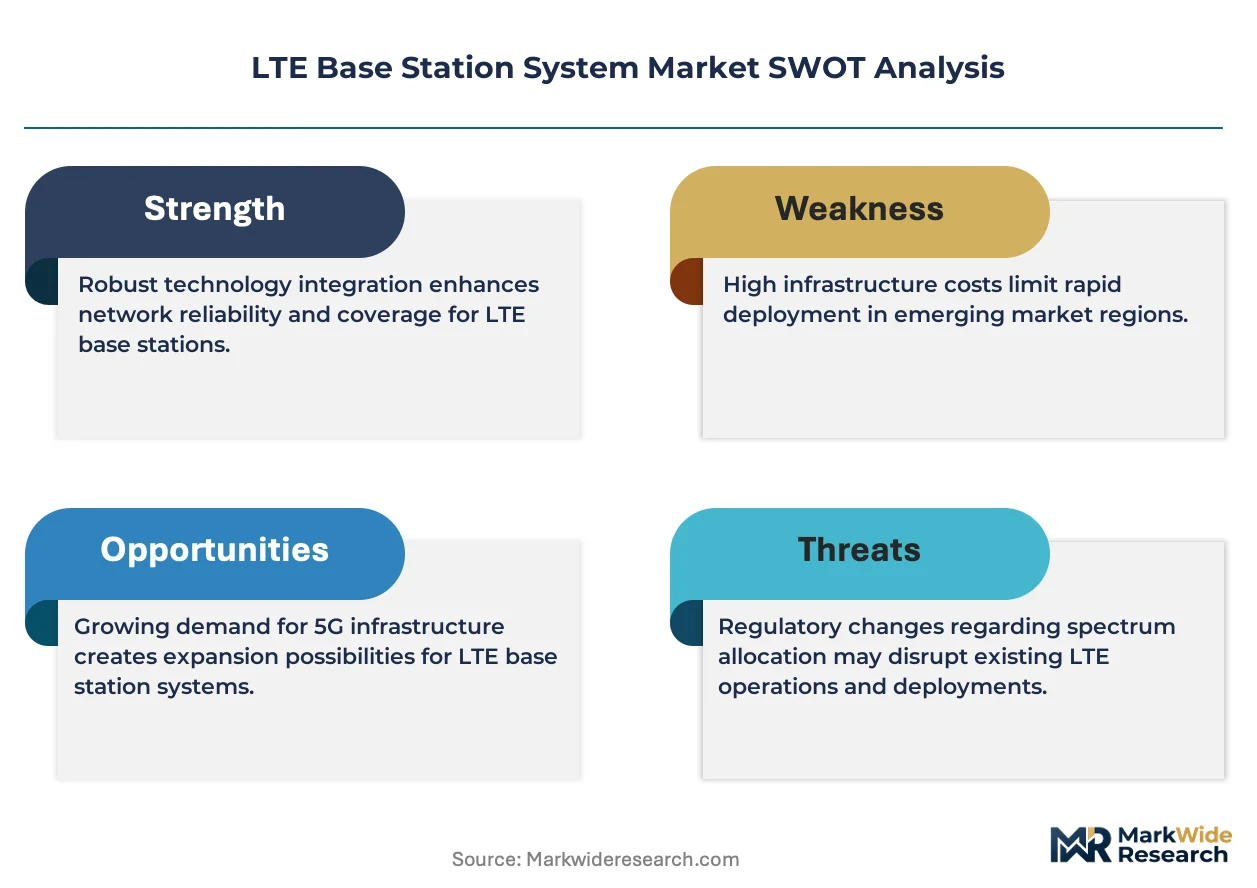
The central structural force shaping the LTE base station system market is the industry-wide shift toward Open RAN architectures. This trend is unwinding the historically tight coupling of hardware and software, fundamentally altering vendor relationships and network deployment economics.
Growth Catalysts
- National Digital Initiatives:Policies from regulators like India's TRAI aimed at expanding rural connectivity and digital inclusion are accelerating large-scale LTE network rollouts, requiring substantial base station deployments.
- Public Safety Modernization:The adoption of dedicated LTE networks for reliable emergency communications by public safety agencies provides a consistent, high-value demand stream for robust base station systems.
- Urban Network Densification:The increasing use of pico and femto base stations to augment capacity and improve coverage in dense urban environments is a significant driver for smaller form-factor products.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for site acquisition, civil works, and deployment of macro base stations remains a substantial barrier for network operators.
- Supply Chain Concentration:Dependence on a limited pool of specialized semiconductor foundries for advanced radio frequency (RF) components creates potential bottlenecks and price volatility.
- Legacy System Integration:The technical complexity and cost associated with integrating new LTE systems with existing 2G and 3G network infrastructure can slow down modernization projects.
Strategic Opportunities
- Private Enterprise Networks:Deploying private LTE infrastructure for dedicated connectivity in industrial IoT environments such as manufacturing, mining, and logistics represents a major growth vector.
- Software-Defined Architectures:Developing solutions based on virtualized RAN (vRAN) and software-defined radio (SDR) allows vendors to align with the move towards disaggregated, software-centric networks.
- Neutral Host Infrastructure:Building and operating shared base station infrastructure for multiple tenants, including mobile operators and enterprises, offers a new service-based revenue model.
Industry Challenges
- Regulatory Fragmentation:Navigating disparate spectrum allocation policies and cybersecurity mandates, such as the EU's directives for critical infrastructure, complicates product design and market entry.
- Multi-Vendor Interoperability:Ensuring seamless integration and performance between components from different suppliers in an Open RAN environment presents a significant technical and testing challenge.
- Intellectual Property Licensing:The complexity of licensing standard-essential patents for technologies like MIMO can lead to costly legal disputes and unpredictable royalty payments for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LTE Base Station System Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $41.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Macro Base Station, Micro Base Station, Pico Base Station, Femto Base Station, Remote Radio Head Technology: TD-LTE, FDD-LTE, MIMO, Carrier Aggregation, VoLTE Application: Public Safety Networks, Smart Cities, Industrial IoT, Transportation Networks, Private Enterprise End User: Mobile Network Operators, Government Agencies, Enterprises, Utilities, Managed Service Providers |
| Companies Covered | ZTE Corporation, Samsung Electronics Co Ltd, Huawei Technologies Co, Cisco Systems Inc, NEC Corporation, Ericsson AB, CommScope Inc, Kathrein SE, Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LTE Base Station System Market Strategic Shifts & Innovations
The evolution from proprietary, monolithic systems toward disaggregated and software-defined architectures is reshaping the competitive landscape. This transition prioritizes interoperability and flexibility, creating new entry points for specialized software and hardware vendors.
Open RAN (O-RAN) architecture defines open interfaces that decouple base station hardware from the software that runs on it. Mobile network operators are adopting this approach to reduce vendor lock-in, lower costs, and accelerate innovation. This technology is fragmenting the traditional, vertically integrated supply chain for radio access networks.
Regulatory actions from bodies like the US FCC are promoting open network ecosystems and shared spectrum access. For instance, the framework for the Citizens Broadband Radio Service (CBRS) band enables new deployment models outside of traditional carrier control. This policy shift most affects the private network segment, allowing enterprises to deploy their own LTE networks more easily.
A notable behavioral shift involves network operators moving away from large, upfront capital expenditures for turnkey systems. This disrupts the traditional sales cycle, favoring vendors who offer more flexible, disaggregated components or as-a-service models. The trend is most prominent in private enterprise and campus network deployments where OpEx-based procurement is preferred.
LTE Base Station System Market Segmentation
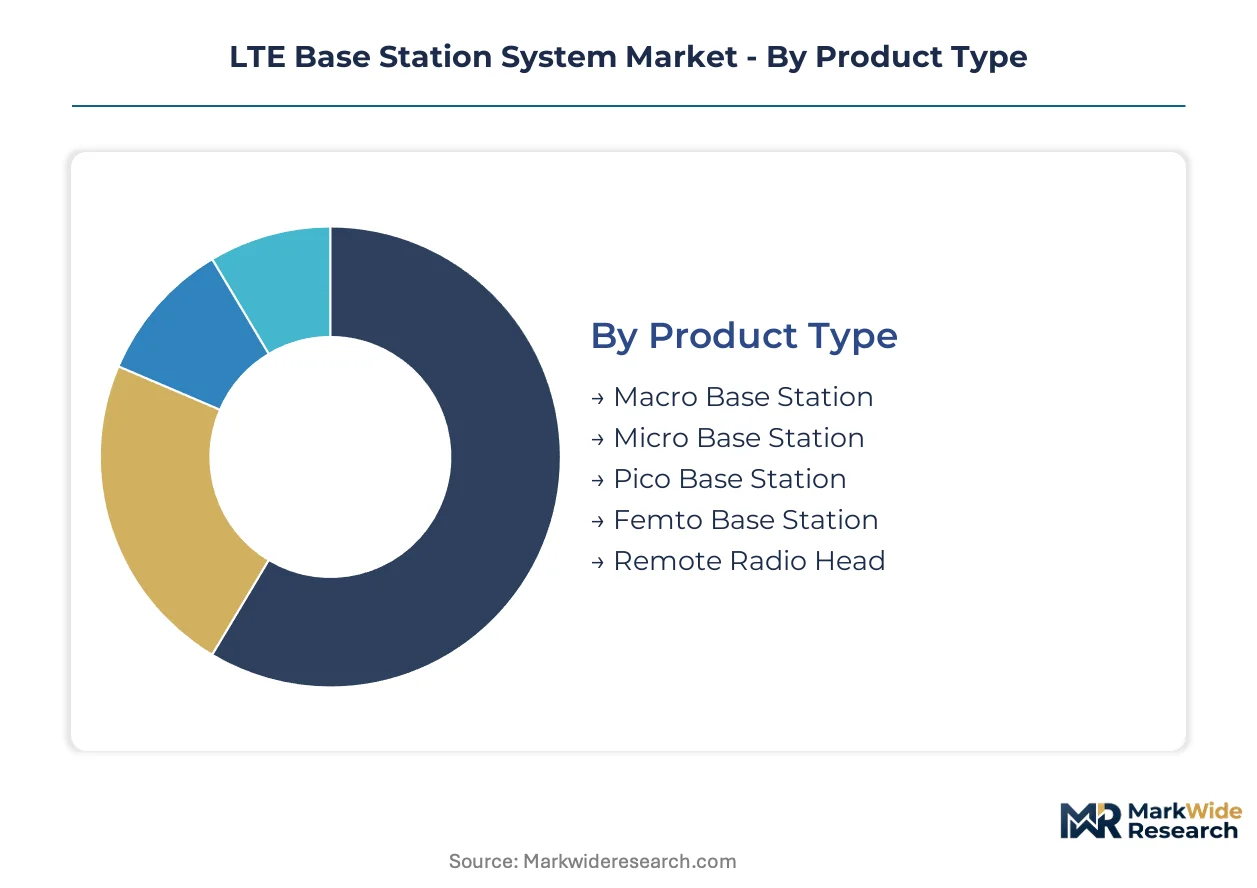
The LTE base station system market's segmentation reveals diverse technological and deployment approaches. Understanding these distinct segments allows stakeholders to identify specific growth vectors and competitive landscapes. Each category reflects unique operational demands and technological requirements.
Product Type:
The product type segmentation highlights how smaller form-factor base stations are increasingly substituting traditional macro deployments for specific use cases.
- Macro Base Station:These systems provide wide-area coverage and high capacity, typically deployed in rural and suburban areas. Demand concentrates in emerging economies like India for national digital inclusion initiatives.
- Pico Base Station:Pico base stations are compact, low-power units designed for targeted coverage and capacity enhancement in urban hotspots or large venues. Their deployment is accelerating in densely populated cities to improve network performance.
- Micro Base Station:Micro base stations offer intermediate coverage and capacity, bridging the gap between macro and smaller cells.
- Femto Base Station:Femto base stations are very small, low-power units primarily for indoor coverage in homes or small offices.
- Remote Radio Head:Remote Radio Heads (RRHs) separate the radio frequency components from the baseband unit, enabling flexible antenna placement.
Macro Base Station anchors the volume base while Pico Base Station gains share at the steepest rate.
Technology:
Technology segmentation differentiates solutions based on their complexity and associated deployment costs for network operators.
- MIMO:Multiple-Input Multiple-Output (MIMO) technology uses multiple antennas at both the transmitter and receiver to improve spectral efficiency and throughput. Mobile network operators in advanced markets like Japan prioritize MIMO for high-speed data services.
- FDD-LTE:Frequency Division Duplex Long Term Evolution (FDD-LTE) utilizes separate frequency bands for uplink and downlink transmission, ensuring high bandwidth for symmetrical traffic. This technology forms the backbone for many commercial networks in Europe and North America.
- TD-LTE:Time Division Duplex Long Term Evolution (TD-LTE) uses a single frequency band for both uplink and downlink, allocating time slots dynamically.
- Carrier Aggregation:Carrier Aggregation combines multiple frequency blocks into a wider virtual channel, increasing data rates and network capacity.
- VoLTE:Voice over LTE (VoLTE) delivers voice calls as data packets over an LTE network, improving call quality and enabling advanced services.
This segment highlights technologies crucial for enhancing network capacity and delivering advanced services across diverse applications.
Application:
The application segment illustrates how LTE base stations address specific connectivity needs across various industry verticals.
- Public Safety Networks:These dedicated LTE networks provide highly reliable and secure communication for emergency services and first responders. Government agencies globally, including those in the US, are modernizing their public safety communication infrastructure.
- Industrial IoT:LTE base stations support private networks for critical machine-to-machine communication in industrial environments such as manufacturing plants and logistics hubs. Enterprises in Germany are increasingly adopting these solutions for operational efficiency.
- Smart Cities:Smart City applications leverage LTE for ubiquitous connectivity, supporting urban services like intelligent traffic management and public surveillance.
- Transportation Networks:Transportation networks use LTE for reliable communication across railways, ports, and intelligent vehicle systems, ensuring operational safety.
- Private Enterprise:Private enterprise networks provide dedicated, secure LTE connectivity for campus environments, enabling localized digital transformation initiatives.
Public Safety Networks represent a mature application, while Industrial IoT applications are rapidly expanding.
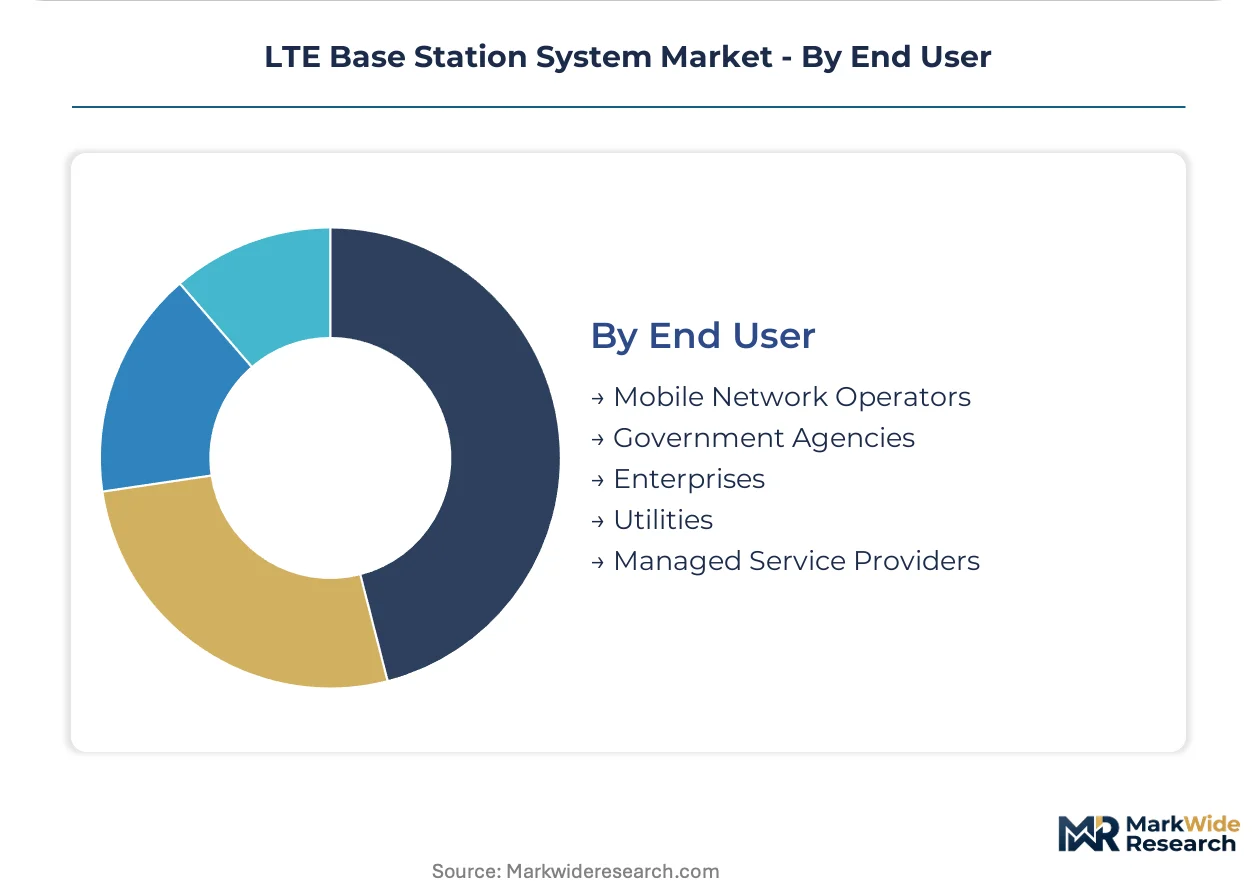
End User:
End-user segmentation categorizes purchasers based on their organizational structure and typical deployment scale.
- Mobile Network Operators:These are the primary buyers, deploying extensive LTE infrastructure to provide commercial mobile broadband services to subscribers. Operators like Vodafone and AT&T continuously upgrade their networks to meet consumer demand.
- Enterprises:Enterprises deploy private LTE networks for their specific operational needs, often for industrial IoT or campus connectivity. Manufacturing firms in South Korea, for example, are investing in these dedicated solutions.
- Government Agencies:Government agencies procure LTE base stations for public safety, defense, and smart city initiatives, prioritizing security and reliability.
- Utilities:Utility companies utilize LTE for grid modernization, smart metering, and remote monitoring of critical infrastructure, ensuring operational resilience.
- Managed Service Providers:Managed Service Providers offer build-and-operate services for private LTE networks, catering to enterprises and specialized industry needs.
Mobile Network Operators drive significant volume, whereas Enterprises represent a high-margin segment for specialized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile network operators represent the primary buyer archetype globally, driving significant LTE base station deployments across diverse geographies. Enterprises and government agencies also contribute substantial demand for specialized private networks. This market’s regional dynamics reflect varying stages of network modernization, regulatory environments, and digital transformation initiatives.
India
Demand for LTE base station systems in India is accelerating due to national digital inclusion and rural connectivity initiatives. The Telecom Regulatory Authority of India (TRAI) policies actively promote network expansion to bridge the digital divide. Large-scale infrastructure projects in areas like Uttar Pradesh and Bihar are requiring substantial base station deployments to support new digital services.
United States
The United States sees consistent demand from public safety agencies modernizing their emergency communication networks. The Federal Communications Commission (FCC) actively allocates spectrum, influencing deployment timelines and technology choices for robust systems. Major urban centers like New York City and Los Angeles are investing in network densification, deploying pico and femto base stations.
Germany
Enterprises in Germany are increasingly adopting private LTE infrastructure for industrial IoT applications within their operational environments. EU directives on cybersecurity for critical infrastructure shape product development, emphasizing secure and reliable solutions. Manufacturing hubs in Bavaria and North Rhine-Westphalia are key areas for these dedicated network deployments.
Japan
Japanese mobile network operators prioritize advanced LTE technologies like MIMO for high-speed data services and enhanced spectral efficiency. The Ministry of Economy, Trade and Industry (METI) supports technological innovation and deployment of sophisticated network solutions. Major cities such as Tokyo and Osaka are driving demand for carrier aggregation and urban densification products.
South Korea
Manufacturing firms in South Korea are investing in private LTE networks to support advanced industrial IoT and smart factory initiatives. Government policies encourage the adoption of cutting-edge communication technologies for economic competitiveness. Industrial complexes in Gyeonggi Province and Ulsan are deploying dedicated LTE base stations for operational efficiency and automation.
LTE Base Station System Market Key Industry Players
Player mix skews toward established telecommunications equipment providers, but the industry is experiencing structural fragmentation due to Open RAN architectures. This shift introduces new specialized software and hardware vendors into the ecosystem. Key strategic archetypes include vertically integrated network infrastructure giants, niche Open RAN software developers, and component manufacturers. Companies primarily engage in strategic partnerships to integrate diverse technologies and pursue portfolio diversification into private enterprise networks.
Established network equipment providers, such as Ericsson AB and Nokia Corporation, exemplify the traditional, vertically integrated approach, leveraging extensive patent portfolios and global operator relationships. Huawei Technologies Co. occupies a position as a scale-driven provider, known for rapid deployment capabilities across emerging markets. These major players are adapting their strategies to integrate Open RAN components, while also focusing on high-value segments like private enterprise networks.
| Leading Market Players |
|---|
| ZTE Corporation |
| Samsung Electronics Co Ltd |
| Huawei Technologies Co |
| Cisco Systems Inc |
| NEC Corporation |
| Ericsson AB |
| CommScope Inc |
| Kathrein SE |
| Nokia Corporation |
| Others |
Cost & Logistics Intelligence
EU's directives on cybersecurity for critical infrastructure gate both supply qualification and price differentiation simultaneously in the LTE base station system market. Vendors must meet these stringent security standards, adding significant development and compliance costs. This directly influences the pricing structure, favoring solutions with proven security and regulatory adherence.
Pricing Analysis
Long-term contract-based offtake agreements with named indexation characterize the pricing model for large-scale LTE base station deployments. Price differentiation stems from Open RAN compatibility, offering flexibility to mobile network operators, and comprehensive after-sales service packages. Pricing softness runs through the macro base station segment due to increased competition and standardization. Mobile network operators exhibit high price sensitivity for volume procurements, while public safety agencies prioritize reliability and security over initial cost.
Supply Chain Analysis
Component inventory levels are tightly managed, reflecting the long lead times for specialized radio frequency components. Geographic supply of critical semiconductor components concentrates in Taiwan and South Korea. Key dependencies include advanced RF components, baseband processors, and optical fiber for backhaul. A structural supply chain risk is the reliance on a limited pool of specialized semiconductor foundries, creating potential bottlenecks. Distribution primarily runs through direct sales channels to mobile network operators, with system integrators serving enterprise and government clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a significant service-attach opportunity, with software licensing and managed services for private networks expanding faster than core hardware sales. This shift allows vendors to capture recurring revenue streams.
For Market Incumbents:Fortify existing operator relationships by offering flexible Open RAN compatible solutions and comprehensive integration services. Invest heavily in intellectual property around advanced MIMO and carrier aggregation technologies to maintain a competitive edge against new entrants. Address the threat of specialized software vendors by developing robust in-house software capabilities and forming strategic partnerships. Leverage extensive patent portfolios as a lever against commoditization.
For New Entrants and Emerging Players:Lead with specialized software-defined radio (SDR) and virtualized RAN (vRAN) solutions that align with Open RAN architectures. Target the rapidly expanding private enterprise networks segment, especially industrial IoT applications, which is a penetrable segment due to its demand for customized solutions. Focus on OpEx-based procurement models and rapid deployment capabilities as a go-to-market angle. Offer modular components that integrate seamlessly into multi-vendor environments.
For Investors and Strategic Acquirers:EU's cybersecurity directives reshape the acquisition landscape, emphasizing secure and compliant technology providers. The market exhibits long-term viability, driven by persistent demand for network densification and public safety modernization. Identify specialized Open RAN software developers or niche RF component manufacturers as prime acquisition targets. A key signal to watch is the acceleration of large-scale Open RAN deployments by Tier 1 mobile network operators, indicating market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Software Development | Accelerates disaggregation and reduces vendor lock-in for mobile operators. |
| Private LTE Solutions Expansion | Captures high-value industrial IoT and enterprise connectivity demand. |
| Strategic Partnership (RF Components) | Ensures stable supply and advanced technology for radio access networks. |
| Rural Connectivity Initiatives | Addresses national digital inclusion goals and expands market reach in India. |
| Cybersecurity Certification Investment | Meets stringent regulatory requirements for critical infrastructure deployments. |
Research Approach
A standing panel of mobile network operators, enterprise IT managers, public safety communication leads, and telecommunication equipment engineers provided ongoing calibration for market sizing and trends. This primary research was rigorously validated through secondary data sources, including 3GPP specifications, ITU reports, national regulatory body publications like the US FCC and India's TRAI, and industry association whitepapers. A comprehensive bottom-up and top-down triangulation approach was employed to ensure data accuracy.
Consistency checks against historical deployment patterns and technology adoption rates validated the forecast framework across the analysis window. Segmentation dimensions, including product type, technology, application, end-user, and regional deployment density, were systematically modeled. Compound annual growth rates were derived from historical trends, expert consensus, and projected technology adoption rates. Spectrum allocation timelines and national digital initiative funding served as key industry-specific forecast inputs.
Forecasts assume regulatory continuity in regimes like the US FCC, India's TRAI, and EU's cybersecurity directives; material policy shifts would require re-modeling. Geopolitical trade restrictions or unforeseen technological disruptions, such as a rapid shift to 6G, represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Thailand ICT Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Algeria Telecom Market
Telecommunications
Telecom Services Market
Telecommunications
Global Radio Access Network Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
United States Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Global Virtual PBX Market
Telecommunications
Mobile Fronthaul and Backhaul Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
Austria Telecom Market
Telecommunications
Russia ICT Market
Telecommunications
Global 5G Services Market
Telecommunications
Telecom Managed Services Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Europe Managed SD-WAN Services Market