
 Mobile Fronthaul and Backhaul Market | 2026-2036
Mobile Fronthaul and Backhaul Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Fronthaul and Backhaul Market Intelligence
The shift towards asset-light leasing and network-as-a-service models for telecom infrastructure is narrowing the competitive field to vendors capable of supporting flexible financing. Cisco Systems leverages its software expertise to offer integrated SDN solutions for complex network environments. Ericsson sustains its market position through strong relationships with mobile network operators for 5G rollouts. Ciena Corporation specializes in coherent optical technologies critical for high-capacity fronthaul links connecting radio units.
Mobile fronthaul and backhaul constitute the transport network segments connecting cellular base station components and linking the cell site back to the core network. Fronthaul specifically links remote radio heads to baseband units and requires extremely low latency, often below 100 microseconds, to function correctly. Optical Fiber solutions dominate the product landscape for new fronthaul deployments due to superior bandwidth and latency performance. The 5G Networks application segment represents the fastest-growing area of investment, with WDM and OTN technologies being essential for multiplexing traffic.
Spectrum allocation policies from regulators like the US FCC and China's MIIT directly influence the pace and location of 5G infrastructure build-outs. Concurrently, standards from organizations like the ITU and 3GPP ensure equipment interoperability and performance benchmarks for all fronthaul and backhaul systems. The critical decision for mobile network operators is balancing the high capital cost of fiber deployment against the performance limitations of microwave and millimeter wave alternatives for specific use cases.
Market Dynamics
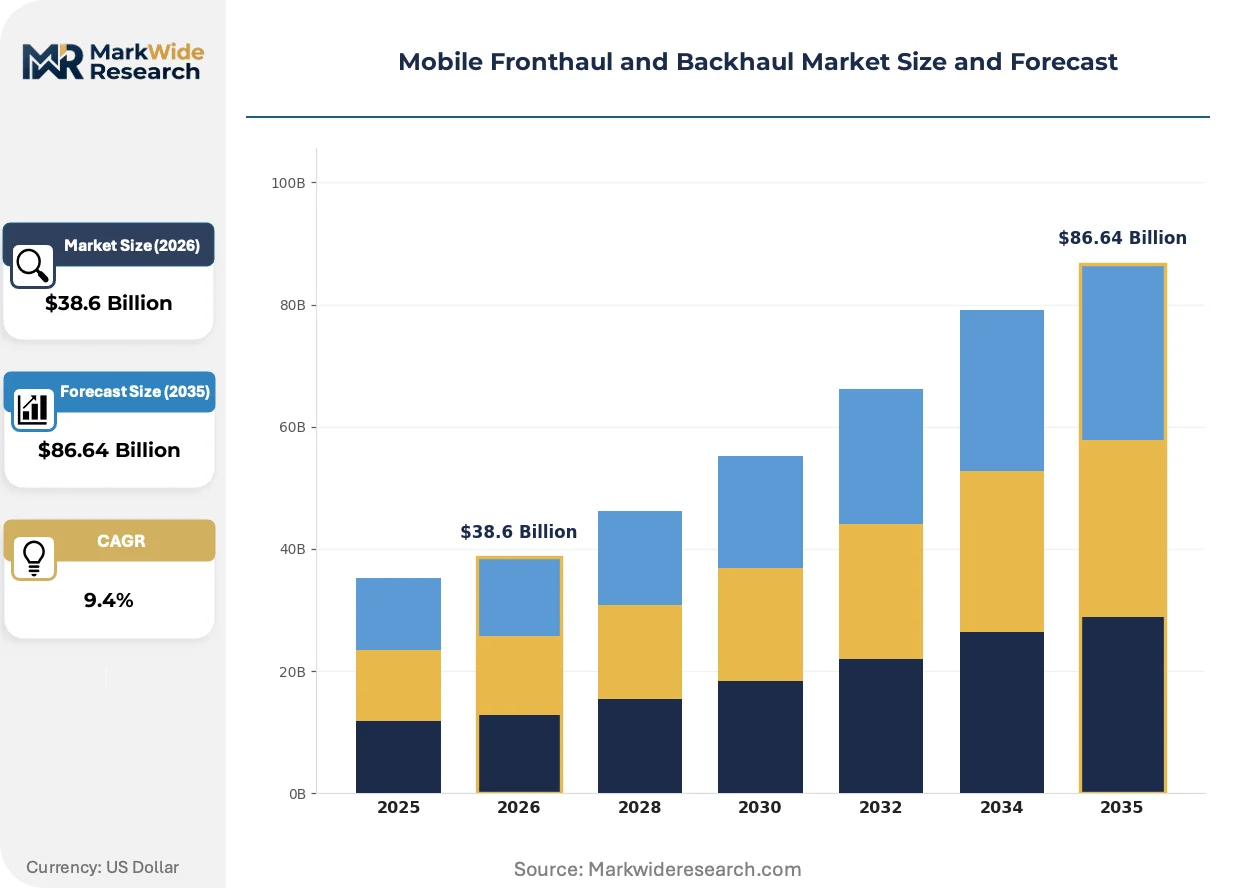
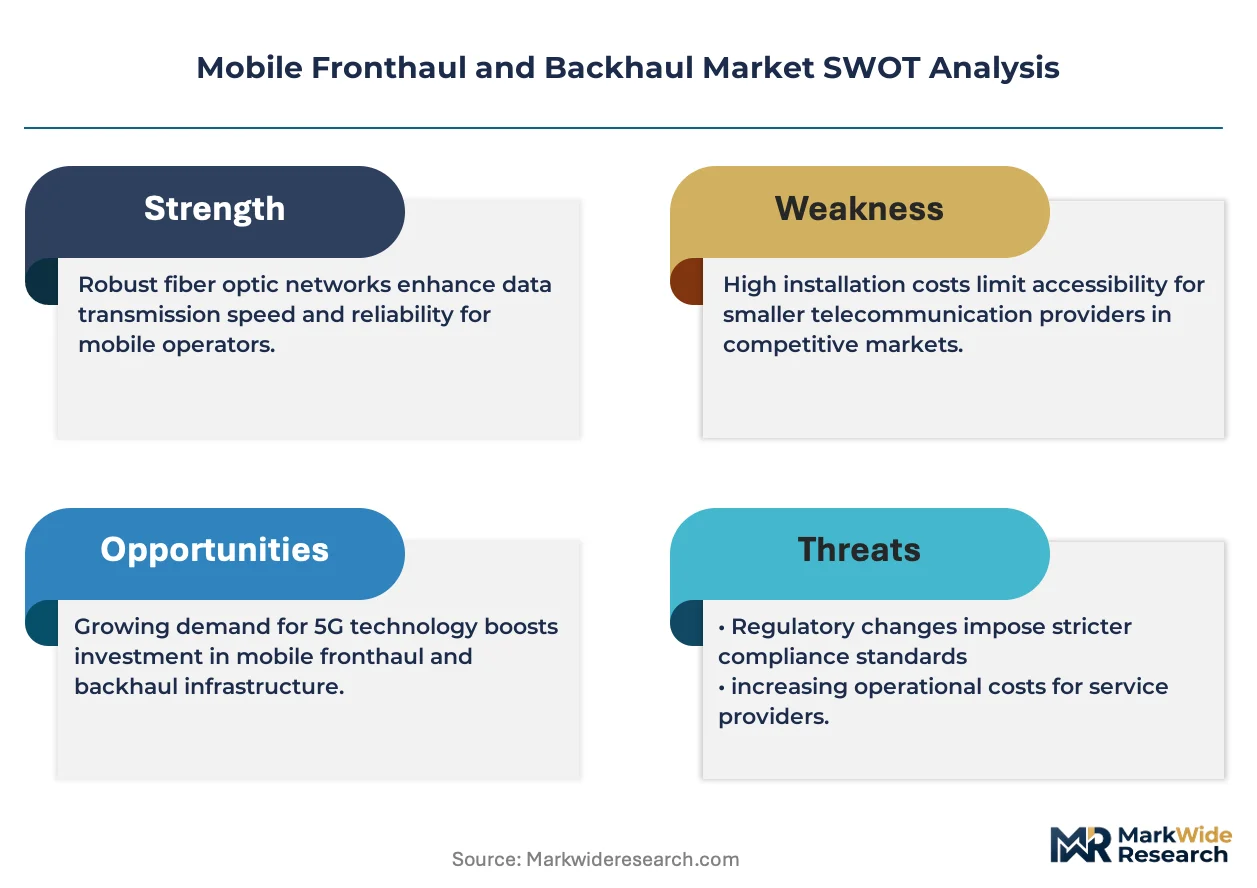
The central dynamic shaping the mobile transport network is the architectural tension between the ultra-low latency and high-bandwidth demands of 5G services and the significant capital expenditure required for ubiquitous fiber optic deployment, forcing operators into critical technology trade-offs.
Growth Catalysts
- 5G Network Investment:The continued global rollout of 5G networks by mobile operators is the primary demand source, necessitating upgrades and new deployments of high-capacity fronthaul and backhaul links to support enhanced mobile broadband and new services.
- Energy Efficiency Mandates:Regulatory frameworks like the EU Green Deal encourage the adoption of energy-efficient technologies, creating a tailwind for modern optical and advanced microwave solutions that offer lower power consumption compared to legacy systems.
- Advanced Optical Technologies:The maturation of Wavelength Division Multiplexing (WDM) and Optical Transport Network (OTN) technologies provides the necessary tools for mobile operators to efficiently multiplex traffic from multiple cell sites onto a single fiber, maximizing asset utilization.
Market Restraints
- High Fiber Deployment Cost:The substantial capital investment and civil works required to lay new fiber optic cable, particularly in dense urban or difficult terrain, remains a significant barrier to entry and slows network expansion for many operators.
- Microwave Performance Limitations:While a common alternative to fiber, microwave and millimeter wave solutions face inherent limitations in bandwidth capacity and susceptibility to atmospheric conditions, restricting their use in the most demanding fronthaul scenarios.
- Spectrum Allocation Delays:The pace of 5G deployment is directly tied to the timing and conditions of spectrum auctions managed by regulators like the FCC in the United States and MIIT in China, with delays directly impacting infrastructure investment timelines.
Strategic Opportunities
- Private 5G Networks:The expansion of private cellular networks for industrial campuses, ports, and enterprise environments creates a new market for tailored fronthaul and backhaul solutions that are independent of public mobile networks.
- Fronthaul and OTN Convergence:Integrating fronthaul transport, such as eCPRI, directly into Optical Transport Network (OTN) equipment offers a path to create a unified, more efficient, and scalable x-haul architecture for operators.
- Rural Broadband Initiatives:Government-funded programs in various countries to extend broadband access to underserved rural areas provide opportunities to build out new backhaul infrastructure that can be shared for mobile and fixed wireless services.
Industry Challenges
- Legacy System Integration:Operators face significant technical challenges in integrating new, packet-based 5G fronthaul equipment with older, circuit-switched backhaul and core network infrastructure, risking service disruption and performance bottlenecks.
- Vendor Interoperability:Ensuring seamless interoperability between radio, fronthaul, and backhaul equipment from different vendors is a persistent challenge, relying on adherence to evolving standards from bodies like the 3GPP and ITU.
- Skilled Workforce Scarcity:A shortage of network engineers and technicians with combined expertise in IP networking, optical transport, and radio frequency (RF) systems complicates the design, deployment, and maintenance of complex 5G transport networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Fronthaul and Backhaul Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Fiber, Microwave Radio, Millimeter Wave, Ethernet, Copper Cable Technology: WDM, TDM, SDN, OTN, MPLS Application: 5G Networks, Fixed Wireless Access, Small Cells, Broadcasting, Public Safety End User: Mobile Network Operators, Telecom Equipment Providers, Infrastructure Vendors, System Integrators |
| Companies Covered | Cisco Systems, Samsung Electronics, Huawei Technologies, Juniper Networks, Ciena Corporation, Ericsson, ZTE Corporation, NEC Corporation, Nokia Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Fronthaul and Backhaul Market Strategic Shifts & Innovations
The evolution of mobile transport infrastructure is defined by a software-driven transformation, enabling greater network flexibility and efficiency. This shift allows mobile operators to move beyond rigid, hardware-centric architectures to support the dynamic service requirements of the 5G era.
Open RAN (O-RAN) architecture is a key innovation that disaggregates radio access network hardware and software components. Mobile network operators are increasingly trialing and deploying O-RAN to foster vendor diversity and manage total cost of ownership. Consequently, the fronthaul network architecture itself is migrating from a rigid, proprietary CPRI interface to a more flexible, packet-based eCPRI over Ethernet, which is essential for enabling this multi-vendor ecosystem.
National spectrum policies directly shape infrastructure investment priorities for mobile network operators. Regulations from bodies like the US FCC and Germany's BNetzA governing the auction of C-band and millimeter-wave frequencies determine where and when 5G services can be launched. The release of these bands forces investment in transport networks capable of supporting the new spectrum's characteristics, with mmWave deployments in particular requiring a denser grid of high-capacity fronthaul links.
A notable behavioral change is the move by mobile operators toward asset-light infrastructure models to manage capital expenditures. This trend is disrupting traditional equipment sales in favor of Network-as-a-Service (NaaS) offerings from specialized tower companies and infrastructure vendors. This shift in procurement is most prominent in competitive European markets and dense Asian cities, where operators prioritize operational agility and faster time-to-market for 5G services.
Mobile Fronthaul and Backhaul Market Segmentation
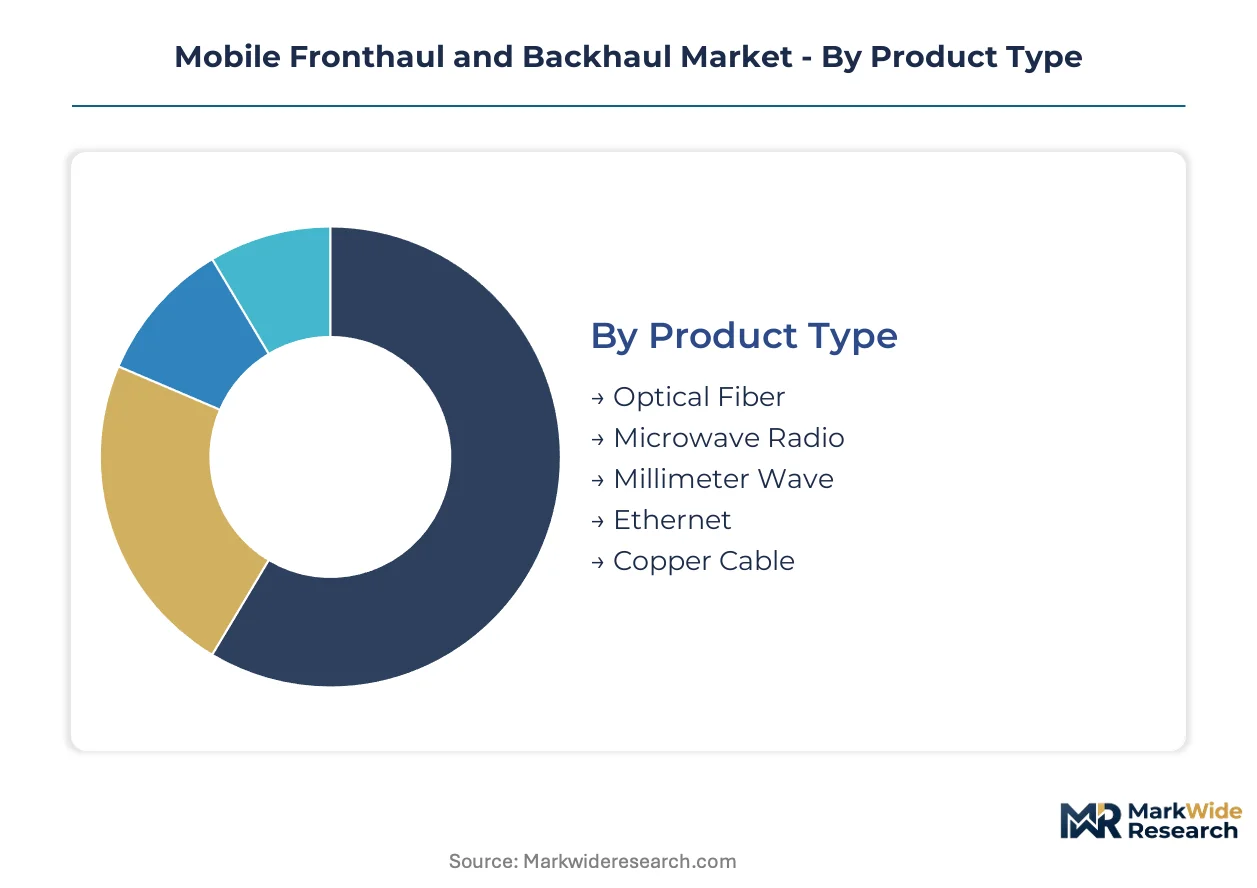
Understanding the Mobile Fronthaul and Backhaul Market through segmentation provides clarity on the diverse technological approaches and application areas driving network evolution. This granular view reveals where investment is concentrated and highlights the specific demands of various end-user groups in the expanding mobile ecosystem.
Product Type:
The product type segment illustrates the maturity spectrum of mobile transport solutions, from established wired options to advanced wireless technologies facilitating 5G deployments.
- Optical Fiber:This solution utilizes light signals transmitted through thin glass strands, offering unparalleled bandwidth capacity and extremely low latency for fronthaul and backhaul connections. Demand concentrates in dense urban areas and for new 5G rollouts, driven by superior performance requirements.
- Microwave Radio:Microwave radio systems transmit data via electromagnetic waves through the air, providing a cost-effective alternative to fiber for medium-capacity links over challenging terrains. Its deployment is common in rural areas or where fiber installation is economically unfeasible, despite susceptibility to atmospheric interference.
- Millimeter Wave:Millimeter wave technology operates at very high frequencies, enabling vast bandwidth over short distances, crucial for dense 5G networks and small cell deployments.
- Ethernet:Ethernet-based solutions provide flexible and scalable transport for packet-based traffic, serving as a foundational technology for modern backhaul and increasingly for fronthaul.
- Copper Cable:Copper cables, including twisted pair and coaxial, offer legacy connectivity for shorter distances and lower bandwidth requirements, primarily in older network infrastructure.
Optical Fiber retains volume leadership; Millimeter Wave holds the steepest expansion curve.
Technology:
Technology choices are driven by specific application requirements and the need for efficient spectrum and infrastructure utilization.
- WDM:Wavelength Division Multiplexing allows multiple data streams to be transmitted simultaneously over a single optical fiber using different wavelengths of light, significantly increasing fiber capacity. This technology is essential for multiplexing traffic from numerous cell sites onto shared fiber infrastructure, maximizing asset utilization.
- OTN:Optical Transport Network provides a standardized framework for efficient and flexible transport of various client signals over optical networks, offering robust management and monitoring capabilities. OTN is critical for creating a unified x-haul architecture, integrating fronthaul transport like eCPRI into a scalable solution.
- SDN:Software-Defined Networking centralizes network control, allowing for dynamic provisioning and management of network resources, enhancing flexibility and operational efficiency.
- TDM:Time Division Multiplexing allocates specific time slots for different data streams over a shared channel, a traditional method for combining traffic in legacy networks.
- MPLS:Multiprotocol Label Switching directs data packets using short path labels rather than long network addresses, speeding up traffic flow and simplifying network management.
WDM solutions lead in deployment scale, while SDN technologies are rapidly gaining strategic importance.
Application:
Application segments delineate where the bulk of mobile transport network investment is currently directed and where future growth is anticipated.
- 5G Networks:This application segment encompasses the transport infrastructure required to support the high bandwidth, ultra-low latency, and massive connectivity demands of next-generation mobile services. 5G Networks represent the fastest-growing area of investment, necessitating significant upgrades and new deployments of high-capacity links globally.
- Fixed Wireless Access:Fixed Wireless Access provides broadband internet connectivity to homes and businesses using wireless cellular technology instead of fiber or copper lines, especially in underserved areas. Government-funded rural broadband initiatives in countries like the United States are driving demand for robust backhaul infrastructure supporting FWA deployments.
- Small Cells:Small cells are low-power cellular radio access nodes that provide coverage over smaller geographical areas or indoors, requiring dense, high-capacity fronthaul links.
- Broadcasting:Broadcasting applications utilize mobile transport networks for transmitting media content, requiring reliable and high-bandwidth connections for live events and content distribution.
- Public Safety:Public safety networks provide dedicated and secure communication for emergency services, demanding resilient and high-availability fronthaul and backhaul infrastructure.
5G Networks remain the dominant application, with Fixed Wireless Access expanding most quickly in specific geographic contexts.
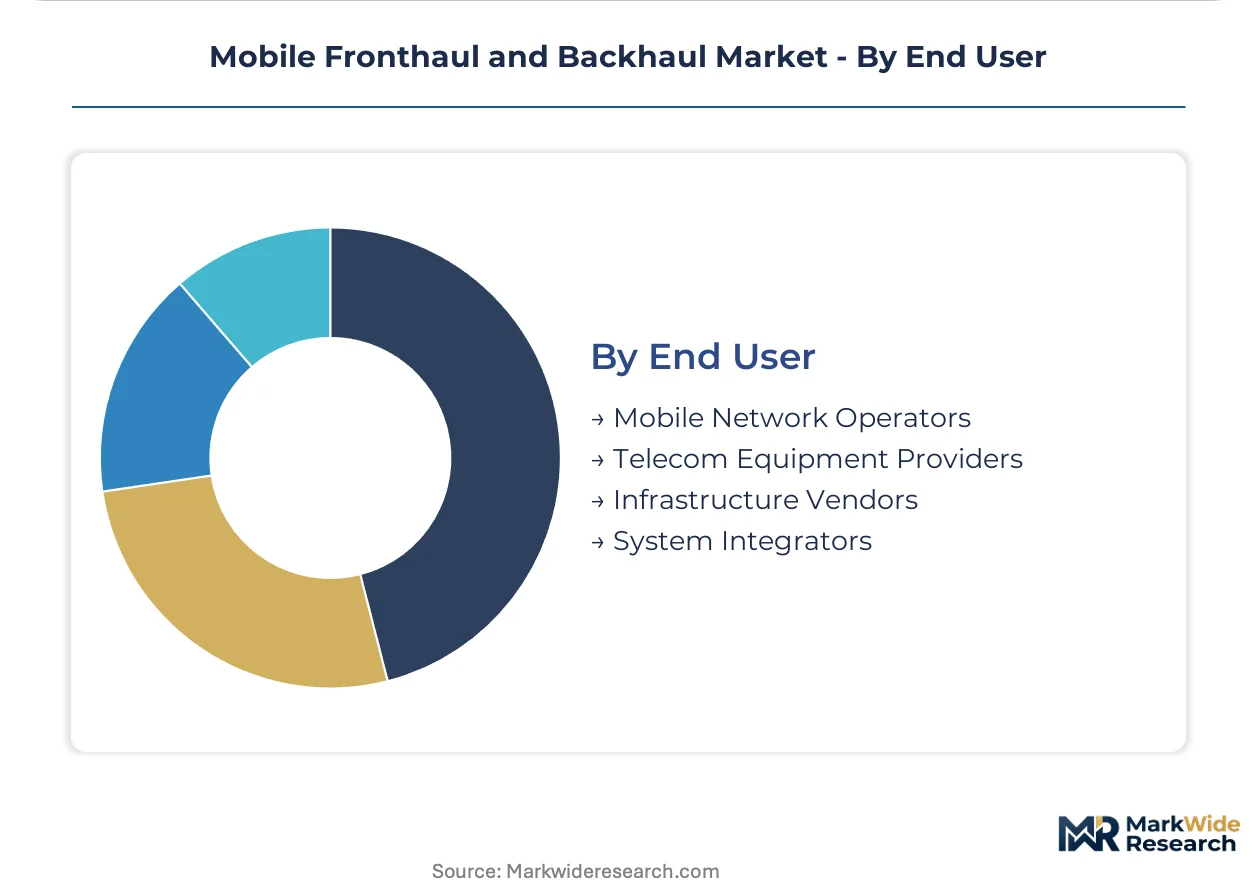
End User:
The end user classification highlights distinct customer types driving demand for mobile fronthaul and backhaul solutions and influencing procurement strategies.
- Mobile Network Operators:These entities own and operate the cellular network infrastructure, including radio access networks and core networks, and are the primary consumers of fronthaul and backhaul solutions. Mobile Network Operators are the largest end-user segment, driving demand through continuous 5G network rollouts and capacity expansions across various countries.
- Infrastructure Vendors:These companies provide the physical and software components for network infrastructure, including optical and microwave equipment, and are increasingly offering network-as-a-service models. Infrastructure Vendors like Ciena Corporation specialize in critical technologies for high-capacity links, influencing network design and deployment strategies.
- Telecom Equipment Providers:These providers supply a wide range of hardware and software components for telecommunications networks, supporting operators with their infrastructure needs.
- System Integrators:System integrators design, implement, and manage complex network solutions by combining products from various vendors, ensuring seamless operation for end-user clients.
Mobile Network Operators command the largest market share, while Infrastructure Vendors are increasingly shaping procurement and service delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Mobile Fronthaul and Backhaul Market exhibits varied investment patterns, reflecting diverse national priorities for digital infrastructure and economic development. Countries with advanced 5G rollouts prioritize high-capacity optical fiber solutions, while others focus on expanding basic mobile broadband access to underserved populations.
United States
Demand for fronthaul and backhaul solutions in the United States stems from aggressive 5G deployments and rural broadband expansion initiatives. The US FCC's spectrum allocation policies, particularly for C-band and millimeter-wave frequencies, drive investment in dense small cell networks. Major urban centers like New York City and Los Angeles are seeing significant infrastructure upgrades to support enhanced mobile broadband services.
China
China's mobile transport network investment is fueled by its vast population and rapid 5G network build-out, aiming for ubiquitous coverage. Policies from the MIIT directly influence the scale and pace of infrastructure development. Cities such as Shanghai and Beijing are at the forefront of deploying advanced WDM and OTN technologies for high-capacity fronthaul links.
South Korea
South Korea exhibits a concentrated demand for advanced mobile transport solutions due to its dense urban environments and high mobile usage rates. Government initiatives support continuous network upgrades to maintain leadership in 5G and future mobile technologies. Seoul's metropolitan area serves as a key hub for testing and implementing ultra-low latency fronthaul solutions.
Germany
Germany's market for mobile fronthaul and backhaul is influenced by the EU Green Deal, promoting energy-efficient optical and microwave solutions. The country's BNetzA regulates spectrum auctions, shaping the investment landscape for 5G expansion. Industrial regions like Bavaria are increasingly adopting private 5G networks, driving demand for tailored transport infrastructure.
India
India's demand for mobile fronthaul and backhaul is largely driven by government-funded rural broadband initiatives and the expansion of 4G and 5G networks. The country's telecom regulatory authority, TRAI, focuses on increasing connectivity across diverse geographies. Major cities like Mumbai and Delhi are experiencing significant backhaul capacity enhancements to support growing data traffic.
Mobile Fronthaul and Backhaul Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with established telecommunications equipment providers dominating the core infrastructure segments. These players leverage their long-standing relationships with mobile network operators to secure large-scale contracts. Strategic partnerships and portfolio diversification are common competitive moves to address evolving network requirements.
Major infrastructure vendors like Ericsson and Huawei Technologies exemplify the global scale and comprehensive product portfolios necessary for 5G network rollouts. Ciena Corporation, a specialist in coherent optical technologies, occupies a critical position in providing high-capacity fronthaul links. These companies anchor the market by offering integrated solutions spanning optical, microwave, and software-defined networking.
| Leading Market Players |
|---|
| Cisco Systems |
| Samsung Electronics |
| Huawei Technologies |
| Juniper Networks |
| Ciena Corporation |
| Ericsson |
| ZTE Corporation |
| NEC Corporation |
| Nokia Networks |
| Others |
Cost & Logistics Intelligence
Dense urban network utilization in South Korea drives supplier behavior and pricing posture for high-capacity optical solutions. This high demand influences the cost structure for advanced technologies and specialized equipment across the market.
Pricing Analysis
Mobile Network Operators anchor the pricing structure for mobile transport solutions, which often combines project-based equipment sales with service-based NaaS offerings. Price differentiation stems from performance metrics, particularly latency and bandwidth capabilities, and the level of integrated service provided. Pricing pressure intensifies due to the substantial capital expenditure required for fiber deployment and the shift towards asset-light models. Mobile Network Operators are highly price-sensitive buyers, seeking optimal cost-performance ratios for extensive network build-outs.
Supply Chain Analysis
Regulatory restriction on spectrum allocation directly impacts the supply chain for mobile transport network components. Supply concentration centers on major equipment providers based in China, the United States, and Nordic countries. The industry draws from specialized optical fiber and advanced semiconductor components. Single-source vulnerability for certain high-performance optical modules presents a structural risk. Distribution runs through direct sales channels to Mobile Network Operators, often supported by system integrators for complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mobile Fronthaul and Backhaul Market presents a defensive-moat story for established players. High switching costs, driven by the complex integration of diverse network components and long-term infrastructure investments, create a significant structural advantage.
For Market Incumbents:Harden core competencies in advanced optical transport, particularly WDM and OTN, to counter emerging O-RAN vendors and maintain performance leadership. Deepen relationships with Mobile Network Operators through tailored Network-as-a-Service offerings, mitigating the threat of asset-light procurement shifts. Leverage software expertise in SDN for integrated solutions, optimizing complex 5G network environments. Invest in continuous R&D for next-generation coherent optical technologies.
For New Entrants and Emerging Players:Pursue niche opportunities within the burgeoning private 5G networks segment for industrial campuses and enterprise environments. Target underserved rural areas by offering cost-effective backhaul solutions that support government-funded broadband initiatives. The Fixed Wireless Access application segment represents a penetrable entry point. Emphasize open-standard, O-RAN compliant solutions to attract operators seeking vendor diversity and reduced total cost of ownership.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among infrastructure vendors offering Network-as-a-Service models and integrated software solutions. This market's long-term viability remains strong due to its foundational role in the global digital economy. Acquisition targets should include specialists in coherent optical technologies or companies with strong SDN and network automation capabilities. The signal to watch for future growth inflection is the accelerating deployment of 5G Standalone core networks and widespread O-RAN adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop eCPRI over OTN solutions | Integrating fronthaul transport directly into OTN equipment creates a unified, scalable x-haul architecture for Mobile Network Operators. |
| Expand Network-as-a-Service offerings | This model aligns with mobile operators' asset-light strategies, providing flexible financing and faster 5G service time-to-market. |
| Invest in energy-efficient optical components | Adopting modern optical solutions supports EU Green Deal mandates and reduces operational costs for telecom infrastructure. |
| Form partnerships for private 5G deployments | Collaborations can capture new market demand for tailored fronthaul and backhaul solutions in industrial environments. |
| Enhance SDN capabilities for network slicing | Software-Defined Networking enables dynamic provisioning and management, crucial for the flexible service requirements of 5G networks. |
Research Approach
Findings reconcile primary fieldwork against secondary review of ITU standards documents, 3GPP specifications, and national telecom regulatory filings. This approach combined in-depth interviews with Mobile Network Operator executives and Infrastructure Vendor product managers. Additional insights came from Telecom Equipment Provider R&D leads and System Integrator technical directors. Bottom-up data aggregation and top-down market sizing validated all quantitative estimates.
The forecast inputs considered include 5G network deployment timelines and global fiber optic cable installation rates. Our analytical framework evaluates market dynamics across the analysis window using a multi-variable regression model. Segmentation dimensions modeled include Product Type, Technology, Application, End User, and regional 5G rollout maturity. Compound Annual Growth Rates were derived through rigorous regression analysis and scenario modeling, reflecting market evolution over the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or inflation rates would shift the trajectory. Forecasts reflect assumptions regarding 5G rollout pace and technology adoption, subject to unforeseen regulatory changes or rapid technological disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Cloud RAN Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
DWDM System Market
Telecommunications
Global IP Phone Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Global Broadband Services Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
5G System Integration Market
Telecommunications
Norway Telecom Market
Telecommunications
Chile Telecom Market
Telecommunications
Iran Telecom Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
Diameter Signaling Market
Telecommunications
Competitive Local Exchange Carriers (CLEC) Market
Telecommunications
Malaysia Telecom Market