
 Europe Managed SD-WAN Services Market | 2026-2036
Europe Managed SD-WAN Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Managed SD-WAN Services Market Insights
Mid-market manufacturers are rotating toward managed SD-WAN as their primary connectivity procurement model, displacing traditional MPLS-centric buying patterns. Orange Business anchors its European position through deep fiber infrastructure and sovereign cloud partnerships. Cisco Systems competes by extending its security-integrated SD-WAN stack through channel-controlled distribution. Vodafone Group specializes in pan-European managed services for regulated industries requiring data residency compliance.
Managed SD-WAN services encompass the outsourcing of software-defined wide area network design, deployment, monitoring, and optimization to third-party providers, typically delivered through centralized orchestration platforms that enforce application-aware traffic policies across hybrid infrastructure. The architecture separates the control plane from the data plane, enabling zero-touch provisioning and dynamic path selection based on real-time link quality metrics. Cloud-based deployment models lead the European market as enterprises accelerate migration of critical workloads to distributed cloud environments. SME-oriented service tiers represent the fastest-growing segment, though margin pools remain concentrated in multinational configurations where complexity premiums justify higher management fees. Hybrid deployment architectures retain structural importance for organizations maintaining legacy on-premises systems alongside cloud-native applications.
The EU NIS2 Directive and GDPR framework reshape provider obligations, mandating incident reporting timelines and cross-border data governance protocols that elevate compliance costs for pan-European deployments. ETSI standards for network function virtualization further constrain vendor selection by requiring interoperability certifications for infrastructure components. Stakeholders must evaluate whether their provider's security operations centers align with evolving ENISA guidance on supply chain resilience for telecommunications infrastructure.
Market Dynamics
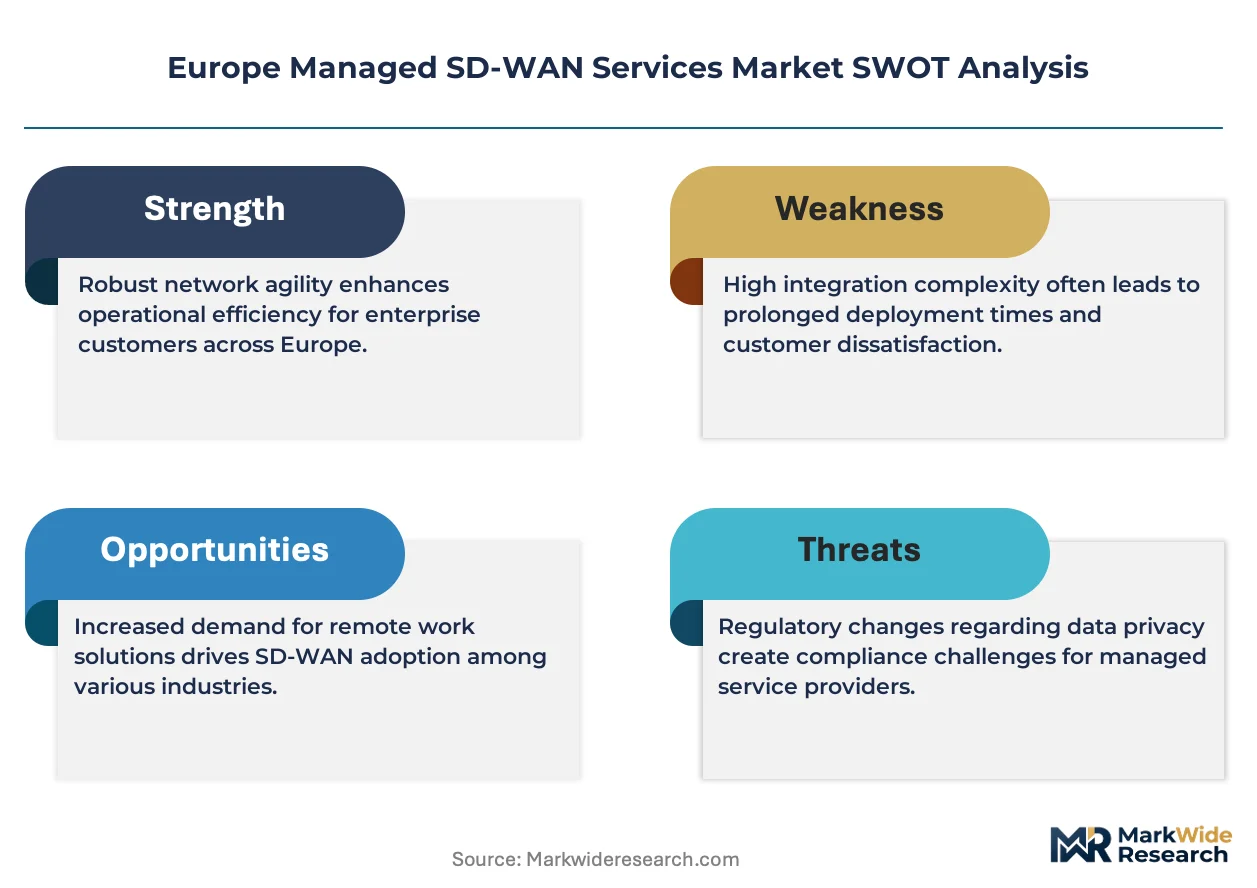
The EU NIS2 Directive is compressing procurement timelines as essential service operators race to achieve mandated network resilience standards before enforcement deadlines, forcing rapid vendor consolidation around certified managed service providers.
Growth Catalysts
- Cloud Migration Acceleration:Financial services institutions are prioritizing branch-to-cloud connectivity architectures that bypass traditional MPLS backhaul, creating immediate demand for managed overlay networks with embedded security stacks.
- GDPR Data Residency Mandates:Cross-border data governance protocols require pan-European enterprises to maintain sovereign network paths, elevating provider selection criteria toward EU-based infrastructure with localized security operations centers.
- SME Digitalization Programs:Germany, France, and the Netherlands are channeling public funding toward mid-market connectivity modernization, converting historically price-sensitive buyers into managed service subscribers.
Market Restraints
- ETSI Inter Certification Costs:Network function virtualization standards require expensive third-party validation for each infrastructure component, elevating vendor onboarding expenses that compress provider margins.
- Talent Concentration in Western Capitals:SD-WAN engineering expertise clusters in London, Paris, and Amsterdam, creating wage premiums and service delivery constraints for deployments in Southern and Eastern Europe.
- Legacy MPLS Contract Rollovers:Enterprises locked into multi-year carrier agreements face penalty structures that delay managed SD-WAN transitions despite technical readiness.
Strategic Opportunities
- Poland and Romania Expansion:Nearshore delivery centers in these markets offer cost arbitrage for managed security operations while maintaining EU data residency compliance under GDPR frameworks.
- AI-Driven Network Automation:Convergence of machine learning inference with SD-WAN orchestration platforms enables predictive path selection and autonomous incident response, differentiating premium service tiers.
- ENISA Supply Chain Guidance:Emerging cybersecurity certification schemes for telecommunications infrastructure create first-mover advantages for providers pre-emptively aligning security operations center architectures with draft standards.
Industry Challenges
- Multi-Vendor Integration Complexity:Enterprises demand seamless interoperability between incumbent firewall estates and cloud-native SD-WAN controllers, stretching professional services capacity at provider organizations.
- Zero-Touch Provisioning Skill Gaps:Field engineering teams require retraining from hardware-centric installation practices toward software-defined automation workflows, slowing deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Managed SD-WAN Services Market |
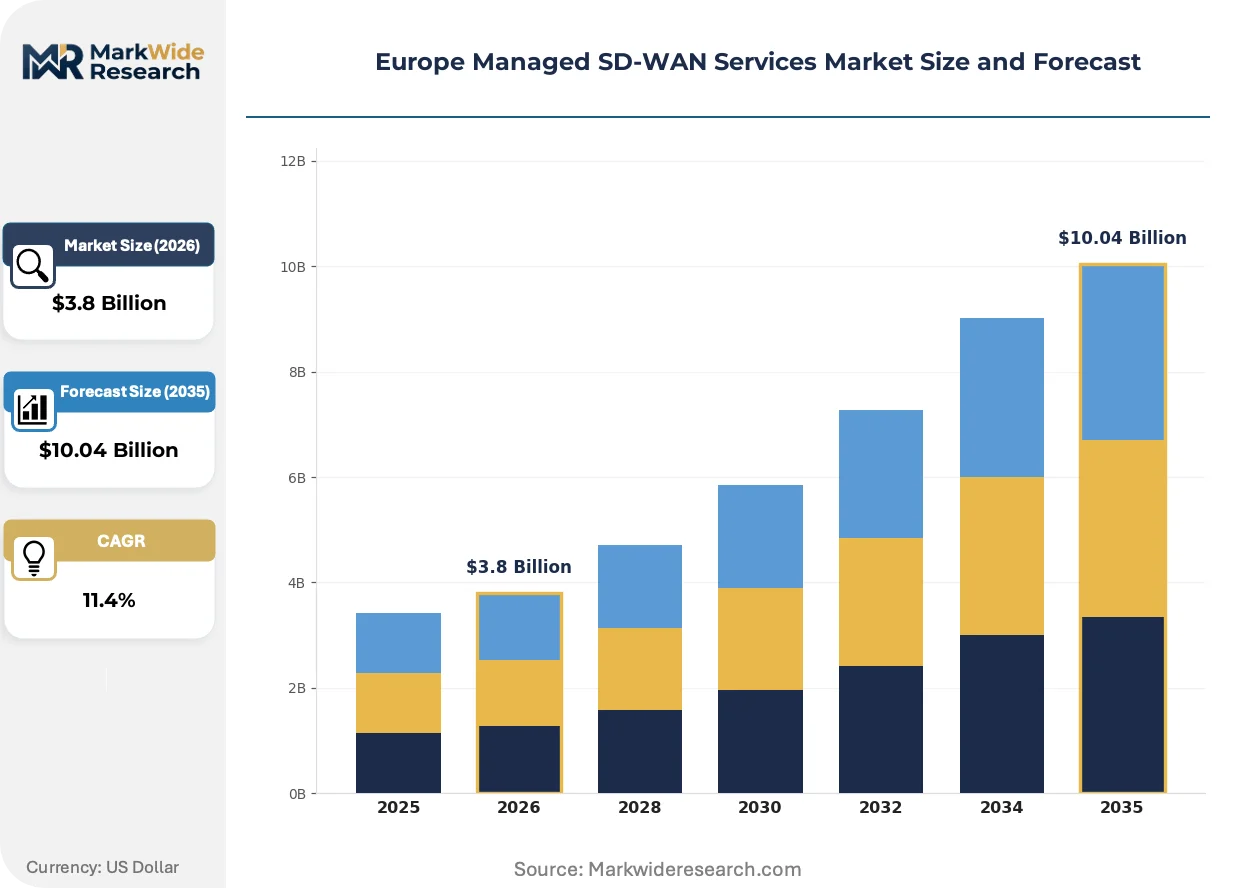
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Monitoring, Configuration, Management, Optimization Deployment Model: Cloud-Based, On-Premises, Hybrid, Multi-Cloud End User Type: Enterprises, SMEs, Government, Educational Institutions Size of Organization: Small, Medium, Large, Multinational |
| Companies Covered | Palo Alto Networks, Orange Business, Cisco Systems, Juniper Networks, VMware, Vodafone Group, AT&T, Huawei, NTT Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Managed SD-WAN Services Market Trends and Innovations
Security-integrated network architectures are displacing standalone connectivity procurement, with buyers demanding converged platforms that collapse WAN optimization, firewall, and zero-trust access into single managed contracts.
SASE architecture adoption is fragmenting traditional SD-WAN vendor categories as cloud security specialists encroach on connectivity markets and incumbent carriers acquire cloud-native security stacks to defend position. Mid-market manufacturers are piloting these converged platforms fastest, compressing the vendor evaluation cycle from twelve months to under ninety days. This technology convergence is fragmenting procurement authority between CIO and CISO functions, creating elongated internal buying committees.
The EU AI Act introduces algorithmic transparency requirements for automated network management systems, compelling providers to document decision logic within SD-WAN path selection engines. Industrial consequence includes mandatory human-in-the-loop protocols for critical infrastructure deployments that slow autonomous orchestration rollouts. Regulated sectors including energy and transport are most affected, with operators in Germany and France pre-emptively redesigning control plane architectures to satisfy anticipated audit protocols.
Enterprise buying committees are consolidating vendor relationships, replacing best-of-breed component sourcing with single-provider accountability for end-to-end branch connectivity. This pattern disrupts traditional channel structures where systems integrators historically stitched together multi-vendor solutions. The shift is most visible in Netherlands-based multinational headquarters, where procurement teams are mandating unified service level agreements spanning access, transport, and security layers.
Europe Managed SD-WAN Services Market Segmentation
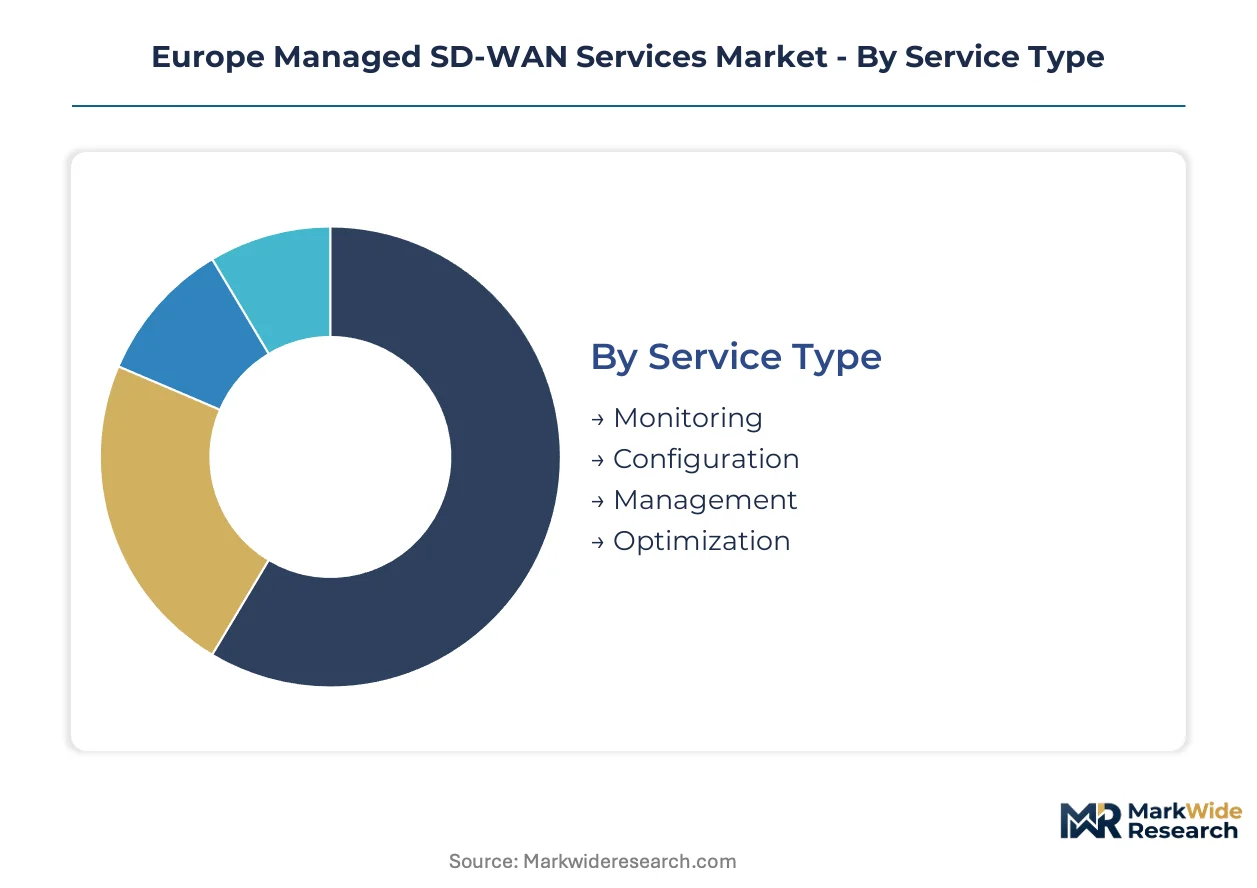
Managed SD-WAN procurement patterns diverge sharply across service tiers and organizational scale. Channel strategy, deployment complexity, and compliance obligations create distinct margin profiles that reshape provider resource allocation across European markets.
Service Type:
Channel economics vary substantially across the service stack, with high-touch professional services commanding direct sales engagement while automated tiers flow through distributor networks.
- Monitoring:Real-time telemetry collection and dashboard visualization of link performance, latency, and application experience metrics. German automotive suppliers and Dutch logistics operators drive concentration here, prioritizing uptime visibility across distributed manufacturing sites under strict EU NIS2 uptime mandates.
- Configuration:Policy definition, zero-touch provisioning workflows, and orchestration template design that governs traffic steering rules. French financial institutions anchor demand, requiring sovereign data path configuration to satisfy GDPR cross-border transfer restrictions and national regulator audit protocols.
- Management:Day-to-day operational oversight including firmware updates, security patch deployment, and incident response coordination.
- Optimization:Continuous traffic engineering, application performance tuning, and cost-performance balancing across access links.
By volume, Management leads as the baseline subscription tier. By growth pace, Configuration is climbing fastest amid NIS2-driven policy standardization urgency.
Deployment Model:
Cost-to-serve spreads widen dramatically across deployment architectures, with cloud-native delivery enabling margin expansion through automation while hybrid configurations absorb disproportionate professional services burden.
- Cloud-Based:Fully hosted control plane with provider-operated orchestration infrastructure and SaaS-delivered management portals. Mid-market manufacturers in the Netherlands and Belgium concentrate here, leveraging rapid provisioning to support cloud-first digitalization programs without capital-intensive infrastructure builds.
- Hybrid:Split architecture retaining on-premises controllers for latency-sensitive workloads alongside cloud-managed branch appliances. German energy utilities and transport operators dominate this segment, balancing GDPR data residency requirements with real-time SCADA network performance needs.
- On-Premises:Customer-managed controller deployment within enterprise data centers or colocation facilities.
- Multi-Cloud:Orchestration spanning multiple public cloud provider environments with unified policy enforcement.
Cloud-Based deployments capture the largest subscriber base. Hybrid architectures command the steepest expansion trajectory as regulated sectors straddle legacy and cloud-native infrastructure.
End User Type:
Customer maturity and procurement sophistication create tiered service packaging requirements, with enterprise buyers demanding bespoke SLAs while SME segments absorb standardized catalog offerings.
- Enterprises:Complex multi-site deployments with custom integration requirements, dedicated account management, and negotiated liability frameworks. Pan-European headquarters in Frankfurt, Paris, and Amsterdam anchor this tier, consolidating vendor relationships under unified connectivity accountability spanning access, transport, and security layers.
- SMEs:Standardized service tiers with templated configurations, self-service portals, and accelerated deployment cycles. German, French, and Dutch mid-market manufacturers drive expansion here, converting from MPLS through publicly subsidized digitalization programs that reduce procurement risk.
- Government:Sovereign network requirements with enhanced security clearance, domestic infrastructure mandates, and public procurement compliance.
- Educational Institutions:Campus and research network connectivity with seasonal bandwidth scaling and collaborative research network integration.
Enterprises generate the deepest revenue pools per account. SMEs are expanding most quickly as public funding unlocks historically price-constrained demand.
Size of Organization:
Account profitability inverts across organizational scale, with mid-size deployments hitting the sweet spot between contract value and service delivery complexity.
- Multinational:Pan-European or global footprint with 50+ sites, multi-currency contracting, and complex data residency orchestration. These accounts justify dedicated security operations center alignment and custom ENISA supply chain compliance documentation.
- Large:National or regional scale with 10-50 sites, standardized configurations, and procurement committee governance.
- Medium:3-10 site deployments with accelerating cloud migration requirements and compressed vendor evaluation cycles.
- Small:Single-site or few-site configurations with out-of-box deployment and minimal customization.
Multinational contracts concentrate margin contribution. Medium organizations are gaining share fastest as channel programs target the underserved middle market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier-grade infrastructure and sovereign cloud capacity concentrate in Germany, France, and the Netherlands, with these three markets absorbing the majority of pan-European managed SD-WAN contract value. Southern and Eastern European markets are gaining traction as nearshore delivery centers and EU funding programs unlock mid-market demand.
Germany
Automotive suppliers and energy utilities drive managed SD-WAN procurement, prioritizing hybrid deployment architectures that balance GDPR data residency with SCADA network performance. The EU NIS2 Directive imposes strict uptime mandates on essential service operators, compressing vendor selection timelines. Frankfurt anchors demand concentration, with multinational headquarters consolidating connectivity contracts under unified accountability frameworks.
France
Financial institutions and transport operators dominate configuration-intensive deployments, requiring sovereign data path design to satisfy CNIL audit protocols and cross-border transfer restrictions. The EU AI Act introduces algorithmic transparency requirements for automated network management systems. Paris-based procurement teams are mandating single-provider SLAs spanning access, transport, and security layers.
Netherlands
Mid-market manufacturers and logistics operators concentrate in cloud-native deployment tiers, leveraging rapid provisioning to support digitalization programs without capital-intensive infrastructure builds. Public funding channels accelerate SME conversion from legacy MPLS contracts. Amsterdam headquarters of pan-European multinationals are consolidating vendor relationships and compressing evaluation cycles to under ninety days.
Poland
Nearshore delivery centers in Warsaw and Krakow offer cost arbitrage for managed security operations while maintaining full EU data residency compliance. ETSI interoperability certification requirements elevate vendor onboarding expenses, favoring established providers with pre-certified infrastructure stacks. German and French enterprises are routing Eastern European branch traffic through Polish-anchored security operations centers.
United Kingdom
London-based financial services and professional services firms demand security-integrated network architectures that collapse WAN optimization, firewall, and zero-trust access into single managed contracts. Post-Brexit data governance frameworks create parallel compliance obligations for UK-EU traffic flows. The concentration of SD-WAN engineering expertise in London generates wage premiums that slow service delivery scaling.
Europe Managed SD-WAN Services Market Competitive Landscape
Concentration sits with telecom carriers and network equipment vendors that combine infrastructure ownership with managed service delivery capabilities. The competitive structure is moderately consolidated, with tier-one providers capturing multinational contracts while regional specialists contest mid-market segments. Two strategic archetypes dominate: carrier-integrated platforms leveraging fiber assets and sovereign cloud partnerships, and security-first vendors extending firewall estates into connectivity markets. Dominant competitive moves include vertical integration into cloud security stacks and geographic expansion through nearshore delivery center establishment.
Within the carrier-integrated tier, Orange Business and Vodafone Group exemplify providers combining deep European fiber infrastructure with GDPR-compliant data residency architectures. Cisco Systems anchors the security-first archetype, extending its integrated SD-WAN and firewall stack through channel-controlled distribution models. These three companies occupy positions that reflect the market's bifurcation between infrastructure-heavy and security-centric procurement criteria.
| Leading Market Players |
|---|
| Palo Alto Networks |
| Orange Business |
| Cisco Systems |
| Juniper Networks |
| VMware |
| Vodafone Group |
| AT&T |
| Huawei |
| NTT Limited |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at centralized orchestration platforms in Germany and the Netherlands creates scale economies that compress per-site management costs while elevating price floors for smaller deployments. This concentration of control plane infrastructure concentrates pricing power among providers with pre-certified ETSI stacks, forcing mid-tier competitors toward cost-absorbing professional services or exit.
Pricing Analysis
Volume-discount tiering structures separate multinational configurations with 50-plus sites from mid-market packages and SME self-service tiers. Pricing stratifies across premium, standard, and economy levels based on security operations center alignment and GDPR compliance certification depth. Cost compression in the SME tier is intensifying because public subsidy programs convert price-sensitive buyers into managed service subscribers with standardized expectations. Multinational enterprises exhibit lowest price sensitivity due to complexity premiums justifying unified SLA accountability, while single-site configurations face acute margin pressure from automated provisioning commoditization.
Supply Chain Analysis
Germany and the Netherlands anchor control plane infrastructure development, while Poland and Romania feed nearshore security operations capacity. Component sourcing draws from Taiwan for network appliance silicon, Ireland for cloud orchestration software development, and domestic EU facilities for GDPR-compliant data center builds. Single-source vulnerability concentrates in specialized SD-WAN engineering talent clustered in London, Paris, and Amsterdam. Distribution runs through carrier-direct sales for enterprise tiers, distributor networks for SME automation, and systems integrator partnerships for hybrid deployment complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Managed SD-WAN Services Market is cycling through a compliance-driven recovery phase as EU NIS2 enforcement deadlines compress procurement timelines and consolidate vendor relationships around certified providers.
For Market Incumbents: Fortify position by deepening sovereign cloud partnerships in Frankfurt and Amsterdam data center clusters to defend against cloud-native security specialists encroaching on connectivity markets. Prioritize ENISA supply chain certification pre-alignment to capture first-mover advantage as emerging cybersecurity schemes for telecommunications infrastructure crystallize. Channel control tightening through exclusive distributor agreements in the mid-market segment represents the critical defensive lever against margin erosion. For New Entrants and Emerging Players: Anchor in Poland and Romania nearshore delivery centers where cost arbitrage for managed security operations meets full EU data residency compliance, creating white-space opportunity against Western European incumbent cost structures. Target medium-sized manufacturers with 3-10 site deployments in Germany, France, and the Netherlands where compressed vendor evaluation cycles favor agile challengers over established carrier bureaucracies. Lead with AI-driven network automation as the differentiated go-to-market angle to bypass incumbent professional services dependencies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among providers with pre-certified ETSI infrastructure stacks and established security operations center footprints spanning multiple EU jurisdictions, indicating superior long-term viability through the 5-10 year regulatory enforcement window. Acquisition target archetype: regional specialists in Southern and Eastern Europe with sovereign network capabilities and underpenetrated mid-market channel relationships. Monitor ENISA supply chain guidance finalization as the critical inflection signal for valuation multiple expansion among pre-compliant providers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converged SASE architectures collapse WAN, firewall, and zero-trust into single managed contracts, displacing multi-vendor procurement patterns. |
| Geographic Expansion | Nearshore delivery center establishment in Poland and Romania unlocks cost arbitrage while maintaining GDPR data residency compliance. |
| Strategic Partnership | Sovereign cloud partnerships with Frankfurt and Amsterdam data center operators satisfy CNIL and BSI audit protocols for financial institutions. |
| Acquisition of Specialist Firm | Cloud-native security stack purchases defend carrier-integrated positions against Palo Alto Networks and Cisco Systems encroachment. |
| Product Launch | AI-driven network automation tiers differentiate premium service offerings through predictive path selection and autonomous incident response capabilities. |
Research Methodology
A spread of perspectives from enterprise CIOs, CISO procurement committees, managed service provider network architects, and channel distributor executives converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against ETSI certification databases, ENISA supply chain guidance drafts, EU NIS2 implementation timelines, and hyperscaler European capex disclosures. Bottom-up site deployment modeling and top-down carrier revenue segmentation were triangulated to anchor volume estimates.
Segmentation dimensions modeled span service type, deployment architecture, organization scale, and end-user vertical across the projection horizon. CAGRs were derived from deployment velocity curves weighted by NIS2 compliance urgency and public funding program conversion rates. Forecast inputs incorporated SD-WAN engineering talent availability by metro cluster, ETSI interoperability certification backlogs, and cloud migration pipeline data from financial services and manufacturing verticals.
Underlying assumptions cover sustained EU regulatory enforcement, stable hyperscaler European expansion, and continued mid-market digitalization funding, with deviation risk concentrated in legacy MPLS contract rollover delays and talent concentration wage spirals in Western capitals. Recalibration cycles align with material shifts in ENISA guidance finalization, EU AI Act algorithmic transparency rulemaking, and NIS2 penalty enforcement precedents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
Peru Telecom Market
Telecommunications
Argentina Telecom Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Turkey Telecom Market
Telecommunications
Global International Calling Apps Market
Telecommunications
Global Radio Access Network Market
Telecommunications
Brazil Telecom Market
Telecommunications
IP PBX Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
Managed M2M Services Market