
 Global Radio Access Network Market | 2026-2036
Global Radio Access Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radio Access Network Market Foresight
Silicon-to-gallium-nitride migration in power amplifiers is consolidating product economics across radio unit manufacturing. Ericsson anchors European supply chains through captive GaN sourcing and in-house module design. Nokia Corporation leverages its ReefShark chipset architecture to sustain margin advantages in massive MIMO deployments. Samsung Electronics Co. Ltd dominates 5G NR equipment shipments across Northeast Asian markets through vertically integrated semiconductor foundries.
A Radio Access Network constitutes the wireless telecommunications infrastructure connecting user devices to core networks through base stations, radio transceivers operating across licensed spectrum bands from 600 MHz to 100 GHz, and backhaul transport links. Its primary commercial purpose enables subscriber data and voice sessions to traverse between mobile handsets and operator core infrastructure with defined latency thresholds. Small Cell deployments now represent the fastest-expanding component category as densification requirements outpace macro site permitting cycles in metropolitan zones. 5G NR technology leads capital allocation across operator budgets while LTE sustains residual upgrade demand in emerging markets where spectrum refarming proceeds gradually.
The FCC in the United States enforces spectrum auction rules and equipment authorization standards that determine vendor market access timelines. ETSI and 3GPP frameworks in Europe codify interoperability mandates shaping procurement specifications for Open RAN architectures. China's MIIT governs domestic network equipment certification and domestic vendor preference policies that influence competitive dynamics. Stakeholders must monitor evolving national security screening regimes for foreign telecommunications equipment as these frameworks increasingly dictate supplier eligibility across major deployment markets.
Market Dynamics
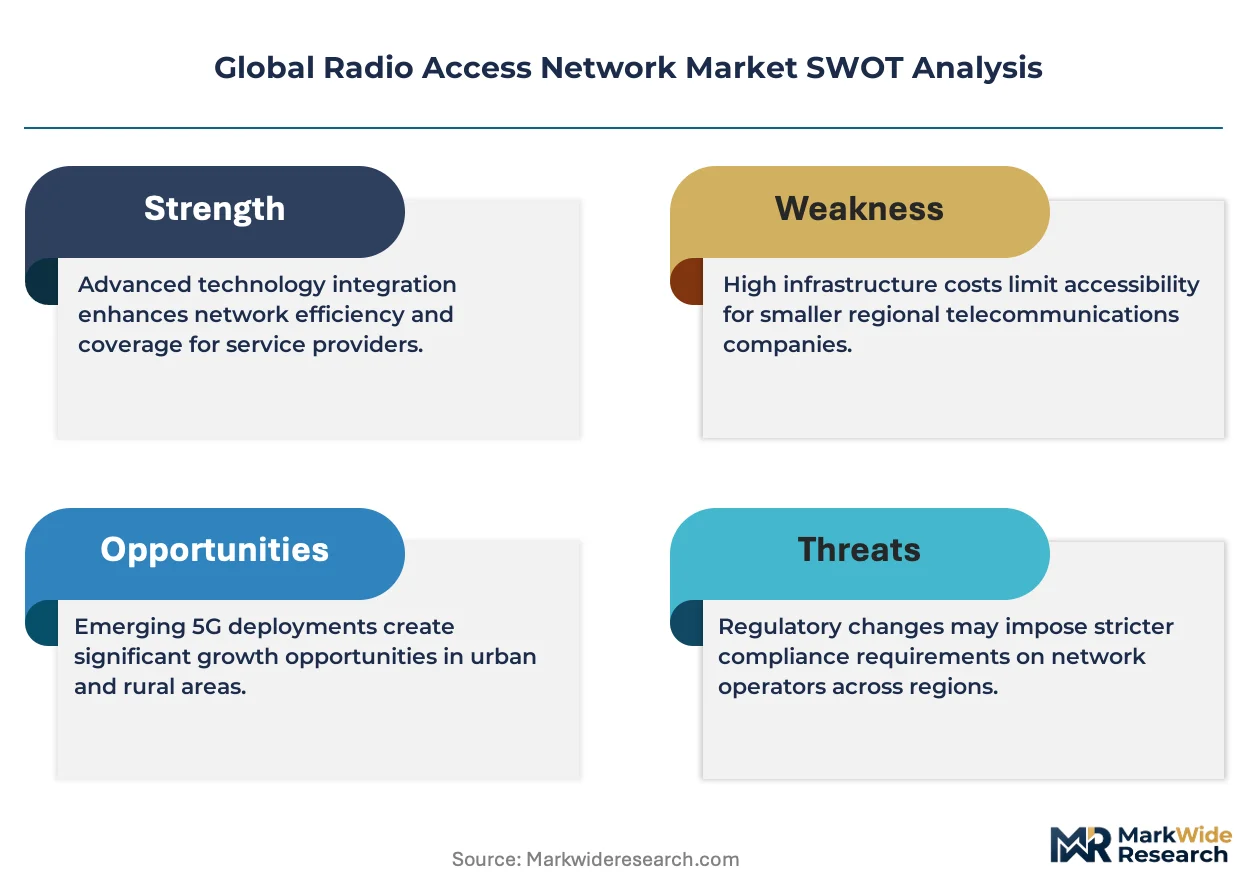
Silicon-to-gallium-nitride migration in power amplifiers is compressing radio unit manufacturing costs while fragmenting supplier hierarchies across base station ecosystems.
Growth Catalysts
- 5G NR spectrum mandates:The FCC's mid-band auction rules and Germany's 3.5 GHz framework are accelerating infrastructure replacement cycles across urban corridors.
- Small cell densification:Metropolitan permitting bottlenecks for macro sites are redirecting capital toward compact base station deployments in Seoul, Mumbai, and São Paulo.
- Open RAN interoperability standards:ETSI and 3GPP specifications are disaggregating hardware-software bundles and enabling multi-vendor procurement models.
Market Restraints
- GaN substrate concentration:Epitaxial wafer supply chains cluster in Japanese and US specialty foundries, creating input bottlenecks for power amplifier modules.
- Equipment authorization delays:FCC certification timelines for new radio configurations extend 12-18 months, freezing vendor market entry schedules.
- Macro site permitting moratoria:Municipal zoning restrictions in dense European and North American cities are constraining macro deployment velocity.
Strategic Opportunities
- Private 5G networks:Manufacturing campuses and port authorities in Germany and South Korea are procuring dedicated radio infrastructure outside carrier frameworks.
- Millimeter-wave backhaul:28 GHz and 39 GHz fixed wireless links are displacing fiber trenching in suburban and rural connectivity builds.
- India's base station rollout:Reliance Jio and Bharti Airtel's procurement programs are creating volume anchors for equipment vendors with localized supply chains.
Industry Challenges
- RF engineering talent scarcity:Millimeter-wave circuit design and massive MIMO beamforming expertise concentrates in a handful of semiconductor hubs.
- Legacy LTE integration:Refarming sub-3 GHz spectrum for 5G NR while maintaining backward-compatible voice services complicates software-defined radio architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radio Access Network Market |
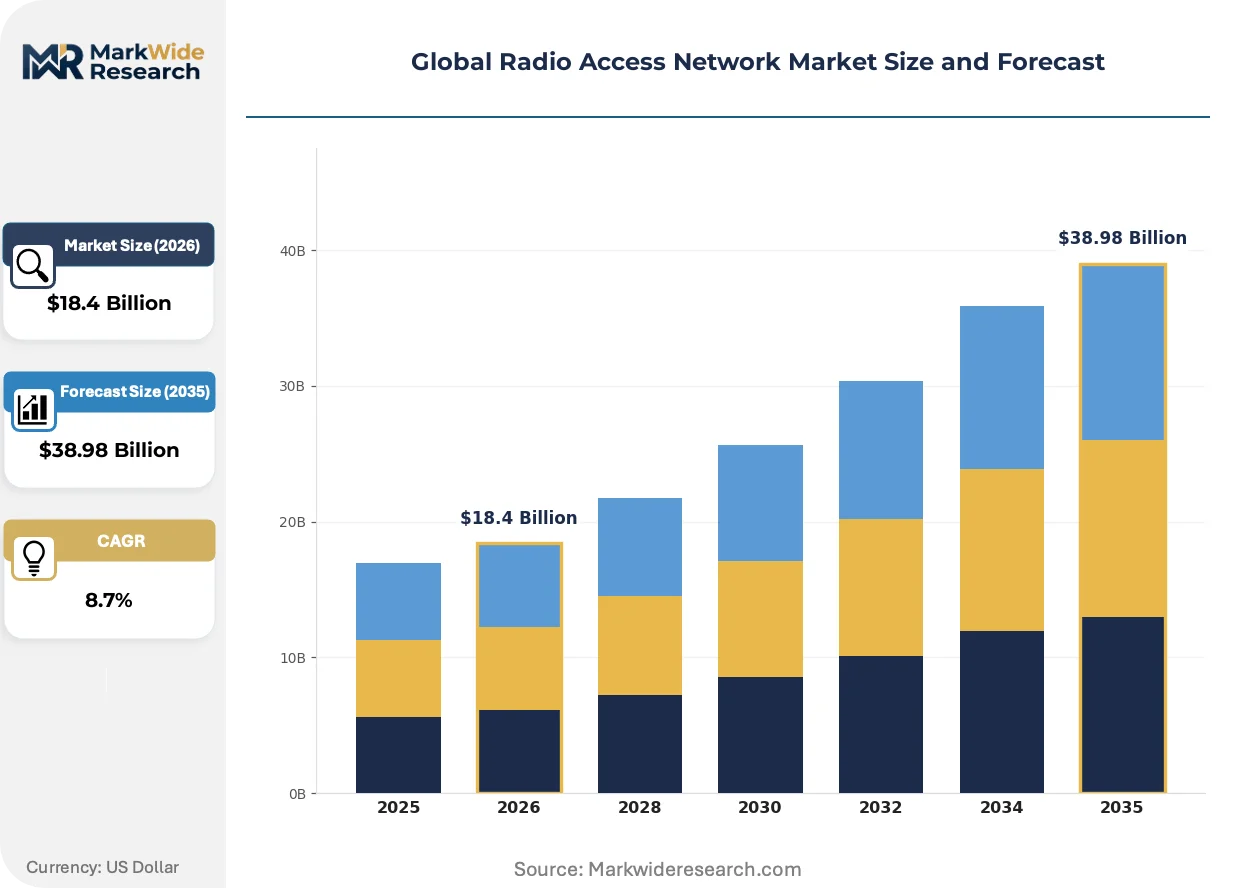
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE, 5G NR, WCDMA, GSM, CDMA, TD-SCDMA Component Type: Macro Cell, Small Cell, Distributed Antenna System, Remote Radio Unit, Baseband Unit, Optical Transport Application: Mobile Broadband, Fixed Wireless Access, IoT Connectivity, Public Safety Networks, Private LTE, Smart Cities End User Industry: Telecommunications Operators, Government Agencies, Utilities, Transportation Providers, Media & Entertainment, Enterprises |
| Companies Covered | Samsung Electronics Co. Ltd, Cisco Systems Inc, Ericsson, Fujitsu Limited, NEC Corporation, Nokia Corporation, ZTE Corporation, Qualcomm Technologies Inc, Huawei Technologies Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radio Access Network Market Shifts & Advancements
Open RAN disaggregation protocols are dissolving traditional vendor lock-in structures and enabling modular procurement across radio, baseband, and software layers.
Virtualized baseband processing is decentralizing network intelligence from centralized data centers toward edge compute nodes. Tier-1 operators in South Korea and Germany are deploying cloud-native distributed units to cut transport latency for industrial automation use cases. This shift is compressing incumbent vendors' integrated hardware margins while expanding software licensing revenue pools.
The EU's Cybersecurity Certification Scheme for 5G networks is mandating formal assurance frameworks for critical radio components. Equipment vendors must now document supply chain provenance and firmware integrity across their product portfolios. German and French procurement specifications are embedding these requirements as mandatory bid preconditions.
Enterprise buyers are unbundling network equipment from managed service contracts and procuring radio units directly for private deployment models. Mining operations in Australia and automotive plants in Germany are sourcing base stations independently of traditional carrier relationships. This disintermediation is fragmenting historical channel structures and forcing vendors to build direct sales capabilities.
Global Radio Access Network Market Segmentation
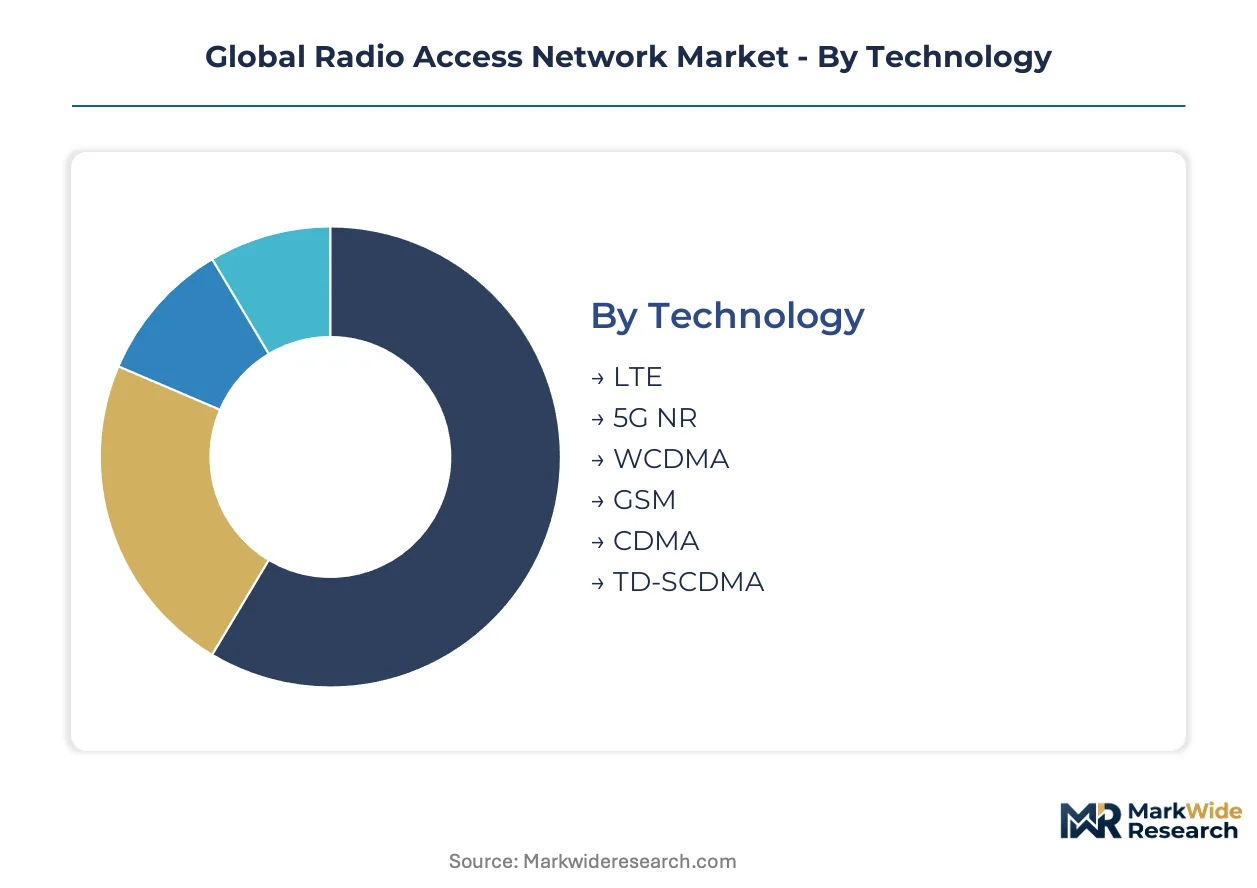
Radio access network procurement varies sharply by deployment scale, spectrum regime, and operational ownership. Segmentation reveals where capital concentrates versus where technology transitions create substitution risks.
Technology:
Standardization intensity spans from globally harmonized 5G NR specifications to legacy GSM protocols with fragmented regional implementations.
- 5G NR:Operates across sub-6 GHz and millimeter-wave bands with massive MIMO beamforming architectures. Deployment concentrates in Germany, South Korea, and the United States where mid-band spectrum auctions have concluded; Ericsson and Samsung dominate base station shipments through captive GaN power amplifier sourcing.
- LTE:Mature FDD/TDD platforms sustaining residual upgrade cycles in emerging markets. India absorbs the largest volume of LTE macro equipment as Reliance Jio and Bharti Airtel extend 4G coverage ahead of 5G NR migration timelines.
- WCDMA:3G infrastructure maintaining voice fallback in rural European zones and legacy spectrum holdings.
- GSM:2G networks persisting for machine-to-machine modules and low-cost voice in Sub-Saharan Africa and parts of South Asia.
- CDMA:Declining footprint limited to specific North American rural carriers and some Latin American operators.
- TD-SCDMA:China-specific 3G standard phased out domestically, negligible new investment.
Most installed capacity flows through LTE. Expansion is steepest in 5G NR.
Component Type:
Physical form factors range from street-level concealment requirements to tower-mounted high-power assemblies with distinct thermal and power constraints.
- Small Cell:Compact base stations below 10W output power designed for metropolitan densification. Demand clusters in Seoul, Mumbai, and São Paulo where macro site permitting bottlenecks redirect capital toward lamp post and building-mounted deployments.
- Macro Cell:High-power outdoor base stations serving wide-area coverage. Rural India and suburban United States represent active procurement zones as operators close geographic coverage gaps.
- Remote Radio Unit:Separated RF processing elements connected to centralized baseband via optical fronthaul. Open RAN disaggregation protocols are accelerating multi-vendor procurement of these units.
- Distributed Antenna System:In-building coverage infrastructure for airports, stadiums, and transit hubs. Sports venues in Germany and transportation terminals in Japan drive specification requirements.
- Baseband Unit:Centralized or distributed signal processing hardware; cloud-native virtualization is compressing dedicated hardware margins.
- Optical Transport:Fronthaul and backhaul fiber or microwave links connecting radio elements to core networks.
Procurement volume tilts toward Remote Radio Units. Climbing the fastest are Small Cell contracts.
Application:
Use case diversity stretches from consumer mass-market data to mission-critical infrastructure with divergent latency and reliability specifications.
- Mobile Broadband:Consumer smartphone data delivery constituting the revenue foundation for carrier business models. Urban corridors in Germany and South Korea show the highest per-capita throughput requirements.
- Private LTE:Dedicated campus networks for industrial automation and asset tracking. Mining operations in Australia and automotive assembly plants in Germany procure equipment independently of public carrier frameworks.
- Fixed Wireless Access:Residential broadband substitution using 5G NR in millimeter-wave or C-band spectrum. Suburban United States markets with fiber deployment gaps represent active target zones.
- IoT Connectivity:Massive machine-type communications requiring extended coverage and deep indoor penetration.
- Public Safety Networks:First responder communications with hardened reliability requirements; government agencies in the United States and France specify dedicated spectrum.
- Smart Cities:Integrated sensor and video infrastructure requiring dense small cell grids.
Mobile Broadband carries the heaviest equipment load. Gaining share fastest is Private LTE.
End User Industry:
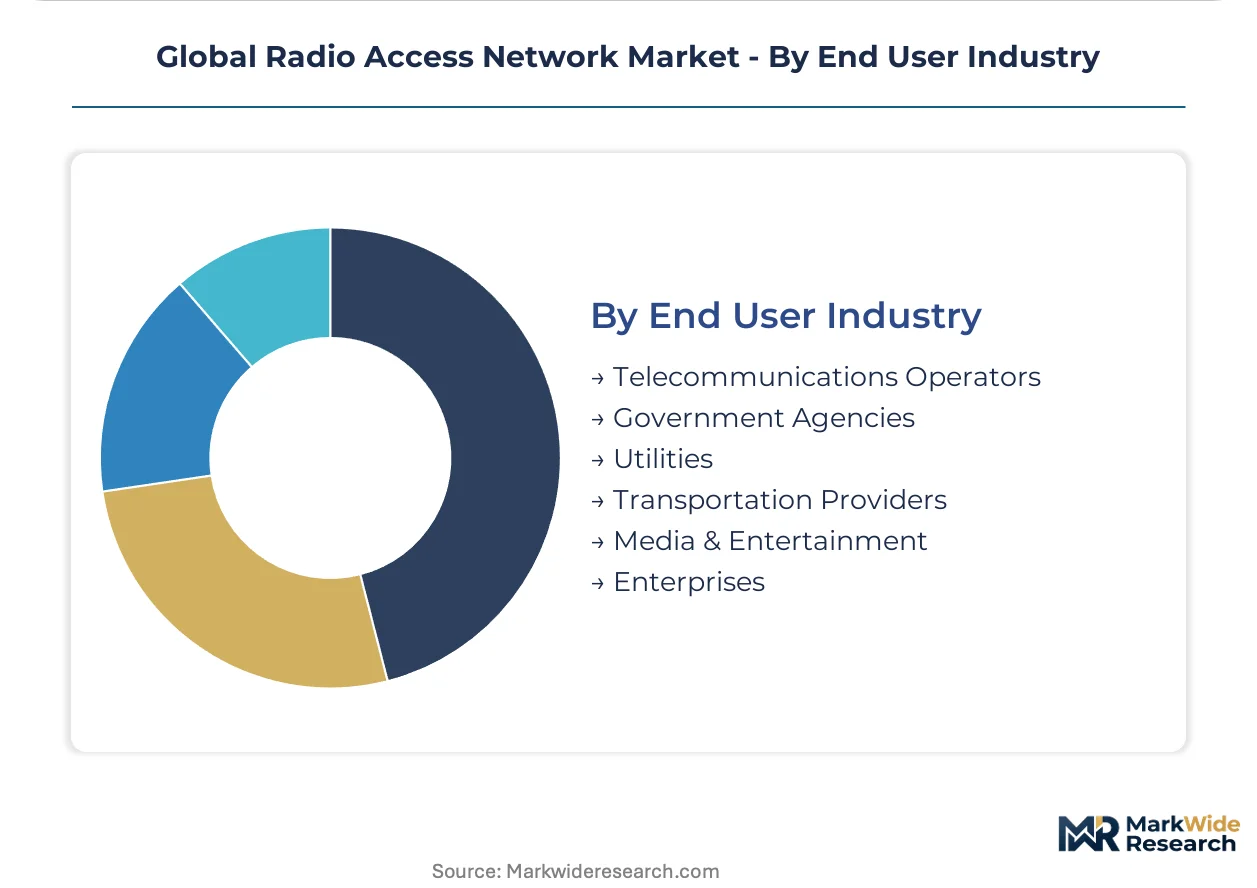
Customer archetypes span from volume-aggregating national carriers to fragmented enterprise buyers with divergent technical sophistication and contract structures.
- Telecommunications Operators:Tier-1 and Tier-2 mobile network operators constituting the traditional procurement channel. Reliance Jio and Bharti Airtel in India, Deutsche Telekom in Germany, and Verizon in the United States set annual volume anchors.
- Enterprises:Manufacturing, logistics, and energy companies procuring private network infrastructure. Port authorities in South Korea and chemical complexes in Germany are executing direct equipment purchases outside carrier managed services.
- Government Agencies:Defense and civilian authorities with sovereign network requirements and security screening mandates.
- Utilities:Power and water grid operators deploying private wireless for field workforce and smart meter backhaul.
- Transportation Providers:Railways, airports, and maritime ports requiring trackside and terminal coverage.
- Media & Entertainment:Broadcasters and venue operators supplementing carrier coverage for event-specific capacity surges.
Telecommunications Operators absorb the dominant share. Direct enterprise procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's base station rollout commands immediate attention as Reliance Jio and Bharti Airtel execute massive procurement programs. FCC spectrum mandates in the United States and Germany's 3.5 GHz framework are accelerating infrastructure replacement cycles across urban corridors. Seoul, Mumbai, and São Paulo represent critical deployment clusters where metropolitan permitting bottlenecks redirect capital toward densification.
United States
Verizon and AT&T are driving mid-band 5G NR deployment across suburban corridors and rural coverage gaps. FCC equipment authorization standards extend certification timelines to 12-18 months, freezing vendor market entry schedules. The Pacific Northwest and Texas corridor host active macro site construction as operators close geographic coverage deficits.
Germany
Deutsche Telekom's massive MIMO procurement anchors European capital allocation for 5G NR infrastructure. ETSI interoperability mandates and the EU Cybersecurity Certification Scheme shape procurement specifications for Open RAN architectures. Bavaria and North Rhine-Westphalia concentrate industrial automation demand driving private 5G network deployments at automotive plants and chemical complexes.
India
Reliance Jio and Bharti Airtel are executing the world's largest base station rollout, creating volume anchors for equipment vendors with localized supply chains. TRAI spectrum allocation frameworks and the Department of Telecommunications' equipment certification requirements govern vendor eligibility. Maharashtra and Karnataka host the densest deployment corridors as operators extend 4G coverage ahead of 5G NR migration timelines.
South Korea
SK Telecom and KT Corporation are deploying cloud-native distributed units to cut transport latency for industrial automation use cases. The Ministry of Science and ICT governs domestic network equipment certification and spectrum allocation for millimeter-wave backhaul links. The Seoul Capital Area and Busan-Ulsan corridor concentrate small cell densification as metropolitan permitting bottlenecks constrain macro site velocity.
Japan
NTT Docomo and KDDI are procuring massive MIMO equipment for urban corridor densification and stadium coverage upgrades. METI industrial policy frameworks and the Ministry of Internal Affairs and Communications' spectrum auction rules determine vendor market access. The Kanto-Tokyo and Kansai-Osaka regions drive specification requirements for distributed antenna systems at transportation terminals and sports venues.
Global Radio Access Network Market Competitive Landscape
Global majors compete with regional champions across radio unit manufacturing and semiconductor sourcing. The vendor base clusters around three strategic tiers: integrated equipment vendors with captive GaN supply chains, semiconductor specialists supplying power amplifier modules, and emerging Open RAN software vendors disaggregating hardware-software bundles. Competitive moves concentrate on strategic partnerships for localized manufacturing and technology licensing for millimeter-wave beamforming architectures.
Within the integrated equipment tier, Samsung Electronics Co. Ltd and Ericsson exemplify scale-driven positions with vertically controlled component sourcing. Nokia Corporation occupies a distinct position through its ReefShark chipset architecture. ZTE Corporation and Huawei Technologies Co. Ltd represent the Chinese vendor segment facing divergent market access conditions across Western and emerging markets. Cisco Systems Inc and Qualcomm Technologies Inc anchor the semiconductor and software layers supplying disaggregated radio elements.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd |
| Cisco Systems Inc |
| Ericsson |
| Fujitsu Limited |
| NEC Corporation |
| Nokia Corporation |
| ZTE Corporation |
| Qualcomm Technologies Inc |
| Huawei Technologies Co. Ltd |
| Others |
Supply & Pricing Matrix
GaN-enabled premium radio units and silicon-based commodity base stations diverge sharply in cost structures, with that bifurcation mapping directly onto supplier concentration in Japanese epitaxial wafer foundries and dispersed assembly networks in India and Vietnam. FCC equipment authorization delays and India's PLI localization mandates reshape how vendors configure regional pricing and sourcing footprints.
Pricing Analysis
Input-cost pass-through from gallium-nitride substrate scarcity dominates pricing dynamics for high-power macro equipment. Three-tier pricing structure across premium massive MIMO, standard macro, and economy small cell levels reflects certification grade and captive GaN supply. Pricing pressure stems from Open RAN disaggregation commoditizing baseband hardware. Telecommunications operators show highest price sensitivity; private 5G enterprise buyers accept premium positioning for latency guarantees.
Supply Chain Analysis
India's PLI scheme and Germany's Cybersecurity Certification Scheme reshape sourcing by mandating domestic assembly and documented firmware provenance. Epitaxial wafer supply concentrates in Japan and the United States; power amplifier module assembly clusters in South Korea and Taiwan. Raw material dependencies span GaN substrates, RF filter ceramics, and high-purity copper for thermal management. Single-source vulnerability runs through Japanese specialty foundries. Distribution runs through carrier procurement frameworks with direct enterprise channels expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where 5G NR massive MIMO specifications harden and Open RAN interoperability becomes table stakes rather than differentiator.
For Market Incumbents: Lock in captive GaN supply through long-term offtake agreements with Japanese epitaxial wafer producers. Deepen backward integration into power amplifier module design to defend margin position against Open RAN disaggregation. Prioritize certification investment under EU Cybersecurity Certification Scheme to maintain bid eligibility across German and French procurement cycles.
For New Entrants and Emerging Players: Millimeter-wave beamforming algorithms offer a technology-first wedge into private 5G network deployments at German automotive plants and South Korean port authorities. Target India's base station rollout through localized manufacturing partnerships with Reliance Jio and Bharti Airtel. Lead with software-defined radio stacks that virtualize baseband processing and bypass incumbent hardware margins.
For Investors and Strategic Acquirers: Consolidation pressure builds where Open RAN software vendors lack hardware manufacturing scale and integrated equipment vendors seek beamforming IP. Long-term viability favors vendors with dual capability across captive semiconductor sourcing and cloud-native distributed unit architectures. Acquisition target archetype: millimeter-wave RF engineering boutiques with massive MIMO patent portfolios. Watch FCC equipment authorization timeline compression as inflection signal for vendor market entry velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Supply Chain Captivity | Long-term offtake agreements with Japanese epitaxial wafer foundries secure input cost predictability for Ericsson and Samsung. |
| Open RAN Software Certification | ETSI interoperability validation enables multi-vendor procurement models at Deutsche Telekom and Verizon. |
| Private 5G Direct Sales Buildout | Direct enterprise channels bypass carrier intermediaries at German chemical complexes and Australian mining operations. |
| India Manufacturing Localization | PLI-compliant assembly footprints qualify Reliance Jio and Bharti Airtel procurement specifications. |
| Millimeter-Wave Backhaul Deployment | 28 GHz fixed wireless links displace fiber trenching in suburban United States connectivity builds. |
Research Methodology
Direct dialogue with RF engineering directors, carrier procurement executives, semiconductor foundry planners, and Open RAN software architects grounded qualitative assessment. Secondary validation drew from FCC equipment authorization databases, 3GPP specification releases, ETSI framework documents, and TRAI spectrum allocation records. Bottom-up triangulation across vendor shipment disclosures and top-down reconciliation against operator capex guidance shaped market sizing.
Model outputs span unit shipments and value projections across the analysis window, with segmentation by technology generation, component form factor, deployment ownership model, and end-user industry. CAGRs derive from regression against spectrum auction timelines and infrastructure replacement cycles. Industry-specific forecast inputs include GaN substrate supply elasticity and Open RAN interoperability certification velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FCC authorization timeline shifts and municipal permitting moratoria in dense European and North American cities. Projections reflect documented assumptions around spectrum allocation schedules and vendor supply chain localization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Competitive Local Exchange Carriers (CLEC) Market
Telecommunications
Mexico MNVO Market
Telecommunications
GPON Market
Telecommunications
Telecom Expense Management Market
Telecommunications
5G System Integration Market
Telecommunications
Argentina ICT Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
LTE Emergency Networks Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
Fixed LTE Market
Telecommunications
Fixed Voice Market
Telecommunications
Russia ICT Market
Telecommunications
Indonesia B2B Telecom Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Portable Base Station (PBS) Market