
 Private LTE Market | 2026-2036
Private LTE Market Size, Share, and Industry Trends Forecast 2026-2036
Private LTE Market Intelligence
A shift from carrier-managed single-source contracts toward multi-vendor in-house network operations is rebalancing procurement patterns across industrial campuses. Nokia Corporation leverages its digital automation platform to anchor large manufacturing deployments in Europe. Samsung Electronics Co., Ltd. competes through integrated baseband-to-radio portfolios that reduce interoperability friction for enterprise buyers. Ericsson specializes in spectrum-coordination software that sustains its position in shared-license markets.
Private LTE denotes a cellular network deployed for exclusive use by a single organization, operating on licensed, shared, or unlicensed spectrum with base stations, evolved packet cores, and subscriber identity modules managed independently from public carriers. These networks deliver deterministic latency below 50 milliseconds and support up to thousands of devices per square kilometer, serving mission-critical industrial automation, remote equipment control, and secure broadband backhaul. Deployment models show managed services capturing early enterprise adopters lacking radio-frequency engineering capacity, while hybrid architectures are gaining traction as manufacturers retain core network control while outsourcing radio planning. Among end users, mining and transportation represent the fastest-expanding demand pools due to their need for continuous coverage across geographically dispersed assets.
The Federal Communications Commission's Citizens Broadband Radio Service framework in the United States, Germany's Bundesnetzagentur local licensing for 3.7–3.8 GHz, and 3GPP security specifications collectively shape equipment certification requirements and spectrum access rules. Enterprises must navigate fragmented national licensing regimes that determine whether private LTE builds proceed on leased, shared, or fully owned spectrum. Stakeholders should monitor evolving national mid-band allocations and 3GPP Release 18 enhancements for reduced capability devices to anticipate where deployment economics shift decisively toward private infrastructure.
Market Dynamics
3GPP Release 16 time-sensitive networking specifications are compressing deployment timelines for industrial automation buyers, forcing equipment vendors to certify products against deterministic latency benchmarks before site trials commence.
Growth Catalysts
- Mining automation in Australia:Autonomous haulage fleets require continuous pit-to-port coverage that public networks cannot guarantee, driving direct spectrum acquisitions.
- Germany's BNetzA local licensing:The 3.7–3.8 GHz framework removes carrier intermediaries for automotive and chemical campus networks in the Ruhr industrial cluster.
- Time-sensitive networking:3GPP Release 16 deterministic latency below 50 milliseconds enables remote equipment control applications previously tethered to wired infrastructure.
Market Restraints
- RF engineering talent scarcity:Enterprises lack in-house radio-frequency planning capacity, forcing reliance on managed service premiums or hiring delays.
- Fragmented national licensing:Each jurisdiction imposes distinct certification requirements, equipment approval timelines, and spectrum access rules without mutual recognition.
- Public 5G slicing substitution:Carrier-managed network slicing offers lower upfront capex for latency-tolerant applications, narrowing private LTE's addressable base.
Strategic Opportunities
- Reduced capability devices:3GPP Release 18 specifications will lower modem costs and power draw, expanding sensor-density economics for predictive maintenance networks.
- Chilean copper mining expansion:Geographically dispersed extraction sites with no fiber backhaul present greenfield deployment opportunities for satellite-integrated private LTE.
- Multi-vendor in-house operations:Enterprises retaining core network control while outsourcing radio planning capture lifecycle cost advantages over fully managed contracts.
Industry Challenges
- EPC core integration complexity:Merging evolved packet cores with existing SCADA and MES systems requires protocol translation layers that extend commissioning schedules.
- Spectrum coordination disputes:Shared-license deployments face interference arbitration with incumbent users, particularly in 3.5 GHz CBRS General Authorized Access tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private LTE Market |
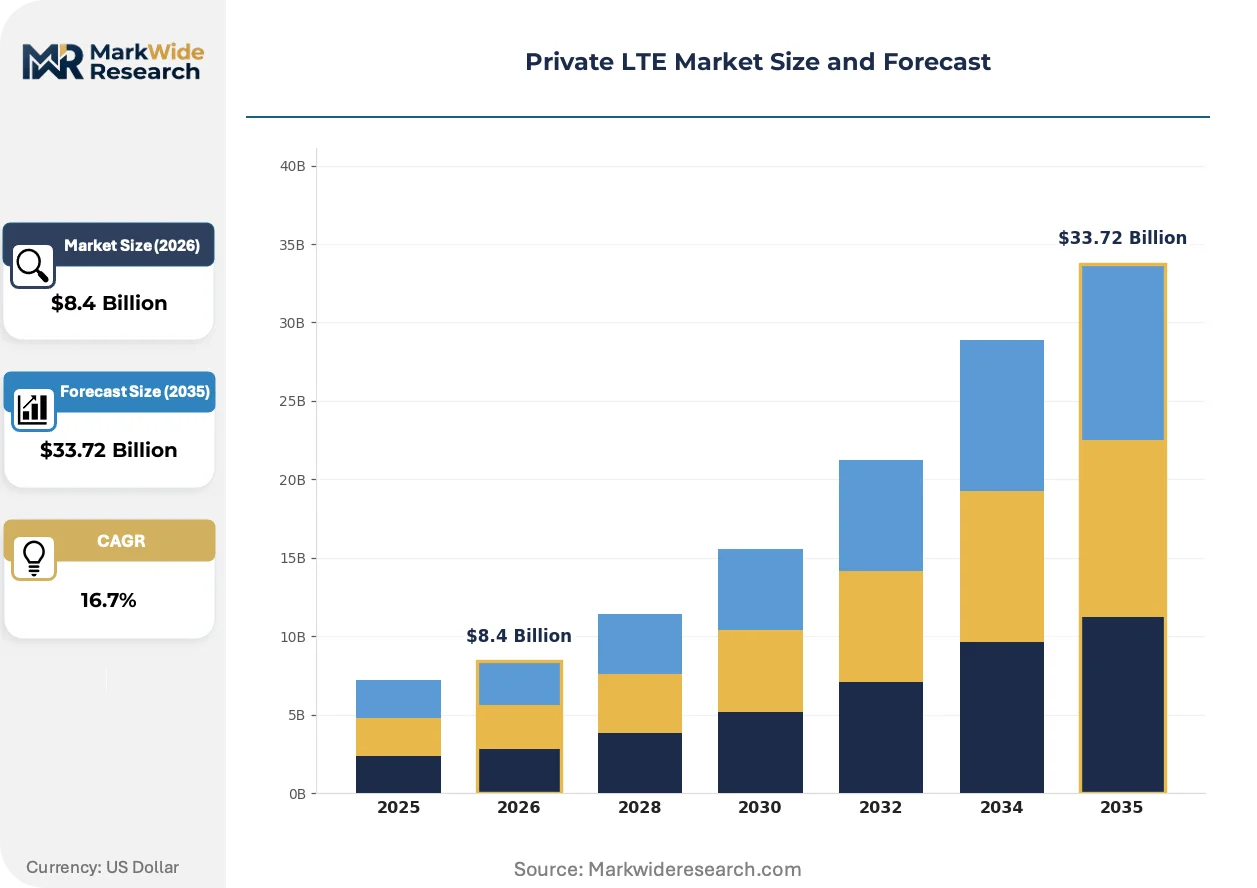
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 4G, LTE Advanced, LTE-M, NB-IoT Deployment Model: On-Premises, Cloud, Hybrid, Managed Services End User: Manufacturing, Transportation, Healthcare, Mining Use Case: Private Network, Mobile Broadband, IoT Connectivity, Emergency Services |
| Companies Covered | Samsung Electronics Co., Ltd., ZTE Corporation, Nokia Corporation, Verizon, NEC Corporation, Ericsson, Cisco Systems, Inc., CommScope Holding Company, Inc., Huawei Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private LTE Market Strategic Shifts & Innovations
Industrial buyers are compressing vendor selection cycles as deterministic latency becomes a non-negotiable specification, forcing equipment suppliers to pre-integrate radio and core components before proof-of-concept deployments.
Open RAN architectures are automating multi-vendor radio access network interoperability, allowing mining operators in Australia to mix baseband units from separate suppliers without proprietary lock-in. Early adopters in Chilean copper extraction report 40% faster commissioning timelines when radio and core elements decouple. This modularization is compressing incumbent suppliers' maintenance revenue streams as enterprises swap components rather than refresh entire systems.
The FCC's Citizens Broadband Radio Service framework is mandating spectrum access system coordination for 3.5 GHz deployments, creating a three-tier priority structure that reserves channels for incumbents while auctioning unused capacity to enterprises. Industrial users in US manufacturing corridors must now budget for SAS subscription fees and environmental sensing capability hardware. Automotive campuses in Michigan and chemical processors along the Gulf Coast are responding by clustering applications into priority access license blocks to guarantee interference-free channels.
Enterprise buyers are consolidating vendor relationships around integrated baseband-to-radio portfolios that reduce interoperability testing burdens, displacing the multi-source procurement patterns common in early private LTE deployments. Mining operators now favor single-supplier accountability for latency performance across geographically dispersed assets. This concentration is most visible in Australian iron ore and Chilean copper belts, where pit-to-port coverage mandates create penalty clauses for vendor finger-pointing during outages.
Private LTE Market Segmentation
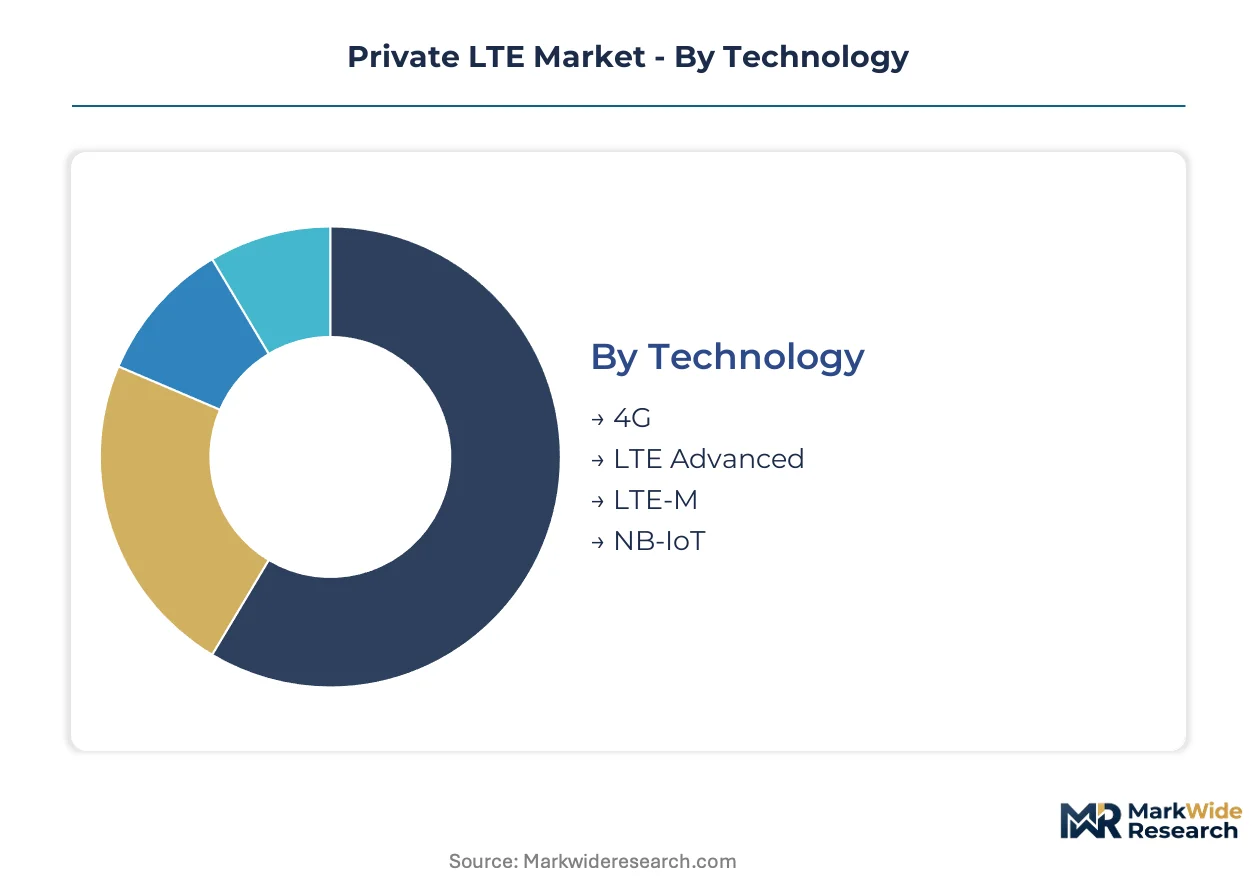
Private LTE deployments fragment across technology generations, operational models, and industrial applications. Each segmentation axis governs capital intensity, latency specifications, and vendor selection criteria for enterprise buyers.
Technology:
Radio access technology determines spectral efficiency, device ecosystem breadth, and migration pathways toward 5G.
- LTE Advanced:Carrier aggregation and enhanced MIMO configurations deliver peak throughput above 300 Mbps for high-definition video backhaul and autonomous vehicle telemetry. Australian iron ore operators specify LTE Advanced for pit-to-port haulage corridors where signal handoff reliability outweighs 5G upgrade premiums.
- 4G:Mature baseband silicon and established handset ecosystems minimize procurement risk for latency-tolerant campus networks. German chemical manufacturers in the Ruhr cluster deploy 4G for personnel push-to-talk and environmental sensor backhaul where deterministic timing remains non-critical.
- LTE-M:Narrowband specification optimized for battery-constrained asset trackers and predictive maintenance sensors across dispersed mining equipment.
- NB-IoT:Ultra-narrowband physical layer penetrates underground mine shafts and dense industrial structures where standard LTE signals attenuate.
LTE Advanced leads on scale; LTE-M gains share fastest among greenfield industrial sensor networks.
Deployment Model:
Operational architecture choices balance control retention against radio-frequency engineering competency gaps.
- Managed Services:Third-party operators assume full responsibility for spectrum licensing, radio planning, and core network maintenance under multi-year service contracts. Chilean copper miners favor this model for geographically dispersed extraction sites lacking local telecom engineering talent.
- Hybrid:Enterprises retain evolved packet core ownership while outsourcing radio access network design and installation. US manufacturing campuses along the Gulf Coast adopt hybrid structures to satisfy internal security policies without building RF planning teams.
- On-Premises:Complete in-house operation of base stations, packet cores, and subscriber management delivers maximum data sovereignty for defense and critical infrastructure operators.
- Cloud:Virtualized core functions hosted in edge computing facilities reduce physical infrastructure footprint for mid-size industrial campuses.
Managed Services dominates current contract value; Hybrid architectures expand most quickly as manufacturers seek core control without RF talent acquisition.
End User:
Industrial verticals impose distinct coverage footprints, device density requirements, and integration complexity with operational technology systems.
- Mining:Autonomous haulage fleets and pit-to-port logistics demand continuous coverage across hundreds of square kilometers of terrain with no fiber backhaul. Australian and Chilean operators drive direct spectrum acquisitions to guarantee availability.
- Manufacturing:Campus-bound deployments prioritize deterministic latency below 50 milliseconds for robotic arm coordination and automated guided vehicle fleet management. Automotive OEMs in Germany specify private LTE to isolate production data from public carrier infrastructure.
- Transportation:Port terminals and rail yards require high-mobility handoff performance for crane operators and yard vehicle dispatch systems.
- Healthcare:Hospital campuses leverage private LTE for secure patient monitoring backhaul and emergency responder coordination within facility boundaries.
Mining leads on geographic deployment scale; Manufacturing climbs fastest as 3GPP Release 16 time-sensitive networking enables wireless replacement of wired industrial controls.
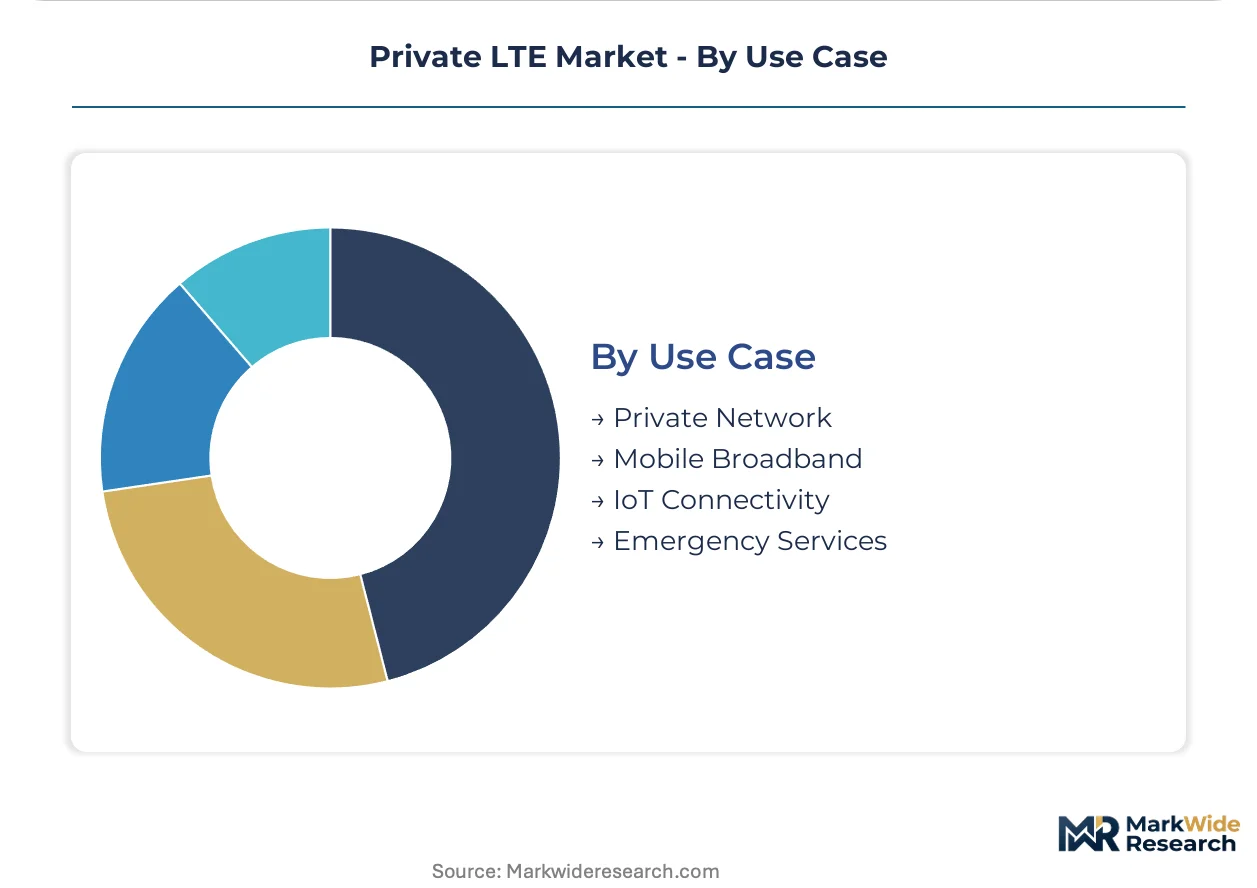
Use Case:
Application purpose governs quality-of-service profiles, security architectures, and device certification requirements.
- IoT Connectivity:Massive machine-type communication for sensor grids and asset tracking dominates device volume. Predictive maintenance networks in Chilean copper extraction deploy thousands of vibration and temperature sensors per site.
- Private Network:Organization-exclusive voice and data services replace legacy TETRA and Wi-Fi systems for mission-critical personnel communications. German chemical processors mandate private network isolation for hazardous area operations.
- Mobile Broadband:High-throughput backhaul for video surveillance, remote expert assistance, and temporary workforce connectivity supplements fixed infrastructure.
- Emergency Services:First-responder priority access and group communications meet public safety availability requirements during carrier network congestion.
IoT Connectivity leads on connected device volume; Private Network exhibits steepest expansion trajectory as regulatory frameworks in Germany and the United States simplify spectrum access for enterprise-exclusive builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial cluster anchors deployment momentum for private LTE infrastructure, with automotive and chemical manufacturers driving spectrum acquisitions across three continents. National licensing frameworks determine whether enterprises build on leased, shared, or fully owned frequencies.
United States
Autonomous haulage fleets in Arizona copper mines and Gulf Coast petrochemical corridors demand continuous coverage that public networks cannot guarantee. The FCC's Citizens Broadband Radio Service framework mandates spectrum access system coordination for 3.5 GHz deployments, creating three-tier priority structures. Michigan automotive campuses cluster applications into priority access license blocks to secure interference-free channels for robotic coordination.
Germany
Automotive OEMs and chemical processors in North Rhine-Westphalia specify private LTE to isolate production data from public carrier infrastructure. BundesnetzA's local licensing for 3.7–3.8 GHz removes carrier intermediaries for campus network builds. The Ruhr industrial cluster exhibits the densest concentration of manufacturing deployments, with deterministic latency specifications below 50 milliseconds for automated guided vehicle fleet management.
Australia
Iron ore operators in Western Australia's Pilbara region deploy pit-to-port coverage across hundreds of square kilometers of terrain lacking fiber backhaul. Direct spectrum acquisitions guarantee availability for autonomous haulage corridors where signal handoff reliability outweighs upgrade premiums. Mining operators favor single-supplier accountability with penalty clauses for vendor finger-pointing during outages across geographically dispersed assets.
Chile
Copper extraction sites in the Atacama Desert present greenfield deployment opportunities for satellite-integrated private LTE where no fiber infrastructure exists. Geographically dispersed extraction sites drive managed service adoption among operators lacking local telecom engineering talent. Predictive maintenance networks deploy thousands of vibration and temperature sensors per site, with LTE-M specifications optimized for battery-constrained asset trackers.
China
Manufacturing campuses in the Yangtze River Delta and Pearl River Delta pursue hybrid architectures to satisfy internal security policies without building radio-frequency planning teams. MIIT spectrum allocations for industrial internet applications shape equipment certification requirements for campus-bound deployments. Shandong Peninsula chemical processors mandate private network isolation for hazardous area operations, replacing legacy TETRA systems.
Private LTE Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cloud-native core virtualization and Open RAN interoperability. The vendor base concentrates around integrated baseband-to-radio portfolios that reduce interoperability testing burdens for enterprise buyers. Three archetypes dominate: telecommunications equipment conglomerates with spectrum-coordination software, digital automation platform specialists, and satellite-integrated connectivity providers. Competitive intensity centers on multi-vendor accountability structures and managed service packaging for buyers lacking radio-frequency engineering capacity.
Within the integrated portfolio tier, Nokia Corporation and Samsung Electronics Co., Ltd. anchor large manufacturing deployments through pre-integrated radio and core components. Ericsson occupies a position in shared-license markets through spectrum-coordination software specialization. ZTE Corporation represents the telecommunications equipment conglomerate archetype with geographic strength in Asia-Pacific industrial corridors. These three exemplify how single-supplier accountability compresses commissioning timelines for latency-sensitive applications.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| ZTE Corporation |
| Nokia Corporation |
| Verizon |
| NEC Corporation |
| Ericsson |
| Cisco Systems, Inc. |
| CommScope Holding Company, Inc. |
| Huawei Technologies Co., Ltd. |
| Others |
Cost & Logistics Intelligence
3GPP Release 16 certification requirements gate qualified supply access and premium-tier pricing for sub-50 millisecond latency equipment, compressing vendor margins on uncertified alternatives while rewarding pre-integrated radio-core portfolios with pricing power.
Pricing Analysis
Input-cost pass-through from baseband silicon and radio frequency component shortages flows into equipment pricing, with LTE Advanced base stations commanding premium positioning against 4G alternatives due to carrier aggregation complexity. Price differentiation centers on deterministic latency certification tier and spectrum coordination software bundling. Cost compression in the 4G tier is intensifying because mature silicon economics erode hardware margins. Mining operators in Australia exhibit lowest price sensitivity due to outage penalty clauses, while mid-size manufacturing campuses in Germany face acute budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining operator demand in Australia and Chile, while systems integrators serve manufacturing campuses lacking radio-frequency engineering capacity. Supply concentrates in Finland, South Korea, and Sweden for baseband processing units and radio access network equipment. Raw material dependencies span gallium nitride for power amplifiers, high-purity silicon for chip fabrication, and rare earth elements for RF filtering components. Single-source vulnerability in evolved packet core software licensing creates procurement risk. Distribution runs through carrier-captive channels, direct enterprise sales teams, and industrial systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private LTE functions as a stable compounder anchored by industrial automation mandates that mandate wireless replacement of wired controls across mining and manufacturing verticals.
For Market Incumbents: Acquire spectrum-coordination software assets to defend against Open RAN interoperability threats that erode proprietary lock-in. Capture radio-frequency engineering talent pools in Germany and Australia to preempt managed service pricing pressure. Deepen backward integration into baseband silicon design to secure supply continuity.
For New Entrants and Emerging Players: Launch via satellite-integrated managed service models targeting Chilean copper extraction sites lacking fiber backhaul infrastructure. Target the LTE-M sensor connectivity segment where reduced capability device economics from 3GPP Release 18 specifications lower capital barriers. Pursue white-label core virtualization partnerships with industrial systems integrators serving mid-size manufacturing campuses.
For Investors and Strategic Acquirers: Roll-up economics work for regional managed service providers because fragmented RF engineering talent pools resist national scaling. Five-to-ten year viability rests on spectrum license duration and 3GPP standard migration pathways. Target acquisition archetypes combine hybrid deployment expertise with existing carrier relationships. Monitor BundesnetzA and FCC licensing queue depth as inflection indicator for capacity-constrained equipment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | Reduces vendor lock-in for Australian mining operators mixing baseband suppliers. |
| Spectrum Coordination Software Acquisition | Secures positioning in FCC CBRS three-tier priority access license markets. |
| Managed Service Geographic Expansion | Captures Chilean copper extraction demand lacking local telecom engineering talent. |
| LTE-M Device Portfolio Development | Addresses predictive maintenance sensor density requirements in dispersed mining equipment. |
| Hybrid Deployment Architecture Launch | Satisfies German automotive OEM security policies without RF team buildout. |
Research Approach
Direct dialogue with radio access network procurement managers, industrial automation engineers, spectrum licensing officials, and managed service operations directors grounds qualitative findings. Secondary validation draws from 3GPP specification documents, FCC equipment authorization databases, BundesnetzA licensing registers, and SEC filings from telecommunications equipment suppliers. Bottom-up and top-down triangulation cross-checks deployment volume estimates against spectrum allocation records and vendor shipment disclosures.
Bottom-up modeling builds from country-level licensing activity, deployment model mix assumptions, and technology generation splits, while top-down approaches benchmark against industrial capital expenditure surveys and mining automation investment disclosures. Segmentation dimensions span radio access technology, deployment model architecture, end-user vertical, and use case application. CAGRs derive from logistic diffusion curves fitted to early adopter deployment timelines and standard-release-driven upgrade cycles. Key inputs include 3GPP Release 16 certification timelines and national mid-band allocation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under spectrum reallocation delays or accelerated public 5G slicing substitution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Optical Networking Market
Network Technology
Global Internet Transit Market
Network Technology
Global Deep Packet Inspection and Processing Market
Network Technology
Network Devices Market
Network Technology
Hyperconnectivity Market
Network Technology
Network Telemetry Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market
Network Technology
Wi-Fi Extender Market
Network Technology
Converged Cable Access Platform (CCAP) Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Global Active Network Management Market
Network Technology
Managed Switches Market
Network Technology
Gigabit Ethernet Market
Network Technology
WAN Optimization Controllers Market