
 Middle East and Africa Telecom Market | 2026-2036
Middle East and Africa Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Telecom Market Foresight
The EU Green Deal's extraterritorial carbon disclosure requirements is hardening sustainability benchmarks for telecom infrastructure procurement across North African export corridors. MTN Group anchors its competitive position through extensive tower-sharing partnerships that reduce energy intensity across twelve markets. Etisalat Group dominates fiber-to-the-home deployment in Gulf Cooperation Council states with vertically integrated cable manufacturing. Zain Group differentiates through mobile money platforms that sustain subscriber stickiness in East African markets with limited banking penetration.
Telecom encompasses the transmission of voice, data, and video across wired and wireless infrastructure operating on licensed spectrum bands from 700 MHz to 28 GHz, employing packet-switching core networks and radio access technologies to enable real-time connectivity for commercial and consumer applications. Internet Services command the largest revenue pool as enterprise cloud migration and streaming consumption expand bandwidth requirements across both regions. 5G represents the fastest-expanding technology segment as Gulf regulators auction millimeter-wave spectrum and South African operators deploy standalone core networks for industrial automation clients. Value-added Services concentrate margin accretion through API monetization, cybersecurity bundles, and IoT platform subscriptions tailored to utility and logistics verticals.
TRAI-equivalent spectrum authorities in Nigeria and South Africa enforce local content rules and infrastructure-sharing mandates that lower barriers for second-tier operators. Saudi Arabia's Communications and Information Technology Commission imposes coverage obligations and data localization standards that shape capital allocation for cloud-based deployments. Stakeholders must monitor regulatory divergence between Gulf states accelerating open-access wholesale frameworks and Sub-Saharan markets grappling with right-of-way disputes and electromagnetic field exposure limits that delay base station permitting.
Market Dynamics
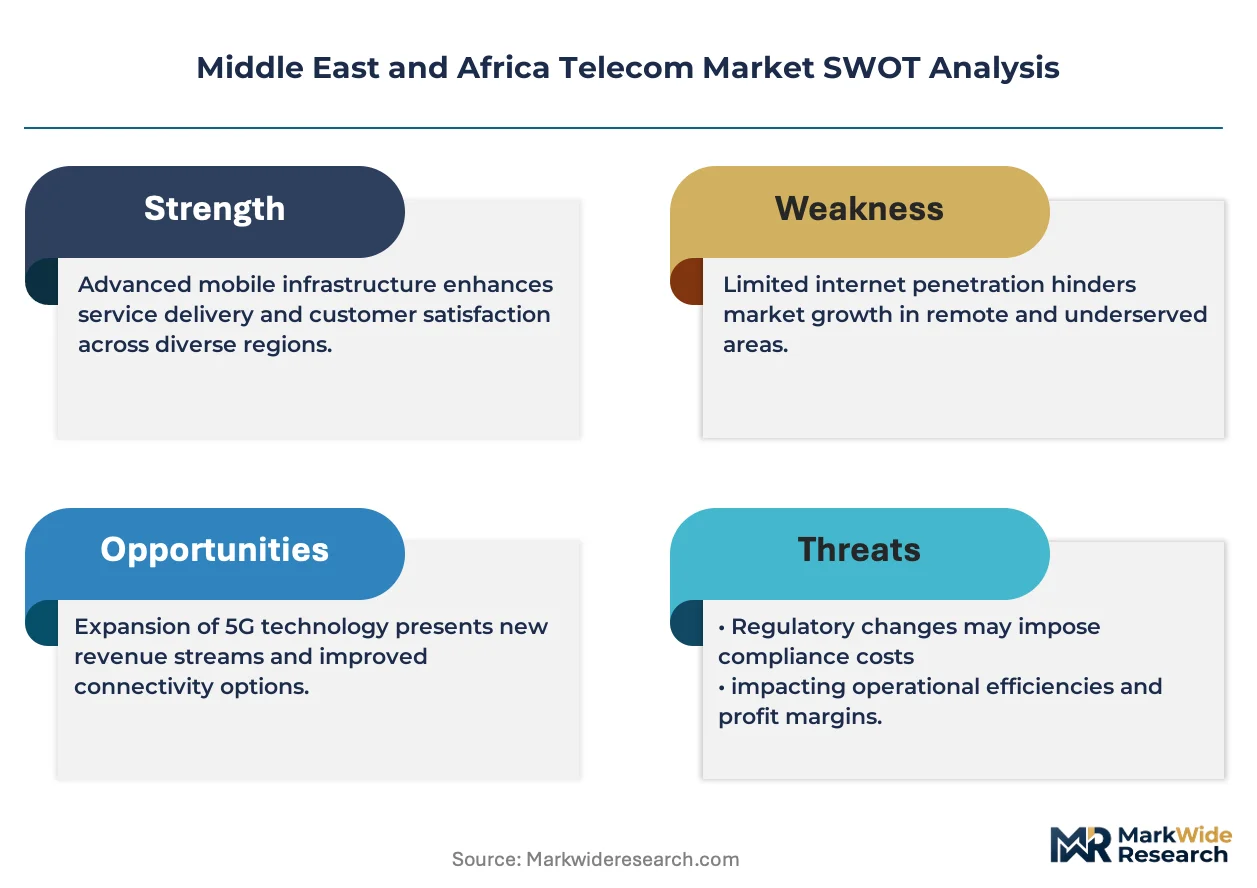
Spectrum liberalization across Gulf Cooperation Council states is compressing deployment timelines for millimeter-wave infrastructure while Sub-Saharan regulators auction sub-1 GHz bands to extend rural coverage. This dual-track regulatory momentum is restructuring capital allocation between high-capacity urban networks and low-cost universal service obligations.
Growth Catalysts
- EU Green Deal extraterritorial carbon disclosure:North African export corridors face hardening sustainability benchmarks for telecom infrastructure procurement, forcing suppliers to certify embodied emissions in fiber cables and base station equipment.
- Mobile financial services adoption:Unbanked populations across Sub-Saharan Africa are leapfrogging traditional banking through USSD and smartphone-based payment platforms that generate data revenue and reduce subscriber churn.
- Standalone 5G core networks:South African industrial automation clients demand network slicing capabilities for mining and logistics applications, pulling capital toward edge computing infrastructure.
Market Restraints
- Right-of-way disputes:Sub-Saharan electromagnetic field exposure limits and municipal permitting delays extend base station deployment cycles by 8-14 months in dense urban centers.
- Input cost volatility:Fiber-optic cable production depends on purified silicon and rare-earth dopants subject to Chinese export quota fluctuations and shipping rate spikes through the Red Sea corridor.
- Technical limitation:Millimeter-wave propagation characteristics require 3-4x denser small cell grids than sub-6 GHz alternatives, multiplying energy and real estate costs in Gulf urban environments.
Strategic Opportunities
- API monetization platforms:Value-added Services bundles incorporating cybersecurity and IoT subscriptions for utility and logistics verticals capture margin accretion beyond connectivity commoditization.
- Tower-sharing partnerships:Infrastructure-sharing mandates from Nigeria's NCC and South Africa's ICASA lower barriers for second-tier operators while reducing energy intensity across twelve markets.
- Open-access wholesale frameworks:Saudi Arabia's CITC and UAE's TDRA are mandating fiber unbundling that creates neutral host opportunities for data center and cloud interconnection providers.
Industry Challenges
- Legacy billing system integration:Converged charging platforms for 5G network slicing must interoperate with decade-old IN and OCS architectures, extending transformation timelines.
- Skill scarcity in radio frequency engineering:Millimeter-wave propagation modeling and massive MIMO antenna calibration require specialized expertise concentrated in European and East Asian labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Telecom Market |
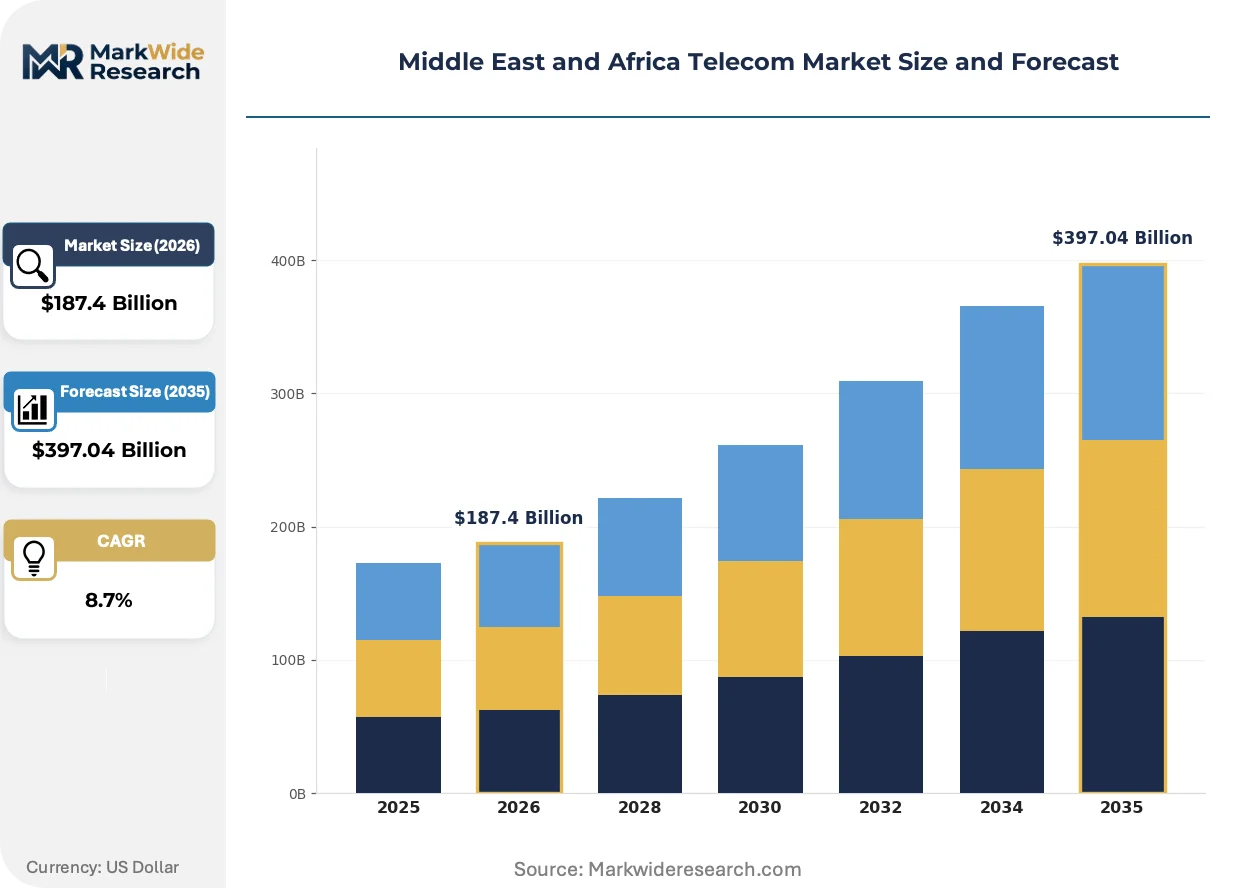
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-line Services, Internet Services, Value-added Services Technology: 4G LTE, 5G, Wi-Fi, Satellite End User: Residential, SME, Large Enterprises, Government Deployment: On-premises, Cloud-based, Hybrid, Managed |
| Companies Covered | MTN Group, Vodacom Group, Saudi Telecom Company (STC) Group, Telecom Egypt, Orange S.A., Etisalat Group, Zain Group, VEON LTD, Ooredoo Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Telecom Market Shifts & Advancements
Open RAN architectures are disaggregating vendor lock-in across Middle Eastern operator procurement cycles. This structural shift is compressing equipment margins while redistributing value toward systems integrators and cloud-native software stacks.
Network function virtualization is converging with containerized core deployments to enable dynamic scaling for enterprise private networks. Mining conglomerates in South Africa and petrochemical operators in Saudi Arabia are adopting these architectures within eighteen-month procurement windows. This technology convergence is compressing traditional hardware refresh cycles and forcing incumbent vendors to restructure pricing models around software subscriptions.
Saudi Arabia's CITC data localization standards are mandating in-country cloud infrastructure for government and financial sector workloads. These regulations are redirecting hyperscaler capital toward Riyadh and Jeddah data center clusters while disqualifying offshore-only service providers from public sector tenders. Enterprise cloud migration timelines are extending by 6-9 months as operators construct compliant facilities.
Streaming consumption and enterprise cloud migration are expanding bandwidth requirements beyond traditional tiered service plans. Nigerian and Kenyan operators are unbundling content delivery network access from core connectivity, creating usage-based revenue streams that displace flat-rate pricing. This behavioral shift concentrates in urban corridors where fiber-to-the-home penetration exceeds 40 percent.
Middle East and Africa Telecom Market Segmentation
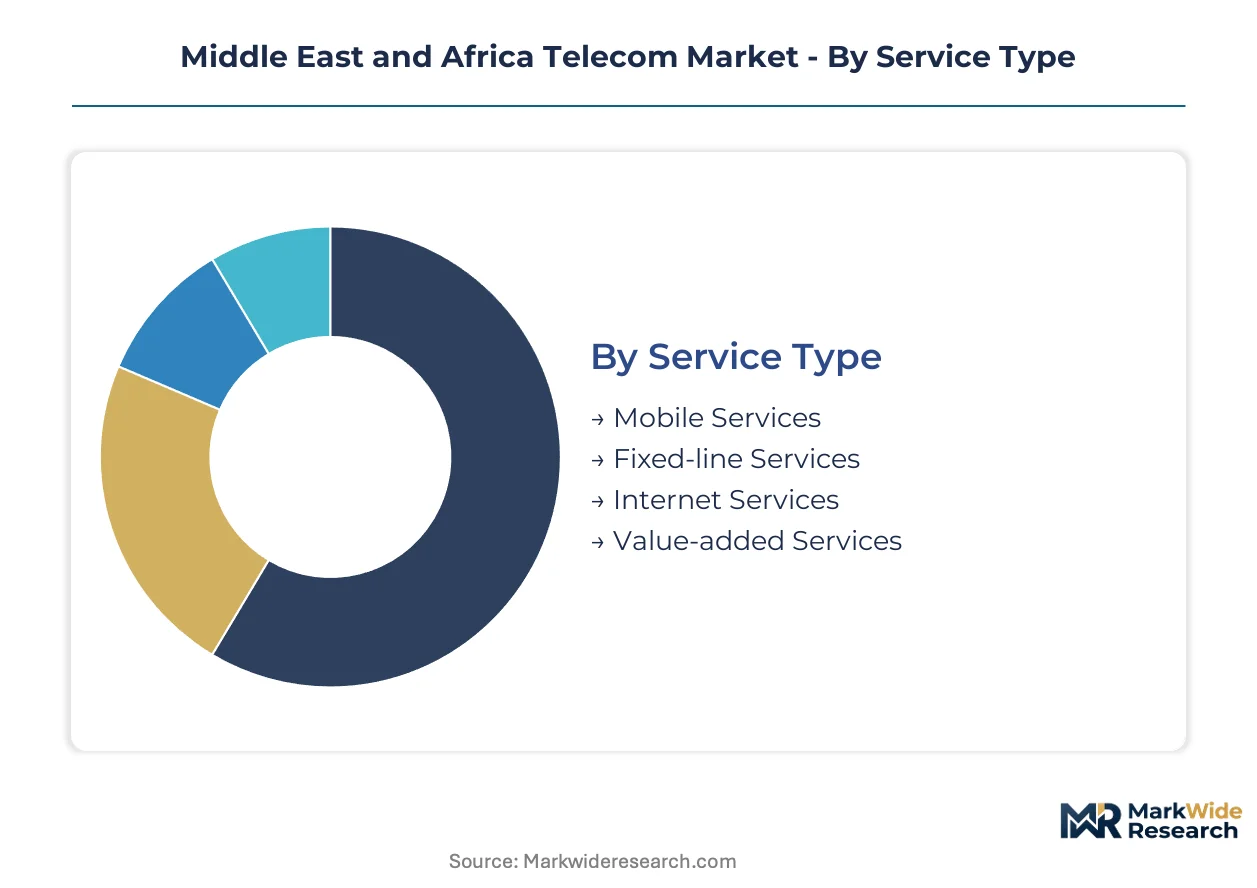
Telecom segmentation in the Middle East and Africa reveals divergent investment priorities between Gulf states pursuing premium infrastructure and Sub-Saharan markets optimizing for coverage economics. Understanding these splits enables targeted capital allocation across service tiers, technology generations, and customer archetypes.
Service Type:
Volume concentration sits with mass-market connectivity, while premium capture concentrates in bundled digital services and enterprise solutions.
- Internet Services:Enterprise cloud migration and streaming consumption across Nigeria, Saudi Arabia, and South Africa expand bandwidth requirements beyond traditional tiered plans. Nigerian and Kenyan operators unbundle content delivery network access from core connectivity, creating usage-based revenue streams.
- Value-added Services:API monetization, cybersecurity bundles, and IoT platform subscriptions tailored to utility and logistics verticals capture margin accretion beyond connectivity commoditization. These bundles sustain pricing power in competitive Gulf markets.
- Mobile Services:USSD and smartphone-based payment platforms generate data revenue and reduce subscriber churn among unbanked populations across Sub-Saharan Africa.
- Fixed-line Services:Fiber-to-the-home deployment concentrates in Gulf Cooperation Council states with vertically integrated cable manufacturing capabilities.
Mature deployment sits with Fixed-line Services. Newer deployment is concentrated in Value-added Services.
Technology:
Cost tier separation distinguishes high-capacity urban infrastructure from low-cost universal service obligations across regulatory jurisdictions.
- 5G:Millimeter-wave spectrum auctions by Gulf regulators and standalone core networks for South African industrial automation clients pull capital toward edge computing infrastructure. Network slicing capabilities serve mining and logistics applications.
- 4G LTE:Sub-1 GHz band auctions by Sub-Saharan regulators extend rural coverage at lower deployment cost per subscriber, anchoring universal service obligations.
- Wi-Fi:Neutral host opportunities emerge from Saudi Arabia's CITC and UAE's TDRA fiber unbundling mandates for data center interconnection.
- Satellite:Low-earth orbit constellations address right-of-way disputes and electromagnetic field exposure limits that delay base station permitting in dense Sub-Saharan urban centers.
Commercial maturity rests with 4G LTE. Steepest expansion trajectory belongs to 5G.
End User:
Customer type stratification separates mass residential consumption from enterprise-grade service level agreements and compliance requirements.
- Large Enterprises:Mining conglomerates in South Africa and petrochemical operators in Saudi Arabia adopt network function virtualization and containerized core deployments within compressed procurement windows.
- Government:Saudi Arabia's CITC data localization standards mandate in-country cloud infrastructure, redirecting hyperscaler capital toward Riyadh and Jeddah data center clusters.
- Residential:Streaming consumption expands bandwidth requirements in urban corridors where fiber-to-the-home penetration exceeds threshold levels.
- SME:Mobile money platforms sustain subscriber stickiness in East African markets with limited banking penetration.
Established revenue concentration sits with Residential. Emerging opportunity concentrates in Government.
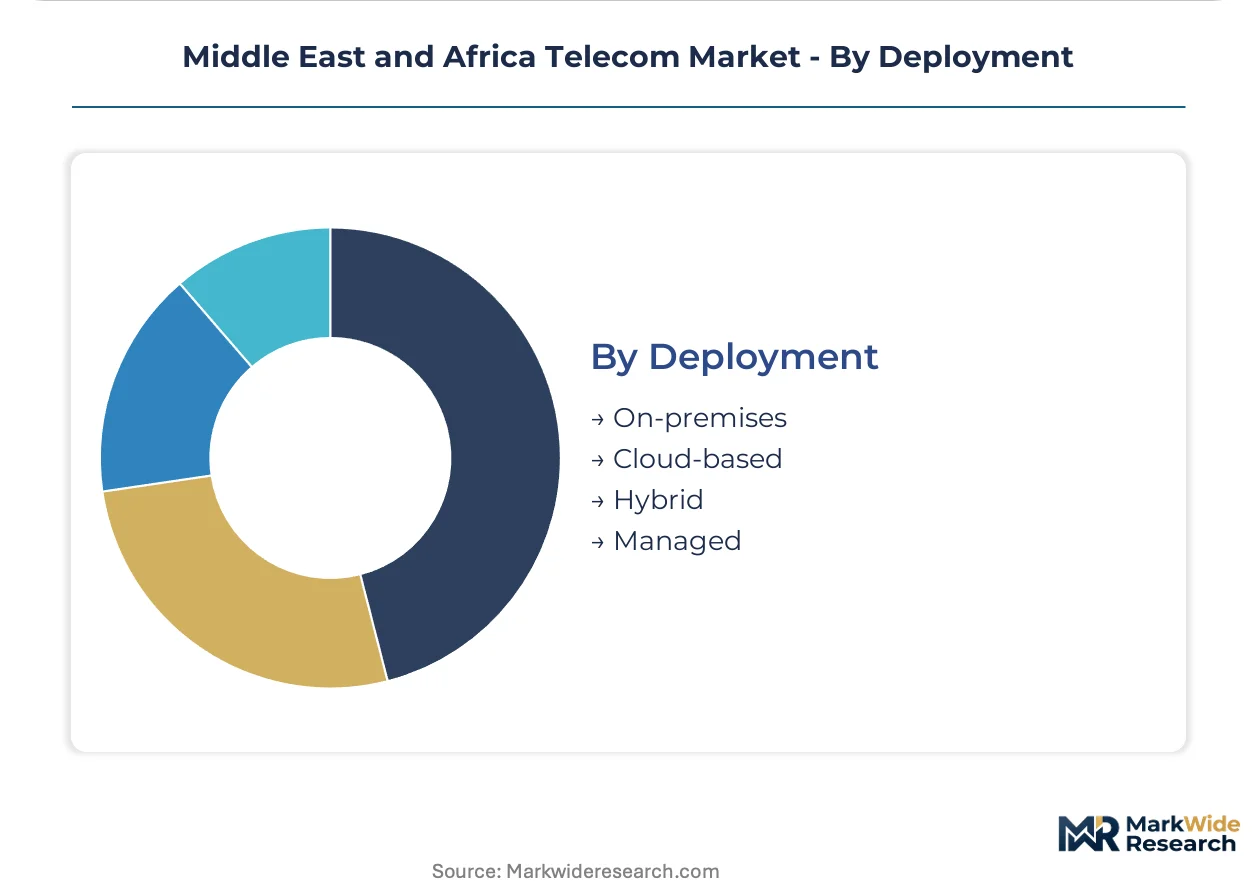
Deployment:
Supply concentration differentiates asset-heavy on-premises installations from scalable cloud-native architectures.
- Cloud-based:Dynamic scaling for enterprise private networks converges with containerized core deployments, compressing traditional hardware refresh cycles.
- Hybrid:Legacy billing system integration requirements for converged charging platforms extend transformation timelines as 5G network slicing must interoperate with decade-old architectures.
- On-premises:Government and financial sector workloads in Saudi Arabia require compliant facilities extending enterprise cloud migration timelines.
- Managed:Tower-sharing partnerships across twelve markets reduce energy intensity while lowering barriers for second-tier operators under infrastructure-sharing mandates.
Legacy install base sits with On-premises. Newer deployment concentrates in Cloud-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Cooperation Council states concentrate infrastructure investment while Sub-Saharan markets expand coverage economics. This production-consumption divide shapes divergent regulatory frameworks and capital allocation priorities across the analysis window.
Saudi Arabia
Standalone 5G core networks for industrial automation pull capital toward edge computing clusters in Riyadh and Jeddah. The Communications and Information Technology Commission imposes data localization standards that mandate in-country cloud infrastructure for government workloads. NEOM's northwest corridor anchors smart city deployments requiring network slicing capabilities for logistics and energy verticals.
South Africa
Mining conglomerates demand containerized core deployments for private networks within compressed procurement cycles. The Independent Communications Authority of South Africa enforces infrastructure-sharing mandates that lower barriers for second-tier operators. Johannesburg-Pretoria corridor concentrates fiber-to-the-home penetration exceeding threshold levels where streaming consumption expands bandwidth requirements.
Nigeria
Mobile financial services adoption among unbanked populations generates data revenue through USSD and smartphone-based payment platforms. The Nigerian Communications Commission applies local content rules and tower-sharing mandates that reduce deployment costs. Lagos-Ibadan corridor anchors content delivery network unbundling as operators create usage-based revenue streams displacing flat-rate pricing.
United Arab Emirates
Millimeter-wave spectrum auctions accelerate high-capacity urban network deployment across Dubai and Abu Dhabi. The Telecommunications and Digital Government Regulatory Authority mandates fiber unbundling that creates neutral host opportunities for data center interconnection. Vertically integrated cable manufacturing capabilities support Etisalat's fiber-to-the-home dominance in premium residential segments.
Egypt
Enterprise cloud migration extends timelines as operators construct compliant facilities for government and financial sector workloads. Telecom Egypt anchors fixed-line infrastructure through submarine cable landing stations connecting Mediterranean and Red Sea corridors. Cairo-Alexandria corridor concentrates international bandwidth exchange serving transit routes between Europe and Asia-Pacific markets.
Middle East and Africa Telecom Market Competitive Landscape
The competitive structure tilts toward diversified regional champions with multi-market footprints. Gulf-based operators leverage vertically integrated supply chains while Pan-African groups exploit tower-sharing economies across fragmented regulatory jurisdictions. Three archetypes dominate: spectrum-integrated infrastructure owners, mobile money platform operators, and wholesale-neutral host providers. Strategic moves center on fiber unbundling compliance and edge computing partnerships for enterprise private networks.
Among Pan-African mobile groups, MTN Group and Vodacom Group exemplify tower-sharing archetypes that reduce energy intensity across twelve markets under infrastructure-sharing mandates. Gulf-based Etisalat Group anchors vertically integrated positioning through captive cable manufacturing and fiber-to-the-home deployment dominance. Zain Group occupies the mobile money specialist tier where payment platforms sustain subscriber stickiness in East African markets with limited banking penetration.
| Leading Market Players |
|---|
| MTN Group |
| Vodacom Group |
| Saudi Telecom Company (STC) Group |
| Telecom Egypt |
| Orange S.A. |
| Etisalat Group |
| Zain Group |
| VEON LTD |
| Ooredoo Group |
| Others |
Supply & Pricing Matrix
Purified silicon and rare-earth dopant costs cascade through fiber-optic cable manufacturing into tiered connectivity pricing across Gulf and Sub-Saharan markets. Input volatility from Chinese export quotas compresses margins at the wholesale infrastructure layer while operators pass selective premiums to enterprise clients demanding guaranteed throughput.
Pricing Analysis
Throughput-based pricing anchors enterprise service level agreements where mining and petrochemical clients pay for guaranteed uptime and network slicing performance. Three-tier pricing structure across premium, standard, and economy levels separates fiber-to-the-home residential bundles from USSD-based mobile money access in unbanked segments. Pricing pressure stems from open-access wholesale frameworks mandated by Saudi Arabia's CITC and UAE's TDRA, which compress retail markups. SME segments in East Africa exhibit highest price sensitivity, while large enterprises in Gulf states accept premium positioning for compliance-guaranteed cloud infrastructure.
Supply Chain Analysis
Red Sea shipping rate spikes and Suez Canal congestion elevate logistics costs for base station equipment destined for North African and Gulf ports. Manufacturing concentration rests in China for fiber-optic components, South Korea for 5G radio units, and domestic Gulf facilities for vertically integrated cable production. Rare-earth dopants and purified silicon draw from constrained upstream refining capacity. Single-source vulnerability concentrates in millimeter-wave antenna calibration equipment sourced from European and East Asian specialists. Distribution runs through operator-led procurement consortiums and neutral host infrastructure partnerships across twelve markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Base station permitting delays averaging 8-14 months in dense Sub-Saharan urban centers constrain deployable capacity, propping pricing power for operators with existing tower portfolios. This supply bottleneck favors asset-heavy incumbents while raising entry barriers for capital-constrained challengers.
For Market Incumbents: Anchor market position through tower-sharing partnerships that amortize fixed costs across multiple tenants under Nigerian NCC and South African ICASA mandates. Deepen backward integration into captive cable manufacturing to offset rare-earth dopant price volatility. Defend against open RAN disaggregation by accelerating software subscription transitions before hardware refresh cycles expire. For New Entrants and Emerging Players: Enter via neutral host infrastructure provision in Saudi Arabia's fiber unbundling corridors and UAE data center interconnection zones. Target satellite-enabled rural coverage in Sub-Saharan markets where electromagnetic field exposure limits block traditional base station deployment. Pursue API monetization platforms for utility and logistics verticals as the most penetrable service layer beyond commoditized connectivity. For Investors and Strategic Acquirers: Standalone 5G core network deployments by South African mining conglomerates and Saudi petrochemical operators are the leading indicator that enterprise private network demand is reaching inflection velocity. Over the projection horizon, vertically integrated infrastructure owners with multi-market tower portfolios represent the most defensible acquisition archetype. Watch for millimeter-wave spectrum auction completion in secondary Gulf states as the signal that capital allocation toward edge computing infrastructure is accelerating.| Strategic Initiative | Industry Significance |
|---|---|
| Tower-Sharing Partnership Expansion | Reduces energy intensity across twelve markets under NCC and ICASA infrastructure-sharing mandates. |
| Open RAN Architecture Adoption | Disaggregates vendor lock-in while redistributing value toward cloud-native software integrators. |
| Mobile Money Platform Integration | Captures data revenue and reduces subscriber churn in East African markets with limited banking penetration. |
| Data Localization Facility Construction | Qualifies operators for Saudi CITC government and financial sector cloud workload tenders. |
| API Monetization Platform Launch | Enables cybersecurity and IoT subscription bundles for utility and logistics verticals beyond connectivity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with network engineering directors, tower infrastructure procurement leads, regulatory affairs managers at spectrum authorities, and mobile money platform operators combined with secondary validation from GSMA intelligence reports, TRAI-equivalent regulatory disclosures, and operator capex announcements. Bottom-up subscriber and traffic projections triangulated against top-down macroeconomic indicators across the analysis window.
Data-stream reconciliation integrated service type segmentation, technology generation splits, and end-user category stratification with deployment model differentiation across cloud-native and legacy on-premises architectures. CAGRs derived from regression analysis against spectrum auction timelines, infrastructure-sharing mandate implementation schedules, and enterprise cloud migration patterns. Edge computing investment flows and fiber unbundling regulatory compliance deadlines served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged Red Sea shipping disruptions or accelerated electromagnetic field exposure limit tightening in Sub-Saharan jurisdictions. Forecasts reflect documented assumptions about spectrum auction completion rates and right-of-way dispute resolution timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Telecom Service Assurance Market
Telecommunications
Telecom Expense Management Market
Telecommunications
Voip Phone Market
Telecommunications
Ireland Telecom Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Turkey Telecom Market
Telecommunications
5G Radio Access Network Market
Telecommunications
Sri Lanka Telecom Tower Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Luxembourg Telecom Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
Fixed Voice Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
Satcom Terminal Market
Telecommunications
Australia Telecom Market