
 Global Virtual PBX Market | 2026-2036
Global Virtual PBX Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual PBX Market Foresight
The split between premium unified-communications suites and commodity voice-only services is realigning competitive boundaries in virtual PBX provisioning. RingCentral leverages deep integration with CRM and workforce platforms to command higher per-seat pricing. Dialpad sustains differentiation through native AI transcription and real-time analytics. 8x8 anchors its position with global PSTN coverage across 40-plus countries, competing on regulatory reach rather than feature velocity.
Virtual PBX denotes a cloud-hosted private branch exchange that routes voice calls, voicemails, and conferencing sessions through internet protocol networks without customer-owned switching hardware, typically operating at 99.999% uptime SLAs with sub-150ms latency targets. Its primary commercial purpose is to replace capital-intensive PBX installations with scalable operational expenditure models. Cloud-based deployment leads absolute revenue contribution as enterprises abandon on-premise maintenance contracts. Contact centers represent the fastest-expanding end-user category, driven by workforce distribution and omnichannel routing requirements. Extension dialing and auto attendant services command the steadiest renewal rates among service types due to their embedded operational workflow status.
FCC STIR/SHAKEN mandates, GDPR data-localization rules in Europe, and Japan's METI cybersecurity guidelines for telecommunications infrastructure each reshape product architecture and geographic service availability. Compliance with these frameworks now functions as a market-access gate rather than a cost center. Stakeholders must monitor divergence between regional encryption standards and cross-border data routing permissions as determinants of platform architecture investment.
Market Dynamics
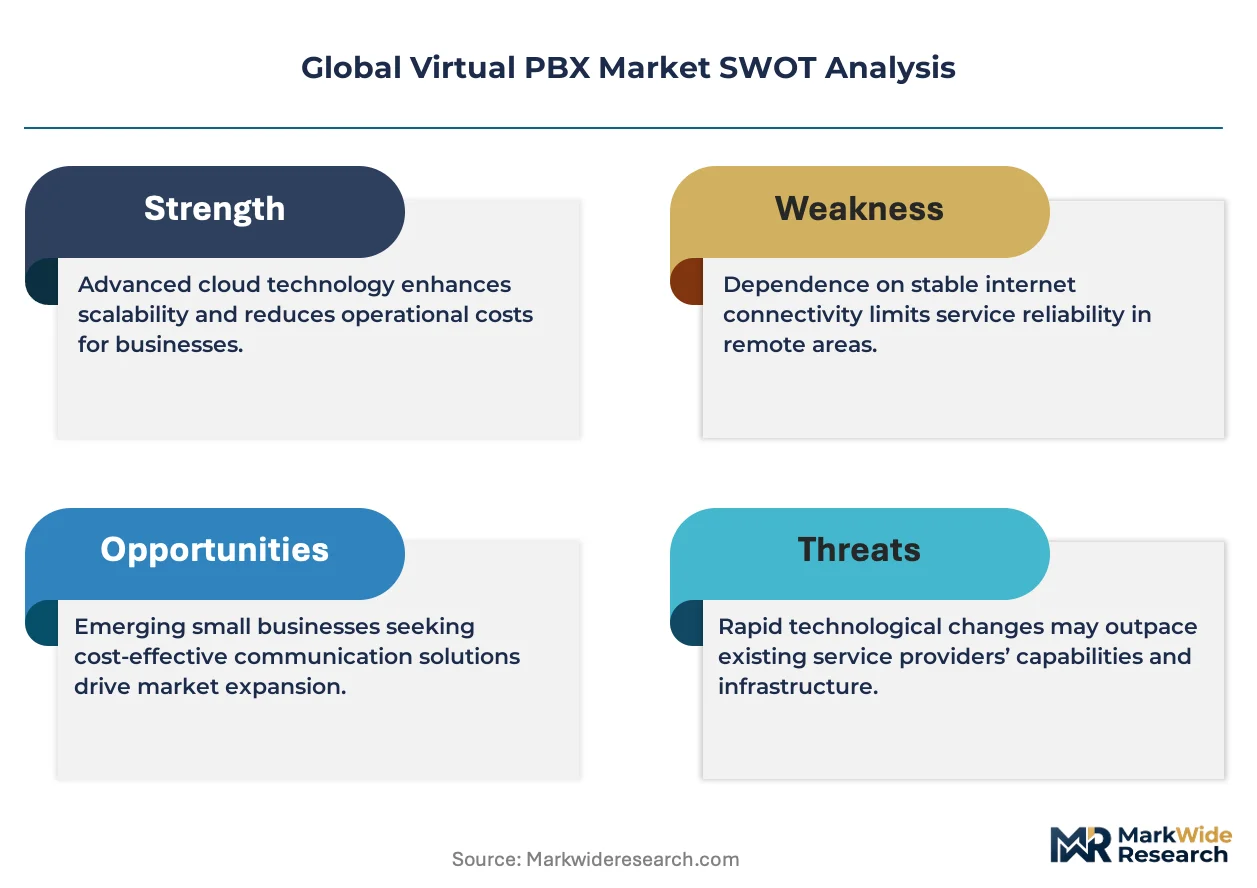
Cloud-native architectures are dismantling the installed base of on-premise PBX hardware, with FCC STIR/SHAKEN mandates now functioning as a compliance gate that filters out legacy VoIP providers lacking authentication infrastructure.
Growth Catalysts
- Healthcare Cloud Migration:Hospitals and telehealth operators in the United States are replacing circuit-switched systems with HIPAA-compliant cloud voice platforms to support distributed clinical workflows.
- FCC STIR/SHAKEN Framework:Mandated caller ID authentication is forcing enterprises to upgrade from basic VoIP trunks to certified virtual PBX stacks, accelerating replacement cycles.
- AI-Native Feature Bundling:Real-time transcription and sentiment analysis are pulling contact centers away from standalone voice-only services toward integrated communications suites.
Market Restraints
- Cross-Border Data Routing Friction:GDPR localization requirements in Germany and France block seamless failover to non-EU data centers, fragmenting platform architecture.
- PSTN Interconnection Concentration:Tier-1 carriers in Japan and the United States control last-mile termination rates, compressing margins for virtual PBX providers serving SMB segments.
- Legacy Equipment Stranding:Enterprises with sunk capital in on-premise Avaya and Cisco hardware face high switching costs that delay cloud migration timelines.
Strategic Opportunities
- India SMB Penetration:TRAI's cloud telephony liberalization is opening access to 63 million unconnected small businesses lacking any PBX infrastructure.
- Embedded Communications:Vertical SaaS platforms in property management and logistics are white-labeling virtual PBX APIs to replace standalone phone systems.
- METI Cybersecurity Certification:Japan's infrastructure security guidelines create preferential procurement status for compliant providers in government and financial verticals.
Industry Challenges
- VoIP Security Talent Scarcity:Shortages of engineers with STIR/SHAKEN implementation experience are delaying certification timelines for mid-tier service providers.
- Legacy PBX Integration Complexity:Hybrid deployments requiring SIP trunking between cloud platforms and aging TDM equipment generate 40% of implementation support tickets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual PBX Market |
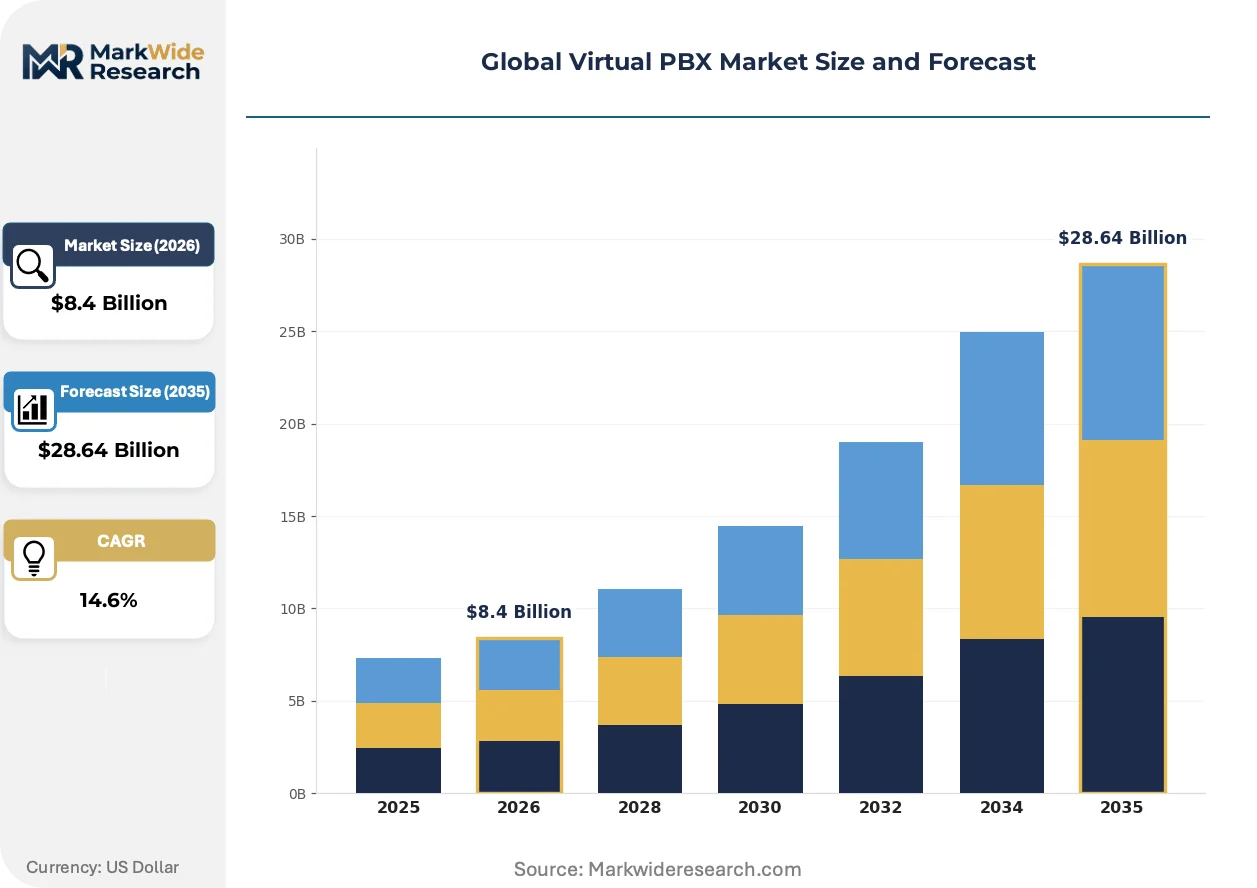
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Cloud-Based, On-Premise, Hybrid, Hosted End User: Small & Medium Enterprises, Large Corporations, Contact Centers, IT & Telecom Providers Service Type: Call Management, Extension Dialing, Auto Attendant, Call Recording, Voicemail Services, Conferencing Industry Vertical: BFSI, Healthcare Providers, Education Institutes, Hospitality Chains, E-Commerce Platforms |
| Companies Covered | Vonage, GoTo Connect, RingCentral, Dialpad, AVOXI, 8x8, Zoom Phone, Aircall, Nextiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual PBX Market Shifts & Advancements
Microservices-based voice stacks are fragmenting the monolithic PBX architecture, enabling enterprises to compose communications workflows from discrete API components rather than purchasing bundled suites.
Containerized voice infrastructure is modularizing how enterprises deploy call routing, allowing DevOps teams to spin up geographic instances without hardware procurement cycles. Financial services firms in Singapore and London are adopting this pattern to satisfy data residency requirements while maintaining single-pane management. The shift is compressing vendor lock-in by standardizing on Kubernetes-orchestrated workloads portable across cloud providers.
Germany's BSI IT-Grundschutz certification requirements for critical infrastructure are mandating encrypted signaling and media paths that exceed baseline GDPR obligations. Energy utilities and municipal governments now exclude uncertified platforms from RFP shortlists. Providers are responding by establishing German-exclusive data zones with sovereign encryption key management.
Enterprise buyers are unbundling professional services from subscription contracts, preferring to self-implement via vendor-provided configuration wizards and community documentation. This pattern is most pronounced among technology and professional services firms with in-house IT capabilities. The displacement of implementation revenue is forcing providers to monetize through usage-based API metering rather than upfront deployment fees.
Global Virtual PBX Market Segmentation
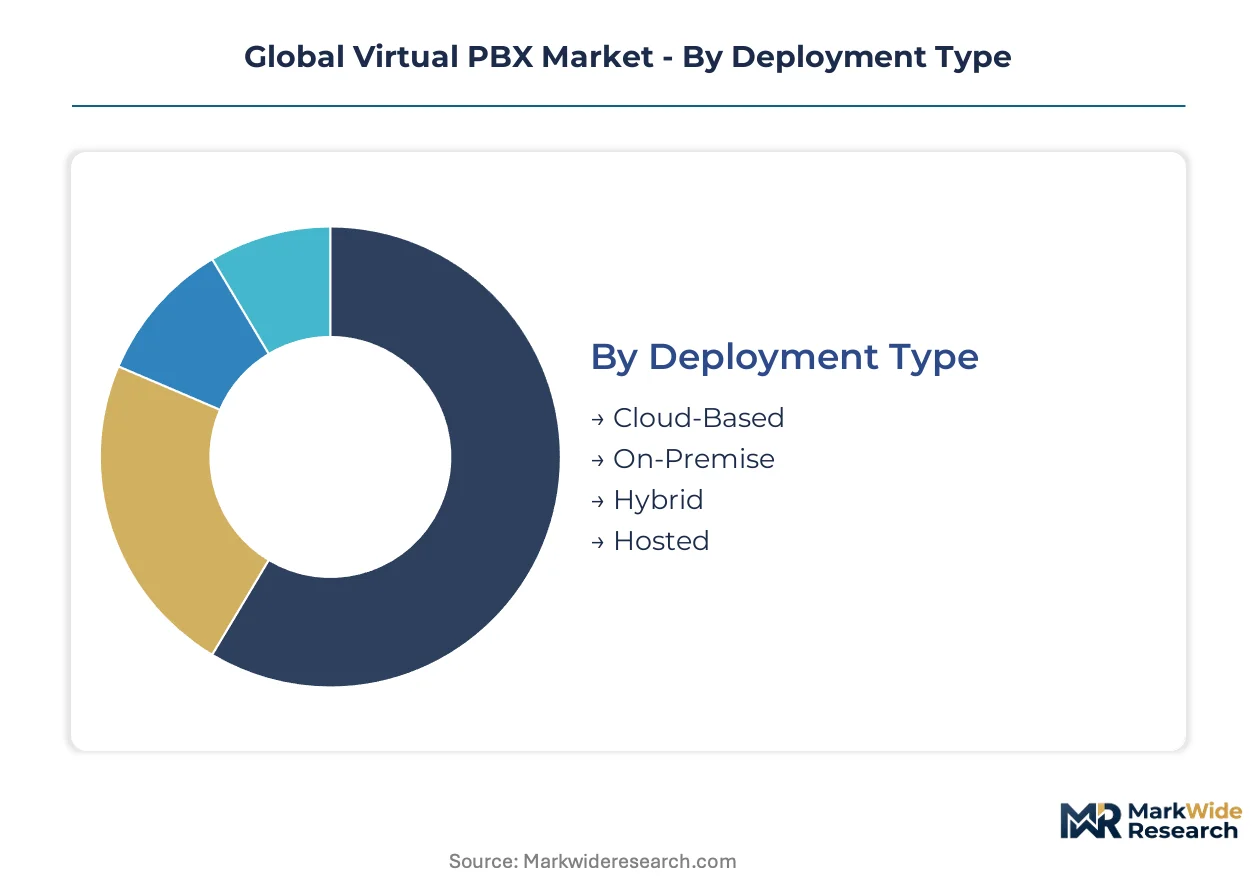
Virtual PBX segmentation reveals how infrastructure choices, buyer scale, and regulatory exposure fragment purchasing patterns across deployment modes and service bundles. Each axis carries distinct margin profiles and vendor specialization requirements.
Deployment Type:
Cloud-native architectures dominate procurement decisions as enterprises weigh data sovereignty against operational agility.
- Cloud-Based:Fully managed multi-tenant platforms eliminate hardware procurement cycles. Demand concentrates among United States healthcare providers replacing circuit-switched systems under HIPAA compliance pressure.
- On-Premise:Customer-managed switching hardware persists in German energy utilities and Japanese financial institutions subject to BSI IT-Grundschutz and METI cybersecurity mandates requiring sovereign key management.
- Hybrid:SIP trunking bridges legacy TDM equipment with cloud control planes. German municipal governments favor this pattern to phase out Avaya installations without workflow disruption.
- Hosted:Single-tenant dedicated instances serve France-based BFSI clients requiring CNIL-audited data localization without shared infrastructure risk.
Cloud-Based leads on scale; Hybrid leads on momentum.
End User:
Buyer sophistication determines feature bundling depth and pricing elasticity across seat volumes.
- Contact Centers:Omnichannel routing requirements pull these buyers toward AI-native transcription and real-time sentiment analytics. Expansion is steepest in India as TRAI liberalization opens 63 million SMB access points.
- Large Corporations:Global PSTN coverage and 99.999% SLA requirements dominate procurement criteria. Japan and United States headquarters drive standardization across regional branch offices.
- Small & Medium Enterprises:Self-service configuration and per-seat pricing without implementation fees attract technology firms with in-house IT capabilities.
- IT & Telecom Providers:White-label API consumption enables embedded communications in vertical SaaS platforms serving property management and logistics segments.
Contact Centers command premium pricing; Large Corporations anchor contract volumes.
Service Type:
Workflow embedding depth determines renewal rates and cross-sell potential across feature modules.
- Extension Dialing:Directory-based internal routing sits at the core of operational workflows. Steadiest renewal rates reflect embedded status in United States healthcare and German manufacturing environments.
- Auto Attendant:IVR-based call routing reduces live agent headcount. Demand concentrates in hospitality chains and e-commerce platforms managing high inbound call volumes.
- Call Management:Queue handling and overflow routing serve SMBs lacking dedicated IT staff for complex configuration.
- Call Recording:Compliance archiving for BFSI and healthcare verticals subject to SEC and HIPAA retention requirements.
- Voicemail Services:Visual voicemail and transcription add-ons generate incremental ARPU in mobile-first workforces.
- Conferencing:Video-enabled meeting rooms compete with standalone collaboration platforms for enterprise attention.
Extension Dialing leads on retention; Auto Attendant leads on attach rate expansion.
Industry Vertical:
Regulatory exposure and communication intensity shape vertical-specific packaging requirements.
- Healthcare Providers:HIPAA-compliant encryption and business associate agreements are non-negotiable. United States hospital systems are accelerating replacement of legacy Nortel and Cisco installations.
- BFSI:Call recording retention, STIR/SHAKEN authentication, and fraud detection integration dominate RFP criteria across Singapore and London financial centers.
- Education Institutes:Budget constraints favor hosted deployments with semester-based scaling for admissions and alumni outreach cycles.
- Hospitality Chains:Multi-property centralized management and guest services integration drive unified communications adoption.
- E-Commerce Platforms:Seasonal demand spikes require elastic capacity without year-round fixed costs.
Healthcare Providers lead on compliance-driven pricing; BFSI leads on feature integration depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers with STIR/SHAKEN implementation expertise cluster in San Francisco Bay Area and Seattle, anchoring North American platform development. Cloud voice architects concentrate in Berlin and Munich, powering European compliance engineering. Tokyo hosts the densest concentration of telecommunications cybersecurity specialists outside the United States.
United States
Healthcare providers in Texas and Florida are replacing legacy Nortel installations with HIPAA-compliant cloud voice platforms. FCC STIR/SHAKEN mandates are filtering out uncertified VoIP providers lacking authentication infrastructure. Hospital systems in Houston and Miami are accelerating procurement cycles to meet June compliance deadlines for caller ID verification.
Germany
Energy utilities in North Rhine-Westphalia are phasing out Avaya hardware under BSI IT-Grundschutz certification pressure. GDPR data-localization rules block seamless failover to non-EU data centers, fragmenting platform architecture. Municipal governments in Cologne and Düsseldorf favor hybrid SIP trunking deployments to maintain workflow continuity during cloud migration.
Japan
Financial institutions in Tokyo are standardizing on METI-certified platforms for government and banking procurement eligibility. METI cybersecurity guidelines for telecommunications infrastructure create preferential vendor status for compliant providers. Headquarters in Marunouchi and Nihonbashi are driving standardization across regional branch offices in Osaka and Nagoya.
India
Contact center operators in Bangalore and Hyderabad are scaling omnichannel routing capacity as TRAI liberalization opens 63 million SMB access points. TRAI's cloud telephony liberalization eliminates legacy licensing barriers for small business voice services. Technology parks in Whitefield and HITEC City are attracting white-label API providers serving embedded communications in vertical SaaS platforms.
United Kingdom
BFSI firms in London are integrating fraud detection with STIR/SHAKEN-authenticated call flows. FCA conduct rules and GDPR obligations shape procurement criteria for financial voice infrastructure. The City and Canary Wharf clusters are demanding 99.999% SLA guarantees with sub-150ms latency targets for trading floor communications.
Global Virtual PBX Market Competitive Landscape
Top-tier vendors anchor enterprise unified-communications suites, while mid-tier specialists compete on vertical-specific compliance certification. The vendor base stratifies across three functional tiers: full-stack platform providers, regional PSTN coverage specialists, and API-first embedded communications enablers. Dominant competitive moves include M&A to acquire STIR/SHAKEN engineering talent and strategic partnerships with tier-1 carriers to secure last-mile termination rates.
Within the premium unified-communications tier, RingCentral and Dialpad exemplify divergent differentiation strategies. RingCentral occupies a position anchored by deep CRM and workforce platform integration, commanding higher per-seat pricing through ecosystem embedding. Dialpad represents the AI-native archetype, leveraging real-time transcription and sentiment analytics to pull contact centers away from voice-only services. 8x8 sits within the global coverage specialist category, competing on regulatory reach across 40-plus countries rather than feature velocity.
| Leading Market Players |
|---|
| Vonage |
| GoTo Connect |
| RingCentral |
| Dialpad |
| AVOXI |
| 8x8 |
| Zoom Phone |
| Aircall |
| Nextiva |
| Others |
Supply & Pricing Matrix
Containerized voice infrastructure is compressing both deployment timelines and vendor concentration, allowing enterprises to bypass traditional hardware procurement cycles while fragmenting platform provider market power across Kubernetes-orchestrated workloads.
Pricing Analysis
Bundled unified-communications suites and unbundled API-first services now split the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and SLA guarantees. Price differentiation hinges on STIR/SHAKEN compliance status and geographic PSTN coverage breadth. Pricing pressure stems from tier-1 carrier termination rate compression in Japan and the United States. Small and medium enterprises exhibit highest price sensitivity, while large corporations prioritize regulatory reach over per-seat cost.
Supply Chain Analysis
Reverse logistics for legacy PBX decommissioning—equipment retrieval, refurbishment, and secure data destruction—now constitutes a material cost line in hybrid migration projects. Hardware manufacturing concentrates in Taiwan, South Korea, and China. Semiconductor components and optical transceivers anchor raw material dependencies. Single-source vulnerability around specialized VoIP security chipsets threatens certification timelines. Distribution runs through tier-1 carrier direct channels and white-label API aggregators serving vertical SaaS platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Virtual PBX Market represents a late-cycle quality story as enterprise buyers shift procurement criteria from voice connectivity toward AI-native transcription and real-time analytics bundles.
For Market Incumbents: Cement platform stickiness through deep CRM and workforce management integration, defending against API-first disaggregators. Prioritize STIR/SHAKEN engineering talent acquisition to maintain compliance gate status. Build German-exclusive data zones with sovereign encryption key management to satisfy BSI IT-Grundschutz procurement requirements. For New Entrants and Emerging Players: TRAI cloud telephony liberalization in India opens a window for contact center omnichannel routing plays among 63 million unconnected SMBs. Target embedded communications APIs for property management and logistics vertical SaaS platforms. Pursue METI cybersecurity certification in Japan to unlock government and financial vertical procurement eligibility. For Investors and Strategic Acquirers: Roll-up economics work for regional PSTN coverage specialists because cross-border data routing fragmentation prevents single-platform global dominance. Five-to-ten year viability favors providers with sovereign infrastructure in three-plus regulatory zones. Monitor divergence between regional encryption standards and cross-border data routing permissions as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| STIR/SHAKEN Infrastructure Investment | FCC mandates filter uncertified VoIP providers from enterprise procurement shortlists. |
| German Data Zone Establishment | BSI IT-Grundschutz certification unlocks energy utility and municipal government RFP access. |
| AI-Native Feature Bundling | Real-time transcription pulls contact centers from voice-only services toward integrated suites. |
| India SMB Channel Development | TRAI liberalization eliminates legacy licensing barriers for small business voice services. |
| METI Cybersecurity Certification | Japanese government and banking procurement eligibility requires compliant platform status. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation against FCC filings, SEC disclosures, hyperscaler capex reports, and telecommunications regulatory databases. Bottom-up deployment mode sizing and top-down market triangulation anchored value estimates.
Segment-weighting approaches modeled cloud-based, on-premise, hybrid, and hosted deployment types alongside end-user categories, service modules, and industry verticals across the projection horizon. CAGRs derived from installed base replacement velocity and net-new seat expansion patterns. Forecast inputs incorporated STIR/SHAKEN compliance adoption curves and cross-border data localization requirement proliferation.
Revisions become necessary when regulatory divergence accelerates, tier-1 carrier consolidation intensifies, or AI-native feature commoditization outpaces differentiation investment. Practitioners should monitor regional encryption standard fragmentation and sovereign cloud procurement mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Cambodia Telecom Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
Iran Telecom Market
Telecommunications
Transport Stream Switching Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
Denmark Telecom Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
IP PBX Market
Telecommunications
Germany Critical Communication Market
Telecommunications
Fixed LTE Market
Telecommunications
Indonesia Telecom Market
Telecommunications
Algeria Telecom Market
Telecommunications
Sri Lanka Telecom Market
Telecommunications
Global Broadband Services Market
Telecommunications
Smart SIM Market
Telecommunications
Global Esim Market