
 Telecom Services Market | 2026-2036
Telecom Services Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Services Market Intelligence
The capital-intensity divergence between legacy infrastructure holders and asset-light virtual network operators is reorganizing the market structure. Major carriers like Verizon and AT&T sustain massive investment in proprietary 5G and fiber optic networks to maintain a competitive edge in network performance and coverage. In contrast, Deutsche Telekom leverages its extensive European footprint and brand strength to offer bundled services across multiple countries, competing on both scale and integrated service portfolios.
Telecom services encompass the electronic transmission of information, including voice, data, and video, over wired or wireless networks. These services rely on protocols like TCP/IP and technologies that manage signal modulation and spectrum allocation to ensure reliable connectivity. While voice services are a mature revenue source, the data services segment, particularly for large enterprises, represents the primary growth vector. The deployment of 5G and fiber optic technologies is critical for delivering the high-bandwidth, low-latency connections these customers require.
Regulatory bodies like the FCC in the United States and China's MIIT heavily influence market access through spectrum auctions and infrastructure mandates. Concurrently, data privacy regulations such as the EU's GDPR impose strict compliance requirements on how providers handle customer information across geographies. Operator success now depends on navigating this complex web of national telecom policies and transnational data governance rules simultaneously to ensure market entry and compliance.
Market Dynamics
The structural divergence in capital intensity between legacy carriers and asset-light operators is reshaping competitive positioning. This is driven by enterprise demand for private 5G networks, forcing massive infrastructure investments to deliver guaranteed low-latency performance for industrial applications and creating a performance-based market bifurcation.
Growth Catalysts
- 5G Network Slicing:This technology enables operators to create customized virtual networks for specific enterprise uses, such as factory automation or remote surgery, unlocking new revenue streams beyond basic connectivity.
- Enterprise Demand:Large corporations are increasingly outsourcing network management through managed SD-WAN and private cellular network services to improve security, performance, and operational efficiency across their global operations.
- Subscriber Growth:Service providers are focusing on high-population markets like India and Indonesia to capture new mobile and broadband subscribers, offsetting saturation in developed economies.
Market Restraints
- Capital Intensity:The enormous cost of deploying and upgrading nationwide 5G and fiber optic networks creates a significant barrier to entry and pressures incumbent operator margins.
- Spectrum Scarcity:Limited availability and high auction prices for radio frequency spectrum, regulated by bodies like the FCC in the United States, constrain network expansion and increase operating costs.
- Legacy System Integration:The complexity of integrating new virtualized network functions with older, rigid infrastructure slows down service innovation and increases operational costs for established carriers.
Strategic Opportunities
- Edge Computing Services:Colocating compute and storage resources at the network edge allows providers to offer ultra-low-latency services required for autonomous vehicles, AR/VR, and real-time industrial analytics.
- Network APIs:Exposing network capabilities like location and quality of service through APIs enables third-party developers to build innovative applications, creating a new service ecosystem.
- Private Network Deployment:Demand from manufacturing, logistics, and energy sectors for dedicated, secure, and high-performance private 5G networks represents a significant greenfield opportunity.
Industry Challenges
- Regulatory Fragmentation:Operators must navigate a complex web of differing national data sovereignty laws and transnational privacy rules like GDPR, increasing compliance costs and operational complexity.
- Cybersecurity Threats:The shift to software-defined, open-architecture networks expands the attack surface, requiring continuous investment in advanced threat detection to protect critical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Services Market |
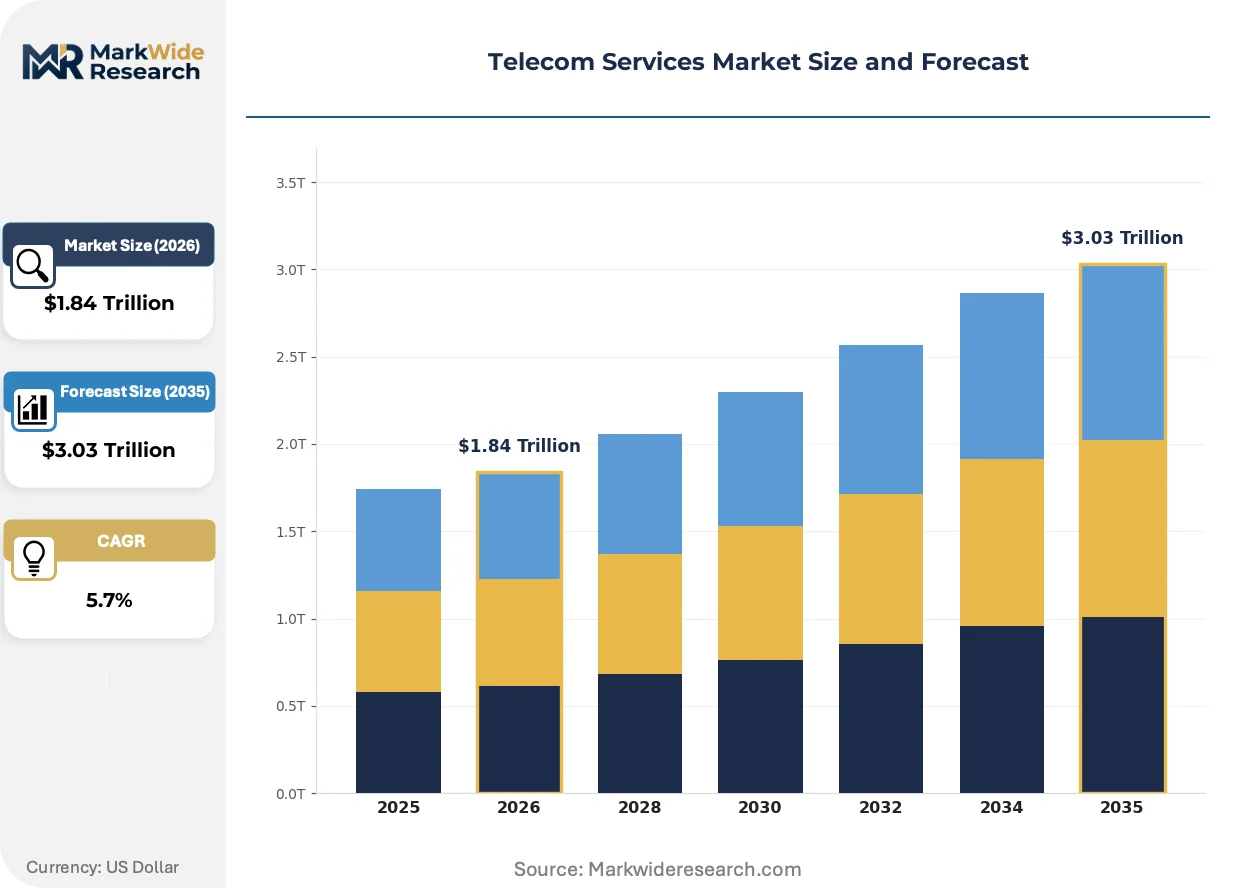
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $3.03 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice, Data, Messaging, Internet, Managed Services Customer Type: Individual Subscribers, Small Businesses, Large Enterprises, Government Agencies, Educational Institutions Technology: 5G, Fiber Optic, Satellite, DSL, VoIP Distribution Channel: Direct Sales, Online Platforms, Retail Stores, Resellers, Partner Networks |
| Companies Covered | China Mobile, Verizon, AT&T, T-Mobile US, Deutsche Telekom, Nippon Telegraph and Telephone, China Telecom, Vodafone, China Unicom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Services Market Strategic Shifts & Innovations
Service monetization is shifting from raw connectivity to specialized, software-defined capabilities. This transition is driven by the convergence of network virtualization technologies and enterprise demands for greater control over performance, security, and application-specific service levels.
Network Function Virtualization (NFV) decouples network functions like routing and firewalls from proprietary hardware. Large enterprises and cloud providers are rapidly adopting NFV to create more agile and cost-effective network infrastructures. This software-centric approach is displacing traditional, hardware-based network architectures, reducing vendor lock-in and accelerating service deployment cycles for operators.
China's Cybersecurity Law, enforced by the MIIT, imposes strict data localization and security review requirements on network operators. This regulation forces global telecom providers to re-architect data storage and processing infrastructure for their Chinese operations. The telecommunications equipment segment is most affected, facing heightened scrutiny and certification demands to access the market.
Enterprise customers are moving from fixed-capacity contracts toward flexible, consumption-based procurement for network services. This change disrupts traditional sales models, favoring providers offering on-demand bandwidth and self-service portals. The shift is most visible in the enterprise cloud access and SD-WAN markets across North America and Europe.
Telecom Services Market Segmentation
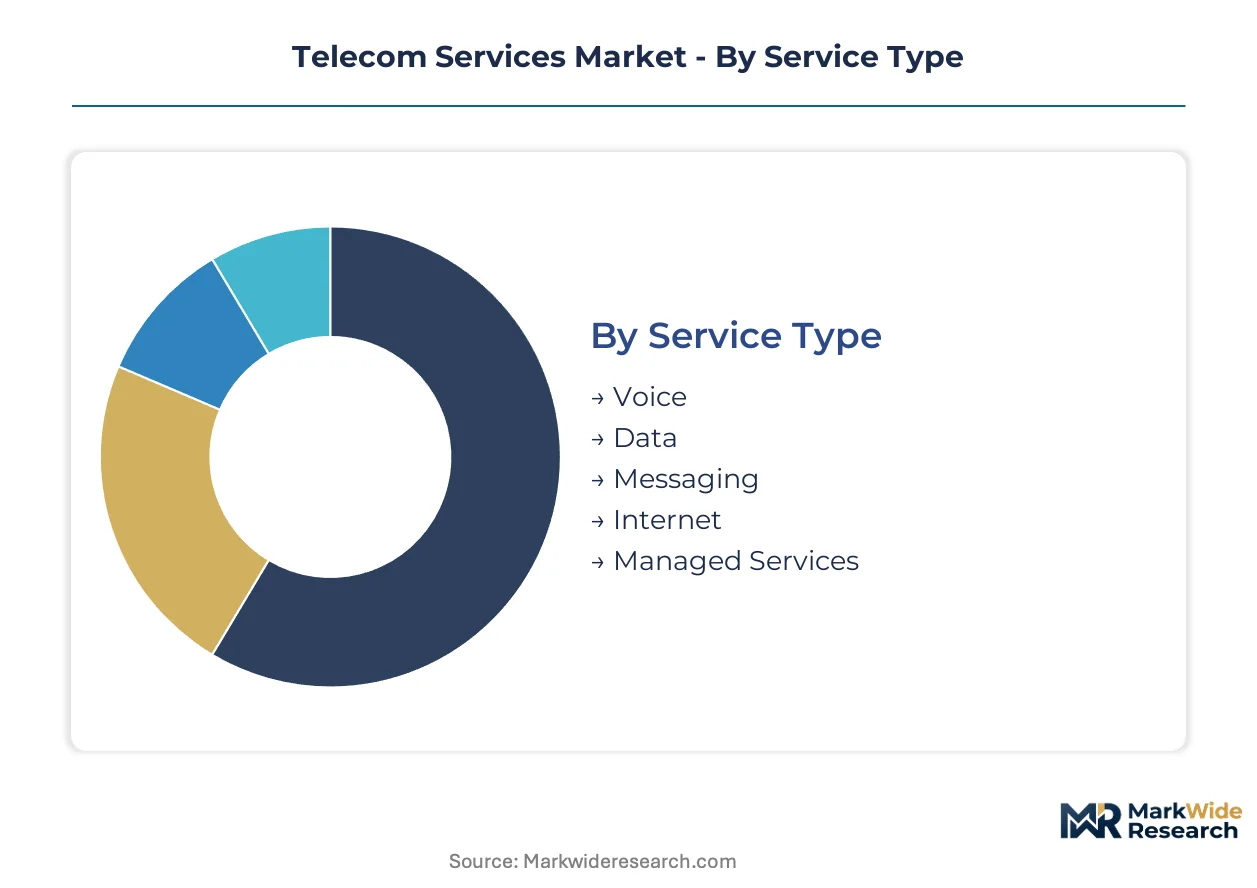
Understanding the Telecom Services Market through segmentation reveals how diverse offerings and customer needs drive distinct competitive dynamics. Each segment presents unique challenges and opportunities, influencing infrastructure investment and service development across different regions.
Service Type:
Substitution pressure is most acute for traditional communication services, as over-the-top applications increasingly offer alternatives to legacy voice and messaging. Service providers must innovate beyond basic connectivity to retain value.
- Data:This segment encompasses high-speed internet access, cloud connectivity, and content delivery, forming the primary growth vector for carriers. Demand for high-bandwidth, low-latency connections from large enterprises in Germany and Japan drives significant infrastructure upgrades.
- Managed Services:Providers offer outsourced network management, security, and cloud integration, allowing businesses to focus on core operations. Large corporations in the United States and India increasingly outsource SD-WAN and private cellular network management to improve operational efficiency.
- Voice:Traditional circuit-switched or VoIP calls constitute this mature service category.
- Messaging:SMS and MMS services remain relevant, especially in markets with lower smartphone penetration like parts of Indonesia.
- Internet:Basic internet access, distinct from specialized data services, serves residential and small business users.
Voice anchors the volume base while Managed Services gains share at the steepest rate.
Customer Type:
The market structure favors customer types capable of demanding specialized, high-value services, influencing how operators tailor their offerings. Individual subscribers seek affordability, while enterprises require performance and security.
- Large Enterprises:These customers demand dedicated connectivity, private networks, and robust security solutions for their global operations. Their need for guaranteed uptime and low latency drives significant investment in 5G and fiber optic infrastructure in countries like China and the United Kingdom.
- Individual Subscribers:This segment includes mobile and fixed-line residential users, primarily seeking affordable and reliable voice, data, and internet services. New subscriber growth concentrates in high-population density markets such as India and Vietnam.
- Small Businesses:This group requires scalable, cost-effective communication and internet solutions, often bundling services.
- Government Agencies:Public sector entities require secure, resilient communication networks for critical operations and public services.
- Educational Institutions:Schools and universities need high-capacity internet and specialized network solutions to support learning and research.
Large Enterprises command premium pricing, while Individual Subscribers represent the largest volume segment.
Technology:
Technology maturity dictates investment cycles and competitive advantage, with newer technologies like 5G and fiber optic requiring substantial capital. Legacy systems face pressure from more efficient, higher-performance alternatives.
- 5G:This generation of cellular technology delivers ultra-low latency, high bandwidth, and massive connectivity, critical for industrial automation and edge computing applications. Deployment efforts accelerate across urban centers in the United States and South Korea.
- Fiber Optic:Providing unparalleled speed and reliability, fiber optic networks form the backbone for high-capacity data transmission to homes and businesses. Extensive build-outs are underway in France and Australia.
- Satellite:This technology provides connectivity to remote or underserved areas where terrestrial infrastructure is impractical.
- DSL:Digital Subscriber Line offers internet access over traditional copper telephone lines, representing an older, widely available technology.
- VoIP:Voice over Internet Protocol enables voice communication over internet connections, often replacing traditional landlines.
5G and Fiber Optic technologies are driving network evolution, while DSL and VoIP maintain a foundational presence.
Distribution Channel:
Distribution channel efficiency directly impacts customer acquisition costs and market reach for telecom services. Digital platforms are gaining prominence due to their scalability and self-service capabilities.
- Online Platforms:Web portals and mobile apps enable self-service provisioning, customer support, and digital sales, reducing operational overhead. This channel is expanding rapidly across Europe and North America for service activation.
- Direct Sales:Dedicated sales teams engage directly with large enterprises and government clients to customize complex service solutions. This channel remains crucial for high-value contracts in Germany and the United States.
- Retail Stores:Physical outlets provide customer service, device sales, and in-person support, particularly for individual subscribers.
- Resellers:Third-party partners sell telecom services, often bundling them with other offerings to reach specific customer segments.
- Partner Networks:Collaborations with other technology or service providers expand market reach and offer integrated solutions.
Online Platforms offer the most efficient customer acquisition, while Direct Sales secures the highest-value contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The telecom services market exhibits a complex export-import balance, with certain nations driving significant infrastructure investment for domestic consumption while others focus on expanding subscriber bases through imported technology. This dynamic creates distinct regional competitive landscapes and regulatory environments for service providers.
United States
Enterprise demand for private 5G networks and high-bandwidth fiber connections drives substantial investment in the United States. The FCC actively manages spectrum auctions, influencing network expansion costs and competitive dynamics for major carriers. Technology hubs like Silicon Valley and major financial centers in New York demand advanced, low-latency connectivity for their innovation ecosystems.
China
China's massive subscriber base and rapid 5G deployment are primary market drivers for telecom services. The MIIT heavily regulates market access and infrastructure development, ensuring national strategic objectives are met. Major urban centers like Beijing and Shanghai are at the forefront of deploying advanced 5G applications and digital infrastructure.
India
Subscriber growth and the government's digital inclusion initiatives significantly boost the telecom sector in India. The TRAI oversees tariff policies and spectrum allocation, shaping the affordability and reach of services. High-population density regions like Uttar Pradesh and Maharashtra represent critical markets for new mobile and broadband connections.
Germany
Demand from large enterprises for secure managed services and robust data connectivity underpins the German telecom market. GDPR compliance requirements impose strict data handling standards on all service providers operating within the country. Industrial centers in Bavaria and North Rhine-Westphalia require high-performance networks for advanced manufacturing and IoT applications.
Indonesia
Indonesia's large, youthful population and increasing smartphone penetration fuel substantial subscriber growth across the archipelago. The government prioritizes digital infrastructure expansion to bridge the connectivity gap between islands and rural areas. Major cities like Jakarta and Surabaya are experiencing rapid growth in mobile data consumption and digital service adoption.
Telecom Services Market Key Industry Players
Concentration sits with large, integrated telecom operators that command extensive network infrastructure and significant market share across multiple service lines. These incumbent players compete through massive capital investments in next-generation technologies and strategic partnerships to expand service offerings. Dominant competitive moves include continuous infrastructure upgrades and aggressive market entry into emerging digital service categories.
At the scale-driven end, China Mobile, a state-owned entity, exemplifies a massive subscriber base operator leveraging national infrastructure for widespread connectivity. Verizon, a prominent North American carrier, represents an archetype focused on premium network performance and enterprise solutions, particularly in 5G and fiber optics. Deutsche Telekom, a European telecommunications giant, anchors the global market with its extensive international footprint and bundled service offerings across diverse geographies.
| Leading Market Players |
|---|
| China Mobile |
| Verizon |
| AT&T |
| T-Mobile US |
| Deutsche Telekom |
| Nippon Telegraph and Telephone |
| China Telecom |
| Vodafone |
| China Unicom |
| Others |
Cost & Logistics Intelligence
Massive infrastructure scale requirements for 5G and fiber optic networks shape supply concentration and influence price floors for connectivity. This capital-intensive environment favors large operators capable of significant investment.
Pricing Analysis
Large enterprise buyers anchor value-based pricing for specialized services, reflecting performance guarantees and customization. Subscription-based models dominate for basic connectivity, while consumption-based procurement gains traction for cloud access. Price differentiation stems from service level agreements and geographic coverage, particularly for low-latency applications in Germany. Pricing softness affects mature voice and messaging services due to over-the-top application substitution. Individual subscribers remain highly price-sensitive, seeking affordable data plans.
Supply Chain Analysis
China and South Korea anchor the supply of critical 5G network equipment, while the United States and Japan contribute significantly to fiber optic cable production. The supply chain depends on specialized semiconductors, optical fiber, and radio frequency components. Geopolitical tensions represent a structural risk, potentially disrupting access to key network infrastructure. Distribution runs through direct sales channels for large enterprise contracts and online platforms for individual subscribers across Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Navigating the complex regulatory landscape and integrating diverse network technologies presents a significant capability gap for many service providers.
For Market Incumbents:Consolidate legacy infrastructure through targeted fiber optic and 5G buildouts to maintain network performance leadership. Expand managed services offerings, particularly for private cellular networks, to capture enterprise demand and counter margin pressure from asset-light virtual operators. Invest in network slicing R&D to unlock new revenue streams beyond basic connectivity. Control key software-defined networking capabilities to reduce vendor lock-in.
For New Entrants and Emerging Players:Certification fast-tracks for specialized industrial IoT applications offer a clear entry point into the enterprise segment. Target underpenetrated rural areas in India and Indonesia with satellite-backhauled or fixed wireless access solutions. Offer API-driven network services to third-party developers, creating a new ecosystem for innovation. Focus on specific verticals like logistics or manufacturing that require dedicated, secure private networks.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors companies with strong intellectual property in network virtualization and edge computing for long-term viability. Seek acquisition targets specializing in cybersecurity solutions for software-defined networks or platform providers enabling network API monetization. A clear signal to watch is the successful commercial deployment of network slicing for specific industrial applications, indicating market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerate 5G Standalone Deployment | Enhances network slicing capabilities for critical enterprise applications, driving new revenue streams. |
| Expand Managed SD-WAN Services | Captures outsourcing demand from large enterprises seeking operational efficiency and security. |
| Develop Edge Computing Infrastructure | Enables ultra-low-latency services for emerging applications like autonomous vehicles and AR/VR. |
| Form Strategic API Partnerships | Fosters a developer ecosystem around network capabilities, extending service offerings. |
| Invest in Cybersecurity Solutions | Protects software-defined networks from evolving threats, ensuring critical infrastructure resilience. |
Research Approach
Operator-level perspectives from network architects, enterprise IT decision-makers, and regulatory affairs specialists anchored the qualitative base for this analysis. Insights were triangulated with extensive secondary research, including regulatory filings and industry association reports. Bottom-up and top-down approaches were employed to validate market sizing and growth projections.
Sensitivity analysis framed the forecast framework, modeling market dynamics across the analysis window. Segmentation dimensions included service type, customer type, technology, and regional market maturity. Compound annual growth rates were derived from historical trends and projected future demand, considering subscriber growth rates in emerging markets and 5G deployment timelines as key inputs.
Decision-makers should treat outputs as directional under current technological and regulatory assumptions; material deviation would warrant model refresh. Forecasts reflect a comprehensive understanding of market forces, but unforeseen changes in national telecom policies or major cybersecurity incidents could revise projections. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Video Door Phones Market
Telecommunications
US 5G Radio Access Network Professional Services Market
Telecommunications
Global 5G Base Station Market
Telecommunications
Turkey Telecom Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Diameter Signaling Market
Telecommunications
Switzerland Telecom Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
Angola Telecom Market
Telecommunications
Asia-Pacific IPTV Market
Telecommunications
IoT Telecom Services Market