
 Algeria Telecom Market | 2026-2036
Algeria Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Algeria Telecom Market Insights
Triple-play bundling of mobile, fixed broadband, and IPTV is repositioning consumer choice toward integrated household contracts. Algérie Télécom leverages its legacy copper infrastructure to anchor fixed-line dominance in secondary cities. Djezzy Algeria competes through aggressive mobile data pricing that extends its prepaid subscriber base. Ooredoo Algeria differentiates via enterprise-grade satellite connectivity for remote oil and gas operations.
Algeria telecom services encompass voice, data, and video transmission delivered over wireless and wireline infrastructures operating across frequency bands from 700 MHz to 3.5 GHz and fiber optic cables with single-mode cores rated for 10 Gbps and higher throughput. These networks enable commercial activity, public administration, and social communication across a territory where terrestrial deployment remains uneven. Mobile services generate the largest revenue pool given prepaid ubiquity and rising smartphone penetration, while fiber optic infrastructure represents the fastest-expanding technology segment as Algérie Télécom accelerates FTTH rollout in dense urban corridors. Satellite connectivity occupies a specialized niche serving enterprises and government agencies in Saharan zones beyond terrestrial reach.
ARPCE governs licensing, interconnection rates, and consumer protection frameworks, while the Agence Nationale Des Fréquences manages spectrum allocation that directly determines which operators can deploy 5G services and at what cost. Algeria's PLI-inspired domestic manufacturing incentives for network equipment are reshaping procurement patterns toward local assembly partnerships. Stakeholders must monitor ARPCE's pending mobile termination rate reforms and spectrum auction timelines to calibrate capital deployment against regulatory certainty.
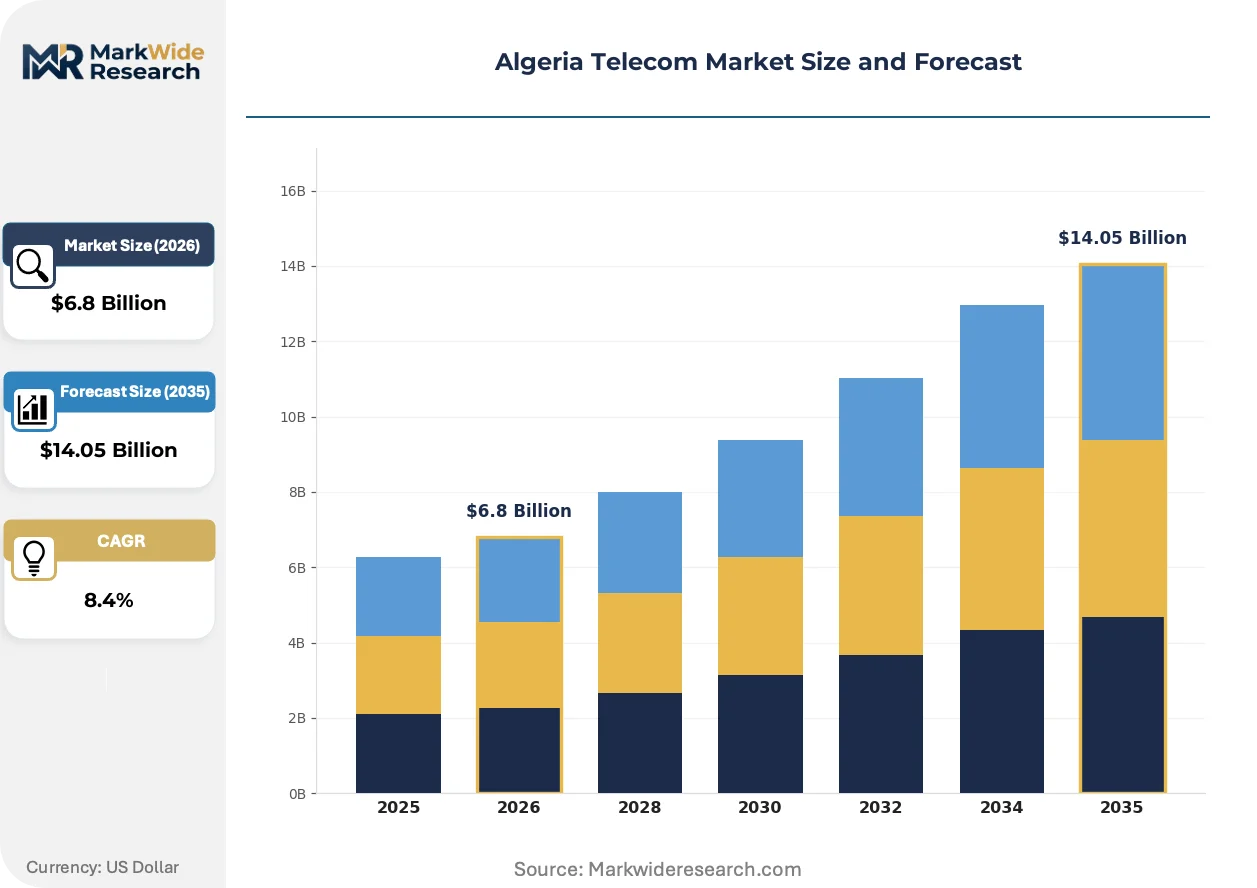
Market Dynamics
ARPCE's spectrum reallocation mandates are forcing operators to redirect capital toward 5G-ready infrastructure while prepaid subscriber economics constrain pricing flexibility. This regulatory pressure intersects with Algérie Télécom's fiber densification push in coastal corridors.
Growth Catalysts
- ARPCE spectrum modernization:Mandates for 700 MHz and 3.5 GHz refarming are unlocking capacity for mobile broadband expansion in dense urban zones.
- Youth mobile data consumption:Smartphone penetration among Algeria's 18-35 demographic is accelerating uptake of bundled service plans with higher data allowances.
- FTTH rollout acceleration:Algérie Télécom's fiber-to-the-home deployment in Algiers and Oran is anchoring fixed broadband growth through competitive pricing enabled by backbone density.
Market Restraints
- Import dependency for optical equipment:Network hardware procurement relies on foreign suppliers, exposing capex timelines to currency volatility and shipping constraints.
- Terrestrial infrastructure gaps:Saharan zones beyond fiber reach require costly satellite fallback, limiting service margins in remote governorates.
- Prepaid revenue model rigidity:Dominant pay-as-you-go mobile subscriptions constrain average revenue per user growth compared to postpaid contract markets.
Strategic Opportunities
- Enterprise satellite connectivity:Oil and gas operations in remote basins present specialized demand for dedicated bandwidth services beyond terrestrial coverage.
- IPTV bundling integration:Triple-play household contracts combining mobile, fixed broadband, and video are repositioning consumer choice toward stickier integrated offerings.
- PLI-inspired local assembly:Domestic manufacturing incentives for network equipment are reshaping procurement patterns toward local partnership models.
Industry Challenges
- Mobile termination rate reform uncertainty:Pending ARPCE decisions on interconnection pricing create capital deployment hesitation among operators.
- Copper-to-fiber migration complexity:Legacy infrastructure retirement demands coordinated workforce retraining and customer migration programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algeria Telecom Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Internet, VoIP, Fixed-line Technology: 4G, 5G, Fiber Optic, Satellite Customer Type: Residential, SMBs, Enterprises, Government Pricing Model: Postpaid, Prepaid, Bundled Packages, Pay-as-you-go |
| Companies Covered | ATM Mobilis, Djezzy Algeria, Ooredoo Algeria, Algérie Télécom, Algérie Télécom Satellite, Optimum Telecom Algeria, ARPCE, Agence Nationale Des Fréquences, ATSC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algeria Telecom Market Trends and Innovations
Software-defined networking architectures are penetrating operator core networks, enabling dynamic bandwidth allocation that responds to traffic spikes in real time. This shift is compressing hardware dependency and accelerating service velocity.
Artificial intelligence-driven network operations is automating fault detection and predictive maintenance across Algeria's mobile infrastructure. Operators are deploying machine learning models to anticipate base station degradation before service interruption occurs. This capability is automating workforce allocation and reducing mean-time-to-repair metrics in dense urban clusters.
ARPCE's pending 5G licensing framework is restructuring spectrum auction timelines and coverage obligations for prospective bidders. The regulatory uncertainty is delaying vendor commitments and financing arrangements. Mobile operators are responding by accelerating 4G capacity investments as interim positioning.
Household procurement of telecom services is consolidating toward single-provider bundles rather than fragmented vendor relationships. Retail channels emphasizing comparison shopping are losing share to direct operator sales and digital onboarding platforms. This concentration is most visible in Algiers and Oran where fiber availability enables competitive triple-play offerings.
Algeria Telecom Market Segmentation
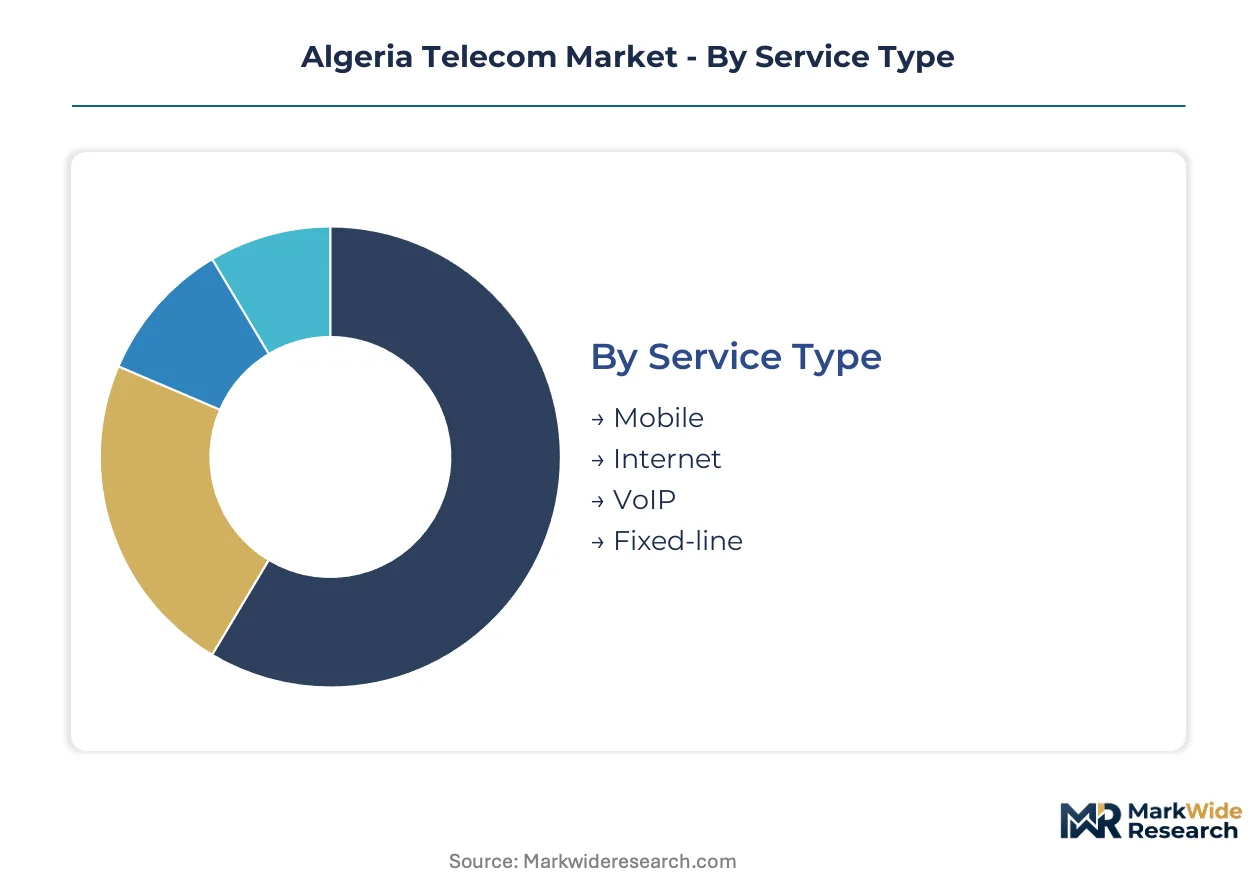
Algeria's telecom segmentation reveals how infrastructure legacy and regulatory mandates fragment revenue pools across incompatible technology generations. Service boundaries blur where fiber density enables triple-play consolidation, while prepaid economics dominate mobile uptake.
Service Type:
Standalone voice services persist in rural zones where smartphone penetration lags, while integrated offerings concentrate in coastal urban corridors with backbone density.
- Mobile:Prepaid subscriptions generate the dominant revenue stream through voice and data services delivered over 4G infrastructure. Youth demographics in Algiers and Oran drive data consumption through bundled plans with higher allowances.
- Internet:Fixed broadband access spans DSL, fiber, and wireless last-mile technologies with asymmetric performance profiles. Demand clusters in dense urban zones where Algérie Télécom's FTTH rollout enables competitive pricing.
- VoIP:Voice-over-IP services ride over fixed and mobile data connections, displacing circuit-switched traffic in enterprise and residential segments. Regulatory frameworks around interconnection rates shape competitive viability.
- Fixed-line:Legacy copper infrastructure anchors voice service in secondary cities beyond fiber reach. Subscriber counts erode as mobile substitution accelerates and fiber migration programs advance.
Mobile leads volumes today; Internet is gaining share fastest.
Technology:
Cost tiers separate capital-intensive fiber deployment from spectrum-dependent wireless coverage, with satellite occupying premium niche positioning.
- 4G:LTE networks operating across 800 MHz, 1800 MHz, and 2600 MHz bands deliver the bulk of mobile data capacity. Operators redirect capital here as ARPCE delays 5G licensing timelines.
- 5G: Next-generation infrastructure awaits spectrum allocation in 700 MHz and 3.5 GHz bands under pending ARPCE frameworks. Coverage obligations and auction pricing remain unresolved.
- Fiber Optic:Single-mode cables rated for 10 Gbps and higher throughput anchor Algérie Télécom's fixed broadband expansion. Algiers and Oran corridors concentrate deployment where trenching economics justify investment.
- Satellite:Geostationary and LEO constellations serve Saharan enterprise demand beyond terrestrial reach. Oil and gas operations in remote basins generate specialized bandwidth requirements.
Fiber Optic commands the steepest expansion trajectory; 4G maintains installed base dominance.
Customer Type:
Application requirements diverge sharply between latency-sensitive enterprise workloads and price-elastic residential consumption.
- Residential:Household demand concentrates on triple-play bundles combining mobile, fixed broadband, and IPTV services. Digital onboarding platforms displace retail comparison shopping in Algiers and Oran.
- SMBs:Small and medium businesses require symmetric connectivity for cloud services and point-of-sale systems. Pricing sensitivity constrains upgrade cycles relative to enterprise segments.
- Enterprises:Large organizations demand SLA-backed services with dedicated bandwidth and redundancy guarantees. Remote oil and gas facilities require satellite fallback where fiber cannot reach.
- Government:Public administration networks prioritize security and nationwide coverage over cost optimization. ARPCE interconnection frameworks directly affect procurement decisions.
Residential accounts for the largest subscriber base; Enterprise delivers the highest revenue per connection.
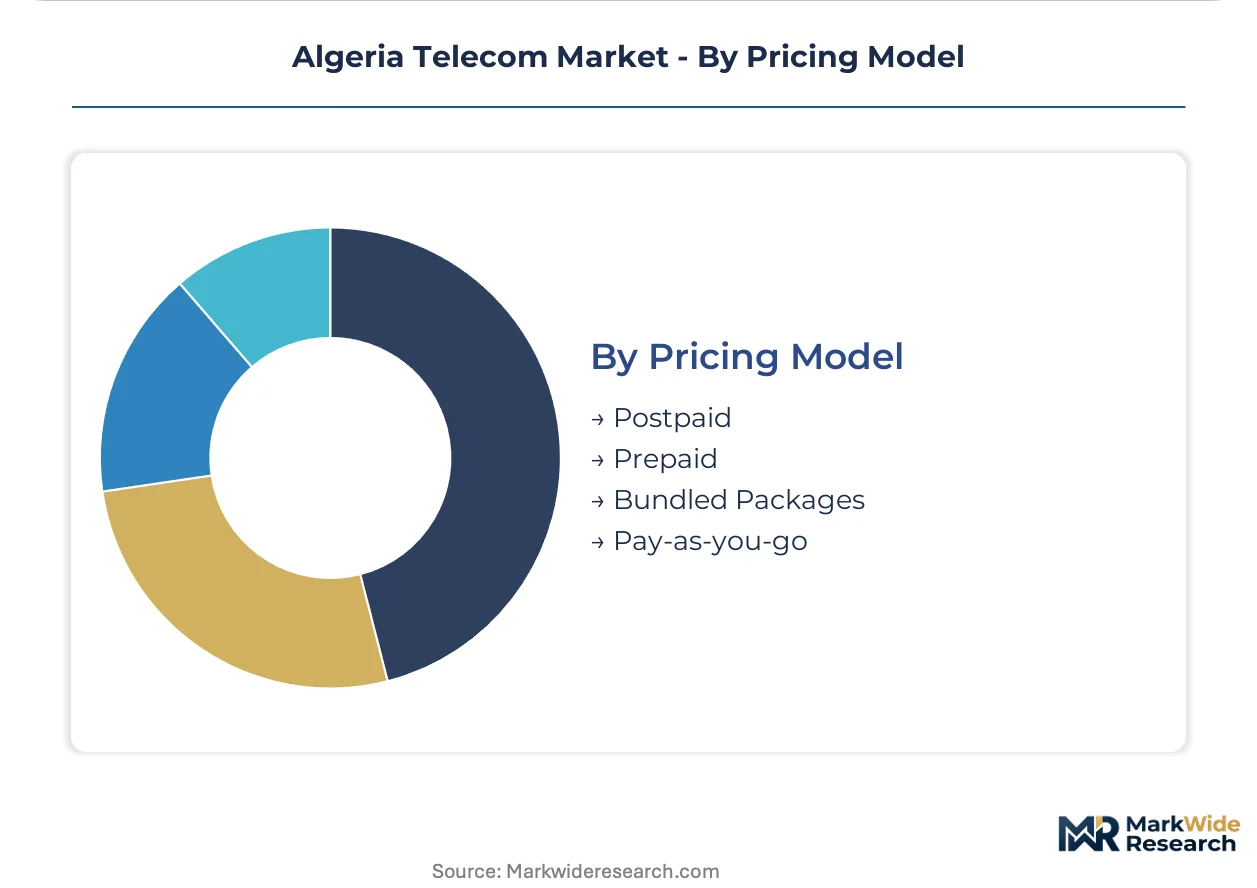
Pricing Model:
Customer type determines margin structure, with contract terms segmenting stability-seeking enterprises from churn-prone prepaid consumers.
- Postpaid:Monthly billing with usage-based overage charges anchors enterprise and affluent residential relationships. ARPU potential exceeds prepaid though subscriber acquisition costs run higher.
- Prepaid:Pay-in-advance models dominate mobile subscriptions through scratch cards and digital top-up platforms. Djezzy Algeria competes aggressively on data unit pricing within this segment.
- Bundled Packages:Triple-play and quad-play contracts combine multiple services at discounted effective rates. Stickiness improves as household switching costs accumulate.
- Pay-as-you-go:Per-minute voice and per-MB data pricing persists for unbanked and transient user populations. Margins compress relative to committed contract structures.
Prepaid dominates subscriber counts; Bundled Packages expand most quickly in fiber-served zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algeria's telecom infrastructure originated from French colonial networks in the 1950s, expanded through state investment during the 1970s hydrocarbon boom, and privatized partially in the 2000s to introduce mobile competition.
Algiers
Algiers concentrates Algeria's highest fiber backbone density and generates the strongest demand for triple-play household bundles. ARPCE's spectrum reallocation mandates prioritize capital deployment in this corridor. The capital's urban infrastructure anchors Algérie Télécom's FTTH rollout and competitive broadband pricing.
Oran
Oran's industrial base drives enterprise-grade connectivity demand from manufacturing and port logistics operations. The city's regulatory environment follows ARPCE's national frameworks with localized licensing enforcement. Coastal fiber density here enables mobile operators to test 5G-ready infrastructure ahead of spectrum auctions.
Constantine
Constantine's public administration and university networks generate specialized demand for secure government-grade services. The country's national frequency agency coordinates spectrum allocation priorities for this eastern hub. Legacy copper infrastructure persists here as fiber migration programs advance more slowly than in coastal metros.
Hassi Messaoud
Hassi Messaoud's oil and gas operations require satellite fallback connectivity beyond terrestrial fiber reach. Enterprise demand concentrates on dedicated bandwidth services with SLA-backed redundancy guarantees. Remote basin operations here exemplify the specialized niche that satellite providers occupy in Algeria's telecom segmentation.
Tamanrasset
Tamanrasset's Saharan location excludes it from fiber backbone coverage, creating dependence on wireless and satellite technologies. ARPCE's universal service obligations partially subsidize coverage extension into these remote governorates. Limited service margins here illustrate the infrastructure gap challenge constraining operator profitability in Algeria's interior.
Algeria Telecom Market Competitive Landscape
The competitive structure tilts toward state-influenced incumbency with mobile challengers operating under regulatory parity mandates. Algérie Télécom retains fixed-line dominance through legacy infrastructure control while three mobile operators contest prepaid subscriber volumes. Two strategic archetypes emerge: infrastructure-anchored incumbents leveraging copper and fiber assets, and mobile-focused challengers competing through data pricing and youth segmentation. Dominant competitive moves include fiber densification acceleration and bundled service integration to improve household stickiness.
Among Algeria-based operators, Algérie Télécom exemplifies the infrastructure-anchored archetype through its historical control of fixed-line and fiber assets. Djezzy Algeria and Ooredoo Algeria represent the mobile-challenger archetype, competing through prepaid data pricing and youth demographic targeting. These three operators collectively illustrate how regulatory-mandated spectrum access and infrastructure legacy shape competitive positioning in Algeria's concentrated telecom market.
| Leading Market Players |
|---|
| ATM Mobilis |
| Djezzy Algeria |
| Ooredoo Algeria |
| Algérie Télécom |
| Algérie Télécom Satellite |
| Optimum Telecom Algeria |
| ARPCE |
| Agence Nationale Des Fréquences |
| ATSC |
| Others |
Pricing and Supply Chain Analysis
Youth mobile data consumption in Algeria's coastal cities is compressing voice-centric pricing models and forcing operators to rebundle services around higher-margin data allowances. This demand-side shift feeds back into procurement patterns as Algérie Télécom accelerates FTTH capex to anchor household stickiness against mobile-only challengers.
Pricing Analysis
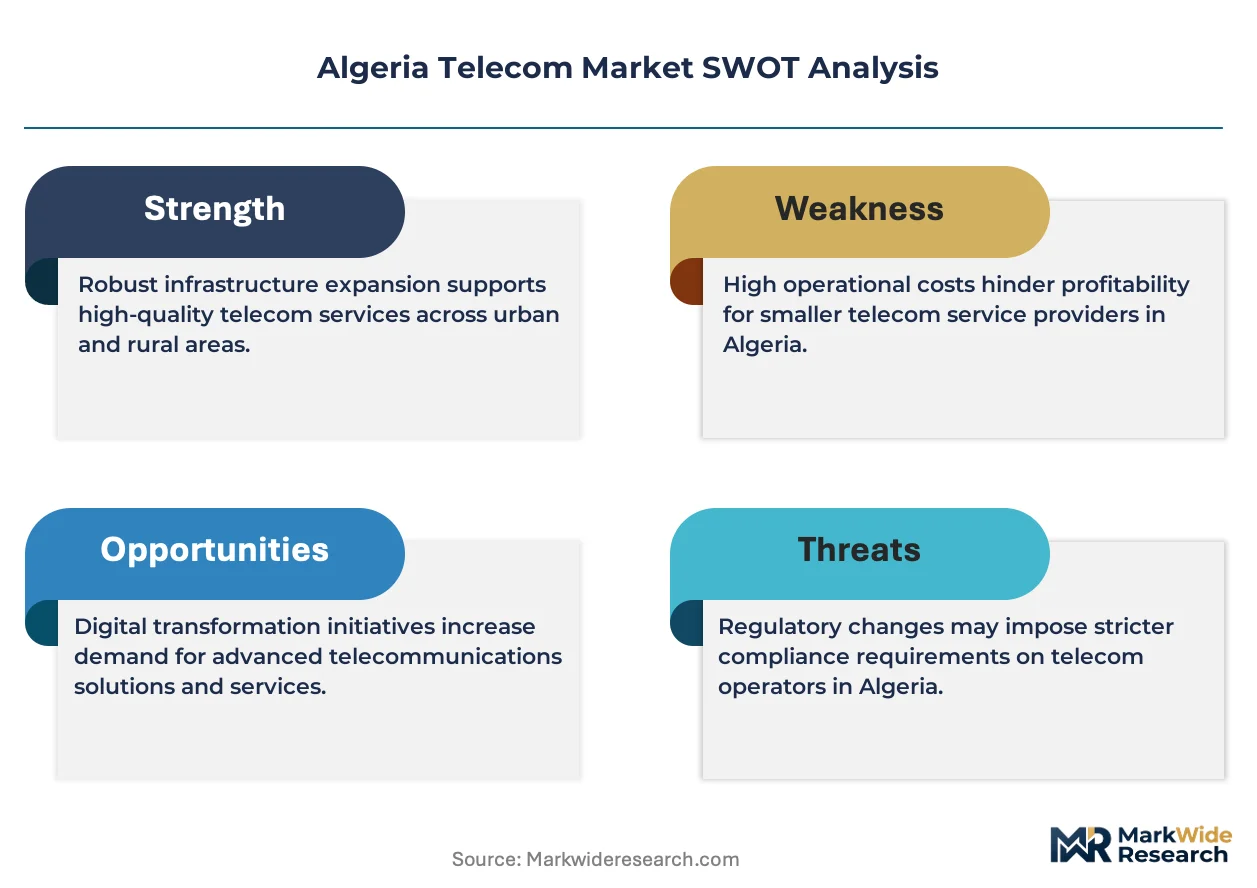
Three-tier pricing structure across premium, standard, and economy levels segments Algeria's telecom market by service bundling intensity and infrastructure access. Premium tiers command higher ARPU through triple-play contracts in Algiers and Oran where fiber density enables competitive video and broadband bundling. Price differentiation hinges on backbone proximity and after-sales service depth. Cost compression in prepaid mobile is intensifying because Djezzy Algeria's aggressive data unit pricing squeezes margins across the pay-as-you-go segment. Enterprise buyers show lowest price sensitivity due to SLA-backed redundancy requirements for oil and gas operations.
Supply Chain Analysis
Freight costs for optical equipment from China, South Korea, and Germany expose Algerian operators to currency volatility and extended lead times. Network hardware procurement draws from foreign suppliers for single-mode fiber cables, 4G base station components, and core routing equipment. Single-source vulnerability concentrates in geostationary satellite terminals serving Saharan enterprise demand. Distribution runs through Algérie Télécom's captive infrastructure for fixed-line services and mobile operators' direct retail channels in dense urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algeria's telecom market offers margin expansion through fiber densification capex efficiency and enterprise satellite premium tiering. Cost-down drivers include PLI-inspired local assembly partnerships reducing import dependency for network equipment.
For Market Incumbents: Deploy ARPCE spectrum reallocation mandates as a regulatory lever to accelerate 4G capacity investments ahead of 5G licensing uncertainty. Defend fixed-line dominance through copper-to-fiber migration programs that consolidate household relationships in secondary cities. Channel control over direct digital onboarding platforms in Algiers and Oran counters retail comparison shopping erosion. For New Entrants and Emerging Players: Oil and gas operations in remote Saharan basins represent an underserved buyer archetype with dedicated bandwidth requirements beyond terrestrial coverage. Satellite fallback services for Hassi Messaoud and Tamanrasset offer the most penetrable segment given limited fiber economics. A go-to-market angle emphasizing SLA-backed redundancy guarantees with enterprise procurement officers bypasses Algérie Télécom's infrastructure moat. For Investors and Strategic Acquirers: Asymmetric upside sits with infrastructure-anchored operators controlling fiber backbone density in coastal corridors. Long-term viability over a multi-year horizon favors incumbents with regulatory relationships and spectrum access rights. The signal to watch is ARPCE's pending mobile termination rate reform as an inflection indicator for operator capital deployment confidence.| Strategic Initiative | Industry Significance |
|---|---|
| FTTH Rollout Acceleration | Algérie Télécom's fiber densification in Algiers and Oran anchors household bundle stickiness against mobile substitution. |
| Spectrum Reallocation Compliance | ARPCE mandates for 700 MHz and 3.5 GHz refarming unlock mobile broadband capacity in dense urban zones. |
| Enterprise Satellite Partnership | Dedicated bandwidth services for remote oil and gas operations capture premium pricing beyond terrestrial reach. |
| Triple-Play Bundle Integration | Combined mobile, fixed broadband, and IPTV contracts reposition consumer choice toward stickier household relationships. |
| PLI-Inspired Local Assembly | Domestic manufacturing incentives reshape procurement patterns toward local partnership models reducing import exposure. |
Research Methodology
Direct dialogue with network operations executives, ARPCE regulatory affairs leads, enterprise procurement managers at oil and gas facilities, and mobile operator strategy heads grounded this analysis in operational reality. Secondary validation drew from ARPCE licensing disclosures, Agence Nationale Des Fréquences spectrum allocation records, operator capex filings, and customs data on optical equipment imports. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing across service type, technology, and customer segmentation dimensions.
Market value and volume outputs across the analysis window reflect a structured analytical framework incorporating infrastructure deployment timelines, spectrum auction probability weighting, and prepaid-to-postpaid migration elasticity. Segmentation dimensions modeled include service type, technology generation, customer archetype, and pricing model commitment structure. CAGRs were derived from trend extrapolation of mobile data consumption intensity, fiber penetration curves, and enterprise bandwidth demand growth. Industry-specific forecast inputs encompass ARPCE regulatory timeline scenarios and PLI scheme implementation progress.
Underlying measurement precision varies by segment; mobile subscriber counts carry tighter precision than satellite enterprise revenue allocations. Forecasts reflect assumptions around spectrum licensing timing, fiber trenching economics, and hydrocarbon sector capex cycles. A model refresh is warranted upon material change in ARPCE's 5G framework publication or mobile termination rate reform implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global IP Phone Market
Telecommunications
Standalone 5G Network Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
SIP Trunking Services Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
Costa Rica Telecom Market
Telecommunications
5G Equipment Market
Telecommunications
Luxembourg Telecom Market
Telecommunications
Thailand Telecom Market
Telecommunications
Hong Kong Telecom Market
Telecommunications
GPON Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
C-RAN Market
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
Vietnam ICT Market
Telecommunications
Thailand ICT Market