
 North America Video Management System Market | 2026-2036
North America Video Management System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Video Management System Market Insights
Modular platform bundling is repositioning buyer procurement patterns across the North America Video Management System Market. Eagle Eye Networks leverages cloud-native architecture to capture mid-market accounts seeking scalable subscription models. Motorola Solutions anchors public safety verticals through integrated command-center ecosystems. Genetec differentiates via unified security platforms that merge video with access control and analytics.
A Video Management System constitutes software and hardware infrastructure that ingests, stores, retrieves, and analyzes video feeds from IP cameras and encoders, typically supporting H.265 compression and ONVIF protocol interoperability for multi-vendor camera compatibility. The primary commercial purpose centers on centralized visual oversight for security operations, operational intelligence, and forensic investigation across distributed physical environments. Cloud-based deployment leads segment momentum as organizations abandon capital-intensive server farms for elastic storage and remote accessibility. Edge computing architectures represent the fastest-growing configuration, processing analytics locally to reduce bandwidth consumption and latency for real-time threat detection. On-premise systems retain dominance in correctional facilities and classified government installations where data sovereignty mandates physical control.
FCC spectrum allocations shape wireless video transmission capabilities for mobile surveillance units across the region. NIST cybersecurity frameworks and state biometric privacy statutes in Illinois and Texas compel vendors to embed encryption, audit logging, and consent management into platform design. Stakeholders must monitor evolving municipal procurement standards and fusion-center interoperability requirements as federal infrastructure funding flows toward integrated public safety networks.
Market Dynamics
Cloud-native architecture is displacing on-premise server infrastructure across North American security operations, compressing capital deployment cycles while expanding elastic storage access for distributed camera networks.
Growth Catalysts
- Smart City Infrastructure:Federal infrastructure funding flows toward integrated public safety networks in Texas and California metropolitan corridors, accelerating procurement of centralized surveillance platforms for municipal operations.
- NIST Cybersecurity Framework:Compliance mandates from the National Institute of Standards and Technology compel enterprise security upgrades, embedding encryption and audit logging into platform procurement specifications.
- Edge Computing Architectures:Local processing capabilities reduce bandwidth consumption for real-time threat detection, enabling deployment in bandwidth-constrained environments across remote industrial facilities.
Market Restraints
- Semiconductor Component Volatility:Specialized encoder chips and GPU shortages create input cost instability for hardware-integrated VMS deployments, squeezing margin structures for appliance-based vendors.
- State Biometric Privacy Statutes:Illinois Biometric Information Privacy Act and Texas biometric consent laws impose litigation exposure and compliance friction on facial recognition analytics deployments.
- Data Sovereignty Mandates:Classified government installations and correctional facilities require physical server control, limiting cloud migration in high-security verticals and fragmenting addressable demand.
Strategic Opportunities
- Mid-Market Subscription Penetration:Scalable SaaS models remain underdeployed among regional retail chains and multi-site healthcare clinics seeking predictable operational expenditure structures.
- Unified Security Convergence:Integration of video management with access control and license plate recognition creates platform stickiness, opening expansion paths for vendors with adjacent security portfolios.
- FCC Spectrum Allocation:Wireless transmission standardization for mobile surveillance units enables temporary deployment models for event security and construction site monitoring across Canadian and US jurisdictions.
Industry Challenges
- Cybersecurity Talent Scarcity:Shortage of professionals skilled in zero-trust architecture and encrypted video pipeline engineering slows enterprise deployment timelines and elevates implementation risk.
- Legacy Analog Migration Complexity:Hybrid environments requiring coexistence of coaxial infrastructure with IP networks create integration friction and extended commissioning cycles for facility upgrades.
- ONVIF Certification Bottlenecks:Multi-vendor camera compatibility testing delays product release schedules and fragments interoperability assurance across manufacturer ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Video Management System Market |
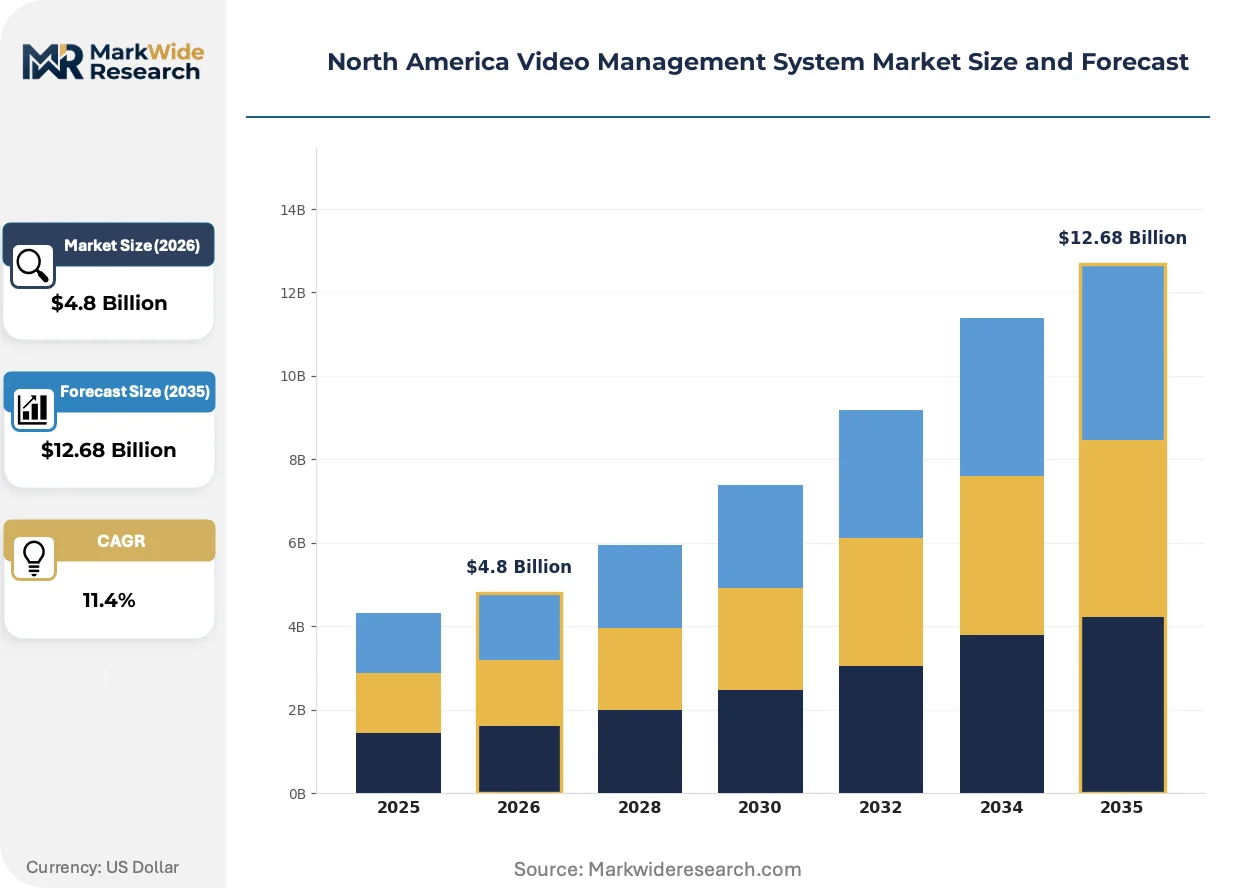
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Service, Cloud-based End User: Retail, Transportation, Hospitality, Education Deployment: On-premise, Cloud, Hybrid, Edge Application: Surveillance, Data Analytics, Traffic Monitoring, Incident Management |
| Companies Covered | Eagle Eye Networks Inc, Motorola Solutions Inc, Genetec Inc, Milestone Systems, Axis Communications AB, Honeywell International Inc, Avigilon Corporation, Verkada Inc, Johnson Controls International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Video Management System Market Trends and Innovations
Artificial intelligence inference at the network edge is compressing response latency while reshaping how security operations centers prioritize human attention allocation across distributed camera feeds.
Edge-based GPU acceleration for real-time video analytics is modularizing platform architectures. Large enterprise campuses and logistics hubs in the US Midwest are deploying containerized microservices that separate storage, processing, and user interface functions. This disaggregation enables independent scaling of compute resources based on analytic intensity rather than camera count.
Illinois and Texas biometric privacy statutes are mandating explicit consent capture and retention limitation for facial recognition deployments. Industrial consequence includes forced redesign of analytics pipelines to embed audit trails and data deletion workflows. Financial services and healthcare verticals are responding by segmenting biometric-enabled cameras into isolated network zones with enhanced access controls.
Security-as-a-service purchasing is consolidating vendor relationships among multi-site retail and quick-service restaurant operators. Traditional reseller channels face displacement by direct cloud provisioning and manufacturer-managed subscription billing. This pattern concentrates most visibly in California and Texas, where property management firms bundle surveillance with access control under single-provider contracts.
North America Video Management System Market Segmentation
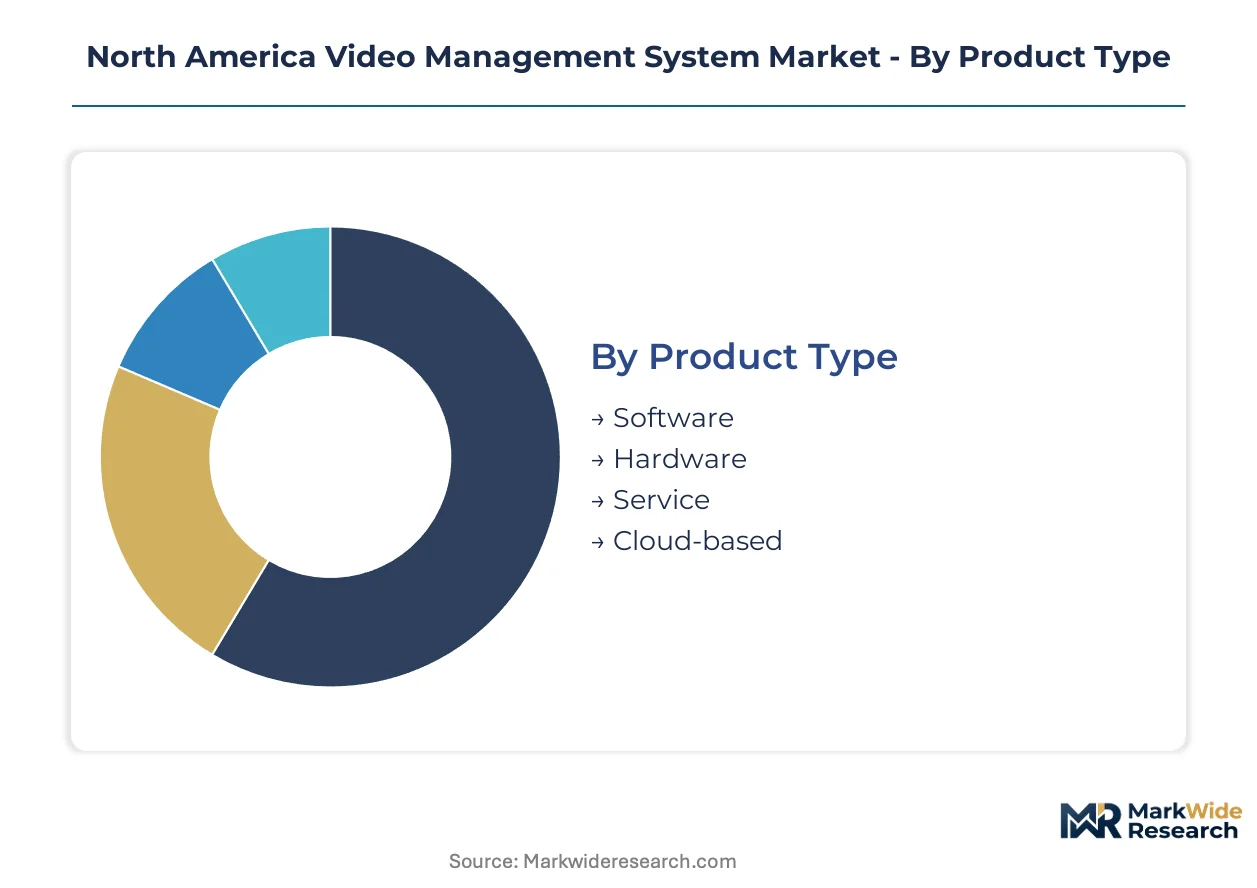
North American procurement patterns diverge sharply between capital-intensive on-premise installations and elastic cloud subscriptions. Segmentation reveals how federal cybersecurity mandates and state privacy statutes reshape vendor prioritization across product architectures and end-use verticals.
Product Type:
Volume concentration sits with hardware appliances and perpetual software licenses. Premium expansion concentrates in recurring-revenue cloud services and managed security offerings.
- Software:On-premise VMS platforms with H.265 codec support and ONVIF protocol interoperability form the technical backbone of enterprise security operations. Demand clusters among Texas and California metropolitan corridors where municipal smart city projects require centralized command-center integration. NIST cybersecurity frameworks compel encryption and audit logging capabilities as baseline procurement requirements.
- Cloud-based:SaaS delivery models with elastic storage and remote accessibility are displacing server infrastructure across mid-market retail and healthcare networks. Subscription economics attract multi-site operators seeking predictable operational expenditure structures without capital-intensive server farms.
- Hardware:Dedicated NVR appliances and encoder devices with GPU acceleration for edge analytics serve bandwidth-constrained industrial facilities.
- Service:Managed security operations and system integration support legacy analog migration and hybrid environment commissioning.
Mature deployment sits with hardware-integrated on-premise systems. Newer deployment is concentrated in cloud-native software architectures.
End User:
Application intensity varies by vertical regulatory exposure and physical asset dispersion.
- Retail:Multi-site chains deploy unified platforms combining surveillance with point-of-sale integration and loss prevention analytics. Illinois and Texas biometric privacy statutes force explicit consent workflows for facial recognition deployments in customer-facing zones.
- Transportation:Airports, seaports, and rail networks require FCC-compliant wireless transmission for mobile surveillance units and temporary event security.
- Education:K-12 and university campuses prioritize incident management integration with access control and mass notification systems.
- Hospitality:Casino and resort operators segment biometric-enabled cameras into isolated network zones with enhanced access controls per state privacy mandates.
Procurement sophistication sits with transportation authorities. Fastest expansion is occurring in retail security-as-a-service consolidation.
Deployment:
Configuration choice hinges on data sovereignty requirements versus bandwidth elasticity needs.
- Cloud:Centralized storage with remote accessibility dominates among regional retail chains and quick-service restaurant operators. California and Texas property management firms bundle surveillance with access control under single-provider contracts.
- Edge:Local GPU processing for real-time analytics reduces bandwidth consumption in remote industrial facilities and logistics hubs. Containerized microservices enable independent scaling of compute resources based on analytic intensity.
- On-premise:Physical server control satisfies classified government installations and correctional facilities with data sovereignty mandates.
- Hybrid:Coexistence architectures bridge legacy coaxial infrastructure with IP networks during extended facility upgrade cycles.
Security-critical deployment sits with on-premise systems. Steepest expansion trajectory belongs to edge computing architectures.
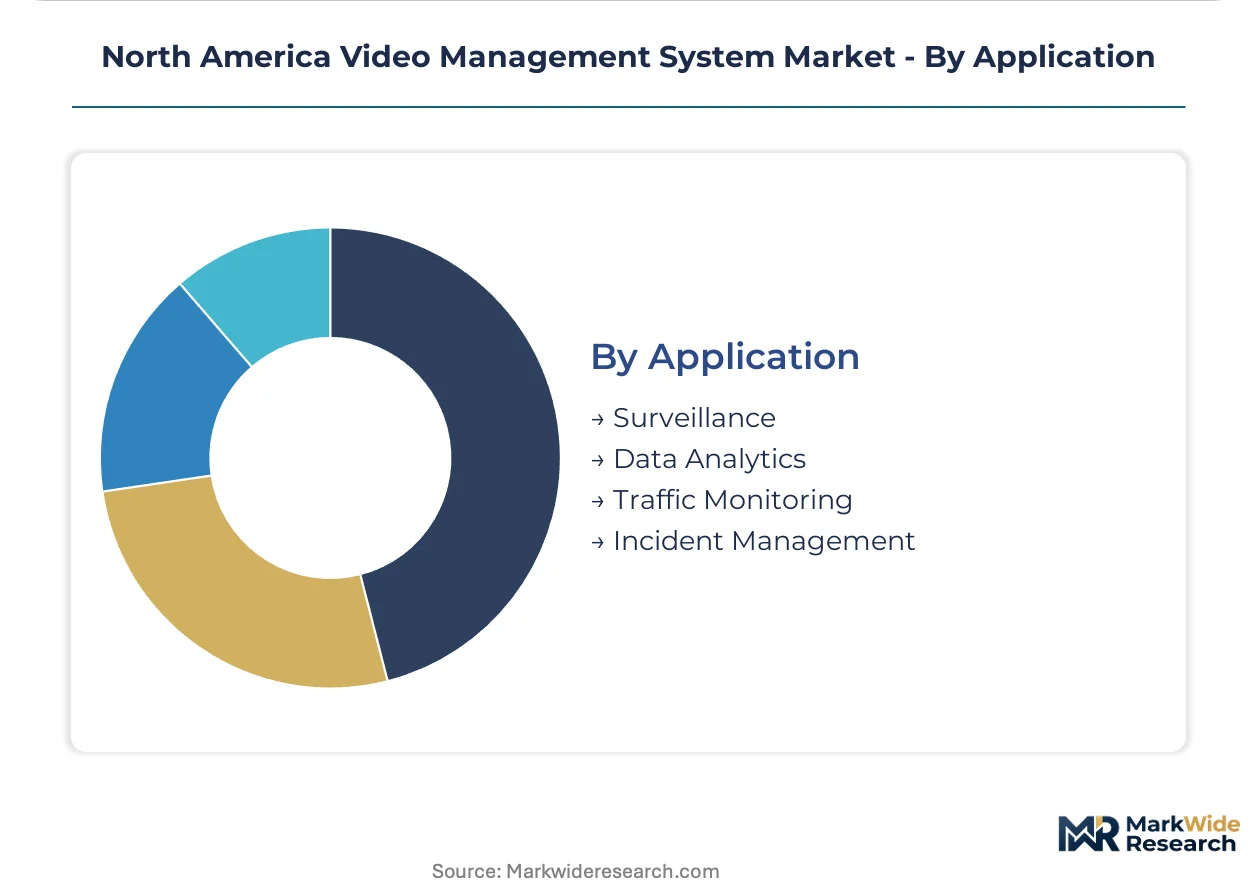
Application:
Functional depth determines platform stickiness and pricing tier access.
- Surveillance:Core video ingestion, storage, and retrieval capabilities with centralized visual oversight for security operations centers. Demand concentrates in enterprise campus upgrades and municipal public safety networks.
- Data Analytics:AI inference for object detection, behavior analysis, and forensic search commands premium positioning. Financial services verticals embed audit trails and data deletion workflows per biometric privacy compliance.
- Traffic Monitoring:License plate recognition and vehicle classification serve transportation authorities and parking management operators.
- Incident Management:Real-time alerting and response coordination integrates with command-center ecosystems for fusion-center interoperability.
Baseline deployment sits with pure surveillance. Advanced deployment is concentrating in analytics-integrated platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of video management hardware concentrates in East Asian manufacturing centers, while consumption and platform development dominate North American metropolitan corridors. The region's procurement patterns split between capital-intensive on-premise installations and elastic cloud subscriptions.
United States
Federal infrastructure funding and smart city initiatives in Texas and California metropolitan corridors accelerate centralized surveillance platform deployment. NIST cybersecurity frameworks mandate encryption and audit logging as baseline procurement requirements. Chicago and Houston anchor municipal demand for integrated public safety networks with fusion-center interoperability.
Canada
Transportation authorities in Toronto and Vancouver drive demand for FCC-compliant wireless transmission in mobile surveillance units. Health Canada privacy guidelines shape biometric analytics consent workflows for financial services and healthcare verticals. Montreal and Calgary concentrate enterprise security upgrades combining video with access control convergence.
Mexico
Manufacturing clusters in Nuevo León and Baja California deploy edge computing architectures for bandwidth-constrained industrial facilities. The country's federal data protection authority imposes retention limitations on cross-border video storage. Mexico City anchors hospitality and retail security-as-a-service consolidation among multi-site operators.
North America Video Management System Market Competitive Landscape
The competitive structure tilts toward cloud-native specialists with recurring-revenue models. Three distinct archetypes occupy the field: subscription-scale platforms targeting mid-market verticals, integrated security conglomerates bundling video with adjacent systems, and hardware-anchored vendors defending appliance-based margins. Dominant competitive moves include strategic partnerships for fusion-center interoperability and portfolio diversification into unified security convergence.
Within the cloud-native tier, Eagle Eye Networks and Verkada exemplify scalable SaaS delivery models displacing capital-intensive server infrastructure. Motorola Solutions and Honeywell International occupy positions among integrated security conglomerates leveraging command-center ecosystems. Genetec represents the unified platform archetype merging video management with access control and analytics for enterprise stickiness.
| Leading Market Players |
|---|
| Eagle Eye Networks Inc |
| Motorola Solutions Inc |
| Genetec Inc |
| Milestone Systems |
| Axis Communications AB |
| Honeywell International Inc |
| Avigilon Corporation |
| Verkada Inc |
| Johnson Controls International |
| Others |
Pricing and Supply Chain Analysis
Embedded software engineering talent concentration in California and Texas metropolitan corridors feeds labor-cost differentials into pricing-tier spreads across cloud-native and on-premise deployment models.
Pricing Analysis
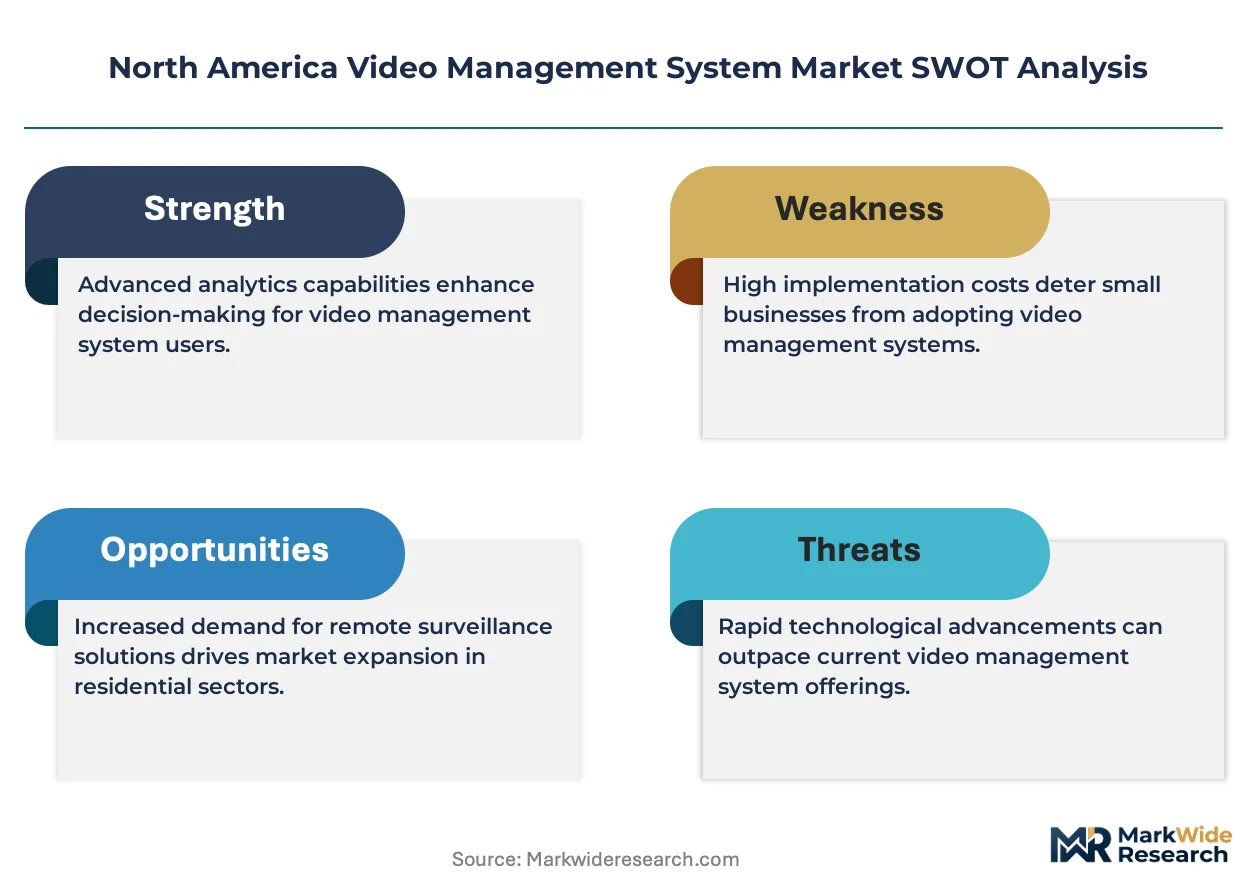
Margin tightening in hardware-integrated tiers reflects GPU and specialized encoder chip shortages squeezing appliance-based vendors. Three-tier pricing structure across premium analytics-enabled, standard surveillance, and economy basic-storage levels separates buyers by AI inference intensity and compliance certification requirements. Cost-down pressure on mid-market SaaS subscriptions accelerates because Eagle Eye Networks and Verkada compete for predictable operational expenditure contracts. Regional retail chains exhibit highest price sensitivity; classified government installations show least sensitivity due to data sovereignty mandates.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced GPU and encoder chip fabrication. Hardware assembly draws from China, Mexico, and domestic US facilities for NVR appliances and edge computing devices. Supply chain risk centers on FCC spectrum allocation delays for wireless transmission components. Distribution runs through manufacturer-direct cloud provisioning displacing traditional reseller channels, with system integrators retaining role in hybrid deployment commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American Video Management System Market consolidation accelerates as NIST cybersecurity compliance costs force sub-scale vendors toward exit or acquisition.
For Market Incumbents: Cement platform stickiness through unified security convergence bundling video with access control and license plate recognition. Deepen backward integration into edge GPU acceleration hardware to defend margin position against cloud-native entrants. Prioritize Health Canada and state biometric privacy certification investment to lock out non-compliant competitors from healthcare and financial services verticals.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in mid-market healthcare clinics and regional retail chains offers white-space entry. Target bandwidth-constrained industrial facilities in Mexico and remote US logistics hubs with containerized microservices edge deployment. Pursue FCC-compliant wireless transmission partnerships as go-to-market angle for temporary event security and construction site monitoring.
For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native specialists with recurring-revenue models above sixty percent given federal infrastructure funding flows toward integrated public safety networks. Long-term viability favors vendors with adjacent security portfolio breadth over pure-play hardware appliance manufacturers. Monitor Illinois and Texas biometric privacy litigation exposure as signal for facial recognition analytics platform valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified security convergence merges video with access control and analytics for enterprise stickiness. |
| Strategic Partnership | FCC spectrum allocation partnerships enable wireless mobile surveillance for event security verticals. |
| Acquisition of Specialist Firm | Edge GPU acceleration capability targets bandwidth-constrained industrial facility deployments. |
| Geographic Expansion | Mexico manufacturing clusters deploy localized edge computing for cross-border data protection compliance. |
| Product Launch | Cloud-native SaaS tiers displace capital-intensive server farms among multi-site retail operators. |
Research Methodology
Independent corroboration across security operations center directors, municipal procurement officers, cloud platform engineers, and system integration specialists underwrites the qualitative findings. Primary fieldwork combined with secondary validation from SEC filings, municipal smart city procurement databases, FCC spectrum allocation records, and NIST cybersecurity framework documentation. Bottom-up camera count and deployment model sizing triangulates against top-down federal infrastructure funding flow analysis.
Rate-of-change decomposition across the analysis window separates volume expansion from value migration between on-premise, cloud, and edge deployment configurations. Segmentation dimensions modeled include product architecture, end-use vertical regulatory exposure, deployment configuration, and application functional depth. CAGRs derive from installed base replacement cycles and greenfield smart city project pipelines. Forecast inputs incorporate NIST compliance mandate implementation timelines and state biometric privacy statute enforcement patterns.
Inputs from municipal procurement databases and federal funding disclosure records were available through the study window; gaps in private cloud subscription pricing transparency introduce uncertainty bands around mid-market SaaS penetration trajectories. Forecasts reflect documented assumptions regarding edge computing hardware cost curves and cybersecurity talent scarcity resolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
US Evidence Management Market
Security Software
Security Testing Market
Security Software
Global Data Masking Market
Security Software
Global Error Monitoring Software Market
Security Software
Cyber Attack Simulation Software Market
Security Software
Secure Flash Drive Market
Security Software
Global Runtime Application Self-Protection Market
Security Software
Europe Lawful Interception Market
Security Software
Europe Video Management System Market
Security Software
Keystroke Dynamics Market
Security Software
Global Network Encryption Market
Security Software
Global Background Screening Market
Security Software
Home Webcam Market
Security Software
Mobile Antivirus Software Market
Security Software
Cloud Security Software Market
Security Software
Europe User Provisioning Market