
 Austria Telecom Market | 2026-2036
Austria Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Telecom Market Insights
Multi-sourced infrastructure deployment is restructuring how Austrian carriers provision capacity. A1 Telekom Austria Group leverages its legacy copper and fiber footprint to anchor wholesale access across rural Bundesländer. Magenta Telekom competes through aggressive fiber-to-the-home buildouts in urban corridors. Hutchison Drei Austria GmbH specializes in mobile-first converged bundles that target price-sensitive residential segments.
Austria Telecom encompasses the provision of voice, data, and internet connectivity services across fixed and wireless infrastructures operating at frequencies from 700 MHz to 3.5 GHz and transmission speeds scaling from 100 Mbps DSL to 10 Gbps passive optical networks. Its primary commercial purpose is enabling digital commerce, remote collaboration, and machine-to-machine communication for Austrian businesses and households. Mobile and broadband services command the largest revenue pools, while 5G and fiber optic deployments represent the fastest-expanding technology segments as enterprises abandon legacy DSL. Government and large enterprise end users concentrate margin opportunities through multi-year managed service contracts with stringent uptime guarantees.
RTR, Austria's national regulatory authority, enforces wholesale access pricing and net neutrality under the EU Electronic Communications Code, directly influencing carrier investment timelines and interconnection economics. GDPR and the EU Cybersecurity Act impose data localization and breach-notification standards that elevate compliance costs for cloud-based deployments. Stakeholders must monitor spectrum auction outcomes and EU state-aid rulings on rural broadband subsidies to anticipate shifts in competitive advantage between infrastructure-heavy and asset-light operating models.
Market Dynamics
Enterprise cloud migration and fiber densification are restructuring carrier economics across Austria, compressing legacy DSL margins while elevating demand for symmetric gigabit connectivity and managed security bundles.
Growth Catalysts
- EU Electronic Communications Code:Wholesale access mandates under RTR enforcement are lowering barriers for alternative carriers to lease incumbent infrastructure, stimulating retail price competition and service innovation in underserved Bundesländer.
- Smart manufacturing clusters:Industrial zones in Upper Austria and Styria are deploying private 5G campus networks for machine-to-machine communication, creating dedicated revenue streams for specialized network integrators.
- Fiber-to-the-home acceleration:Municipal partnerships in Vienna and Graz are pooling rights-of-way and construction permits, reducing deployment timelines for last-mile optical infrastructure.
Market Restraints
- Copper network maintenance burden:Incumbent carriers face stranded asset costs as legacy DSL subscriber bases erode, forcing parallel investment in fiber overlay while sustaining declining revenue pools.
- GDPR compliance overhead:Data localization and breach-notification standards impose recurring audit and encryption infrastructure costs that disproportionately burden mid-tier operators with limited legal resources.
- Fixed wireless substitution:5G fixed wireless access from mobile-first operators is capturing price-sensitive households in multi-dwelling units, constraining fiber penetration in dense urban micro-markets.
Strategic Opportunities
- Rural broadband subsidies:EU state-aid rulings on broadband deployment in Burgenland and Carinthia are unlocking public co-funding for fiber extension into sub-scale municipalities previously deemed uneconomical.
- Edge computing convergence:Integration of distributed cloud nodes with 5G base stations is creating low-latency service bundles for autonomous logistics and real-time industrial control applications.
- Cybersecurity service layering:The EU Cybersecurity Act is mandating baseline security standards for critical infrastructure, opening managed security service contracts for carriers with certified network operations centers.
Industry Challenges
- Fiber splicing technician shortage:Specialized optical installation skills are concentrated among aging incumbent workforces, constraining deployment velocity for competitive overbuilders.
- Legacy billing system integration:Converged fixed-mobile bundles require real-time rating engines that interoperate with decades-old copper-era customer management platforms, elevating IT transformation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Telecom Market |
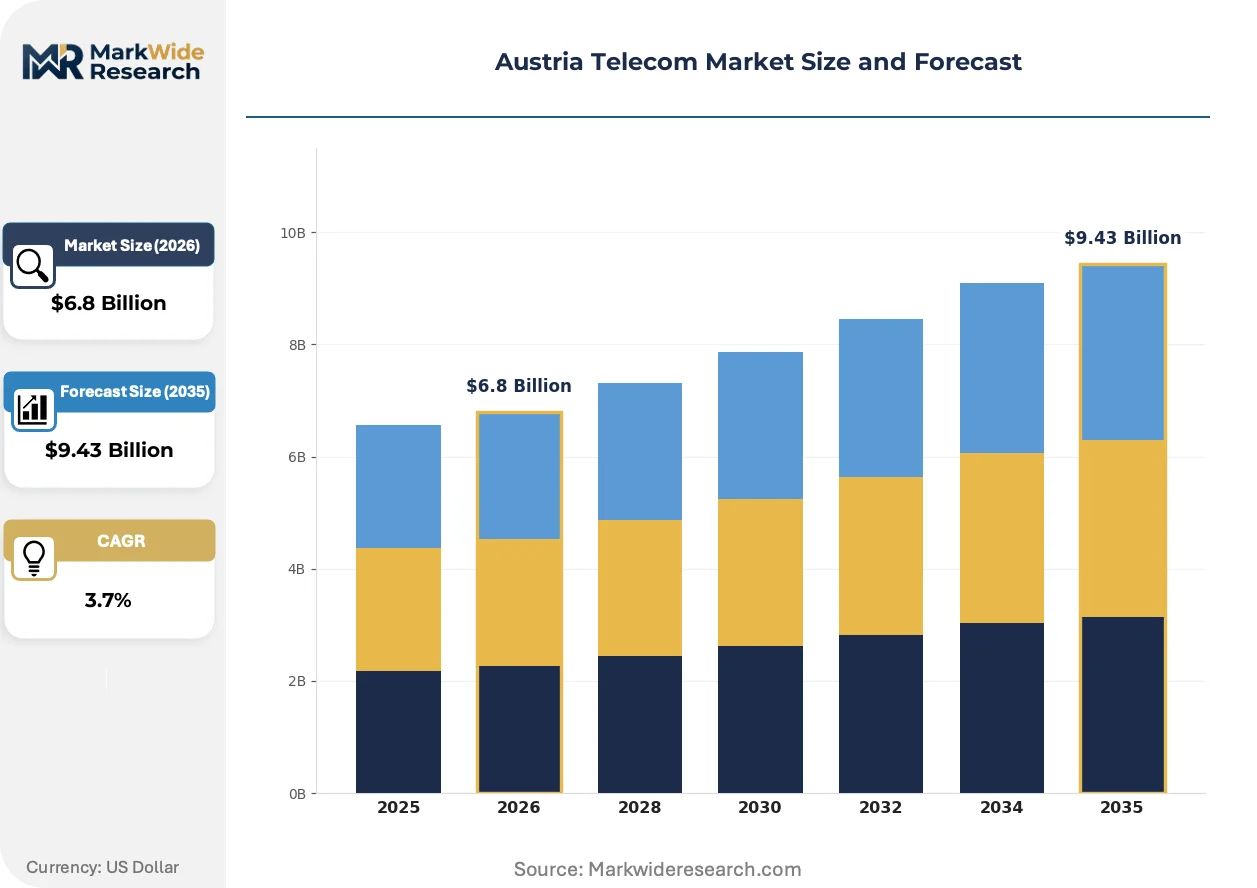
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Broadband, Fixed-Line, VoIP Technology: Fiber Optic, DSL, LTE, 5G End User: Residential, SME, Large Enterprise, Government Deployment: On-Premises, Cloud-Based, Hybrid, Managed |
| Companies Covered | A1 Telekom Austria Group, Magenta Telekom, Hutchison Drei Austria GmbH, Telekom Austria AG, Red Bull Mobile, telering, bob, B-free, Yesss!, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Telecom Market Trends and Innovations
Open RAN architectures and software-defined networking are dissolving hardware vendor lock-in across Austrian mobile infrastructure, enabling multi-vendor interoperability and operational cost restructuring.
Network function virtualization is decentralizing core network intelligence from centralized data centers toward distributed edge nodes. Tier-one carriers in Vienna are deploying virtualized baseband units within regional aggregation points, reducing backhaul latency for enterprise applications. This topology shift is compressing capital intensity per subscriber while enabling dynamic spectrum slicing for differentiated service tiers.
RTR's implementation of the EU Electronic Communications Code is tightening wholesale access pricing transparency requirements. Carriers must now publish reference offers for unbundled local loop and bitstream access with standardized cost accounting methodologies. Infrastructure-heavy operators are responding by accelerating fiber depreciation schedules and lobbying for geographic cost averaging in regulated rates.
Enterprise procurement patterns are migrating from connectivity-only contracts toward integrated digital workspace bundles. Mid-sized manufacturers in Linz and Salzburg are sourcing combined SD-WAN, unified communications, and endpoint security through single-vendor frameworks, displacing multi-supplier arrangements. Channel partners with vertical industry certifications are capturing margin previously retained by direct carrier sales teams.
Austria Telecom Market Segmentation
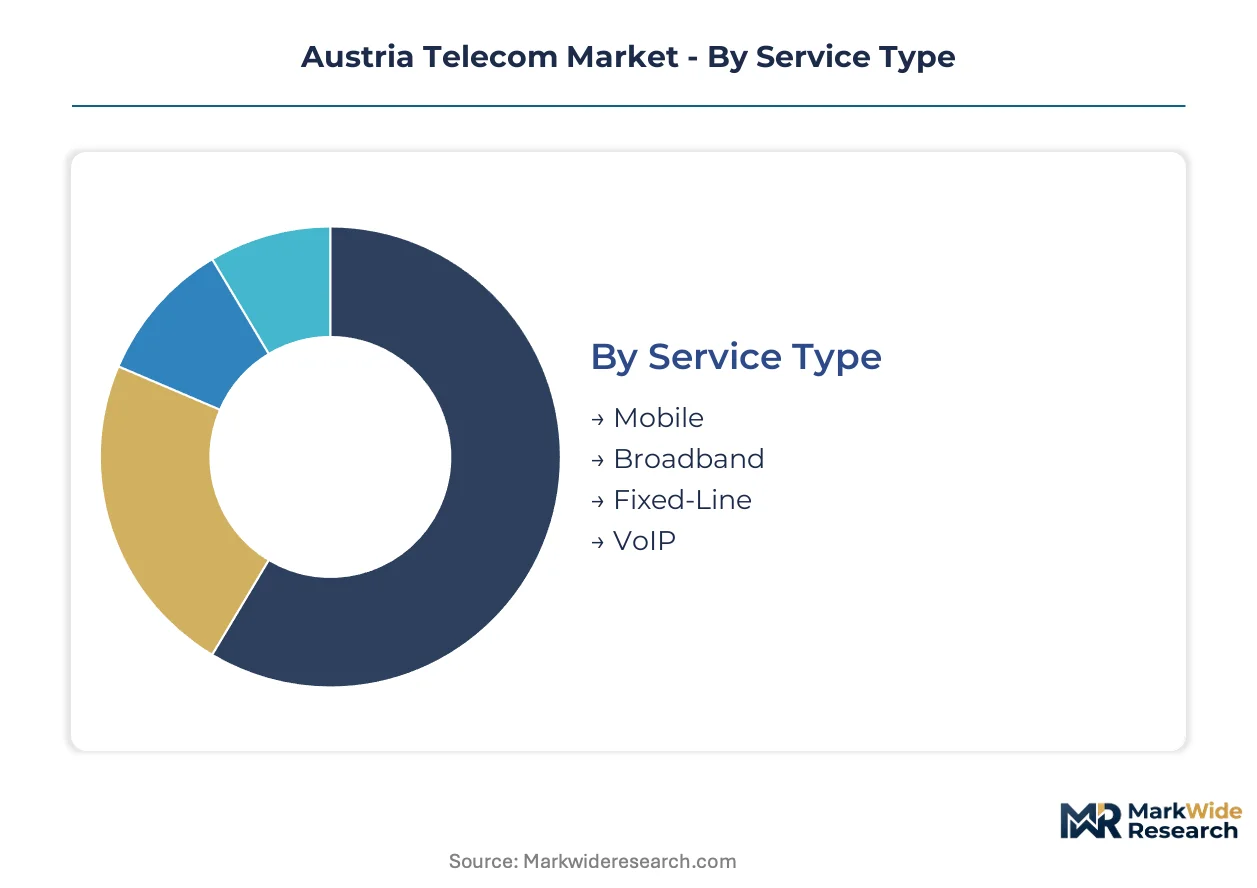
Carrier revenue streams in Austria diverge sharply across service modalities and infrastructure layers. Understanding these partitions reveals where RTR-regulated wholesale access intersects with enterprise procurement patterns and residential price sensitivity.
Service Type:
Customization intensity varies from standardized mass-market bundles to negotiated managed service frameworks with uptime guarantees.
- Mobile:Wireless voice and data services operating across 700 MHz to 3.5 GHz spectrum bands. Demand concentrates among price-sensitive residential subscribers in Vienna's multi-dwelling units where 5G fixed wireless substitutes for fiber installation delays.
- Broadband:High-speed internet access spanning DSL, cable, and fiber-to-the-home technologies. Large enterprises in Upper Austria's manufacturing clusters drive symmetric gigabit requirements for cloud migration and real-time machine-to-machine communication.
- Fixed-Line:Traditional copper-based voice services with declining subscriber bases. Rural Bundesländer retain residual demand from aging demographics and businesses requiring guaranteed service continuity during power outages.
- VoIP:Packet-switched voice delivery over IP networks with unified communications integration. SMEs in Graz and Salzburg adopt cloud-based PBX systems to eliminate premise equipment maintenance costs.
Most installed capacity flows through Mobile. Expansion is steepest in Broadband.
Technology:
Capital intensity and depreciation timelines separate legacy amortization plays from greenfield infrastructure bets.
- Fiber Optic:Passive optical networks delivering up to 10 Gbps symmetric speeds over single-mode glass. Municipal partnerships in Vienna and Graz accelerate last-mile deployment through pooled rights-of-way and streamlined construction permitting.
- DSL:Copper-pair digital subscriber line technologies from ADSL2+ to VDSL2 vectoring. Incumbent carriers face stranded asset costs as subscriber migration erodes revenue pools while parallel fiber overlay demands sustained capital allocation.
- LTE:Fourth-generation mobile broadband using 800 MHz and 2600 MHz bands for wide-area coverage. Rural coverage obligations under RTR spectrum licenses sustain deployment in Burgenland and Carinthia sub-scale municipalities.
- 5G:New radio standards enabling network slicing and ultra-reliable low-latency communication. Private campus networks in Styrian industrial zones create dedicated revenue streams for specialized network integrators serving smart manufacturing clusters.
DSL retains the largest installed base. 5G claims the steepest expansion trajectory.
End User:
Contract duration and service level agreement stringency scale with organizational scale and regulatory exposure.
- Residential:Individual households and consumers purchasing standardized bundles. Price competition intensifies in dense urban corridors where Magenta Telekom's fiber buildouts confront Hutchison Drei's mobile-first converged offerings.
- SME:Small and medium enterprises with 10-250 employees requiring managed connectivity without dedicated IT staff. SD-WAN and unified communications bundles displace multi-supplier arrangements in Linz and Salzburg mid-market manufacturing.
- Large Enterprise:Major corporations with multi-year managed service contracts and stringent uptime guarantees. Cloud migration in Vienna's financial services sector elevates demand for symmetric gigabit connectivity and edge computing convergence.
- Government:Federal and provincial agencies with cybersecurity certification requirements under the EU Cybersecurity Act. Data localization mandates and breach-notification standards favor carriers with certified network operations centers and sovereign cloud partnerships.
Residential generates the highest connection volume. Large Enterprise captures the steepest margin expansion.
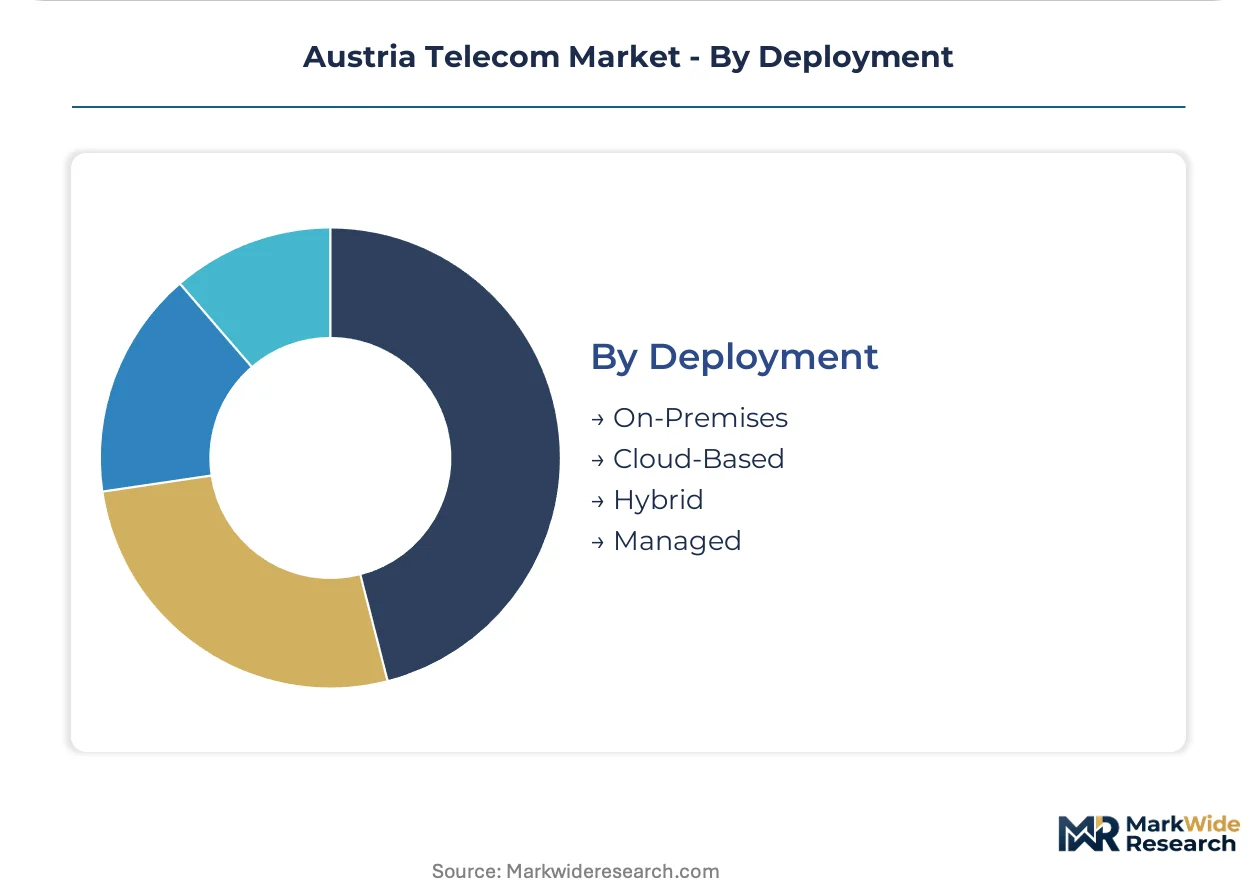
Deployment:
Control retention versus operational offload defines the architectural choice spectrum.
- On-Premises:Customer-operated equipment with full hardware ownership and maintenance responsibility. Security-sensitive government agencies in Vienna maintain legacy PBX and routing infrastructure for air-gapped operational continuity.
- Cloud-Based:Fully hosted services with subscription pricing and vendor-managed infrastructure. SMEs accelerate adoption of cloud PBX and SaaS collaboration tools to eliminate capital expenditure and technical staffing requirements.
- Hybrid:Mixed architectures combining retained premise equipment with cloud-delivered functions. Large enterprises in Salzburg deploy hybrid WAN to maintain local breakout for latency-critical applications while cloud-routing general traffic.
- Managed:Outsourced network operations with guaranteed service levels and proactive monitoring. Manufacturing clusters in Upper Austria procure managed security and connectivity bundles to satisfy industrial control system reliability requirements.
On-Premises retains residual share in regulated sectors. Cloud-Based deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vienna's metropolitan corridor anchors Austrian telecom infrastructure investment, with fiber densification and 5G campus networks concentrating in the capital's industrial zones and surrounding eastern provinces where enterprise cloud migration accelerates.
Vienna
Vienna's financial services sector drives symmetric gigabit demand for cloud migration and real-time data processing. GDPR and the EU Cybersecurity Act impose data localization standards that elevate compliance costs for carriers deploying cloud-based infrastructure. The city's smart manufacturing clusters in Floridsdorf and Simmering are deploying private 5G networks for autonomous logistics applications.
Upper Austria
Industrial zones in Linz and Steyr generate dedicated revenue streams for specialized network integrators serving smart manufacturing clusters. RTR enforces wholesale access pricing under the EU Electronic Communications Code, lowering barriers for alternative carriers to lease incumbent infrastructure. Machine-to-machine communication requirements in Wels and Leonding are compressing legacy DSL margins while elevating demand for managed security bundles.
Styria
Styrian manufacturing corridors require ultra-reliable low-latency connectivity for industrial control systems. The EU Electronic Communications Code mandates wholesale access transparency, stimulating retail price competition in Graz's underserved districts. Private 5G campus networks in Voitsberg and Kapfenberg create specialized revenue pools for network integrators targeting autonomous production lines.
Salzburg
Mid-market manufacturers in Salzburg adopt SD-WAN and unified communications bundles to displace multi-supplier arrangements. GDPR compliance overhead imposes recurring audit costs that disproportionately burden regional operators with limited legal resources. Hybrid WAN deployments in Hallein and Seekirchen maintain local breakout for latency-critical applications while cloud-routing general traffic.
Carinthia and Burgenland
Rural broadband subsidies under EU state-aid rulings unlock public co-funding for fiber extension into sub-scale municipalities previously deemed uneconomical. RTR spectrum licenses impose rural coverage obligations that sustain LTE deployment in Villach and Eisenstadt peripheries. Municipal partnerships in Klagenfurt and Wiener Neustadt are pooling rights-of-way to reduce last-mile optical infrastructure timelines.
Austria Telecom Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mobile-first converged bundles and specialized network integration. The Austrian market exhibits tiered consolidation around infrastructure-heavy incumbents, asset-light mobile operators, and regional overbuilders. Three archetypes dominate: legacy copper-fiber hybrids anchoring wholesale access, aggressive fiber-to-the-home builders, and mobile specialists capturing price-sensitive residential segments. Competitive moves concentrate on municipal partnership formation for rights-of-way pooling and vertical specialization into private 5G campus network deployment.
Within the infrastructure-heavy tier, A1 Telekom Austria Group and Telekom Austria AG represent legacy copper-fiber hybrid operators leveraging incumbent footprints to anchor wholesale access across rural Bundesländer. Magenta Telekom exemplifies the aggressive fiber-to-the-home builder archetype competing through urban corridor densification. Hutchison Drei Austria GmbH occupies the mobile-first specialist position targeting price-sensitive residential segments with converged bundles.
| Leading Market Players |
|---|
| A1 Telekom Austria Group |
| Magenta Telekom |
| Hutchison Drei Austria GmbH |
| Telekom Austria AG |
| Red Bull Mobile |
| telering |
| bob |
| B-free |
| Yesss! |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon-neutrality mandates for data center operations gate qualified supply access and premium-tier pricing for Austrian carriers deploying edge computing infrastructure, as energy-efficient certification becomes a threshold requirement for municipal partnership eligibility and enterprise contract participation.
Pricing Analysis
Input-cost pass-through from fiber optic cable and 5G radio equipment determines retail rate structures across subscription tiers. Pricing stratifies across premium symmetric-gigabit, standard asymmetric-fiber, and economy DSL-residual tiers based on latency guarantees and installation priority. Cost compression in legacy copper maintenance is intensifying because parallel fiber overlay demands sustained capital allocation. Residential subscribers in Vienna's multi-dwelling units exhibit highest price sensitivity, while government agencies with cybersecurity certification requirements show lowest sensitivity due to compliance-driven procurement.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the Netherlands anchor hub-and-spoke patterns for network equipment provisioning into Austrian carrier warehouses. Hardware sourcing draws from Finnish-German optical component specialists, Chinese base station manufacturers, and Taiwanese semiconductor foundries. Single-source vulnerability concentrates in 5G antenna arrays where Ericsson and Nokia dominate qualified vendor lists. Distribution runs through carrier-direct procurement for core infrastructure and specialized network integrators for private campus deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where RTR-regulated wholesale access pricing in Austria undercuts German Bundesnetzagentur benchmarks, enabling margin capture for infrastructure-heavy operators willing to extend fiber into Burgenland and Carinthia sub-scale municipalities.
For Market Incumbents: Hedge stranded copper asset exposure by accelerating fiber depreciation schedules and lobbying RTR for geographic cost averaging in regulated wholesale rates. Secure municipal rights-of-way partnerships in Graz and Salzburg before competitive overbuilders consolidate construction permit pipelines. Threat substitution from 5G fixed wireless access by Hutchison Drei demands defensive fiber densification in Vienna's multi-dwelling corridors. For New Entrants and Emerging Players: EU Electronic Communications Code wholesale access mandates in Austria open a window for asset-light MVNOs to lease incumbent infrastructure and undercut retail pricing in underserved Bundesländer. White-space targets concentrate in private 5G campus networks for Styrian manufacturing clusters and managed security bundles for GDPR-exposed SMEs in Linz. Go-to-market leverage vertical industry certifications from manufacturing automation vendors to displace direct carrier sales teams. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fiber overbuilders with municipal partnership pipelines in Carinthia and Burgenland but limited balance sheet capacity for construction acceleration. Long-term viability hinges on EU state-aid rural broadband subsidy continuity and RTR spectrum auction timing. Watch RTR wholesale access pricing reviews as the inflection signal for infrastructure-heavy versus asset-light model repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-to-the-Home Acceleration | Municipal partnerships in Vienna and Graz pool rights-of-way to compress last-mile deployment timelines. |
| Private 5G Campus Network Deployment | Smart manufacturing clusters in Upper Austria generate dedicated revenue streams for specialized integrators. |
| Managed Security Service Layering | EU Cybersecurity Act mandates open certified network operations center contracts for compliant carriers. |
| Edge Computing Convergence | Virtualized baseband units in regional aggregation points reduce backhaul latency for enterprise applications. |
| Open RAN Architecture Migration | Multi-vendor interoperability dissolves hardware lock-in and restructures operational cost profiles. |
Research Methodology
Bottom-up enterprise procurement modeling reconciled against top-down infrastructure deployment tracking forms the analytical core of this study. Primary interviews with carrier network planning executives, municipal digitalization officers, RTR regulatory affairs specialists, and enterprise IT procurement managers in Vienna and Linz combine with secondary validation from RTR spectrum auction records, EU Electronic Communications Code implementation directives, and carrier SEC filings. Trade data on optical fiber imports and 5G equipment customs declarations anchor supply-side triangulation.
Input-output matrices map subscriber growth assumptions to capital intensity per connection across fiber, 5G, and fixed wireless technologies. Segmentation dimensions span service modality, infrastructure layer, end-user scale, and deployment architecture throughout the forecast period. CAGRs derive from installed base erosion rates for legacy DSL overlaid with greenfield fiber and 5G adoption curves. Forecast inputs incorporate RTR wholesale access pricing trajectories and EU state-aid rural broadband subsidy allocation patterns.
Revisions become necessary when RTR regulatory rulings on geographic cost averaging, EU state-aid broadband subsidy eligibility shifts, or 5G spectrum auction timing changes materialize. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Australia Telecom Tower Market
Telecommunications
Argentina ICT Market
Telecommunications
Ireland Telecom Market
Telecommunications
Telecom Managed Services Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Voip Phone Market
Telecommunications
Turkey Telecom Market
Telecommunications
Iceland Telecom Market
Telecommunications
Managed M2M Services Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
Luxembourg Telecom Market
Telecommunications
Myanmar Telecom Market
Telecommunications
Global LTE Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
Prepaid Communication Market