
 Vietnam Telecom Market | 2026-2036
Vietnam Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Telecom Market Outlook
The capital-intensity gap between state-backed and private operators is collapsing as 5G rollout demands uniform infrastructure spending. Viettel Group leverages its defense-linked R&D pipeline to dominate network equipment sourcing. FPT Corp. competes through vertical integration into cloud data centers and enterprise software layers. Mobifone Corporation anchors its position in government and defense contracts where security clearance creates barriers.
Vietnam telecom encompasses wired and wireless communication services, network infrastructure, and digital content delivery operating across frequency bands from 700 MHz to 28 GHz with fiber backhaul requirements exceeding 100 Gbps per node. The sector enables e-commerce, remote education, telemedicine, and Industry 4.0 manufacturing across a population of roughly 100 million. Mobile Services and Internet Services together absorb the majority of consumer expenditure as smartphone penetration crosses threshold levels in secondary cities. 5G deployment under the Technology segment is expanding fastest in industrial zones near Hai Phong and Bac Ninh, while Fixed Line Services stagnates as Voice over IP substitutes legacy copper. Value-Added Services targeted at Large Enterprises generates disproportionate margin contribution relative to its revenue share.
The Ministry of Information and Communications and the Vietnam Telecommunications Authority shape spectrum allocation, licensing timelines, and domestic content requirements that determine which vendors qualify for infrastructure contracts. BIS-aligned equipment certification and cybersecurity decrees add compliance layers for foreign suppliers seeking market access. Stakeholders must monitor whether the next spectrum auction structure favors incumbent balance sheets or enables new entrants to challenge the three-operator core.
Market Dynamics
Vietnam's National Digital Transformation Program is compressing infrastructure deployment timelines while forcing state-backed and private operators toward convergent capex profiles. Spectrum scarcity in the 3.5 GHz band is intensifying competitive pressure on equipment sourcing strategies.
Growth Catalysts
- Universal Broadband Mandate:The Ministry of Information and Communications requires fiber-to-the-home coverage expansion into secondary provinces, creating guaranteed demand pools for fixed infrastructure vendors.
- Mobile Financial Services:Rural consumer adoption of wallet-based payments is driving smartphone penetration and data consumption in previously underbanked districts.
- Industrial Zone 5G Deployment:Manufacturing clusters near Hai Phong and Bac Ninh are requesting dedicated network slices for Industry 4.0 automation, pulling private network investment.
Market Restraints
- Equipment Certification Delays:BIS-aligned testing protocols for base station hardware extend vendor qualification timelines by six to nine months.
- Frequency Fragmentation:Non-contiguous spectrum blocks across 700 MHz, 2.6 GHz, and 3.5 GHz bands force multi-band radio complexity and higher unit costs.
- Copper Network Stranded Assets:Legacy fixed-line infrastructure in the Red River Delta generates maintenance drag as Voice over IP substitution accelerates.
Strategic Opportunities
- Central Highlands Connectivity Gap:Dak Lak and Gia Lai provinces show sub-40 percent broadband penetration, offering greenfield deployment potential.
- Enterprise Cloud Integration:Convergence of 5G edge computing with domestic data center expansion enables low-latency services for financial trading platforms.
- Cybersecurity Decree Tailwinds:Mandatory data localization requirements under national security frameworks favor domestic cloud and hosting providers.
Industry Challenges
- Radio Frequency Engineering Talent Scarcity:5G massive MIMO deployment requires specialized antenna design skills concentrated in Ho Chi Minh City.
- Multi-Vendor Interoperability:Disaggregated RAN architectures from Viettel Group and private operators create integration testing burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Telecom Market |
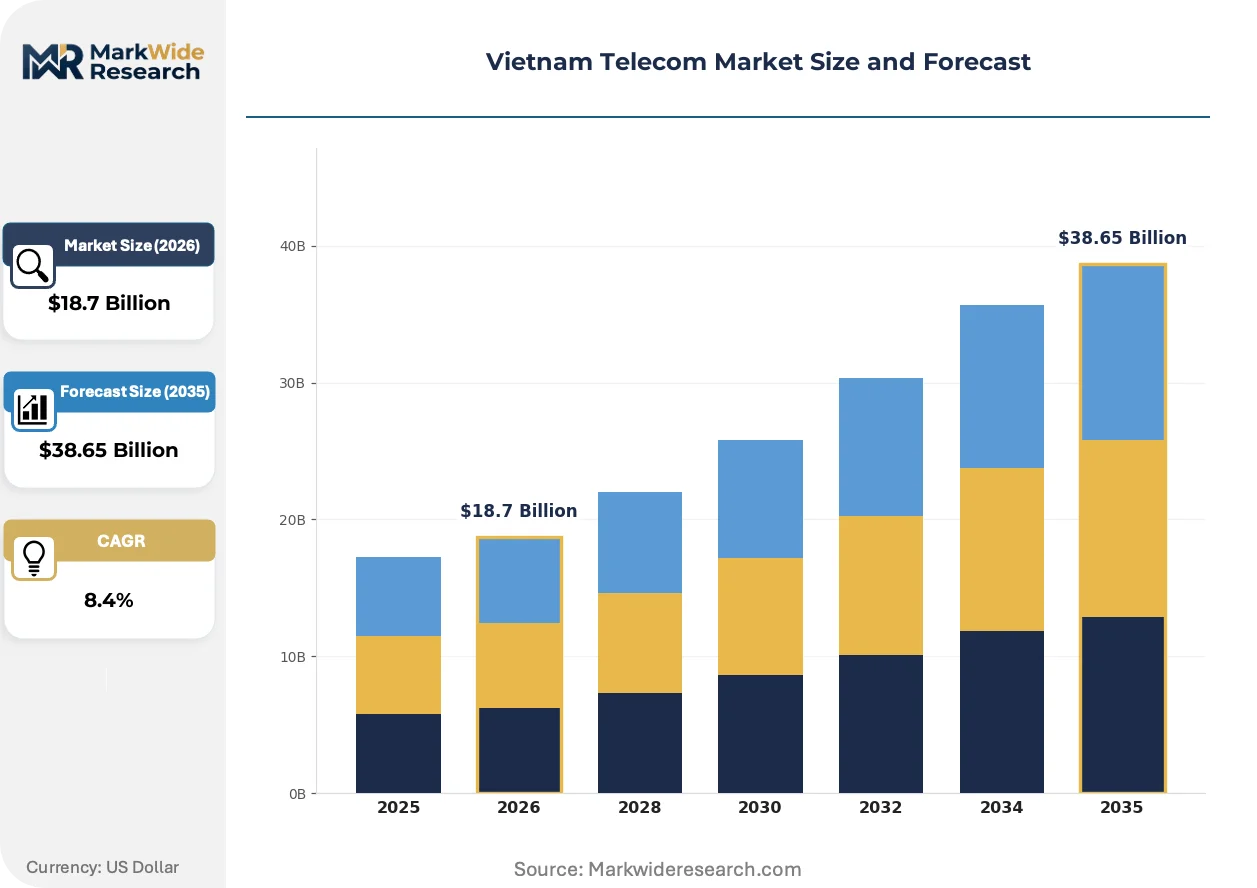
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed Line Services, Internet Services, Value-Added Services Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services Customer Type: Residential, Small and Medium Enterprises, Large Enterprises, Government Technology: 4G, 5G, Fiber Optics, Satellite |
| Companies Covered | Vietnamobile, FPT Corp., Viettel Group, Hanoi Telecom Corp., CMC Corp., VNPT Vinaphone, Gmobile, Saigon Postal and Telecommunications Services Joint Stock Co., Mobifone Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Telecom Market Strategic Shifts
Open RAN architectures are fragmenting vendor lock-in patterns while forcing incumbent equipment suppliers to unbundle hardware and software pricing. This shift is redistributing margin pools across the value chain.
Virtualized baseband units running on commodity servers are displacing proprietary hardware stacks in greenfield 5G deployments. Viettel Group is piloting disaggregated RAN in Hai Phong industrial zones. The move is displacing traditional integrated radio vendors from core network contracts.
The Ministry of Information and Communications is tightening domestic content requirements for infrastructure procurement. Foreign suppliers must now partner with local manufacturers for final assembly. Equipment vendors are responding by relocating printed circuit board fabrication to Bac Ninh province.
Enterprise buyers in Ho Chi Minh City are unbundling connectivity from managed services. Large manufacturers now source raw bandwidth and layer security and monitoring from specialized software vendors. This pattern is most visible among export-oriented electronics assemblers seeking direct cloud interconnection.
Vietnam Telecom Market Segmentation
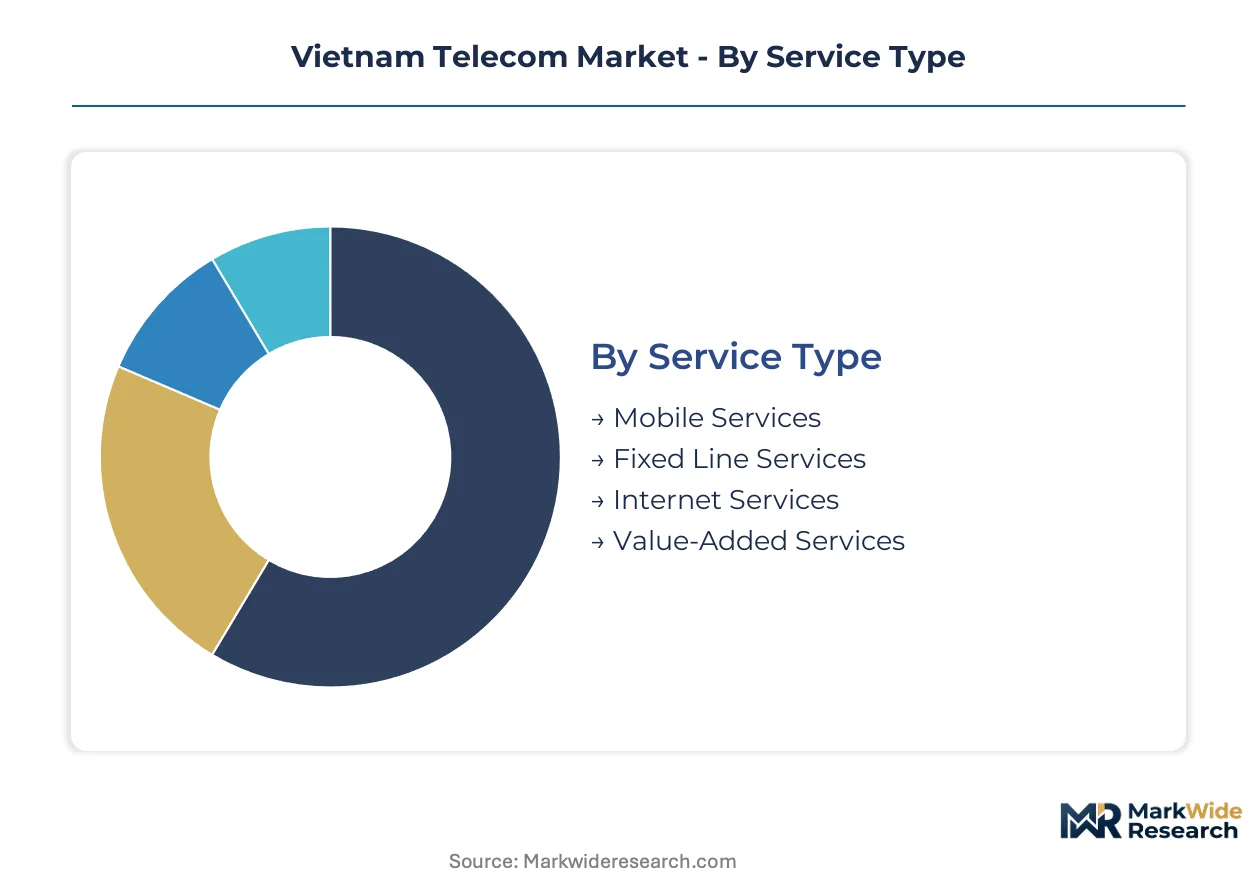
Vietnam's telecom segmentation reflects channel fragmentation between consumer retail, direct enterprise sales, and government procurement corridors. Each category carries distinct margin profiles and regulatory exposure that shape operator investment priorities.
Service Type:
Channel mix varies sharply: Mobile Services flow through retail storefronts and digital wallets, Fixed Line Services depend on direct technician deployment, while Value-Added Services route through enterprise solution teams.
- Mobile Services:Voice and data subscriptions delivered over cellular infrastructure with prepaid dominance in rural provinces. Ho Chi Minh City and the Red River Delta corridor concentrate ARPU growth as smartphone penetration crosses threshold levels in secondary cities. The National Digital Transformation Program mandates universal coverage that sustains baseline demand.
- Internet Services:Broadband access spanning fiber-to-the-home and fixed wireless configurations. Dak Lak and Gia Lai provinces show sub-forty percent penetration, creating greenfield deployment potential where mobile financial services adoption is accelerating among rural consumers.
- Fixed Line Services:Legacy copper and Voice over IP voice connectivity. Maintenance drag intensifies in the Red River Delta as substitution accelerates.
- Value-Added Services:Cloud hosting, cybersecurity, and managed solutions layered atop core connectivity. Large Enterprises generate disproportionate margin contribution relative to revenue share.
By volume, Mobile Services leads. By growth pace, Internet Services is expanding most quickly.
Deployment Model:
Cost tier separation defines this category: Cloud-Based and Managed Services command premium pricing, while On-Premises solutions compete on capital efficiency for budget-constrained buyers.
- Cloud-Based:Infrastructure and software delivered via remote data centers with subscription economics. Financial trading platforms in Ho Chi Minh City are driving low-latency edge computing demand that converges with domestic data center expansion.
- Managed Services:Outsourced network operations and security monitoring with SLA-backed performance. Government and defense contracts where security clearance creates barriers anchor procurement volume.
- On-Premises:Customer-owned hardware and software stacks requiring dedicated IT staff. Manufacturing clusters near Hai Phong and Bac Ninh favor this model for Industry 4.0 automation control.
- Hybrid:Split workloads across private infrastructure and public cloud resources. Export-oriented electronics assemblers seeking direct cloud interconnection are unbundling connectivity from managed services.
By revenue concentration, Managed Services dominates government verticals. By expansion trajectory, Cloud-Based is gaining share fastest.
Customer Type:
Application intensity separates segments: Residential consumption centers on entertainment and payments, while Large Enterprises and Government drive infrastructure-grade reliability requirements.
- Residential:Individual consumers purchasing voice, data, and content services. Rural wallet-based payment adoption is pulling smartphone penetration and data consumption in previously underbanked districts.
- Large Enterprises:Multinational and domestic corporations requiring dedicated connectivity and integrated solutions. Mandatory data localization under national security frameworks favors domestic cloud and hosting providers.
- Small and Medium Enterprises:Mid-scale businesses sourcing standardized connectivity packages with limited customization. Bac Ninh province industrial zones show concentrated demand for bundled internet and voice.
- Government:State agencies and defense entities with security-cleared procurement processes. Mobifone Corporation anchors position here where clearance requirements exclude non-incumbent competition.
By subscriber count, Residential leads. By value per connection, Large Enterprises is climbing the fastest.
Technology:
Maturity gradient structures competitive dynamics: 4G and Fiber Optics represent deployed base, while 5G and Satellite capture incremental investment for specialized applications.
- 5G:Next-generation cellular delivering network slicing and massive IoT density. Industrial zones near Hai Phong and Bac Ninh are requesting dedicated slices for Industry 4.0 automation, pulling private network investment.
- Fiber Optics:Glass-core transmission infrastructure with backhaul requirements exceeding 100 Gbps per node. The Ministry of Information and Communications requires fiber-to-the-home coverage expansion into secondary provinces, creating guaranteed demand pools.
- 4G:Mature LTE infrastructure covering population centers with diminishing upgrade cycles. Spectrum scarcity in the 3.5 GHz band is intensifying competitive pressure on equipment sourcing strategies for next-generation overlay.
- Satellite:Orbital and high-altitude platform connectivity for remote geography. Central Highlands provinces with sub-forty percent broadband penetration represent addressable gaps where terrestrial deployment remains uneconomic.
By installed base, Fiber Optics leads. By deployment momentum, 5G shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City and the Red River Delta corridor concentrate high-value enterprise demand while rural provinces drive mobile financial services adoption through wallet-based payments. This geographic split creates divergent infrastructure investment profiles across Vietnam's telecom landscape.
Ho Chi Minh City Metro
Financial trading platforms and export-oriented electronics assemblers demand low-latency edge computing and direct cloud interconnection. The Ministry of Information and Communications enforces mandatory data localization under national security frameworks. District 7 and Thu Duc City host concentrated data center expansion where enterprises unbundle connectivity from managed services.
Red River Delta
Voice over IP substitution accelerates across legacy copper networks while fiber-to-the-home deployment targets secondary provinces. Vietnam's National Digital Transformation Program mandates universal broadband coverage expansion. Bac Ninh province industrial zones request dedicated 5G network slices for Industry 4.0 automation control.
Central Highlands
Dak Lak and Gia Lai provinces exhibit sub-forty percent broadband penetration with mobile financial services adoption accelerating among rural consumers. Spectrum allocation policies from the Vietnam Telecommunications Authority shape coverage obligations for underserved geography. Satellite connectivity addresses gaps where terrestrial deployment remains uneconomic.
Hai Phong Industrial Zone
Manufacturing clusters request private 5G network investment for automation and quality control systems. BIS-aligned equipment certification protocols extend vendor qualification timelines for base station hardware. Viettel Group pilots disaggregated RAN architectures in this corridor, displacing traditional integrated radio vendors.
Vietnam Telecom Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Vietnam's telecom structure. State-backed operators leverage defense-linked procurement channels and security clearance requirements to anchor government verticals. Private challengers compete through cloud data center integration and enterprise software layering. Dominant competitive moves include vertical integration into network equipment sourcing and strategic partnerships for Open RAN deployment.
Within the integrated operator tier, Viettel Group and Mobifone Corporation exemplify state-linked market presence. FPT Corp. occupies a position among private challengers with enterprise-focused diversification. These three anchors represent divergent strategic archetypes: defense-integrated infrastructure control, security-cleared government contracting, and vertical integration into digital services.
| Leading Market Players |
|---|
| Vietnamobile |
| FPT Corp. |
| Viettel Group |
| Hanoi Telecom Corp. |
| CMC Corp. |
| VNPT Vinaphone |
| Gmobile |
| Saigon Postal and Telecommunications Services Joint Stock Co. |
| Mobifone Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term equipment procurement contracts with Viettel Group and Mobifone Corporation lock in multi-year supply access while providing price visibility for base station hardware and fiber infrastructure. These arrangements shield vendors from spot-market volatility in semiconductor components while committing operators to predictable capex profiles across the National Digital Transformation Program rollout.
Pricing Analysis
Managed service contracts and extended cybersecurity SLAs now drive lifetime value beyond raw connectivity sales. Three-tier pricing structure across premium, standard, and economy levels separates government-grade encrypted services from consumer prepaid bundles. Price differentiation hinges on BIS-aligned certification tiers and geographic deployment density. Cost compression in rural fiber-to-the-home builds is intensifying because of terrain complexity and lower ARPU density. Small and medium enterprises in Bac Ninh province show highest price sensitivity, while defense and government buyers absorb premium tiers without volume negotiation.
Supply Chain Analysis
Inventory buffers for massive MIMO antennas and baseband units now stretch six to nine months due to BIS certification backlogs. Equipment sourcing concentrates in China, South Korea, and domestic Vietnamese assembly plants near Bac Ninh. Raw material dependencies span gallium nitride semiconductors, high-purity optical fiber, and lithium-ion backup power systems. Single-source vulnerability sits with advanced radio frequency components from limited qualified vendors. Distribution runs through state-operator procurement corridors and direct enterprise solution teams rather than open channel markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
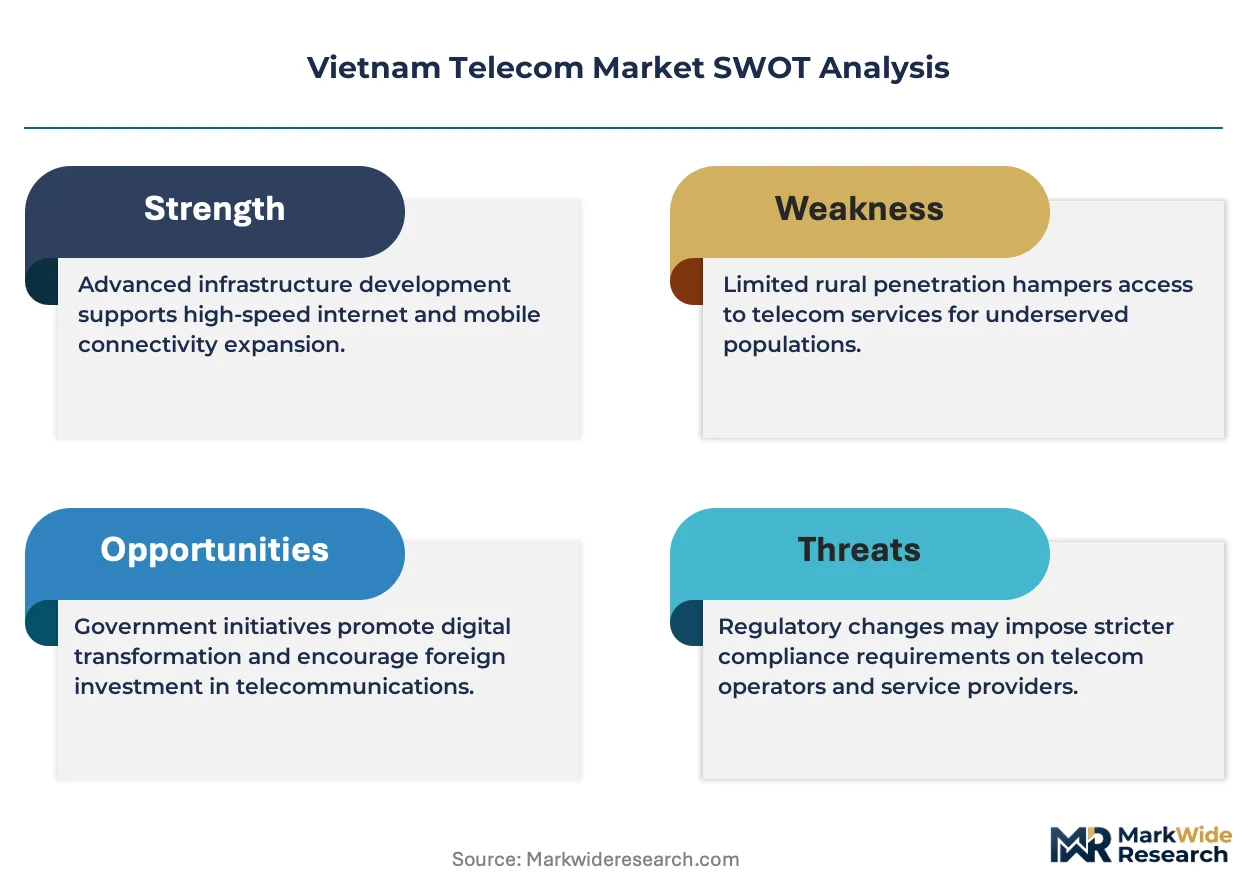
Vietnam's telecom market reads as a service-attach opportunity where cloud hosting and cybersecurity layers expand faster than underlying connectivity hardware. Recurring revenue from data localization compliance and managed security now outpaces subscriber growth economics.
For Market Incumbents: Shield government verticals through accelerated security clearance investments before cybersecurity decree enforcement tightens. Consolidate equipment sourcing leverage by expanding captive R&D into Open RAN software stacks. The threat of disaggregated vendor architectures from private operators demands faster vertical integration into baseband processing silicon.
For New Entrants and Emerging Players: BIS fast-track certification for printed circuit board assembly partners offers the fastest path to infrastructure contract eligibility. White-space targets center on Central Highlands satellite-to-fiber hybrid deployments and Hai Phong industrial zone private 5G slices. Go-to-market positioning should lead with edge computing integration for financial trading platforms in Ho Chi Minh City rather than competing on raw bandwidth.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic cloud operators with mandatory data localization contracts already in force. Long-term viability over the coming decade rests on regulatory capture through security clearance relationships rather than spectrum scale alone. The signal to watch is Ministry of Information and Communications spectrum auction structure favoring new entrant balance sheets versus incumbent extension.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Deployment Partnership | Disaggregated architectures reduce vendor lock-in while forcing incumbent suppliers to unbundle hardware and software pricing layers. |
| Domestic Content Assembly Relocation | Foreign equipment vendors now relocate printed circuit board fabrication to Bac Ninh province to satisfy procurement requirements. |
| Edge Computing Data Center Expansion | Ho Chi Minh City financial platforms demand low-latency infrastructure that converges 5G with localized cloud resources. |
| Cybersecurity Compliance Certification | Mandatory data localization under national security frameworks creates recurring revenue streams for domestic hosting providers. |
| Industrial Zone Private Network Investment | Manufacturing clusters near Hai Phong request dedicated 5G slices for Industry 4.0 automation and quality control systems. |
Study Parameters
A standing panel of network infrastructure procurement managers, regulatory affairs specialists at the Ministry of Information and Communications, enterprise IT directors, and base station deployment engineers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from Vietnam Telecommunications Authority licensing records, BIS equipment certification databases, operator capex disclosures, and industrial zone development filings. Bottom-up subscriber and revenue modeling triangulated against top-down macroeconomic projections across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning service type, deployment model, customer vertical, and technology generation alongside geographic density tiers and regulatory compliance clusters. CAGRs were derived from fitted growth curves applied to disclosed infrastructure deployment schedules and spectrum allocation timelines. Forecast inputs incorporated National Digital Transformation Program mandate pacing and mobile financial services adoption curves in rural provinces.
Decision-makers should treat outputs as directional under assumptions of continued state-backed operator dominance and stable cybersecurity decree enforcement; material deviation in spectrum auction structure or foreign vendor access policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
China ICT Market
Telecommunications
Norway Telecom Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
Indonesia B2B Telecom Market
Telecommunications
Germany Critical Communication Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Egypt Telecom Tower Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
France Telecom Market
Telecommunications
GPON Market
Telecommunications
Philippines Telecom Market
Telecommunications
Algeria Telecom Market