
 Supply Chain Management (SCM) Software Market | 2026-2036
Supply Chain Management (SCM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
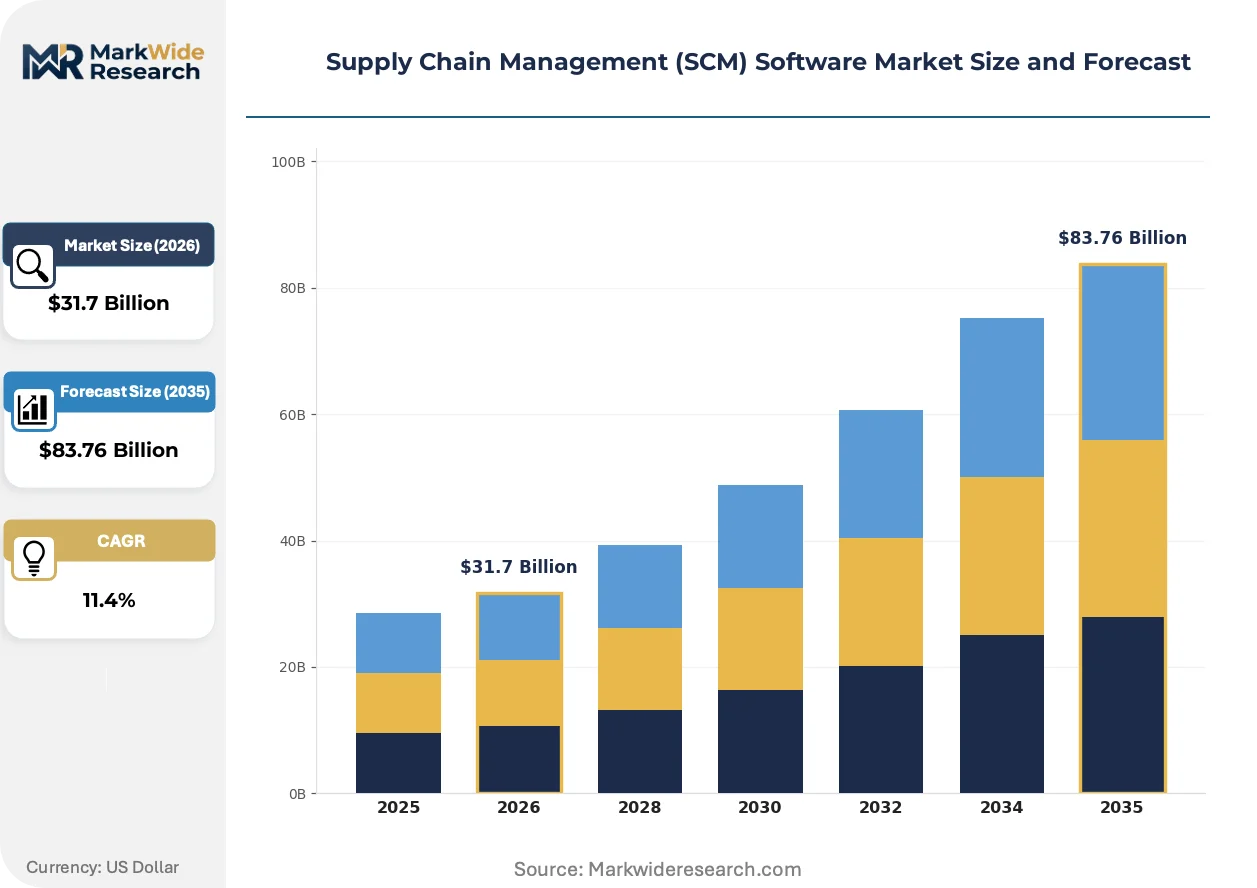
Supply Chain Management (SCM) Software Market Outlook
Pharmaceutical distribution is repositioning as a primary demand vertical for SCM software as cold-chain compliance requirements tighten. SAP leverages deep ERP integration to anchor enterprise deployments across European pharmaceutical networks. Kinaxis competes through concurrent planning engines that specialize in rapid scenario modeling for vaccine and biologics supply chains. Blue Yonder extends its position via AI-native demand forecasting that dominates retail replenishment workflows in North America.
Supply Chain Management software constitutes an integrated suite of applications that orchestrate material flows, information exchange, and financial settlement across multi-tier supplier networks, typically operating through API-driven architectures with sub-second refresh cycles for inventory telemetry. Its primary commercial purpose is to minimize working capital trapped in stock while maximizing order fulfillment rates against volatile demand patterns. Cloud-based deployment leads absolute growth as manufacturers abandon on-premises infrastructure for elastic compute capacity, while demand forecasting functionality captures disproportionate R&D investment as probabilistic models displace static safety-stock calculations. Supplier management solutions remain margin-dense due to the complexity of integrating external ERP instances across heterogeneous technology stacks.
The EU AI Act and FDA 21 CFR Part 11 requirements are reshaping vendor development roadmaps by mandating explainable algorithms and electronic record integrity in validated environments. GDPR cross-border data transfer restrictions complicate cloud hosting architectures for European manufacturers with Asian supplier bases. ISO 28000 supply chain security standards further filter market access for platforms serving defense and aerospace contractors. Stakeholders must evaluate whether their vendor's compliance investments match the regulatory trajectory of their highest-growth end-use verticals.
Market Dynamics
Cloud-native architectures are absorbing enterprise workloads as pharmaceutical and automotive manufacturers abandon rigid on-premises infrastructure for elastic, API-driven supply chain orchestration platforms.
Growth Catalysts
- EU AI Act compliance mandates:Pharmaceutical manufacturers now require algorithmic transparency in demand forecasting modules, forcing vendors to embed explainable AI capabilities that validate cold-chain integrity predictions.
- Automotive tiered-network visibility:German OEMs demand real-time supplier telemetry across multi-tier networks, pulling concurrent planning engines into production environments.
- API-driven inventory telemetry:Sub-second refresh cycles for stock visibility are compressing safety-stock calculations and minimizing working capital traps across European distribution networks.
Market Restraints
- GDPR cross-border friction:European manufacturers with Asian supplier bases face architectural constraints on cloud hosting configurations, complicating unified platform deployments.
- Validation environment costs:FDA 21 CFR Part 11 requirements for electronic record integrity impose substantial capital intensity on software vendors serving pharmaceutical distribution.
- Legacy ERP heterogeneity:Supplier management solutions struggle with integration complexity across incompatible technology stacks, inflating implementation timelines and professional services dependency.
Strategic Opportunities
- Biologics supply chain specialization:Vaccine and cell-therapy logistics create white space for scenario-modeling engines that handle temperature excursion protocols and shelf-life constraints.
- Defense contractor certification:ISO 28000 supply chain security standards filter market access, creating protected positions for platforms achieving aerospace-grade validation.
- AI-native demand forecasting convergence:Probabilistic models combining machine learning with real-time POS data are displacing static replenishment workflows in North American retail networks.
Industry Challenges
- Concurrent planning talent scarcity:Vendors struggle to hire supply chain scientists capable of modeling multi-echelon optimization across pharmaceutical and automotive verticals simultaneously.
- Regulatory timeline compression:The EU AI Act's phased implementation demands rapid algorithmic re-engineering, stretching R&D resources across compliance and innovation roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supply Chain Management (SCM) Software Market |
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $83.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Subscription End User: Manufacturers, Distributors, Retailers, Logistics Providers Solution: Inventory Management, Order Management, Supplier Management, Analytics Functionality: Demand Forecasting, Transportation Management, Procurement, Visibility |
| Companies Covered | Kinaxis, Microsoft Dynamics, Blue Yonder, Infor Nexus, o9 Solutions, SAP, Manhattan Associates, E2open, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supply Chain Management (SCM) Software Market Strategic Shifts
Digital twin architectures and explainable AI are compressing decision cycles across supply chain planning, while regulatory pressure on algorithmic accountability rewrites vendor development priorities.
Digital twin technology is absorbing simulation workloads previously handled by static spreadsheet models. Automotive manufacturers in Germany deploy virtual replicas of tiered supplier networks to stress-test disruption scenarios before physical inventory moves. This capability is absorbing market share from legacy APS systems that cannot model concurrent material and capacity constraints in real time.
The EU AI Act's risk-classification framework for algorithmic decision-making imposes documentation and audit-trail requirements on demand forecasting modules. Vendors must now expose model logic to regulatory scrutiny, reshaping R&D investment toward interpretability rather than pure predictive accuracy. Pharmaceutical distribution networks face the steepest compliance burden, as cold-chain integrity predictions fall under high-risk system definitions.
Buyer procurement patterns are compressing vendor evaluation cycles from eighteen-month enterprise sales processes to six-month pilot-to-production timelines. Mid-market manufacturers now demand pre-configured industry templates rather than custom implementations, favoring platforms with vertical-specific data models. This shift is most visible in North American retail, where replenishment teams prioritize speed-to-value over deep customization.
Supply Chain Management (SCM) Software Market Segmentation
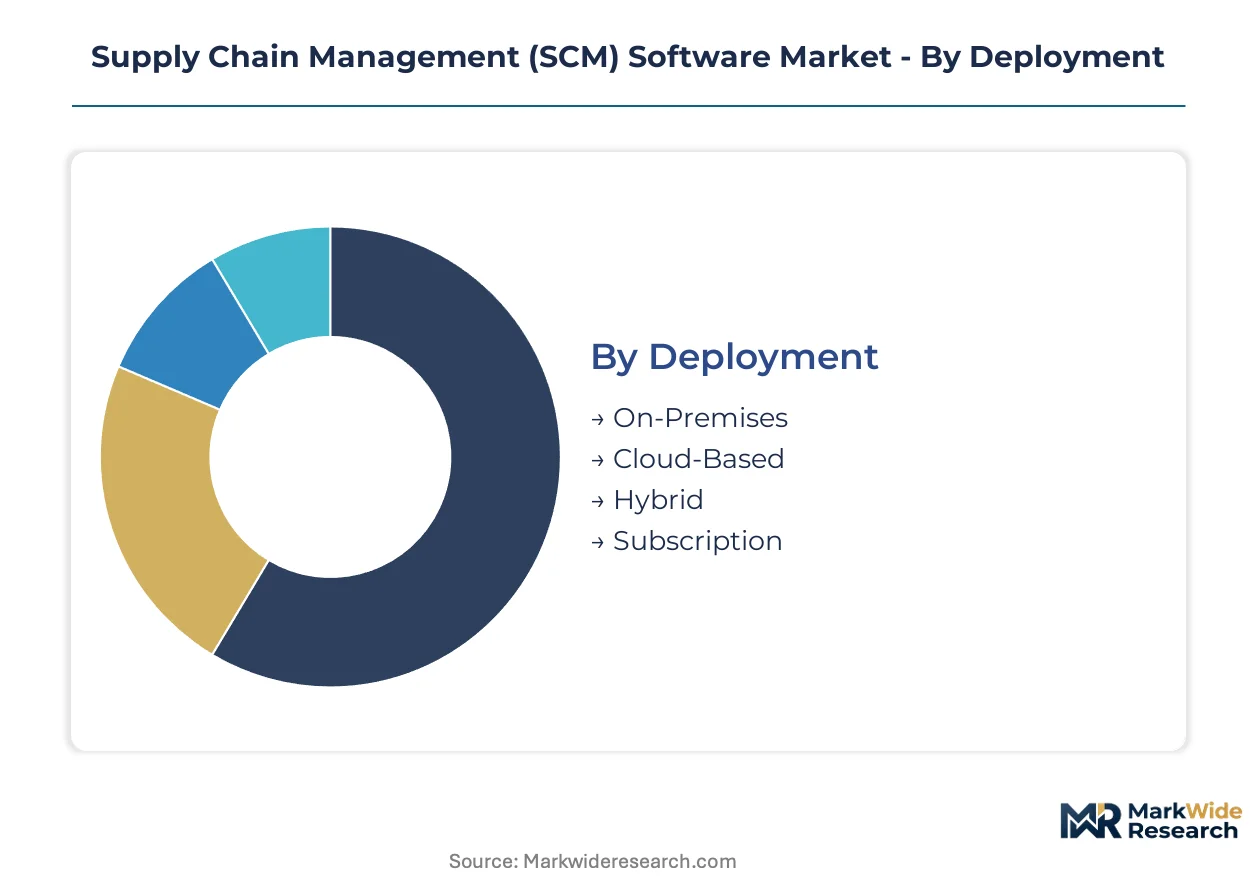
SCM software purchasing decisions hinge on deployment flexibility, end-user operational complexity, and regulatory validation requirements. Segmentation reveals where upgrade cycles concentrate and which solution categories command premium pricing.
Deployment:
Replacement cycles accelerate as manufacturers abandon rigid legacy infrastructure for consumption-based models with faster refresh cadences.
- Cloud-Based:Elastic compute architectures enable sub-second inventory telemetry refresh cycles without capital-intensive server procurement. Pharmaceutical manufacturers in Germany and automotive OEMs across Bavaria and Baden-Württemberg drive demand as they require real-time supplier visibility across tiered networks without on-premises maintenance overhead.
- On-Premises:Perpetual license deployments persist in validated environments where FDA 21 CFR Part 11 mandates direct control over electronic record infrastructure. Defense contractors and aerospace manufacturers with ISO 28000 security requirements retain on-site hosting to satisfy air-gapped operational constraints.
- Hybrid:Split architectures partition sensitive demand forecasting workloads on-site while pushing non-critical analytics to public cloud instances.
- Subscription:Consumption-based pricing models reduce upfront capital commitment for mid-market distributors with seasonal volume fluctuations.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest as manufacturers seek staged migration paths.
End User:
Operational maturity and supplier network complexity determine which end-user category captures disproportionate platform investment.
- Manufacturers:Multi-echelon production environments with concurrent material and capacity constraints require planning engines capable of modeling disruption scenarios. German automotive OEMs anchor this segment through tiered-network visibility mandates spanning hundreds of direct and indirect suppliers.
- Distributors:Cold-chain pharmaceutical distributors face EU AI Act algorithmic transparency requirements for demand forecasting modules that predict temperature excursion risks. Warehouse management integration with transportation optimization drives platform selection.
- Retailers:Replenishment teams prioritize AI-native demand forecasting combining machine learning with point-of-sale data streams.
- Logistics Providers:Third-party operators compete on asset utilization metrics, pulling visibility and transportation management functionality into unified control towers.
Manufacturers command the largest addressable spend, though Distributors expand most rapidly as cold-chain compliance tightens.
Solution:
Margin concentration tracks integration complexity and the difficulty of unifying data across heterogeneous ERP landscapes.
- Supplier Management:External ERP integration across incompatible technology stacks creates substantial professional services dependency and pricing power. The complexity of onboarding tier-2 and tier-3 automotive suppliers in Germany sustains premium implementation fees.
- Inventory Management:Real-time stock positioning with safety-stock optimization compresses working capital traps. Pharmaceutical networks leverage this capability to minimize spoilage exposure for temperature-sensitive biologics.
- Order Management:Omnichannel fulfillment orchestration unifies allocation logic across direct-to-consumer and wholesale channels.
- Analytics:Descriptive and diagnostic dashboards mature into predictive capabilities as explainable AI requirements reshape vendor roadmaps.
Supplier Management generates the highest margin per deployment, while Analytics gains share fastest as regulatory pressure elevates algorithmic accountability.
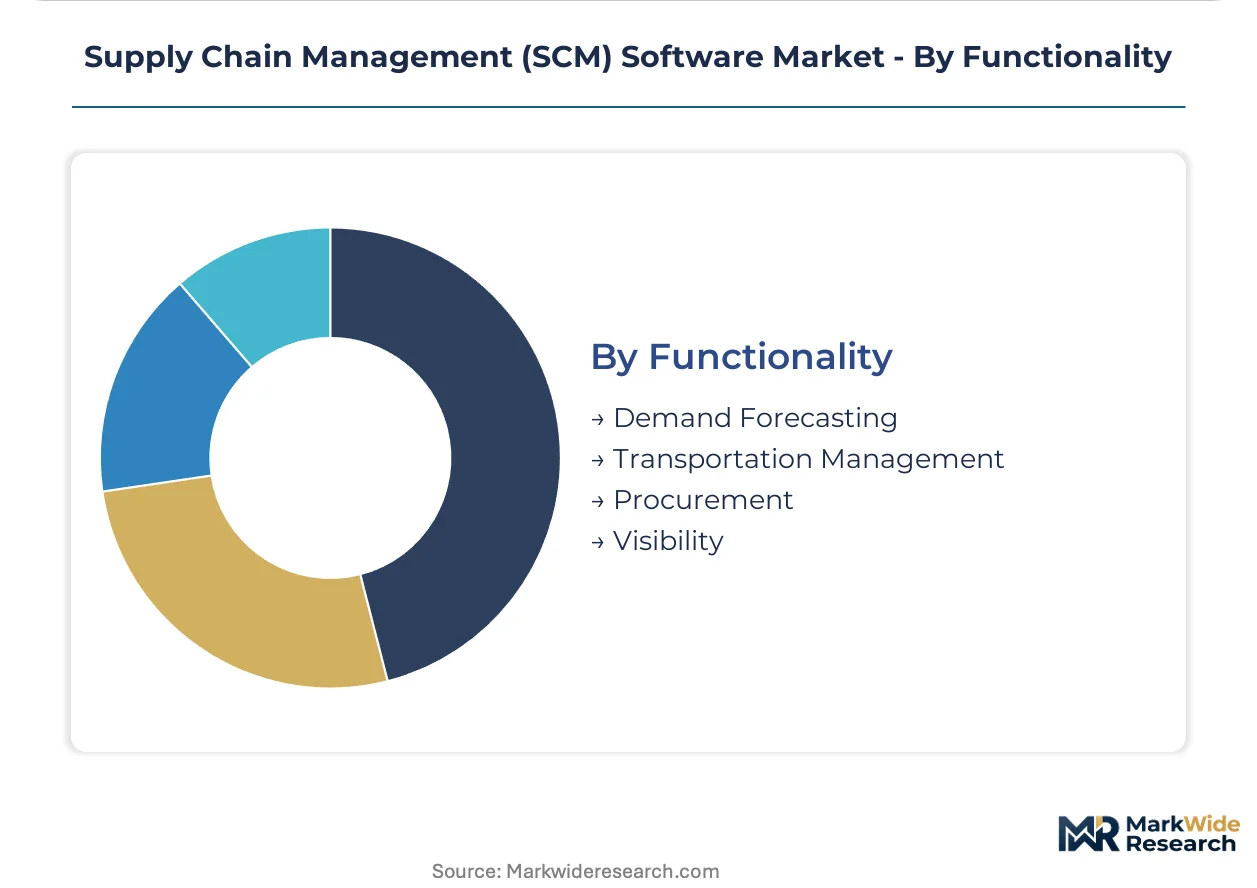
Functionality:
R&D investment disproportionately flows toward capabilities that reduce demand uncertainty and automate procurement decisions.
- Demand Forecasting:Probabilistic models displace static safety-stock calculations through machine learning pipelines processing real-time POS and supplier signals. The EU AI Act's high-risk system classification for cold-chain integrity predictions forces vendors to embed interpretability layers.
- Transportation Management:Dynamic route optimization and carrier selection reduce freight spend while meeting delivery window commitments. Retail networks in North America deploy this functionality to compress last-mile costs.
- Procurement:Strategic sourcing automation with supplier risk scoring integrates financial and operational data for contract negotiation leverage.
- Visibility:Control tower architectures aggregate telemetry across multi-tier networks into unified exception management workflows.
Demand Forecasting absorbs the largest development budget, with Visibility expanding most quickly as tiered-network mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting pharmaceutical and automotive SCM software procurement toward jurisdictions with harmonized compliance frameworks, as manufacturers seek to minimize dual-validation costs across the EU AI Act and FDA 21 CFR Part 11 requirements.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg mandate real-time tiered-network visibility spanning hundreds of direct and indirect suppliers. The EU AI Act's high-risk system classification pressures vendors to embed explainable AI into demand forecasting modules. Stuttgart's automotive cluster anchors concurrent planning engine deployments for multi-echelon optimization.
United States
FDA 21 CFR Part 11 requirements for electronic record integrity sustain on-premises deployments among pharmaceutical distributors with validated environments. Cold-chain compliance for biologics logistics pulls cloud-native SCM platforms into California's life sciences corridor. Boston's biotech cluster drives scenario-modeling specialization for temperature excursion protocols.
India
CDSCO's tightening cold-chain regulations for vaccine distribution accelerate cloud-based SCM adoption among pharmaceutical manufacturers. The PLI scheme for pharmaceuticals incentivizes supply chain digitization to meet export compliance standards. Hyderabad's vaccine manufacturing hub deploys real-time inventory telemetry to minimize spoilage exposure.
United Kingdom
Post-Brexit customs complexity drives demand for supplier management solutions that reconcile EU and UK regulatory divergences. The Medicines and Healthcare products Regulatory Agency's updated guidance on distribution GDP compliance elevates audit-trail requirements. London's pharmaceutical trading networks prioritize API-driven architectures for cross-border visibility.
Japan
METI's supply chain resilience initiatives promote digital twin adoption among automotive and electronics manufacturers. PMDA's pharmaceutical quality management standards align with international ICH guidelines, simplifying vendor validation processes. The Nagoya automotive cluster integrates concurrent planning engines to model disruption scenarios across tiered supplier networks.
Supply Chain Management (SCM) Software Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors seek to bridge capability gaps without absorbing full R&D burden. The market structure concentrates around three tiers: ERP-integrated incumbents with deep enterprise footprints, cloud-native specialists with concurrent planning engines, and AI-first challengers with probabilistic forecasting capabilities. Two competitive moves define positioning: vertical capability expansion into adjacent supply chain functions, and geographic co-development agreements with regional system integrators.
Within the ERP-integrated tier, SAP and Oracle exemplify platform consolidation strategies that embed SCM modules within broader enterprise suites. Kinaxis and Blue Yonder occupy the cloud-native specialist position, representing concurrent planning and AI-native forecasting archetypes respectively. o9 Solutions anchors the AI-first challenger segment, illustrating how probabilistic models displace static replenishment workflows.
| Leading Market Players |
|---|
| Kinaxis |
| Microsoft Dynamics |
| Blue Yonder |
| Infor Nexus |
| o9 Solutions |
| SAP |
| Manhattan Associates |
| E2open |
| Oracle |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical procurement teams in Germany and the United States now mandate explainable AI documentation as a standard vendor qualification criterion, forcing SCM platform providers to absorb compliance engineering costs that compress margin structures while elevating pricing for validated-environment deployments.
Pricing Analysis
Distributor margin layers in European pharmaceutical networks absorb substantial implementation complexity premiums, particularly for cold-chain compliance modules. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation depth and ERP integration scope. Pricing pressure stems from mid-market manufacturers demanding pre-configured industry templates with compressed six-month deployment timelines. Retail replenishment teams in North America exhibit highest price sensitivity, while German automotive OEMs prioritize concurrent planning capability over cost minimization.
Supply Chain Analysis
Reverse-logistics flows for cloud infrastructure hardware remain minimal in this intangible software market, though data center equipment refresh cycles in Ireland, the Netherlands, and Germany create secondary markets for decommissioned servers. Supply concentration centers on hyperscaler compute capacity in the United States, Ireland, and Germany, with platform development talent concentrated in India and Poland. Supply chain risk manifests through GDPR cross-border data transfer restrictions complicating unified hosting architectures. Distribution runs through direct enterprise sales teams and regional system integrators with vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's phased implementation through high-risk system classifications functions as a regulatory compounder, accelerating replacement cycles for demand forecasting modules across pharmaceutical and automotive verticals.
For Market Incumbents: Cement platform stickiness through deep ERP integration investments that raise switching costs for German automotive OEMs with tiered-network visibility mandates. Prioritize explainable AI R&D to defend against cloud-native challengers exploiting compliance timeline compression. Concurrent planning talent acquisition in Stuttgart and Boston anchors defensive positioning. For New Entrants and Emerging Players: Launch via vertical-specific pilot programs targeting mid-market pharmaceutical distributors in India seeking CDSCO-compliant cold-chain solutions. Biologics supply chain specialization offers penetrable white space, with scenario-modeling engines for temperature excursion protocols commanding premium positioning against generalized platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native forecasting specialists possessing validated-environment deployment experience. Long-term viability hinges on regulatory trajectory alignment across EU AI Act and FDA 21 CFR Part 11 frameworks. Watch for tiered-network visibility mandates expanding beyond automotive into aerospace and defense contractor procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Module Development | EU AI Act compliance creates validated-environment entry barriers for pharmaceutical networks. |
| Concurrent Planning Engine Acquisition | German automotive OEMs demand real-time multi-echelon optimization across tiered suppliers. |
| Vertical Template Pre-configuration | Mid-market buyers compress evaluation cycles from eighteen months to six-month deployments. |
| Regional System Integrator Partnership | European pharmaceutical networks require localized GDPR-compliant implementation expertise. |
| Cold-Chain Specialization Investment | Biologics logistics create protected positions for temperature excursion protocol expertise. |
Study Parameters
Bottom-up pharmaceutical and automotive manufacturer modeling reconciled against top-down cloud infrastructure capacity tracking forms the analytical core. Primary interviews with supply chain directors, IT procurement officers, platform engineers, and regulatory affairs specialists combined with secondary validation against FDA 21 CFR Part 11 guidance documents, EU AI Act implementation timelines, SEC software vendor filings, and hyperscaler capex disclosures. Triangulation between deployment data and end-user spending patterns ensures segmentation integrity.
Historical trendline analysis across deployment model adoption curves, functionality investment patterns, and regional regulatory implementation schedules informs projection frameworks. Segmentation dimensions span cloud-native versus on-premises architectures, enterprise versus mid-market organization size, pharmaceutical versus automotive versus retail verticals, and European versus North American versus Asia-Pacific adoption clusters. CAGRs derive from elasticity modeling of replacement cycle compression and compliance-driven upgrade mandates, with digital twin adoption velocity and explainable AI development timelines as key forecast inputs across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or prolonged FDA validation backlog conditions. Forecasts reflect documented assumptions regarding regulatory timeline adherence and enterprise cloud migration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Cloud Enterprise Resource Planning Market
Software & Services
Global Board Management Software Market
Software & Services
Pure Play Software Testing Market
Software & Services
Output Management Software Market
Software & Services
Global DevOps Software Market
Software & Services
Global PPC Software Market
Software & Services
Vending Software Market
Software & Services
Global Mindfulness Meditation Apps Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Shift Planning Software Market
Software & Services
Productivity Management Software Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Global Presentation Software Market
Software & Services
Global Catalog Management Systems Market
Software & Services
Global Policy Management Software Market
Software & Services
Enterprise Backup and Recovery Software Market