
 Thailand ICT Market | 2026-2036
Thailand ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand ICT Market Analytics
Market Context
Software-defined networking and edge computing integration is tilting enterprise architecture toward distributed, low-latency configurations across Thai commercial corridors. Cisco Systems Inc. dominates core routing and security infrastructure for large financial institutions in Bangkok and its surrounding economic zones. True Corporation leverages its converged telecom-media-technology platform to anchor enterprise connectivity bundles. Huawei Investment & Holding Co. Ltd competes aggressively on 5G base station deployment and government-backed smart city infrastructure tenders.
Technical Definition and Segment Structure
Thailand ICT encompasses information and communications technology systems including semiconductor-based hardware, licensed and open-source software, managed network services, and cloud-native infrastructure deployed across enterprise and public sector environments. Primary commercial purpose centers on data processing, transmission, storage, and analytics automation that reduces operational latency while scaling decision throughput. Hardware and infrastructure segments retain the largest revenue share due to ongoing data center construction and 5G network buildouts, though cloud computing services within the technology dimension are expanding fastest as enterprises exit legacy on-premises estates. The government end-user category absorbs substantial procurement volume through e-government and digital ID programs, while healthcare ICT spending is concentrating around hospital information system modernization and telemedicine platform integration.
Regulatory Environment and Outlook
The National Broadcasting and Telecommunications Commission governs spectrum allocation and telecommunications licensing, directly shaping market entry timelines for infrastructure vendors. The Personal Data Protection Act, enforced by the Personal Data Protection Committee, mandates data localization and cross-border transfer protocols that influence cloud deployment architecture decisions by AWS, Microsoft, and domestic providers. Thailand's Board of Investment augments this framework with tax incentives for digital investment zones in Eastern Economic Corridor provinces. Stakeholders must monitor how forthcoming cybersecurity certification requirements and critical infrastructure designation rules alter vendor qualification thresholds and procurement eligibility.
Market Dynamics
Enterprise cloud migration across Thai financial institutions is compressing procurement cycles and concentrating vendor relationships around integrated platform providers capable of delivering end-to-end infrastructure stacks.
Growth Catalysts
- National Digital Economy and Society Plan:Government-mandated digital transformation timelines accelerate public sector ICT procurement across e-government and digital ID programs.
- 5G spectrum allocation:The National Broadcasting and Telecommunications Commission's licensing framework enables network densification projects that drive base station and edge infrastructure deployment.
- Hospital information system modernization:Thai healthcare providers are replacing legacy patient management platforms with integrated electronic health record systems.
Market Restraints
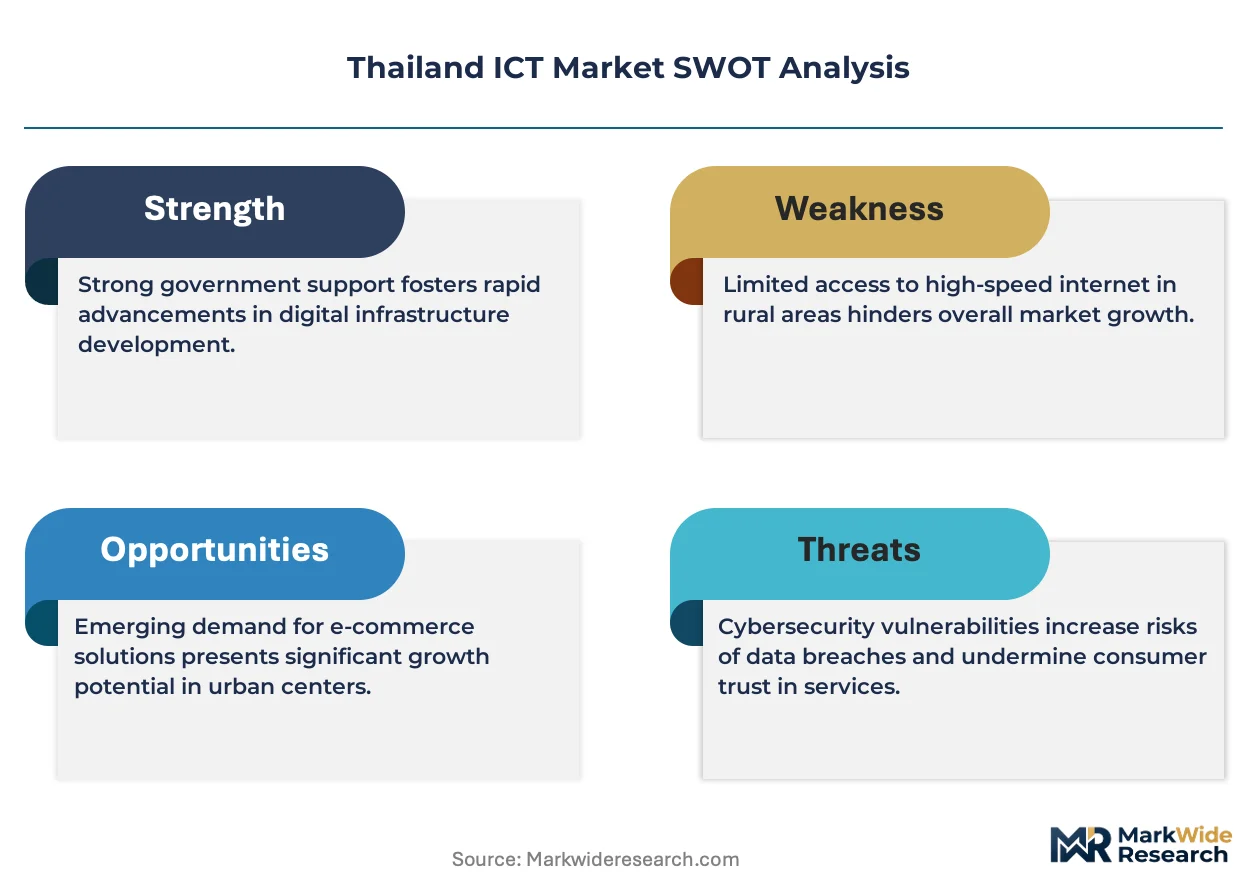
- Semiconductor supply concentration:Thailand's hardware-dependent ICT expansion faces input bottlenecks from concentrated East Asian chip fabrication capacity.
- Data localization mandates:The Personal Data Protection Act imposes cross-border transfer restrictions that inflate cloud architecture costs for multinational enterprises.
- Technical skills scarcity:Domestic talent pools lack depth in cloud-native DevOps and cybersecurity specializations required for enterprise transformation.
Strategic Opportunities
- Eastern Economic Corridor digital zones:Board of Investment tax incentives for data center and R&D facilities create landed cost advantages for infrastructure operators.
- Edge-AI convergence:Manufacturing and logistics sectors in Bangkok and surrounding provinces are piloting distributed inference workloads that demand low-latency compute placement.
- Smart city infrastructure:Municipal procurement frameworks in Bangkok prioritize integrated IoT, surveillance, and traffic management platforms.
Industry Challenges
- Legacy system integration complexity:Thai banks must maintain core banking system interoperability during multi-year cloud transitions.
- Cybersecurity certification timelines:Pending critical infrastructure designation rules threaten to delay vendor qualification and contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand ICT Market |
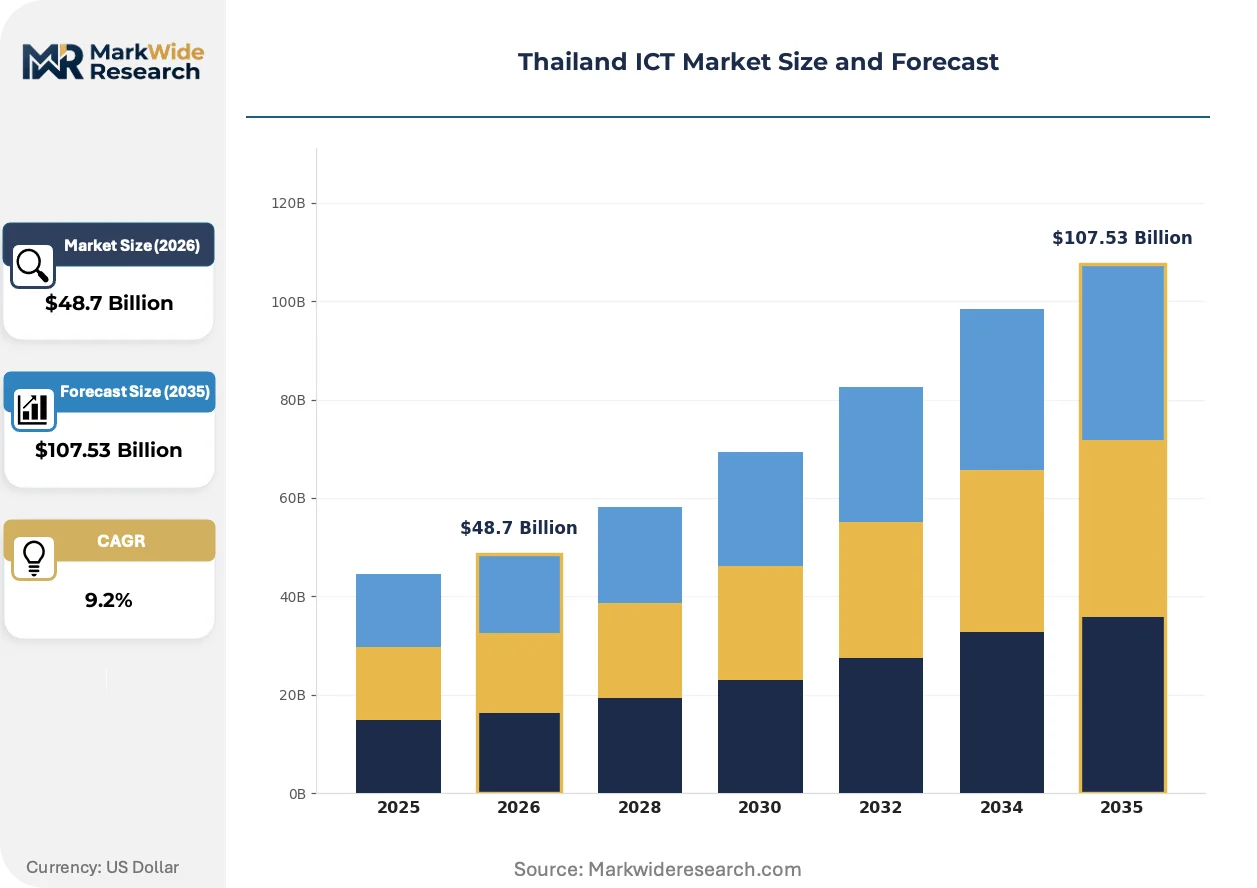
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $107.53 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Infrastructure End User: Government, Education, Healthcare, Enterprise Technology: Cloud Computing, Artificial Intelligence, Big Data, IoT Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Cisco Systems Inc., IBM Corporation, Dell Technologies Inc., Huawei Investment & Holding Co. Ltd, Amazon Web Services Inc., Advanced Info Service (AIS), True Corporation, Total Access Communication Public Company Limited (DTAC), Microsoft Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand ICT Market Evolving Landscape
Thailand's ICT architecture is pivoting toward distributed, software-defined configurations that collapse traditional boundaries between networking, compute, and storage layers. This structural reconfiguration is reshaping how enterprises procure, deploy, and operate technology infrastructure.
Software-defined wide area networking is migrating from pilot deployments to production environments across Thai retail and manufacturing supply chains. Mid-sized enterprises in the automotive and electronics sectors are adopting managed SD-WAN services to replace MPLS connectivity. This technology is migrating from cost-reduction rationale toward application-aware traffic engineering that prioritizes real-time operational systems.
The Personal Data Protection Act enforcement by the Personal Data Protection Committee is mandating data residency and breach notification protocols that alter cloud provider selection criteria. Multinational hyperscalers must establish Thai sovereign cloud instances or risk exclusion from public sector and regulated industry tenders. Financial services and healthcare verticals are driving demand for localized infrastructure that satisfies audit and compliance requirements.
Enterprise buyers are consolidating vendor relationships around platform providers capable of delivering integrated infrastructure, security, and managed services bundles. Discrete point-solution procurement is giving way to multi-year framework agreements with single-source accountability. This pattern is most pronounced among Thai banking groups and conglomerate holding companies with distributed subsidiary networks.
Thailand ICT Market Segmentation
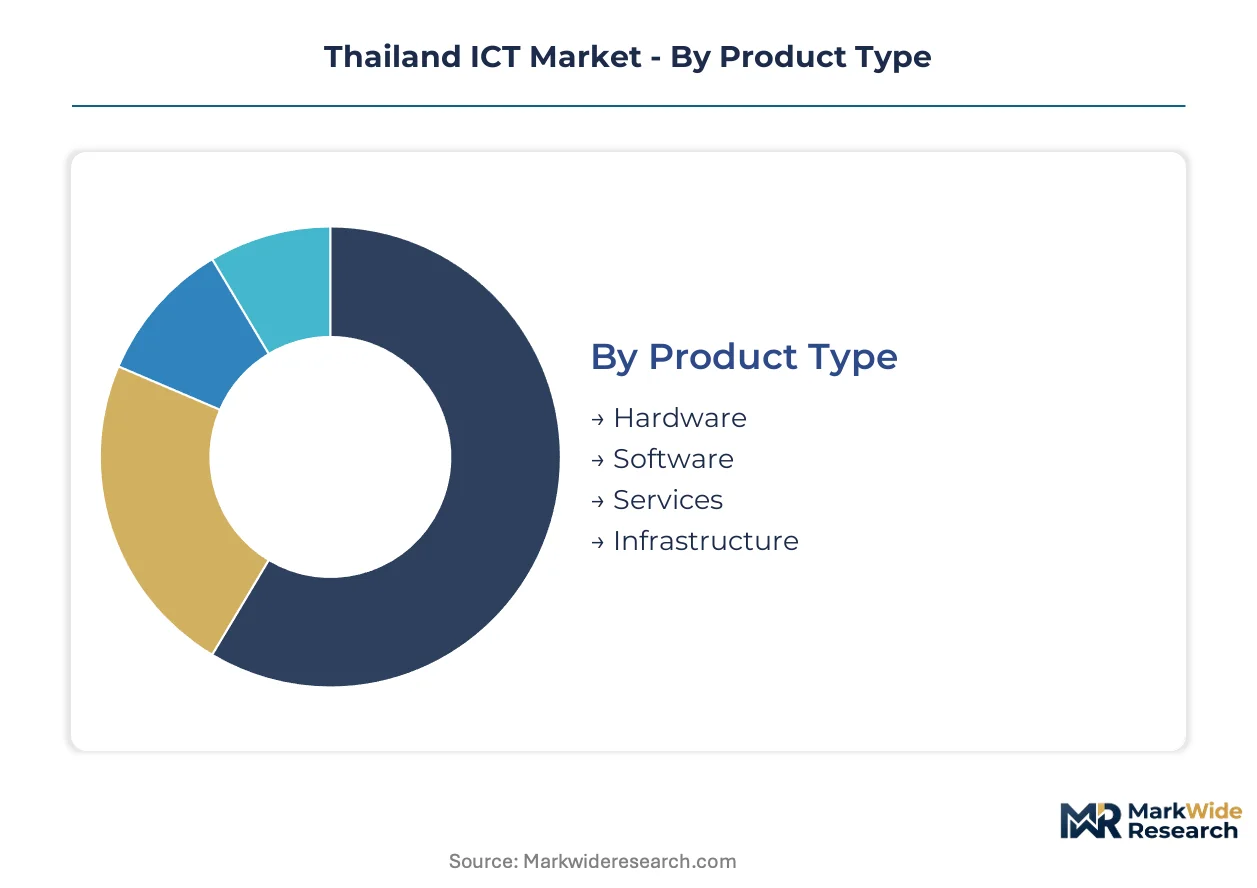
Thailand's ICT procurement patterns diverge sharply across product categories, end-user verticals, and deployment models. Understanding these fault lines reveals where vendor relationships consolidate and where integration complexity creates margin pressure.
Product Type:
After-sales service intensity varies dramatically across hardware, software, and services segments, with infrastructure assets demanding multi-year maintenance contracts while software shifts toward subscription-based support models.
- Hardware:Semiconductor-based equipment including servers, networking gear, and endpoint devices forms the procurement foundation for Thai data center buildouts. Demand concentrates among Bangkok-based financial institutions replacing legacy core banking infrastructure; the National Broadcasting and Telecommunications Commission's 5G licensing timeline accelerates base station procurement cycles.
- Software:Licensed enterprise applications and open-source platforms enable process automation across Thai manufacturing and logistics corridors. Hospital information system modernization in provincial healthcare networks drives electronic health record licensing volume; the Personal Data Protection Act mandates audit-compliant deployment architectures.
- Services:Systems integration and managed service contracts absorb substantial procurement spend as enterprises exit legacy estates. Thai conglomerates with distributed subsidiary networks favor single-source accountability for multi-year transformation programs.
- Infrastructure:Data center construction and edge compute placement dominate capital allocation in Eastern Economic Corridor provinces. Board of Investment tax incentives for digital zones create landed cost advantages for facility operators.
Hardware holds the largest share; momentum sits with Services as enterprises prioritize outcome-based procurement over asset ownership.
End User:
Cost tier differentiation separates premium enterprise deployments from standardized public sector tenders, with compliance requirements driving price stratification across verticals.
- Government:E-government platforms and digital ID programs absorb substantial budget allocation under the National Digital Economy and Society Plan. Procurement frameworks prioritize sovereign cloud instances and data residency compliance.
- Education:Learning management systems and campus connectivity upgrades concentrate demand among Bangkok metropolitan universities and vocational training institutes. Hybrid classroom infrastructure drives endpoint device refresh cycles.
- Healthcare:Integrated electronic health record systems and telemedicine platforms modernize patient management across provincial hospital networks. The Personal Data Protection Committee's breach notification protocols mandate secure deployment architectures.
- Enterprise:Banking groups and manufacturing conglomerates lead cloud migration spending, consolidating vendor relationships around integrated platform providers. Mid-sized automotive suppliers pilot edge-AI inference workloads for quality control automation.
Enterprise captures the dominant procurement volume; Healthcare is expanding most quickly as hospital information system replacement cycles accelerate nationwide.
Technology:
Application maturity separates production-ready deployments from pilot programs, with cloud infrastructure reaching mainstream adoption while artificial intelligence remains concentrated in proof-of-concept environments.
- Cloud Computing:Hyperscale infrastructure and sovereign cloud instances enable enterprise workload migration across Thai financial services and retail sectors. AWS, Microsoft, and domestic providers compete for public sector tenders requiring data localization compliance.
- Artificial Intelligence:Machine learning platforms and natural language processing tools pilot in manufacturing quality control and customer service automation. Technical skills scarcity in cloud-native DevOps specializations constrains production deployment timelines.
- Big Data:Analytics platforms process operational telemetry from IoT sensor networks in Bangkok smart city corridors. Municipal procurement frameworks prioritize integrated data visualization and predictive maintenance capabilities.
- IoT:Connected device networks support traffic management, environmental monitoring, and industrial asset tracking across Eastern Economic Corridor manufacturing zones. Edge gateway deployment accompanies 5G network densification projects.
Cloud Computing holds the largest share; momentum sits with IoT as smart city infrastructure tenders concentrate procurement volume among integrated service providers.
Deployment:
Customer type segmentation separates regulated industries with mandatory on-premises requirements from agile enterprises adopting cloud-native architectures.
- On-Premises:Legacy core banking systems and patient management platforms persist in highly regulated Thai financial and healthcare institutions. Interoperability requirements during multi-year cloud transitions maintain capital allocation to owned infrastructure.
- Cloud-Based:SaaS applications and hyperscale infrastructure services displace on-premises estates among retail, logistics, and professional services firms. Subscription economics reduce upfront capital requirements for mid-sized enterprises.
- Hybrid:Split workload architectures balance sensitive data residency with elastic compute scalability. Thai conglomerates with distributed subsidiary networks favor hybrid models maintaining control over critical systems while outsourcing commodity workloads.
- Managed Services:Outsourced infrastructure operations and security monitoring address technical skills scarcity in domestic talent pools. Single-source accountability for end-to-end stack delivery reduces vendor management overhead.
On-Premises retains substantial installed base; Cloud-Based is gaining share fastest as procurement cycles compress and vendor relationships consolidate around integrated platform providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers across Thai commercial corridors concentrate procurement decisions in Bangkok-based banking groups and Eastern Economic Corridor manufacturing conglomerates, with vendor selection criteria tightening around integrated platform capabilities and sovereign cloud compliance.
Central Thailand and Bangkok Metropolitan Region
Financial institutions and conglomerate headquarters drive premium infrastructure procurement across core banking modernization and enterprise resource planning deployments. The National Digital Economy and Society Plan mandates e-government platform integration that channels public sector spending through centralized procurement frameworks. Smart city infrastructure tenders in Bangkok prioritize integrated IoT, surveillance, and traffic management platforms from vendors with sovereign cloud instances.
Eastern Economic Corridor
Manufacturing conglomerates and logistics operators pilot edge-AI inference workloads for quality control automation alongside 5G-enabled industrial asset tracking. Board of Investment tax incentives for digital investment zones reduce landed costs for data center and R&D facility operators establishing regional compute nodes. Provincial hospital networks in Chonburi and Rayong modernize patient management platforms under centralized healthcare ICT budgets.
Northern Thailand
Automotive suppliers and electronics contract manufacturers adopt managed SD-WAN services to replace legacy MPLS connectivity across dispersed production facilities. The Personal Data Protection Act drives demand for localized infrastructure among provincial healthcare providers upgrading electronic health record systems. Chiang Mai's emerging digital services cluster attracts mid-sized enterprises seeking lower-cost cloud migration alternatives to Bangkok-centric providers.
Northeastern Thailand
Agricultural processing and logistics firms deploy IoT sensor networks for supply chain visibility under provincial smart agriculture initiatives. Technical skills scarcity in cloud-native DevOps specializations constrains production deployment timelines for regional enterprises. Khon Kaen anchors demand for campus connectivity upgrades and learning management systems among vocational training institutes.
Southern Thailand
Port operators and maritime logistics providers invest in edge compute placement for real-time cargo tracking and customs automation. Tourism sector recovery drives hotel chain procurement of guest-facing digital service platforms and property management system modernization. Phuket and Surat Thani concentrate hospitality ICT spending among integrated service providers capable of delivering end-to-end infrastructure stacks.
Thailand ICT Market Competitive Landscape
Channel-controlling players compete with product-specialist players across converged infrastructure and managed services categories, with procurement consolidation favoring integrated platform providers capable of single-source accountability. The vendor base spans three strategic tiers: global hyperscalers with sovereign cloud offerings, regional telecom-media-technology conglomerates with converged connectivity bundles, and specialized infrastructure vendors competing on 5G base station deployment and security certification. Dominant competitive moves include strategic partnerships between hardware manufacturers and domestic service providers, alongside portfolio diversification into edge-AI and smart city solution stacks.
Within the infrastructure-specialist tier, Cisco Systems Inc. and Huawei Investment & Holding Co. Ltd occupy positions exemplifying divergent approaches to core routing and 5G deployment. True Corporation anchors the regional telecom-media-technology category, representing the converged platform model that enterprise buyers increasingly favor for bundled connectivity and managed services procurement. These three companies illustrate the competitive fault lines between Western-certified infrastructure and regionally-integrated service delivery models that shape vendor qualification thresholds in Thai public sector tenders.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| IBM Corporation |
| Dell Technologies Inc. |
| Huawei Investment & Holding Co. Ltd |
| Amazon Web Services Inc. |
| Advanced Info Service (AIS) |
| True Corporation |
| Total Access Communication Public Company Limited (DTAC) |
| Microsoft Corporation |
| Others |
Value Network & Pricing Analysis
Undercapacity in Taiwan and South Korea semiconductor fabrication is tightening component availability across Thai data center buildouts, compressing supplier margins while inflating long-term contract premiums for enterprise buyers.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate hardware procurement for Thai banking infrastructure. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified equipment separates multinational vendor offerings from regional alternatives. Pricing pressure stems from the Personal Data Protection Act's data localization mandates, which inflate sovereign cloud deployment costs. Mid-sized enterprises in provincial manufacturing zones exhibit highest price sensitivity, while Bangkok financial institutions prioritize compliance over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Thai banking groups are easing working capital constraints for domestic systems integrators. Component sourcing draws from Taiwan, South Korea, and China for semiconductors, networking gear, and server assemblies. Single-source vulnerability concentrates in advanced node chip fabrication. Distribution runs through Bangkok-based value-added resellers and Eastern Economic Corridor logistics hubs serving manufacturing conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment models and compliance tiers creates niche opportunities for specialized vendors as Thai enterprises diverge between sovereign cloud mandates and agile cloud-native architectures.
For Market Incumbents: Harden sovereign cloud certification pipelines to defend public sector eligibility against emerging domestic providers. Deepen backward integration into edge compute hardware to offset semiconductor supply volatility. Prioritize multi-year framework agreements with Bangkok banking groups consolidating vendor relationships. For New Entrants and Emerging Players: Provincial hospital networks in Northeastern Thailand represent the most penetrable entry point for electronic health record modernization underserved by incumbent platforms. Mid-market manufacturing conglomerates in the Eastern Economic Corridor seek alternatives to Bangkok-centric managed service providers. Partner with domestic systems integrators possessing existing National Digital Economy and Society Plan accreditation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers with multi-year public sector contracts. Long-term viability favors vendors with sovereign cloud infrastructure and critical infrastructure cybersecurity certification pathways. Monitor National Broadcasting and Telecommunications Commission 5G spectrum reallocation timelines as inflection indicator for edge infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Personal Data Protection Committee compliance enables public sector tender participation. |
| Edge-AI Platform Integration | Manufacturing quality control automation pilots in Eastern Economic Corridor drive demand. |
| Smart City Infrastructure Partnership | Bangkok municipal tenders prioritize integrated IoT and traffic management capabilities. |
| Managed SD-WAN Service Launch | Automotive suppliers in Northern Thailand replace legacy MPLS connectivity. |
| Hospital Information System Modernization | Provincial healthcare networks accelerate electronic health record deployment timelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Thai ICT procurement officers, cloud architects, and systems integration leads; and secondary validation through National Broadcasting and Telecommunications Commission licensing records, Board of Investment digital zone disclosures, and hyperscaler sovereign cloud announcements. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Forecast inputs incorporated deployment model adoption curves, vertical-specific compliance timelines, and infrastructure investment patterns across the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, technology layer, and deployment architecture. CAGRs derived from elasticity-adjusted demand projections and supply-side capacity constraints.
Practitioners should monitor National Digital Economy and Society Plan budget allocation shifts and cybersecurity certification rule finalization for early signals. Forecasts reflect documented assumptions about spectrum allocation timelines and data center construction permits. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
LTE Base Station System Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
Global LTE Market
Telecommunications
Competitive Local Exchange Carriers (CLEC) Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
DECT System Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
Bahrain Telecom Market
Telecommunications
Indonesia Volte Market
Telecommunications
Sri Lanka Telecom Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Ghana Telecom Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Italy Telecom Market