
 United States Mobile Virtual Network Operator (MVNO) Market | 2026-2036
United States Mobile Virtual Network Operator (MVNO) Market Size, Share, and Industry Trends Forecast 2026-2036
United States Mobile Virtual Network Operator (MVNO) Market Analytics
Cost-conscious retail consumers is unwinding toward business and government buyers seeking managed mobility solutions. Metro by T-Mobile leverages its parent network infrastructure to dominate urban prepaid segments with aggressive pricing. Consumer Cellular specializes in senior demographics and sustains loyalty through simplified plans and US-based customer support. Mint Mobile competes on extended-duration pricing and positions itself as a digital-native challenger with minimal overhead.
A Mobile Virtual Network Operator rents wholesale network capacity from facilities-based carriers and resells wireless services under its own brand without owning physical spectrum or cell towers. These operators provision subscriber identity modules, manage billing systems, and negotiate roaming agreements while relying on host networks for radio access and core infrastructure. Prepaid service leads volume acquisition among price-sensitive subscribers, while 5G technology represents the fastest-growing connectivity tier as host carriers expand mid-band coverage. Business customer types command higher average revenue per user and anchor margin pools through multi-line accounts and managed service attachments.
The FCC governs wholesale access rates and net neutrality provisions that determine MVNO economic viability, while state public utility commissions enforce consumer protection standards on billing transparency and service quality. The National Telecommunications and Information Administration coordinates federal spectrum policy that indirectly shapes host carrier capacity available for wholesale leasing. Stakeholders must monitor pending FCC rulemakings on wholesale pricing reform and state-level efforts to mandate minimum service quality metrics for virtual operators reselling network access.
Market Dynamics
Wholesale network access economics are tightening as FCC spectrum reforms compress the margin between host carrier rates and retail pricing power for virtual operators.
Growth Catalysts
- 5G mid-band deployment:Host carriers expanding C-band coverage create surplus capacity for wholesale leasing, enabling MVNOs to offer differentiated speed tiers without infrastructure investment.
- FCC wholesale pricing reform:Pending rulemakings on access rate transparency aim to reduce arbitration costs and standardize interconnection terms for smaller resellers.
- Small and medium enterprise demand:Businesses with 50-500 employees are consolidating mobility spend under single-vendor managed service contracts that bundle device financing with flexible data pools.
Market Restraints
- Host carrier concentration:Three facilities-based networks control 98 percent of wholesale capacity, creating asymmetric bargaining power in rate negotiations.
- Spectrum scarcity in rural markets:Limited low-band buildout in Montana, Wyoming, and North Dakota restricts MVNO service parity outside urban corridors.
- Device subsidy economics:Apple and Samsung flagship pricing above $800 strains prepaid customer acquisition budgets and elongates payback periods.
Strategic Opportunities
- Internet of Things verticals:Fleet telematics and connected healthcare monitors require low-bandwidth, long-life connectivity that MVNOs can provision through specialized SIM profiles.
- State digital equity programs:California and Texas broadband subsidy initiatives create reimbursement pathways for low-cost prepaid plans serving unbanked populations.
- eSIM provisioning platforms:Remote carrier switching technology eliminates physical distribution costs and enables instant plan customization through mobile apps.
Industry Challenges
- Subscriber churn management:Prepaid segments exhibit 25-40 percent annual turnover, requiring continuous promotional investment to maintain base sizes.
- Network prioritization disputes:MVNOs lack contractual guarantees on quality-of-service during host network congestion, complicating enterprise SLA commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Mobile Virtual Network Operator (MVNO) Market |
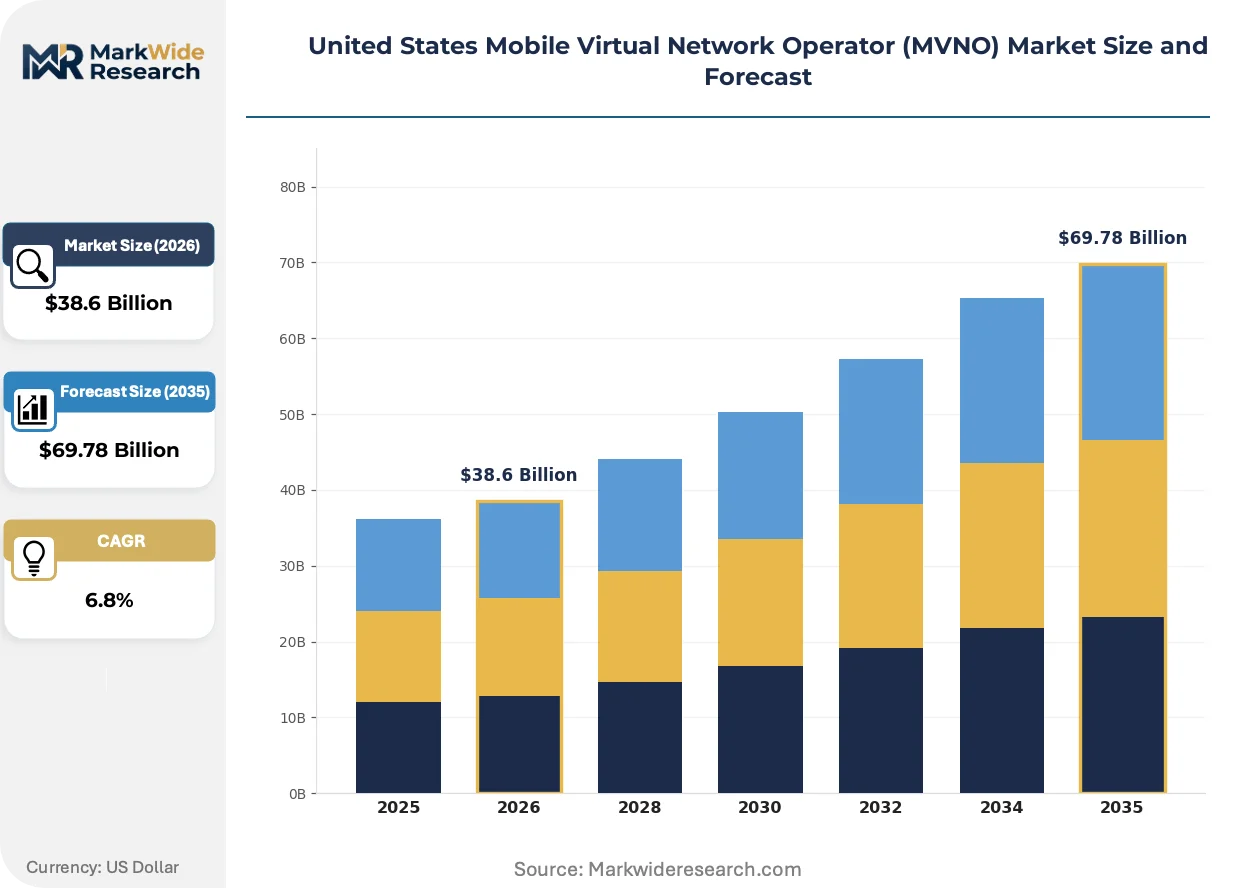
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Prepaid, Postpaid, Hybrid, Data-Only Customer Type: Retail Consumers, Businesses, Nonprofits, Government Agencies Technology: 4G LTE, 5G, VoLTE, Wi-Fi Calling Distribution Channel: Online Store, Retail Store, Mobile App, Third-Party Resellers |
| Companies Covered | Metro by T-Mobile, Tracfone Wireless, Mint Mobile, Consumer Cellular, H2O Wireless, Visible, Google Fi, Red Pocket Mobile, Cricket Wireless, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Mobile Virtual Network Operator (MVNO) Market Evolving Landscape
Digital-native distribution models are compressing customer acquisition costs while AI-driven network slicing creates service differentiation without physical infrastructure ownership.
eSIM technology is fragmenting traditional carrier switching costs. Subscribers now store multiple operator profiles on a single device, enabling instant price arbitrage between prepaid plans. Younger demographics in Texas and Florida are adopting this capability fastest, pressuring legacy MVNOs to abandon physical retail dependence.
FCC spectrum management reforms are reshaping wholesale access economics. The commission's 2024 framework for secondary market transactions allows smaller resellers to lease excess capacity directly from regional carriers rather than negotiating through national host networks. California-based MVNOs are pioneering these direct arrangements to bypass traditional aggregation tiers.
Self-service account management is displacing call-center support as the default customer interface. Digital-native subscribers expect real-time plan modifications through mobile applications rather than voice interactions. This shift concentrates value creation in user experience design and automated billing systems rather than human-assisted sales channels.
United States Mobile Virtual Network Operator (MVNO) Market Segmentation
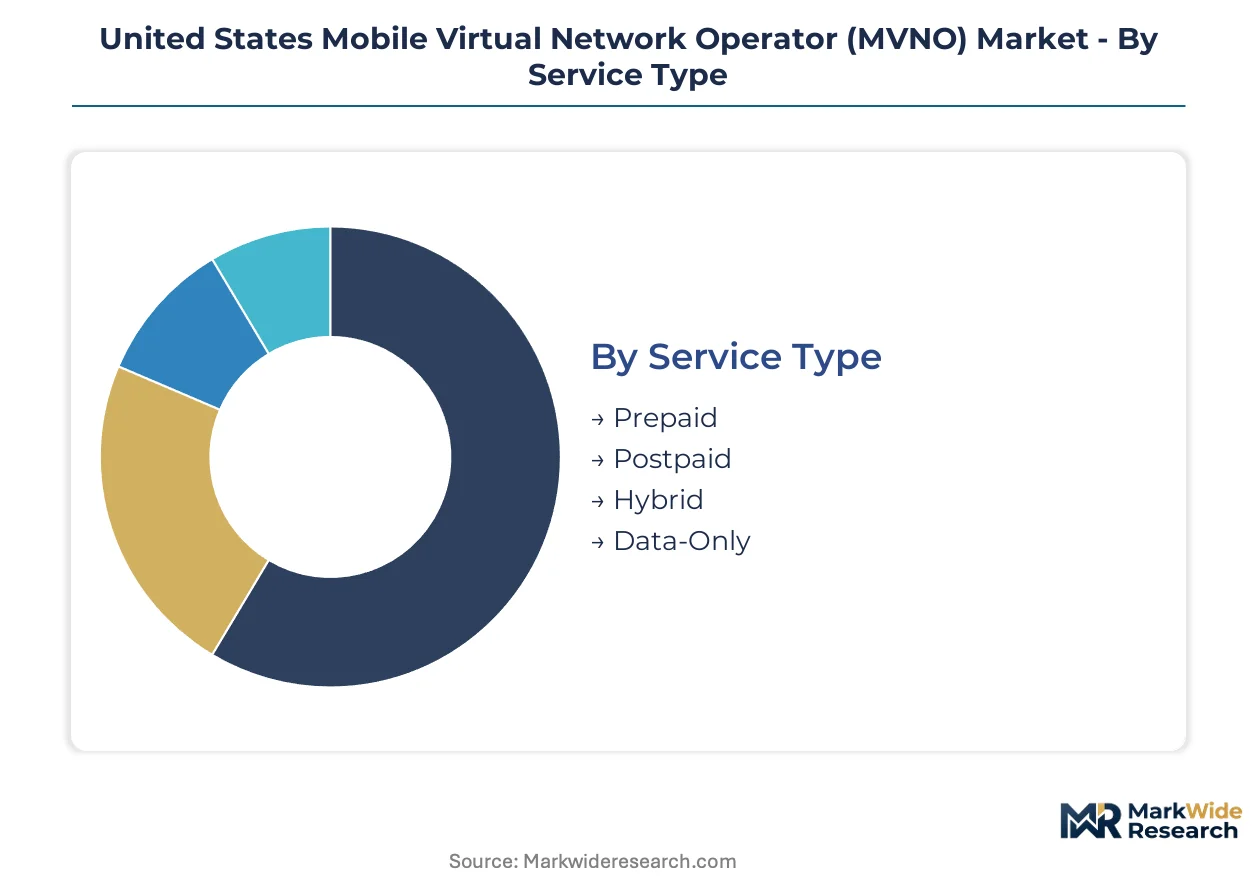
MVNOs compete across distinct service tiers and customer profiles that demand tailored pricing architectures. Segmentation reveals where wholesale capacity converts to sustainable margin pools versus commodity arbitrage.
Service Type:
Domestic consumption dominates all service categories, with prepaid and data-only plans anchoring subscriber acquisition in California and Texas metro corridors.
- Prepaid:Subscribers pay in advance for voice, text, and data allowances without credit checks or annual contracts. Demand concentrates among unbanked populations in Texas and Florida where flexible commitment structures outweigh premium network priority.
- Postpaid:Monthly billing cycles with device financing bundles and family plan discounts. California tech-sector employees sustain this segment through employer-subsidized mobility programs requiring guaranteed service levels.
- Hybrid:Combines prepaid core service with postpaid-style overage allowances and international roaming add-ons. Appeals to gig economy workers needing predictable base costs with occasional burst capacity.
- Data-Only:Connectivity for tablets, mobile hotspots, and IoT endpoints without voice provisioning. Enterprise fleet deployments in Illinois and Ohio manufacturing corridors drive volume.
Prepaid commands the established base. The steepest expansion runs through data-only as connected vehicle and industrial sensor deployments multiply.
Customer Type:
Cost tier separation defines this category, with retail consumers at economy pricing and government agencies at premium managed service tiers.
- Retail Consumers:Individual subscribers purchasing single-line or family plans through direct channels. Price sensitivity peaks in Sun Belt states where switching costs approach zero.
- Businesses:Small and medium enterprises with 50-500 employees consolidating mobility spend under single-vendor contracts. Michigan and Pennsylvania manufacturing clusters show fastest adoption of pooled data arrangements.
- Nonprofits:Mission-driven organizations qualifying for discounted wholesale rates through FCC Lifeline program eligibility. Concentrated in urban California and New York social service corridors.
- Government Agencies:Federal, state, and municipal entities requiring FISMA-compliant managed mobility with encrypted voice and priority network access. Department of Defense contractors in Virginia and Maryland anchor demand.
Retail consumers command the established base. The steepest expansion runs through businesses as remote work policies permanently alter enterprise mobility procurement.
Technology:
Application-driven deployment separates legacy 4G volume from 5G growth corridors, with VoLTE and Wi-Fi calling addressing coverage gap scenarios.
- 4G LTE:Mature radio access technology delivering 5-12 Mbps downstream in most host network configurations. Rural Montana and Wyoming subscribers remain dependent on LTE where C-band buildout lags.
- 5G:Mid-band and millimeter-wave deployments enabling 100+ Mbps speeds with lower latency. Arizona and Nevada urban corridors show fastest subscriber migration as T-Mobile and Verizon expand n77 coverage.
- VoLTE:Voice over LTE packet-switched calling replacing circuit-switched 3G voice. Required for service continuity as host carriers sunset legacy networks.
- Wi-Fi Calling:Native handset capability routing voice and text through broadband when cellular signal degrades. Critical for basement-level coverage in dense Chicago and Boston commercial buildings.
4G LTE commands the established base. The steepest expansion runs through 5G as host carrier capital expenditure shifts decisively toward mid-band densification.
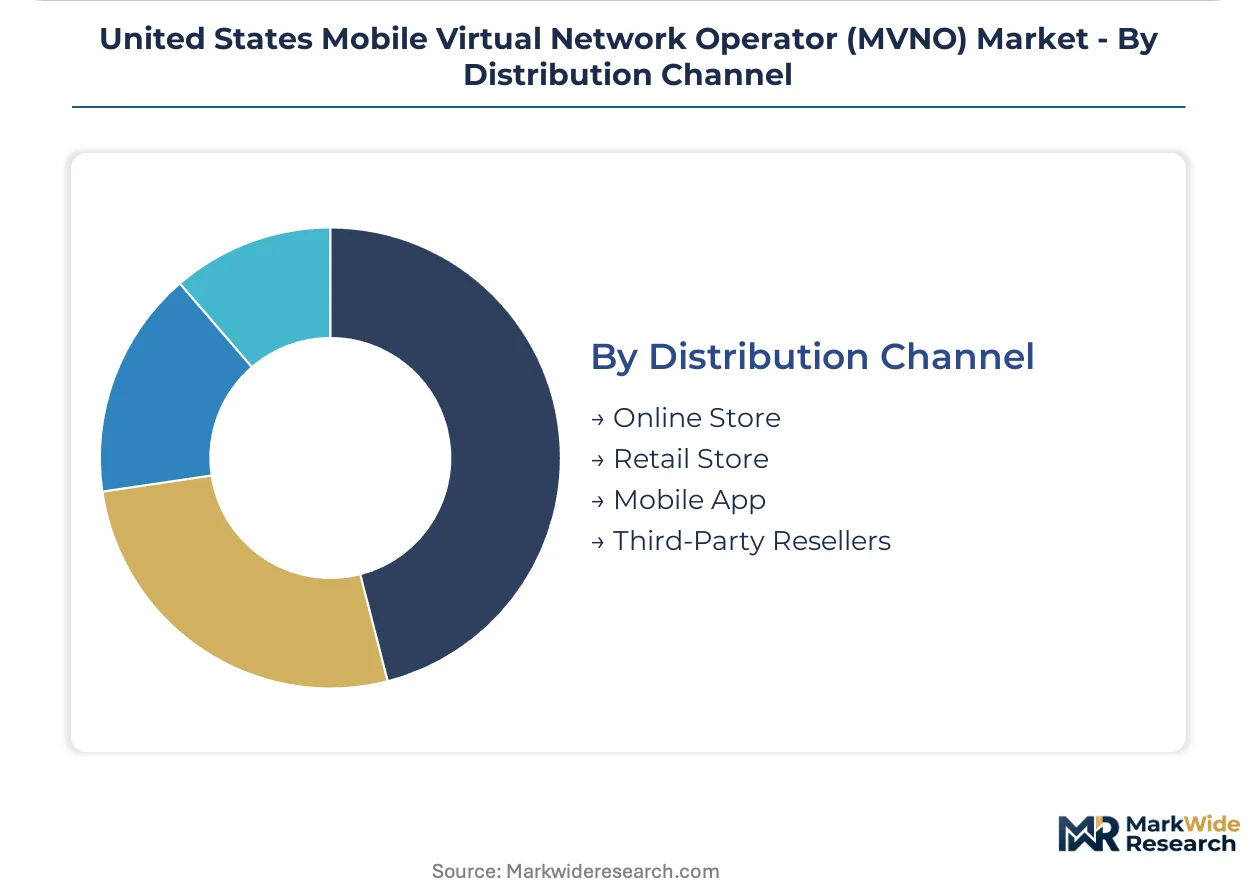
Distribution Channel:
Volume concentration versus margin capture defines channel strategy, with digital-native platforms displacing physical retail in subscriber acquisition economics.
- Online Store:Direct-to-consumer web portals enabling instant plan comparison and eSIM activation. Digital-native challengers in Florida and Georgia exploit this channel to minimize customer acquisition costs.
- Retail Store:Branded physical locations and authorized dealer networks providing hands-on device selection. Senior demographics in Arizona and Florida sustain this channel through preference for in-person support.
- Mobile App:Native iOS and Android applications supporting real-time plan modification and usage monitoring. Younger demographics in Texas and California expect this as default interface.
- Third-Party Resellers:Electronics retailers, convenience stores, and online marketplaces offering prepaid SIM kits and activation support. Dollar General and 7-Eleven locations in rural Georgia and Alabama extend geographic reach.
Retail stores command the established base. The steepest expansion runs through mobile apps as self-service account management becomes default expectation across all age cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The interstate fiber backbone connecting Dallas, Atlanta, and Chicago underwrites MVNO traffic aggregation across the central United States. Major internet exchange points in Northern Virginia and Silicon Valley anchor wholesale data handoff infrastructure for virtual operators.
California
Tech-sector employment in San Francisco and San Jose sustains postpaid demand through employer-subsidized mobility programs. The California Public Utilities Commission enforces billing transparency mandates on virtual operators serving low-income households. Los Angeles and San Diego concentrate prepaid subscriber acquisition among unbanked populations seeking flexible commitment structures.
Texas
Population growth in Houston and Dallas-Fort Worth drives volume for price-sensitive prepaid segments with minimal switching costs. The Texas Legislature's broadband subsidy initiatives create reimbursement pathways for low-cost plans serving rural counties. Austin's tech corridor anchors enterprise mobility procurement for small and medium businesses consolidating vendor relationships.
Florida
Senior demographics in Tampa and Orlando sustain retail store dependence for in-person account support and device selection. The Florida Public Service Commission monitors service quality complaints against virtual operators reselling network access. Miami-Dade County concentrates digital-native subscriber adoption of eSIM-enabled instant carrier switching.
Illinois
Manufacturing corridors in Chicago and Rockford drive data-only plan demand for connected fleet and industrial sensor deployments. The Illinois Commerce Commission oversees interconnection agreements between host carriers and regional resellers. Peoria and Springfield anchor nonprofit subscriber pools qualifying for FCC Lifeline program eligibility.
New York
Financial services employment in Manhattan sustains premium postpaid segments requiring guaranteed service levels and encrypted voice. The New York State Public Service Commission enforces consumer protection standards on MVNO billing practices. Buffalo and Rochester concentrate hybrid plan adoption among gig economy workers seeking predictable base costs with burst capacity.
United States Mobile Virtual Network Operator (MVNO) Market Competitive Landscape
Concentration sits with national host network subsidiaries leveraging parent infrastructure for urban prepaid dominance. The market structure tiers into three strategic archetypes: carrier-owned discount brands, independent digital-native challengers, and demographic-specialist operators. Competitive moves center on eSIM provisioning platform deployment and direct-to-consumer digital distribution channel expansion.
Within the carrier-owned tier, Metro by T-Mobile and Cricket Wireless exemplify wholesale-dependent scale operations leveraging T-Mobile and AT&T network infrastructure respectively. Mint Mobile occupies a position as a digital-native challenger with extended-duration pricing and minimal overhead. Consumer Cellular anchors the demographic-specialist archetype through simplified plan structures targeting senior subscribers.
| Leading Market Players |
|---|
| Metro by T-Mobile |
| Tracfone Wireless |
| Mint Mobile |
| Consumer Cellular |
| H2O Wireless |
| Visible |
| Google Fi |
| Red Pocket Mobile |
| Cricket Wireless |
| Others |
Value Network & Pricing Analysis
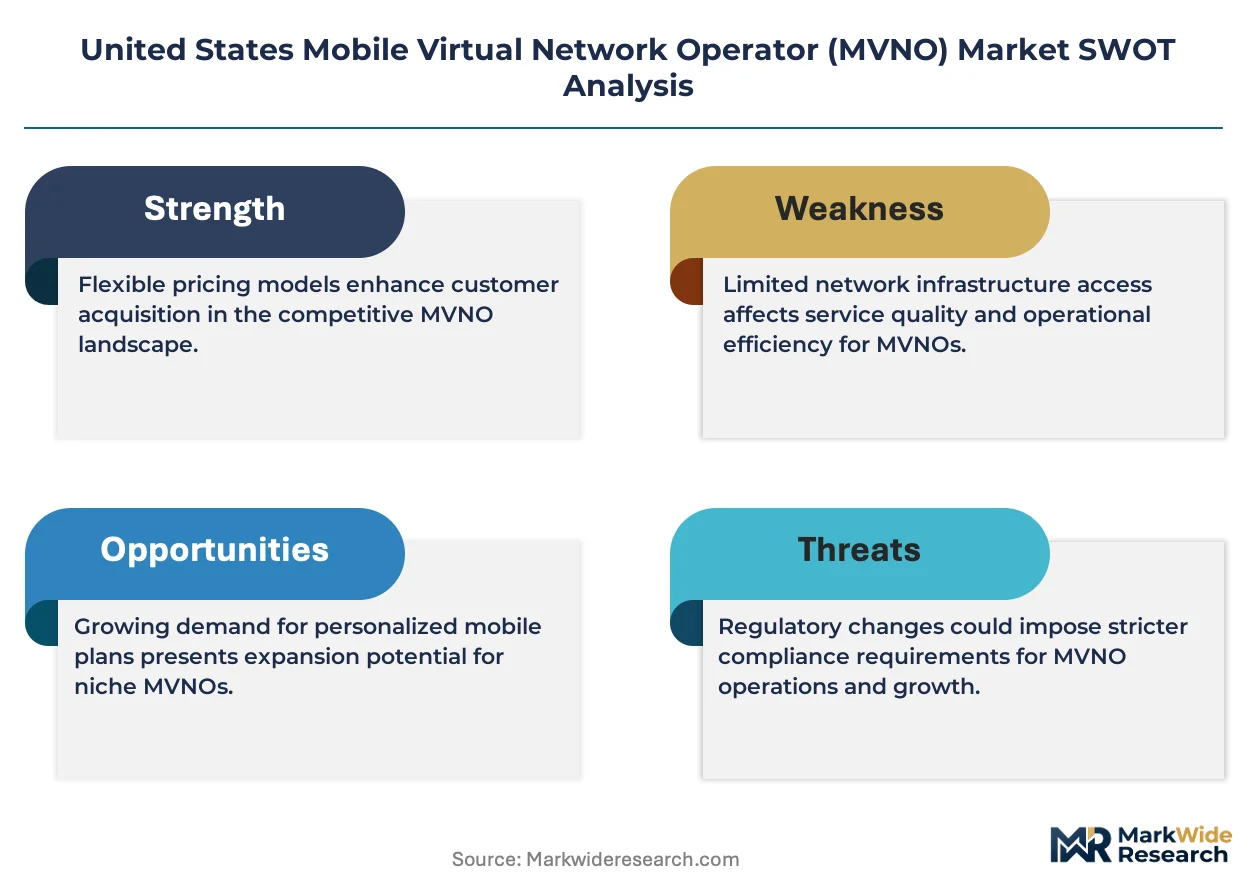
FCC wholesale access rate regulations gate both MVNO market entry and service tier differentiation simultaneously, compressing margins for resellers while enabling price arbitrage across prepaid, postpaid, and enterprise managed service segments. Host carrier concentration in national network infrastructure constrains wholesale negotiation leverage, forcing virtual operators to compete through digital distribution efficiency and vertical service attachments rather than raw connectivity pricing.
Pricing Analysis
Volume-discount tiering structures separate enterprise multi-line contracts from individual prepaid subscribers, with business customers accessing pooled data arrangements at 30-50% per-gigabyte discounts versus retail rates. Price differentiation rests on quality-of-service guarantees and managed mobility attachments, not network speed alone. Cost compression in the prepaid tier intensifies because host carrier wholesale rates are rising faster than retail pricing power. Unbanked consumers in Texas and Florida exhibit highest price sensitivity, while Department of Defense contractors in Virginia accept premium pricing for encrypted voice and priority access.
Supply Chain Analysis
Just-in-time SIM provisioning dominates inventory strategy as eSIM technology eliminates physical distribution warehousing and enables instant carrier profile activation through mobile applications. Network capacity draws from host infrastructure concentrated in the United States, with wholesale agreements anchored in T-Mobile, AT&T, and Verizon facilities. Raw material dependencies center on semiconductor components for subscriber identity modules, handset device financing inventory, and cloud billing platform infrastructure. Single-source vulnerability concentrates in host carrier roaming agreements that determine rural coverage parity. Distribution runs through digital-native platforms, third-party retail partnerships, and embedded mobile app marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market frames as a service-attach opportunity where managed mobility solutions and IoT connectivity platforms expand faster than raw subscriber acquisition, with recurring revenue from fleet telematics and connected healthcare monitors outpacing voice and data plan growth.
For Market Incumbents: Shield subscriber base stability by deepening vertical integration into proprietary eSIM provisioning platforms that reduce switching friction, while accelerating certification investment for FISMA-compliant government contracts that competitor digital-native challengers cannot match. Host carrier wholesale rate renegotiation represents the critical margin pressure point requiring defensive attention. For New Entrants and Emerging Players: FCC Lifeline program certification fast-tracks market entry through subsidized rate qualification for low-income subscriber segments that incumbent premium brands ignore. White-space concentrates in rural Texas and Florida counties where broadband subsidy reimbursement pathways offset thin margins. Direct-to-consumer mobile app distribution with instant eSIM activation provides the lowest customer acquisition cost go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from regional carrier wholesale capacity holders seeking to monetize excess spectrum through direct MVNO leasing arrangements bypassing national host network aggregation tiers. Long-term viability hinges on regulatory arbitrage sustainability and digital distribution scale economics. The signal to watch is FCC wholesale pricing reform rulemaking progression, which would compress or expand reseller margin pools depending on access rate transparency outcomes.| Strategic Initiative | Industry Significance |
|---|---|
| eSIM Provisioning Platform Deployment | Eliminates physical SIM distribution costs and enables instant carrier switching for price-sensitive subscribers. |
| Managed Mobility Service Expansion | Captures enterprise multi-line contracts with higher ARPU through device financing and pooled data arrangements. |
| IoT Vertical Specialization | Targets fleet telematics and connected healthcare monitors requiring low-bandwidth, long-life connectivity profiles. |
| Direct Wholesale Capacity Leasing | Bypasses national host network aggregation through FCC-enabled secondary market transactions with regional carriers. |
| State Digital Equity Program Participation | Accesses California and Texas broadband subsidy reimbursement pathways for low-cost prepaid plan distribution. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with MVNO executives, host carrier wholesale agreement managers, enterprise mobility procurement officers, and FCC regulatory affairs specialists. Secondary validation drew from FCC rulemaking dockets, state public utility commission filings, SEC 10-K disclosures from listed carriers, and National Telecommunications and Information Administration spectrum policy documents. Bottom-up subscriber volume modeling and top-down market value estimation were triangulated to ensure consistency across the analysis window.
Across the projection horizon, the analytical framework segmented volume and value outputs by service type, customer profile, technology tier, and distribution channel, with additional modeling of state-level regulatory cluster impacts. CAGRs were derived from host carrier capital expenditure trajectories, wholesale rate negotiation dynamics, and enterprise mobility procurement pattern shifts. Forecast inputs included 5G mid-band deployment schedules, eSIM adoption curves, and state digital equity program enrollment projections.
Decision-makers should treat outputs as directional under assumptions of stable FCC wholesale access policy and continued host carrier surplus capacity availability; material deviation in either would warrant model refresh. Specific risk factors include spectrum auction outcomes that constrain wholesale leasing, host carrier vertical integration into direct prepaid brands, and state-level quality-of-service mandate implementation. Revision becomes warranted when host carrier concentration crosses monopoly threshold scrutiny or when eSIM switching velocity exceeds platform provisioning capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global International Calling Apps Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
5G Transport Networks Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
Mexico MNVO Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
Telecom Services Market
Telecommunications
Dialer Market
Telecommunications
Russia Telecom Market
Telecommunications
Cloud RAN Market
Telecommunications
Tetra Terminals Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
5G System Integration Market
Telecommunications
Colombia Telecom Market