
 Telecom Service Assurance Market | 2026-2036
Telecom Service Assurance Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Service Assurance Market Analysis
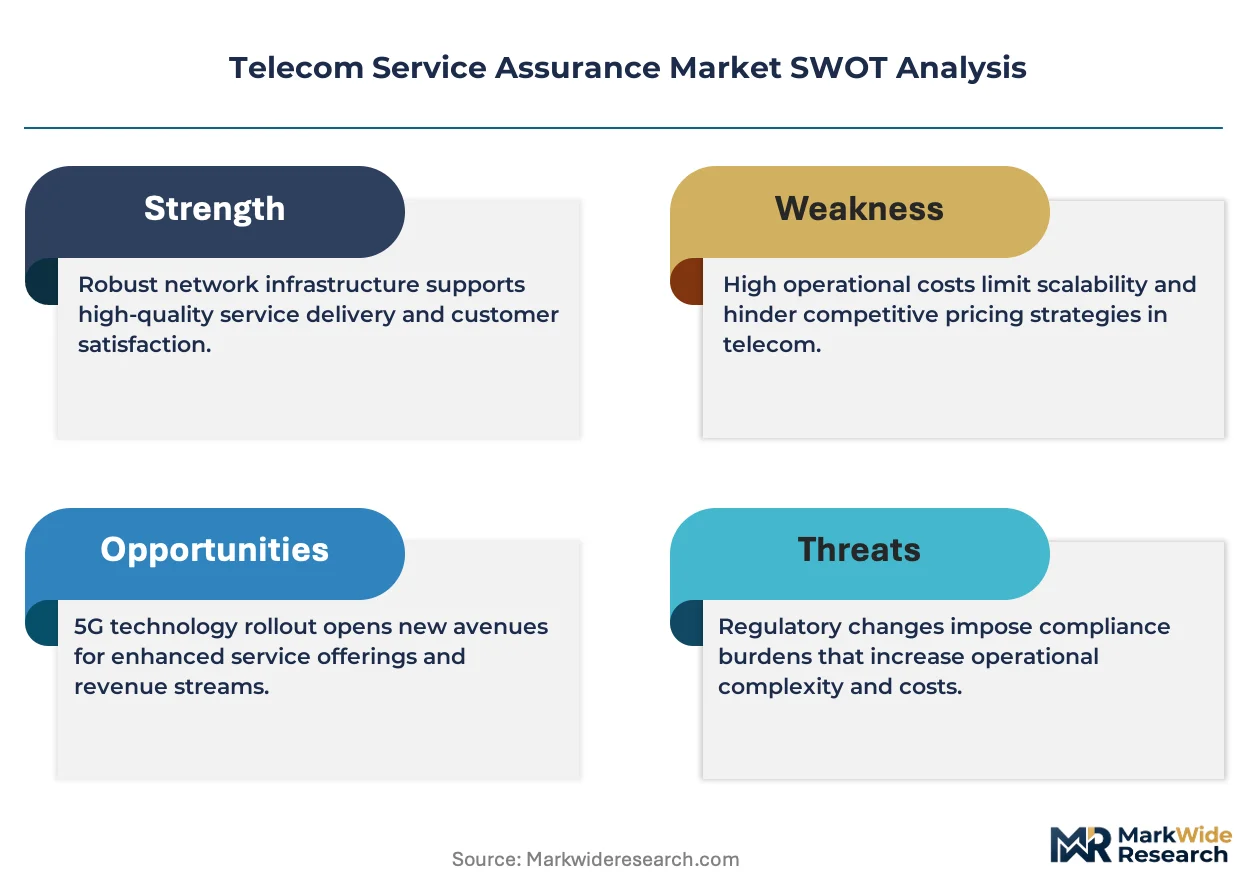
Cloud-native observability is reconfiguring how telecom service assurance platforms are architected and deployed across carrier networks. Ericsson leverages its radio access heritage to anchor assurance capabilities at the network edge. Nokia Corporation competes through integrated IP and optical domain visibility. NETSCOUT Systems, Inc. specializes in packet-level intelligence for enterprise and service provider environments.
Telecom Service Assurance encompasses the systems, processes, and software tools that monitor, measure, and maintain quality of service across telecommunications infrastructure, typically operating at millisecond-level latency thresholds and processing petabyte-scale telemetry streams to preemptively detect faults before subscriber impact. Performance Monitoring commands the largest share of service type expenditure as carriers prioritize real-time quality of experience metrics. Artificial Intelligence and Machine Learning represent the fastest-expanding technology layer, displacing rule-based correlation engines with predictive anomaly detection. Cloud Services application segments attract disproportionate R&D allocation as over-the-top traffic patterns complicate traditional assurance models.
The Federal Communications Commission shapes US market access through network reliability mandates and outage reporting requirements. Europe's Cyber Resilience Act and GDPR impose data governance standards on cross-border assurance platforms processing subscriber metadata. Japan's Ministry of Internal Affairs and Communications drives standardization through 5G service quality benchmarks. Stakeholders must evaluate whether their assurance architectures can absorb quantum-safe encryption and edge-native telemetry without forklift replacement of core analytics engines.
Market Dynamics
The migration from hardware-centric probes to software-defined telemetry agents constitutes the dominant structural force reshaping Telecom Service Assurance architecture. This shift compresses deployment cycles from months to days while eliminating proprietary hardware lock-in across carrier networks.
Growth Catalysts
- 5G Standalone Core Deployment:Mobile operators in the United States, Germany, and Japan are mandating sub-50 millisecond latency guarantees that legacy assurance platforms cannot satisfy. This forces wholesale replacement of monitoring infrastructure.
- FCC Network Reliability Mandates:Outage reporting requirements and service quality benchmarks are compelling US carriers to invest in predictive fault detection capabilities ahead of subscriber impact.
- EU Cyber Resilience Act:Cross-border data governance standards for subscriber metadata processing are creating compliance-driven demand for encrypted telemetry pipelines and sovereign cloud assurance deployments.
Market Restraints
- Specialized Engineering Talent Scarcity:The intersection of telco protocol expertise and machine learning engineering remains concentrated in a handful of technology hubs. This bottleneck extends implementation timelines by 40-60 percent for complex root cause analysis deployments.
- Optical Transport Equipment Concentration:Three Asian component suppliers dominate coherent optical DSP supply. Geopolitical friction or logistics disruption threatens assurance visibility into backbone networks.
- GDPR Cross-Border Friction:European data localization requirements complicate centralized assurance analytics for multinational operators with pan-European footprints.
Strategic Opportunities
- India's Telecom Infrastructure Modernization:TRAI's quality of service regulations and the government's BharatNet rural broadband initiative are creating first-mover advantages for cloud-native assurance vendors.
- Open RAN Intelligence Layer:The convergence of containerized microservices and streaming analytics is collapsing traditional probe architectures into lightweight edge agents. This enables real-time correlation across disaggregated radio access networks.
- Outcome-Based Assurance Contracts:Brazilian and Mexican mobile operators are piloting service level agreements tied to subscriber-perceived quality metrics rather than network-centric KPIs.
Industry Challenges
- Millisecond-Resolution Data Engineering:Streaming petabyte-scale telemetry through analytics pipelines without sampling degradation demands specialized time-series database expertise that carriers lack in-house.
- Quantum-Safe Cryptography Migration:Assurance platforms must absorb post-quantum encryption standards without forklift replacement of core correlation engines. This hardware-software coordination spans multi-year capital cycles.
- Interoperability Certification Delays:TM Forum Open APIs and 3GPP standardization timelines lag commercial deployment by 18-24 months, forcing vendor-specific integrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Service Assurance Market |
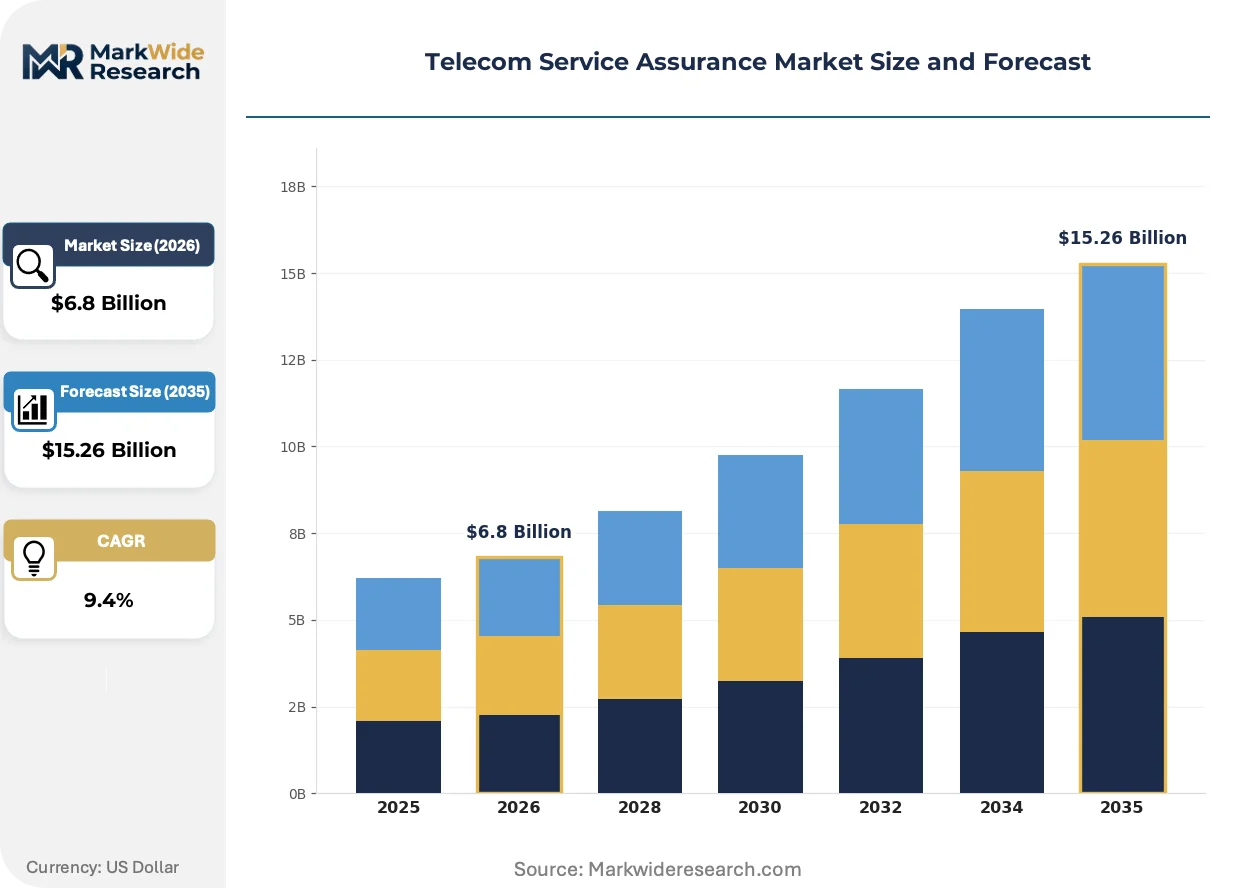
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Performance Monitoring, Fault Management, Configuration Management, Security Management Technology: Artificial Intelligence, Big Data Analytics, Machine Learning, Network Function Virtualization Application: Cloud Services, Voice Services, Data Services, Video Streaming End User: Telecom Operators, Managed Service Providers, Enterprises, Government |
| Companies Covered | IBM Corporation, Hewlett Packard Enterprise, Huawei Technologies Co., Ltd, TEOCO Corporation, Ericsson, Nokia Corporation, NETSCOUT Systems, Inc., Amdocs, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Service Assurance Market Emerging Trajectories
Artificial intelligence is collapsing traditional assurance workflows from reactive ticketing to predictive remediation. Three interconnected developments are compressing the fault-to-resolution cycle while expanding the scope of automated network management.
eBPF-based kernel instrumentation is collapsing the boundary between network infrastructure and observability software. Cloud-native service meshes are adopting these lightweight probes to capture packet-level telemetry without dedicated hardware appliances. This architecture collapses capital expenditure into operational software licenses while enabling continuous deployment of new analytics capabilities.
Japan's Ministry of Internal Affairs and Communications has issued binding 5G service quality benchmarks that mandate automated fault prediction. Japanese carriers must demonstrate sub-100 millisecond detection-to-escalation intervals for critical network elements. Equipment vendors are responding with embedded machine learning inference engines that operate at the network edge rather than centralized data centers.
Enterprise procurement of assurance capabilities is fragmenting from monolithic platform licenses toward modular API consumption. Large enterprises in financial services and healthcare are unbundling monitoring from remediation, selecting best-of-breed components through cloud marketplaces. This pattern is most visible in the United States, where HIPAA-covered entities prioritize specialized vendors for patient data-carrying network segments.
Telecom Service Assurance Market Segmentation
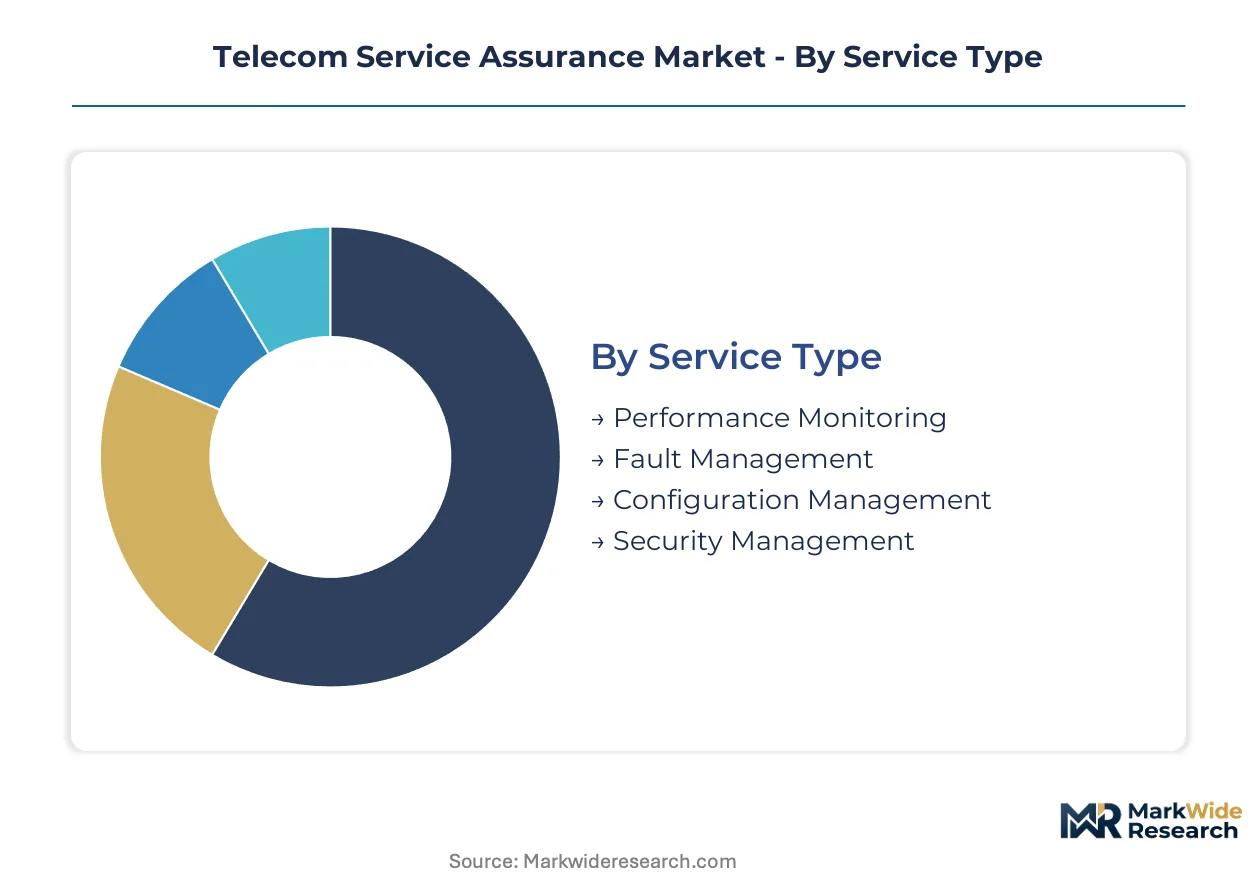
Telecom service assurance architectures diverge sharply across deployment contexts, with latency requirements and telemetry scale dictating technology selection. Understanding these segment boundaries clarifies where vendor capabilities align with carrier procurement priorities.
Service Type:
Cost tier stratification within service types reflects the operational criticality of each function and its capital intensity relative to software-defined alternatives.
- Performance Monitoring:Real-time quality of experience metrics collection operates at millisecond resolution across radio access, transport, and core domains. United States carriers prioritize this segment under FCC network reliability mandates that mandate predictive fault detection ahead of subscriber impact. The shift from hardware probes to software agents compresses deployment cycles while maintaining telemetry fidelity.
- Fault Management:Root cause analysis engines correlate alarms across multi-vendor infrastructure to isolate failure points before service degradation. German mobile operators are mandating sub-50 millisecond detection-to-escalation intervals for 5G standalone core elements, forcing wholesale replacement of legacy correlation platforms. AI-driven inference is displacing rule-based engines in this segment.
- Configuration Management:Automated provisioning and policy enforcement across disaggregated network functions.
- Security Management:Threat detection and encrypted telemetry pipeline governance for subscriber metadata protection.
Performance Monitoring holds installed capacity. Fault Management is rotating up the share rankings.
Technology:
Application maturity varies dramatically across these technology layers, with some already production-hardened while others remain in carrier trial phases.
- Artificial Intelligence:Predictive anomaly detection and automated remediation workflows operate at the network edge rather than centralized data centers. Japanese carriers must demonstrate sub-100 millisecond inference latency under binding 5G service quality benchmarks issued by the Ministry of Internal Affairs and Communications. Embedded machine learning engines are collapsing traditional reactive ticketing workflows.
- Machine Learning:Pattern recognition across petabyte-scale telemetry streams enables preemptive fault identification without sampling degradation. The intersection of telco protocol expertise and ML engineering remains concentrated in technology hubs, extending implementation timelines for complex deployments. Specialized time-series database expertise is scarce among carriers.
- Big Data Analytics:Historical trend analysis and capacity planning across multi-dimensional network datasets.
- Network Function Virtualization:Containerized assurance microservices deployed on commodity infrastructure.
Artificial Intelligence commands current R&D allocation. Machine Learning is gaining share fastest.
Application:
Volume concentration within application segments tracks the underlying traffic growth curves and their associated quality-of-service enforcement challenges.
- Cloud Services:Over-the-top traffic patterns complicate traditional assurance models as enterprise workloads migrate to distributed edge locations. United States financial services and healthcare enterprises are unbundling monitoring from remediation, selecting best-of-breed components through cloud marketplaces for patient data-carrying network segments. HIPAA-covered entities prioritize specialized vendors with proven compliance architectures.
- Video Streaming:Buffer-free delivery mandates require continuous throughput measurement and adaptive bitrate optimization across last-mile connections. Brazilian and Mexican mobile operators are piloting service level agreements tied to subscriber-perceived quality metrics rather than network-centric KPIs. Outcome-based contracts are reshaping procurement criteria.
- Voice Services:Latency-sensitive call quality monitoring and mean opinion score tracking.
- Data Services:Packet-level integrity verification for enterprise VPN and IoT connectivity.
Cloud Services anchors current expenditure. Video Streaming shows the steepest expansion trajectory.
End User:
Customer type determines procurement authority, integration complexity, and the balance between standardized platforms versus customized deployments.
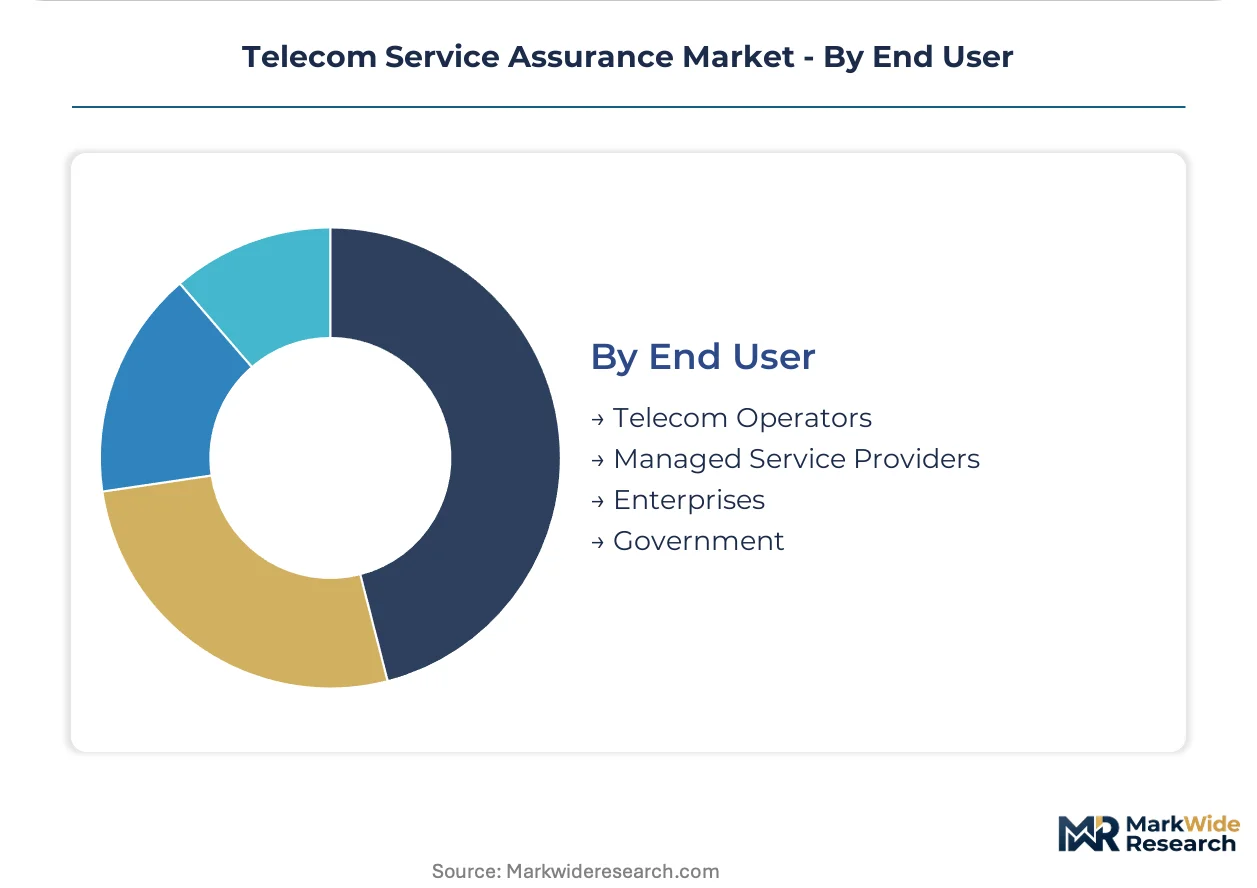
- Telecom Operators:Mobile and fixed-line carriers with end-to-end infrastructure ownership require unified assurance across access, transport, and core domains. India's TRAI quality of service regulations and the BharatNet rural broadband initiative are creating first-mover advantages for cloud-native vendors. Modernization timelines are accelerating across tier-1 and tier-2 operators.
- Enterprises:Large organizations in regulated industries are fragmenting procurement from monolithic licenses toward modular API consumption. Financial services firms demand specialized packet-level intelligence for trading infrastructure. Healthcare networks require segmented assurance for protected health information flows.
- Managed Service Providers:Multi-tenant assurance platforms serving distributed enterprise footprints.
- Government:Sovereign cloud deployments with encrypted telemetry and data localization requirements.
Telecom Operators retain dominant procurement volume. Enterprises are climbing the fastest in share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German assurance platform vendors export cloud-native telemetry solutions to mobile operators across Central Europe and the Nordics. This trade corridor reflects the concentration of 5G standalone core deployments in markets with binding latency regulations.
United States
Verizon and AT&T are mandating sub-50 millisecond latency guarantees for standalone 5G cores that legacy monitoring cannot satisfy. FCC network reliability mandates compel carriers to invest in predictive fault detection ahead of subscriber impact. The Dallas-Fort Worth metroplex hosts concentrated engineering talent for AI-driven root cause analysis platforms.
Germany
Deutsche Telekom and Vodafone Germany are replacing hardware-centric probe architectures with software-defined telemetry agents. The EU Cyber Resilience Act imposes encrypted pipeline requirements for cross-border subscriber metadata processing. Munich and Stuttgart anchor development clusters for quantum-safe cryptography migration in assurance platforms.
Japan
NTT Docomo and KDDI must demonstrate sub-100 millisecond detection-to-escalation intervals under binding 5G quality benchmarks. The Ministry of Internal Affairs and Communications mandates automated fault prediction for critical network elements. Tokyo and Osaka host embedded machine learning inference engine development for edge-native assurance.
India
Reliance Jio and Bharti Airtel are accelerating cloud-native assurance procurement under TRAI quality of service regulations. The BharatNet rural broadband initiative creates first-mover advantages for vendors with lightweight deployment models. Bengaluru and Hyderabad concentrate engineering talent for streaming analytics microservices.
Brazil
Vivo and Claro are piloting outcome-based assurance contracts tied to subscriber-perceived quality metrics rather than network-centric KPIs. ANATEL's quality of service enforcement drives investment in real-time quality of experience measurement. São Paulo anchors Latin America's largest systems integration cluster for multi-vendor fault correlation.
Telecom Service Assurance Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers. Tier-one infrastructure vendors leverage radio access heritage to bundle assurance with equipment contracts. Tier-two pure-play software specialists compete through packet-level intelligence and cloud-native architectures. Tier-three systems integrators assemble multi-vendor solutions for enterprise and government clients. Dominant competitive moves include vertical integration of machine learning inference engines into network equipment and strategic partnerships between telco software vendors and hyperscale cloud providers.
Among Nordic-origin infrastructure specialists, Ericsson and Nokia Corporation exemplify the equipment-anchored archetype, embedding assurance capabilities directly into radio access and transport domain portfolios. IBM Corporation occupies a position within the enterprise-facing systems integration tier, assembling multi-vendor assurance stacks for regulated industries with specialized compliance requirements. These three companies represent distinct competitive vectors: radio access heritage, IP-optical domain integration, and enterprise solution assembly.
| Leading Market Players |
|---|
| IBM Corporation |
| Hewlett Packard Enterprise |
| Huawei Technologies Co., Ltd |
| TEOCO Corporation |
| Ericsson |
| Nokia Corporation |
| NETSCOUT Systems, Inc. |
| Amdocs |
| Accenture |
| Others |
Supply Flow & Price Mechanics
Three Asian component suppliers dominate coherent optical DSP supply, concentrating margin capture upstream while forcing downstream assurance vendors into software licensing models to preserve returns. This concentration shapes how carriers procure telemetry infrastructure, with hardware margins compressed and value migrating to analytics layers.
Pricing Analysis
Legacy probe-based assurance commands premium pricing against cloud-native software alternatives, while next-generation edge-native telemetry sits at a cost disadvantage until deployment scale materializes. Pricing stratifies across premium hardware-appliance tiers, standard subscription SaaS offerings, and economy open-source-based deployments. Price differentiation hinges on millisecond-latency guarantees and FCC compliance certification tiers. Cost compression in the hardware tier is intensifying because software-defined agents eliminate proprietary appliance lock-in. Tier-2 mobile operators exhibit highest price sensitivity; tier-1 carriers with regulatory mandates show lowest.
Supply Chain Analysis
US export controls on advanced semiconductors restrict flows of coherent optical DSPs and high-performance inference accelerators to Chinese equipment vendors, fragmenting global assurance platform supply. Manufacturing concentrates in China, South Korea, and Taiwan for optical components; Germany and the United States anchor software development. Raw material dependencies include indium phosphide for optical transceivers, advanced node silicon for ML inference engines, and rare earth elements for specialized magnetics. Single-source vulnerability in coherent optical DSP supply threatens backbone network visibility. Distribution runs through carrier procurement consortiums and hyperscale cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated tier-1 mobile operators with multi-vendor leverage, fragmenting procurement across specialized vendors rather than accepting bundled equipment-assurance packages.
For Market Incumbents: Harden defensive positions through backward integration into edge-native ML inference silicon and captive supply of quantum-safe cryptographic modules. Equipment-anchored vendors face disintermediation by cloud-native software specialists; priority investment in containerized microservices architectures preserves carrier relationships. Certification investment in FCC, GDPR, and Japan MIC compliance tiers creates switching costs. For New Entrants and Emerging Players: India's BharatNet rural broadband initiative offers underpenetrated deployment terrain for lightweight assurance microservices. White-space targets include outcome-based SLA contracts in Brazil and Mexico, plus modular API consumption by US healthcare enterprises. Go-to-market through hyperscale cloud marketplaces bypasses carrier procurement gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play assurance software vendors with cloud-native architectures but limited carrier relationships. Long-term viability favors platforms absorbing quantum-safe cryptography without forklift replacement. Target acquisition profile: vendors with embedded edge inference engines and proven 5G standalone core integrations. Watch for inflection in Open RAN deployment velocity as signal for assurance architecture disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native ML Inference Integration | Japanese MIC mandates sub-100 millisecond detection intervals, forcing edge deployment. |
| Quantum-Safe Cryptography Migration | EU Cyber Resilience Act imposes encrypted pipeline requirements for subscriber metadata. |
| Open RAN Intelligence Layer Development | Containerized microservices collapse traditional probe architectures into lightweight agents. |
| Outcome-Based Assurance Contracting | Brazilian operators pilot SLAs tied to subscriber-perceived quality metrics. |
| Hyperscale Cloud Marketplace Distribution | US healthcare enterprises unbundle monitoring from remediation through API consumption. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, carrier capex disclosures, and vendor contract announcements. Primary interviews engaged network operations executives at tier-1 mobile operators, assurance platform product managers, procurement leads at telecom equipment vendors, and systems integration specialists. Secondary sources included FCC outage reports, EU Cyber Resilience Act implementation guidance, Japan MIC 5G quality benchmarks, TRAI quality of service regulations, and SEC filings from listed equipment vendors. Bottom-up deployment modeling triangulates against top-down carrier spending forecasts.
Forecast inputs span service type expenditure patterns, technology layer adoption curves, application segment traffic growth, and end-user procurement fragmentation across the analysis window. Segmentation dimensions modeled include service type, technology layer, application, and end-user category, with geographic regulatory cluster as an additional cross-cutting dimension. CAGRs derive from carrier capex trajectory analysis, vendor booking patterns, and equipment shipment correlations. Industry-specific inputs include 5G standalone core deployment timelines and Open RAN commercialization velocity.
Macroeconomic conditions sit as an overlay; deviation in carrier capital expenditure cycles, semiconductor supply availability, or geopolitical friction in optical component trade would shift the trajectory. Forecasts reflect assumptions around regulatory mandate enforcement intensity and cloud-native migration pace. Material shifts in quantum-safe cryptography standardization timelines or Open RAN interoperability certification delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Egypt ICT Market
Telecommunications
IP Telephony Market
Telecommunications
Singapore MVNO Market
Telecommunications
Sri Lanka Telecom Tower Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
Competitive Local Exchange Carriers (CLEC) Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
5G Core Market
Telecommunications
Vietnam ICT Market
Telecommunications
Mftpaas Market
Telecommunications
Standalone 5G Network Market