
 LPG [Liquefied Petroleum Gas] Market | 2026-2036
LPG [Liquefied Petroleum Gas] Market Size, Share, and Industry Trends Forecast 2026-2036
LPG [Liquefied Petroleum Gas] Market Analysis
Automotive-grade LPG specifications is redrawing competitive boundaries across fuel retail networks. Saudi Aramco leverages integrated refining and NGL extraction to dominate supply reliability. Shell plc sustains extensive downstream distribution infrastructure across European and Asian markets. Exxon Mobil Corporation anchors its position through proprietary odorant and specification technologies for transport applications.
Liquefied Petroleum Gas consists primarily of propane and butane hydrocarbons recovered from natural gas processing or crude oil refining, stored under moderate pressure at ambient temperature for transport and combustion. Its principal commercial purpose spans residential thermal energy, industrial process heat, and transportation fuel substitution. Propane leads product-type revenue pools due to broader climatic operability and established heating infrastructure compatibility. The automotive application segment shows structural momentum from fleet conversion incentives in multiple jurisdictions. Residential end users command stable volume baselines through subsidized cylinder programs in South Asia and sub-Saharan Africa.
The US EPA regulates LPG composition and emission profiles under Clean Air Act mobile source provisions, while India's PESO mandates cylinder safety standards and filling protocols. China's SAMR enforces GB quality standards for commercial and automotive grades. Stakeholders must monitor evolving carbon-accounting frameworks that could recast LPG against renewable alternatives in national decarbonization pathways.
Market Dynamics
LPG distribution economics are compressing as national subsidy reforms in India and China shift cylinder procurement from state-controlled channels to direct benefit transfers, forcing infrastructure reinvestment across last-mile networks.
Growth Catalysts
- India's PAHAL Direct Benefit Transfer:This subsidy mechanism eliminates intermediary leakage and expands household cylinder access across Bihar, Uttar Pradesh, and Odisha. Cash transfers now reach 80 million active consumers.
- Automotive Fleet Conversion Mandates:Turkey's NGV-LPG retrofit program and South Korea's tax incentives for commercial vehicle conversion are accelerating transport-sector demand. Istanbul's taxi cooperatives now operate 15,000 dedicated LPG vehicles.
- Crude Oil Refining Integration:Middle Eastern producers with captive NGL extraction capacity are securing long-term supply contracts. Saudi Aramco's Yanbu and Jubail complexes anchor regional export reliability.
Market Restraints
- Propane-Butane Price Volatility:Feedstock costs track Mont Belvieu and FEI index fluctuations with 30-45 day lag. Asian importers face working capital compression during winter price spikes.
- Supply Concentration in Persian Gulf:Qatar, Saudi Arabia, and the UAE control 40% of seaborne LPG exports. Any Strait of Hormuz disruption cascades through Asian pricing benchmarks.
- Electrification Substitution Pressure:China's MIIT electric cooking subsidies and India's Ujjwala 2.0 biogas pilots threaten residential LPG retention in rural districts. Grid extension outpaces cylinder refill logistics in some states.
Strategic Opportunities
- Sub-Saharan Africa Clean Cooking Gap:Nigeria, Kenya, and Ghana exhibit sub-20% LPG penetration among urban households. Distributor financing models can unlock 50-million-cylinder annual demand.
- Marine Fuel Specification Convergence:IMO 2020 sulfur caps and EU MRV carbon accounting create openings for LPG as a compliant bunker fuel. Rotterdam and Singapore terminals are adapting loading infrastructure.
- Digital Cylinder Tracking Integration:RFID-enabled asset management combined with mobile payment platforms reduces cylinder float losses. Indian distributors deploying IoT weight sensors report 15% inventory efficiency gains.
Industry Challenges
- Cryogenic Handling Certification Shortage:Licensed technicians for pressure vessel maintenance remain scarce in Indonesia, Bangladesh, and Pakistan. Training accreditation through national petroleum safety authorities lags deployment targets.
- Legacy Cylinder Pool Modernization:India's PESO-mandated 15-year retirement rule requires simultaneous scrap-and-replace programs across 250 million installed units. Manufacturing capacity constraints extend replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LPG [Liquefied Petroleum Gas] Market |
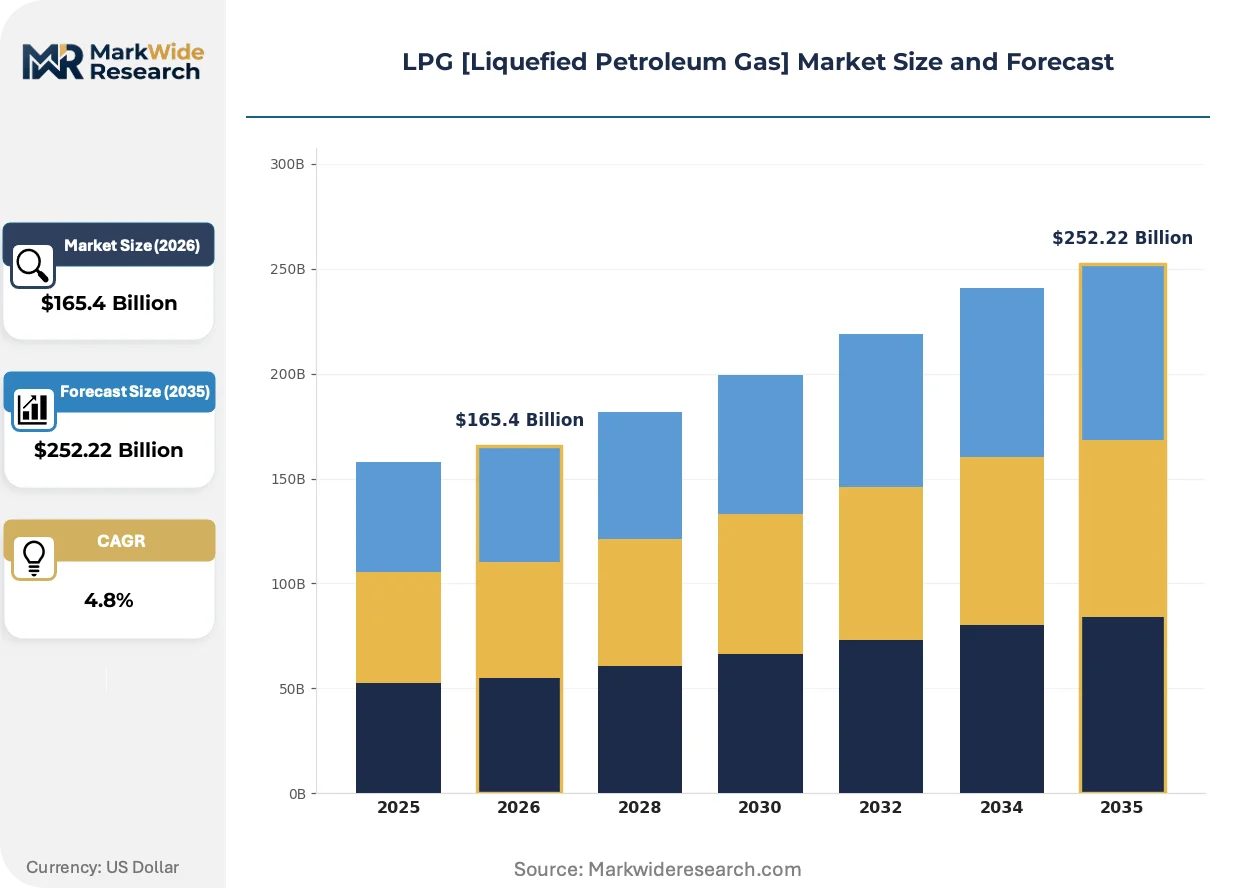
| Market Size in 2026 | $165.4 Billion |
| Market Size in 2035 | $252.22 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Propane, Butane, Propylene, Butylene Application: Heating, Cooking, Automotive, Industrial End User: Residential, Commercial, Agricultural, Transportation Distribution Channel: Retail, Wholesale, Bulk, Cylinder |
| Companies Covered | Saudi Aramco, Shell plc, Exxon Mobil Corporation, BP plc, TotalEnergies SE, China Petroleum & Chemical Corporation (Sinopec), Chevron Corporation, Reliance Industries Limited, QatarEnergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LPG [Liquefied Petroleum Gas] Market Emerging Trajectories
Refinery-petrochemical integration and carbon-accounting transparency are reconfiguring how LPG grades are specified, traded, and consumed across residential, industrial, and transport applications.
Composite-wrapped LPG cylinders are miniaturizing storage footprints while maintaining pressure ratings. European camping equipment manufacturers and Indian urban apartment complexes are adopting these lightweight alternatives. The technology is miniaturizing installation constraints in space-constrained environments.
China's GB 11174-2011 automotive LPG quality standard revision is tightening vapor pressure and sulfur specifications. Domestic refiners must upgrade hydrotreating capacity or surrender transport-fuel market share. Guangdong and Jiangsu province filling stations are retrofitting vapor recovery systems to comply.
Commercial buyers in Brazil and Mexico are consolidating procurement through long-term offtake contracts rather than spot-indexed purchases. Large hotel chains and food processors now negotiate direct supply agreements with import terminal operators. This concentration is visible in São Paulo's restaurant district, where single-source contracts replaced fragmented distributor relationships.
LPG [Liquefied Petroleum Gas] Market Segmentation
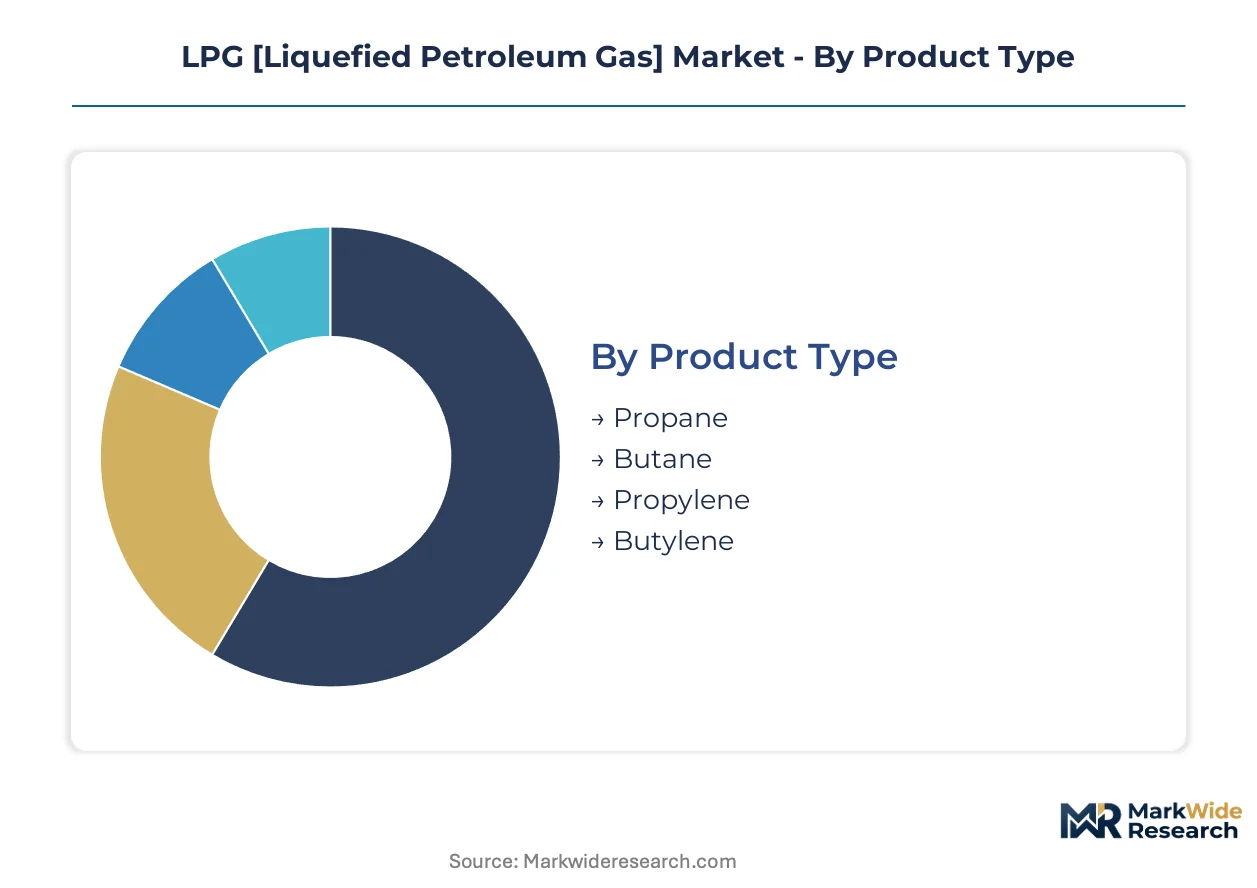
LPG segmentation reflects divergent supply economics across geographies. Product-grade specifications determine whether molecules flow into domestic heating networks or seaborne export markets. Channel structure varies sharply between subsidized cylinder programs in South Asia and automated bulk terminals in industrialized economies.
Product Type:
Propane and butane trade on fundamentally different geographic footprints—propane serves cold-climate heating demand across North America and Northern Europe, while butane concentrates in Asian petrochemical feedstock and warmer-climate cooking markets.
- Propane:This C3 hydrocarbon maintains vapor pressure stability below freezing, enabling year-round operability in heating-dependent regions. Demand concentrates in US Midwest agricultural drying and Northeast residential heating, where pipeline infrastructure locks in supply reliability. EPA odorant specifications for transport-grade propane create specification premiums over standard commercial grades.
- Butane:Higher boiling points suit warm-climate cooking applications across India, Brazil, and Southeast Asia. Indian refiners blend butane-rich fractions for domestic cylinder markets, while Middle Eastern exporters direct normal butane to Asian steam cracker operations. Seasonal price spreads against propane widen during Northern Hemisphere winter.
- Propylene:Refinery-grade propylene serves regional petrochemical derivatives manufacturing.
- Butylene:Butylene fractions feed synthetic rubber and fuel additive production, primarily in East Asian chemical complexes.
Propane commands the established base in temperate-zone heating infrastructure. The steepest expansion runs through butane as urban cooking transitions accelerate across tropical and subtropical economies.
Application:
Application segmentation tracks regulatory differentiation—automotive and industrial grades face emissions testing protocols that residential heating bypasses entirely.
- Heating:Residential and commercial thermal applications anchor volume baselines in climates with sustained cold seasons. US EIA data tracks propane heating degree-day correlations. German and Polish district heating operators blend LPG as peak-shaving fuel.
- Cooking:Cylinder-based cooking dominates emerging economy demand. India's PAHAL subsidy infrastructure and Brazil's social program distribution networks concentrate procurement power at national scale.
- Automotive:Turkey's NGV-LPG retrofit mandates and South Korean commercial fleet incentives drive transport-fuel specification demand. Istanbul taxi cooperatives operate dedicated LPG vehicle pools.
- Industrial:Process heat applications in ceramics, glass, and metalworking use bulk terminal supply. Mexican food processors negotiate direct offtake contracts with import terminal operators.
Cooking applications anchor volume in subsidy-dependent emerging markets. Automotive conversion programs are gaining share fastest where fleet mandates intersect with retail fuel taxation advantages.
End User:
End-user segmentation reveals procurement scale divergence—residential consumers purchase single cylinders while transportation fleets negotiate thousand-ton annual contracts.
- Residential:Individual households access subsidized cylinders through direct benefit transfer mechanisms. India's 80 million active PAHAL consumers represent the largest single residential pool globally.
- Commercial:Hotels, restaurants, and food processors consolidate procurement through distributor relationships or direct terminal agreements. São Paulo restaurant districts have shifted from fragmented distributor networks to single-source supply contracts.
- Agricultural:Crop drying and greenhouse heating concentrate in grain-belt regions with seasonal demand spikes.
- Transportation:Fleet operators specify automotive-grade product with vapor pressure and sulfur compliance. South Korean commercial vehicle tax incentives accelerate fleet conversion timelines.
Residential end users command the established base through subsidy-locked cylinder programs. Commercial consolidation is expanding most quickly as large buyers bypass distributor markups.
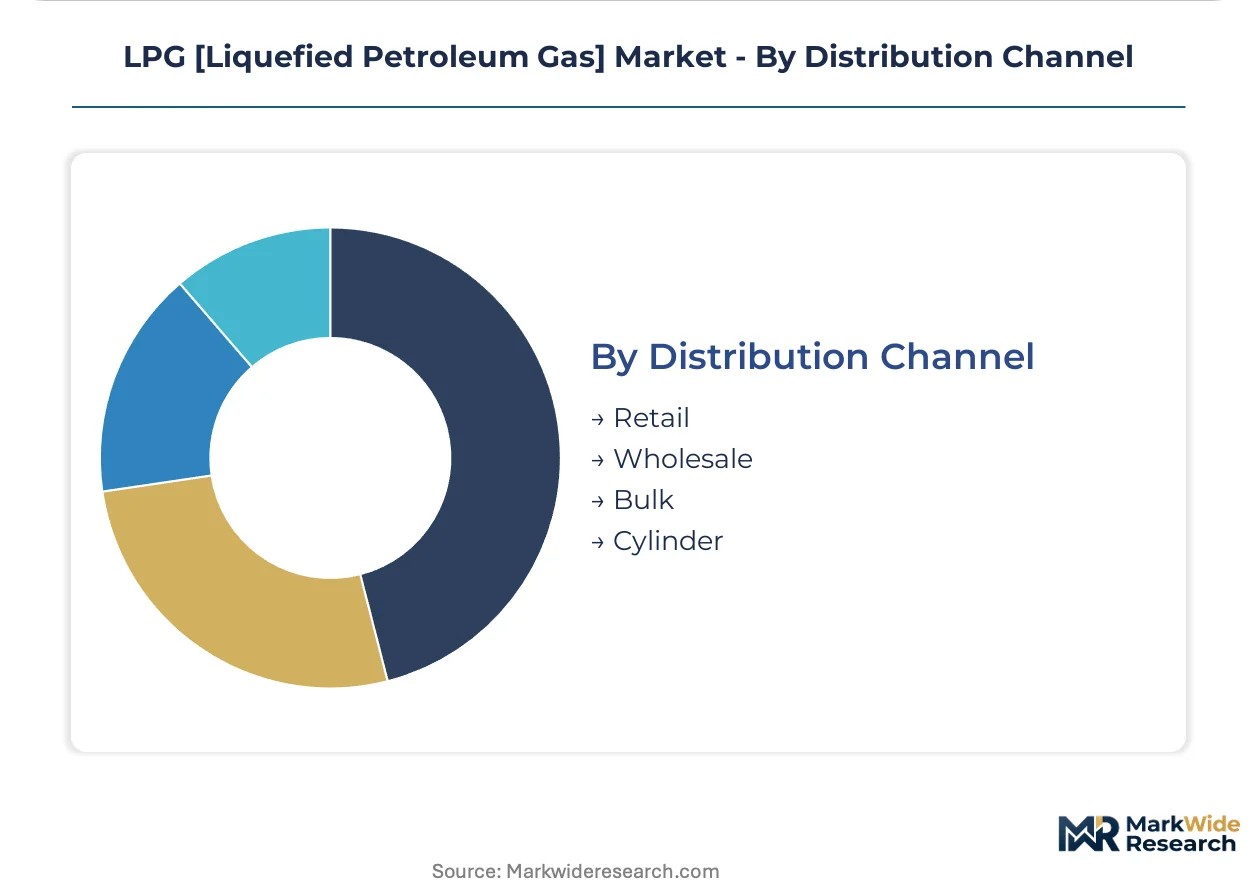
Distribution Channel:
Channel structure determines working capital intensity—cylinder float requirements strain distributor balance sheets while bulk terminals concentrate credit risk at import scale.
- Retail:Service station forecourts and small-format cylinder exchanges serve immediate consumption needs. Turkish automotive LPG retail networks operate dedicated pump islands.
- Wholesale:Regional distributors aggregate cylinder volumes for last-mile delivery. Indian distributors deploying RFID-enabled asset management report inventory efficiency improvements.
- Bulk:Industrial terminals and marine loading facilities handle thousand-ton parcel sizes. Rotterdam and Singapore terminals adapt infrastructure for IMO 2020-compliant bunker fuel specifications.
- Cylinder:Subsidized cylinder programs dominate residential access in India, Indonesia, and Bangladesh. PESO-mandated 15-year retirement rules force simultaneous replacement across 250 million installed Indian units.
Cylinder distribution commands the established base in emerging economy residential markets. Bulk terminal direct sourcing is climbing the fastest as commercial buyers consolidate procurement scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar, Saudi Arabia, and the UAE collectively control two-fifths of seaborne LPG exports, creating pricing leverage across Asian import markets. This concentration shapes contract structures and inventory strategies from Mumbai to Seoul. The following countries illustrate how regional demand patterns and policy frameworks diverge.
India
Residential cooking demand concentrates in Bihar, Uttar Pradesh, and Odisha where PAHAL direct benefit transfers now reach 80 million active consumers. The PESO mandates 15-year cylinder retirement rules across 250 million installed units. Mumbai's distributor networks deploy RFID-enabled asset management to reduce float losses.
China
City gas conversion programs and MIIT electric cooking subsidies create competing pressures on residential LPG retention. The SAMR enforces GB 11174-2011 automotive quality standards with tightened vapor pressure specifications. Guangdong province filling stations retrofit vapor recovery systems to comply with revised sulfur limits.
Brazil
Social program distribution networks concentrate cylinder procurement power at national scale. ANVISA oversees product safety standards for domestic consumption. São Paulo's restaurant districts have shifted from fragmented distributor relationships to single-source supply contracts with import terminal operators.
Turkey
NGV-LPG retrofit mandates accelerate transport-sector demand through commercial fleet incentives. Istanbul's taxi cooperatives operate 15,000 dedicated LPG vehicles with dedicated pump islands at retail networks. The country's national petroleum safety authority licenses pressure vessel technicians.
South Korea
Commercial vehicle tax incentives accelerate fleet conversion timelines for automotive-grade product. The MFDS regulates product quality standards for domestic distribution. Busan-Ulsan industrial corridors anchor bulk terminal supply agreements with process heat users.
LPG [Liquefied Petroleum Gas] Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the LPG value chain. The market structure concentrates upstream supply among integrated national oil companies with captive NGL extraction, while downstream distribution fragments across regional distributors and retail networks. Two strategic archetypes dominate: integrated producers with refinery-petrochemical assets, and specialized distributors with last-mile cylinder infrastructure. Competitive moves center on long-term offtake contract negotiations and digital tracking platform deployment.
Among Middle Eastern integrated producers, Saudi Aramco and QatarEnergy exemplify the upstream-controlled archetype with Yanbu and Jubail complex capacity. Shell plc and BP plc occupy positions within the European-Asian downstream distribution tier. Reliance Industries Limited represents the emerging market distributor model with consolidated procurement scale.
| Leading Market Players |
|---|
| Saudi Aramco |
| Shell plc |
| Exxon Mobil Corporation |
| BP plc |
| TotalEnergies SE |
| China Petroleum & Chemical Corporation (Sinopec) |
| Chevron Corporation |
| Reliance Industries Limited |
| QatarEnergy |
| Others |
Supply Flow & Price Mechanics
EPA Clean Air Act mobile source provisions gate both supply qualification and price differentiation across automotive-grade LPG markets. The regulation mandates specific odorant and vapor pressure specifications that create compliance premiums over standard commercial grades while disqualifying non-certified suppliers from transport-fuel participation.
Pricing Analysis
EPA odorant specifications dictate the pricing tier structure across automotive and transport applications. Three-tier pricing structure across premium automotive-grade, standard commercial-grade, and economy bulk-terminal levels separates certified transport fuel from heating applications. Price differentiation rests on certification grade compliance and geographic delivery cost to inland markets. Cost compression in standard commercial grades is intensifying because Middle Eastern exporters prioritize long-term offtake contracts over spot exposure. Fleet operators show least price sensitivity due to tax incentive lock-in, while residential cylinder consumers exhibit highest sensitivity to refill cost fluctuations.
Supply Chain Analysis
Strategic stockpile preferences dominate Asian importer behavior given winter price spike exposure and 30-45 day feedstock cost lags. Supply concentrates in Qatar, Saudi Arabia, and the UAE, which control two-fifths of seaborne exports. Raw material dependencies center on natural gas processing NGL extraction and crude oil refinery off-gas recovery. Single-source vulnerability runs through Strait of Hormuz chokepoint exposure. Distribution runs through integrated national oil company term contracts to regional distributors with last-mile cylinder float ownership.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed pressure vessel technicians for cryogenic handling remain scarce across Indonesia, Bangladesh, and Pakistan, constraining deployment velocity regardless of capital availability. This capability gap rewards players who solve certification bottlenecks before competitors.
For Market Incumbents: Secure long-term offtake contracts with Middle Eastern NGL producers to lock in feedstock cost predictability against Mont Belvieu index volatility. Deepen backward integration into refinery-petrochemical complexes to capture margin from standard-grade production. Invest in RFID-enabled cylinder tracking platforms to reduce float losses and defend distributor relationships against digital-native entrants. For New Entrants and Emerging Players: Last-mile logistics under-service in sub-Saharan Africa urban districts offers white-space entry with distributor financing models for cylinder procurement. Target Nigeria, Kenya, and Ghana where sub-20% household penetration meets rising clean cooking policy priority. Pursue direct terminal agreements with commercial buyers in São Paulo-style restaurant districts to bypass fragmented legacy distributor networks. For Investors and Strategic Acquirers: China's SAMR GB 11174-2011 revision reshapes the acquisition landscape by forcing hydrotreating upgrades or market share surrender among domestic refiners. Position for 5-10 year viability through downstream distribution infrastructure rather than upstream extraction exposure. Target cylinder fleet operators with IoT weight sensor deployment and mobile payment platform integration. Watch for biogas pilot scale-up in India's Ujjwala 2.0 program as electrification substitution inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks in NGL feedstock pricing against Mont Belvieu volatility for Asian importers. |
| Backward Integration | Captures margin from refinery off-gas recovery through Yanbu and Jubail complex capacity. |
| Digital Tracking Platform | RFID-enabled cylinder management reduces float losses for Indian distributors. |
| Certification Investment | EPA automotive-grade compliance opens transport-fuel premium pricing tiers. |
| Geographic Expansion | Sub-Saharan Africa distributor financing unlocks 50-million-cylinder annual demand potential. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase. Stakeholder interviews included refinery operations managers, LPG distributor network heads, cylinder fleet operators, and national petroleum safety authority regulators. Secondary validation drew from EIA inventory data, IEA energy outlooks, PESO safety compliance filings, and customs trade records. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Across the analysis window, the forecast framework disaggregated demand by product type, application segment, end-user category, and distribution channel. CAGRs were derived from regression analysis against heating degree-day correlations, subsidy program enrollment trajectories, and fleet conversion incentive uptake rates. Industry-specific inputs included PAHAL direct benefit transfer participation data and NGV-LPG retrofit program deployment statistics.
Underlying assumptions cover subsidy policy continuity in India and China, with deviation risk concentrated in electrification substitution acceleration and marine fuel specification convergence timelines. Forecasts reflect these documented conditions with sensitivity scenarios for Strait of Hormuz disruption and biogas pilot scale-up. Revision becomes warranted when electric cooking subsidy penetration crosses rural district threshold coverage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Pale Oil Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Tar Oil Market
Petroleum Products
Oil Refinery Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Petcoke Market
Petroleum Products
PAG Base Oil Market
Petroleum Products
Marine Minerals Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Balanos Oil Market